
 Cathode Battery Material Market | 2026-2036
Cathode Battery Material Market Size, Share, and Industry Trends Forecast 2026-2036
Cathode Battery Material Market Analysis
Automotive OEM procurement is consolidating around a shrinking pool of qualified cathode suppliers capable of meeting stringent purity and consistency requirements. BASF SE leverages its integrated precursor-to-cathode production network across European and Asian hubs. Umicore anchors its position through closed-loop battery material recycling capabilities that reduce virgin metal dependence. POSCO FUTURE M dominates nickel-rich cathode output from its Pohang and Gwangyang manufacturing complexes.
Cathode battery materials are engineered crystalline compounds, typically lithium transition-metal oxides with layered or olivine structures, that serve as the positive electrode in rechargeable lithium-ion cells by reversibly intercalating lithium ions during charge and discharge cycles. Manufacturing requires precise stoichiometric control, high-temperature calcination above 700°C, and particle size distribution management to achieve target energy density and cycle life specifications. Lithium Nickel Manganese Cobalt formulations lead volume shipments due to their superior energy density profile for electric vehicle applications. Lithium Iron Phosphate sustains cost-sensitive energy storage system demand where cycle stability outweighs gravimetric energy targets. Lithium Cobalt Oxide occupies premium consumer electronics segments where volumetric energy density determines device form factor constraints.
Europe's REACH and RoHS frameworks restrict hazardous substance content in cathode precursors, while the EU Green Deal's carbon border adjustments incentivize low-emission production pathways. China's GB standards and dual carbon goals enforce energy efficiency benchmarks that reshape domestic cathode manufacturing investment patterns. South Korea's MFDS and METI-aligned industrial policies coordinate cathode supply chain security with battery OEM expansion plans. Stakeholders must monitor evolving nickel and cobalt sourcing certification requirements that will determine qualified supplier status across major automotive OEM qualification programs.
Market Dynamics
OEM qualification programs are compressing the supplier base for cathode materials as battery energy density targets tighten and traceability requirements harden. This consolidation force is reshaping competitive positioning across precursor sourcing, calcination capacity, and closed-loop metal recovery.
Growth Catalysts
- High-nickel cathode formulations:Electric vehicle OEMs are scaling procurement of NCM 811 and 9-series materials to meet pack-level energy density thresholds above 300 Wh/kg.
- China's dual carbon goals:Beijing's GB standards and carbon intensity benchmarks are accelerating domestic cathode capacity buildout with state-backed financing for integrated precursor-to-active-material complexes.
- South Korea's industrial corridor:POSCO FUTURE M and LG Chem suppliers are concentrating demand in the Pohang-Gwangyang battery-chemical cluster, creating dense supplier ecosystems.
Market Restraints
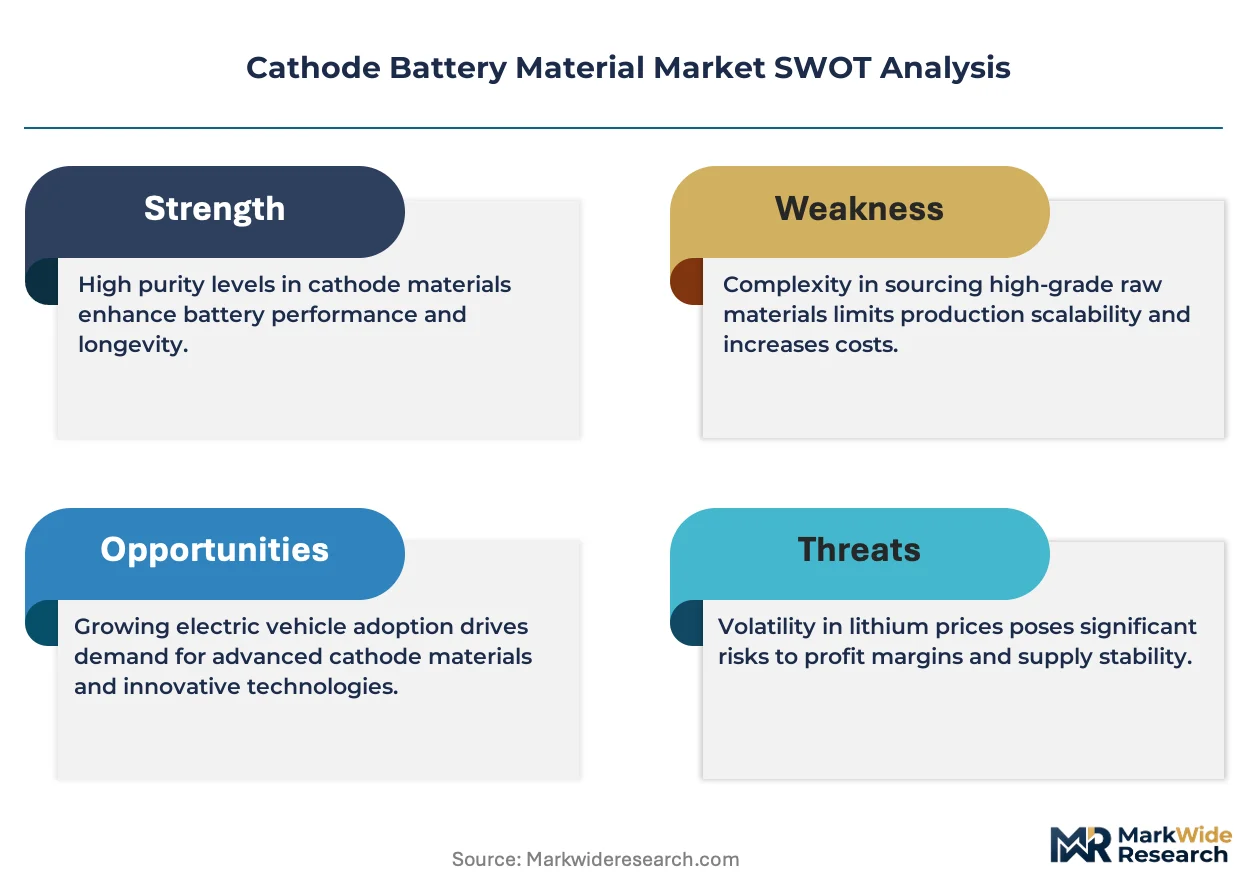
- Nickel and cobalt price volatility:London Metal Exchange price swings for Class 1 nickel and cobalt metal are compressing cathode producer margins and complicating long-term contract structures.
- Supply concentration in Indonesia:Over 40% of global nickel intermediate supply originates from Indonesian HPAL and RKEF operations, creating single-geography dependency risk.
- Technical limitations of silicon-anode pairing:Volume expansion mismatch between high-nickel cathodes and silicon-dominant anodes is delaying next-generation cell commercialization timelines.
Strategic Opportunities
- European battery value chain localization:EU Green Deal carbon border adjustments and Critical Raw Materials Act incentives are creating offtake opportunities for low-emission cathode production in Finland and Germany.
- Stationary energy storage applications:Grid-scale battery deployments are opening volume channels for lithium iron phosphate cathodes where cycle stability outweighs gravimetric energy density.
- Direct recycling technology convergence:Hydrometallurgical and direct regeneration processes are integrating with OEM qualification frameworks to reduce virgin metal dependence.
Industry Challenges
- High-temperature calcination expertise gap:Precise atmosphere control and particle morphology engineering at 700-900°C requires specialized process engineers in short supply across emerging production regions.
- OEM certification timeline compression:Automotive qualification cycles spanning 18-24 months for new cathode formulations are misaligned with cell chemistry roadmaps and model-year deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathode Battery Material Market |
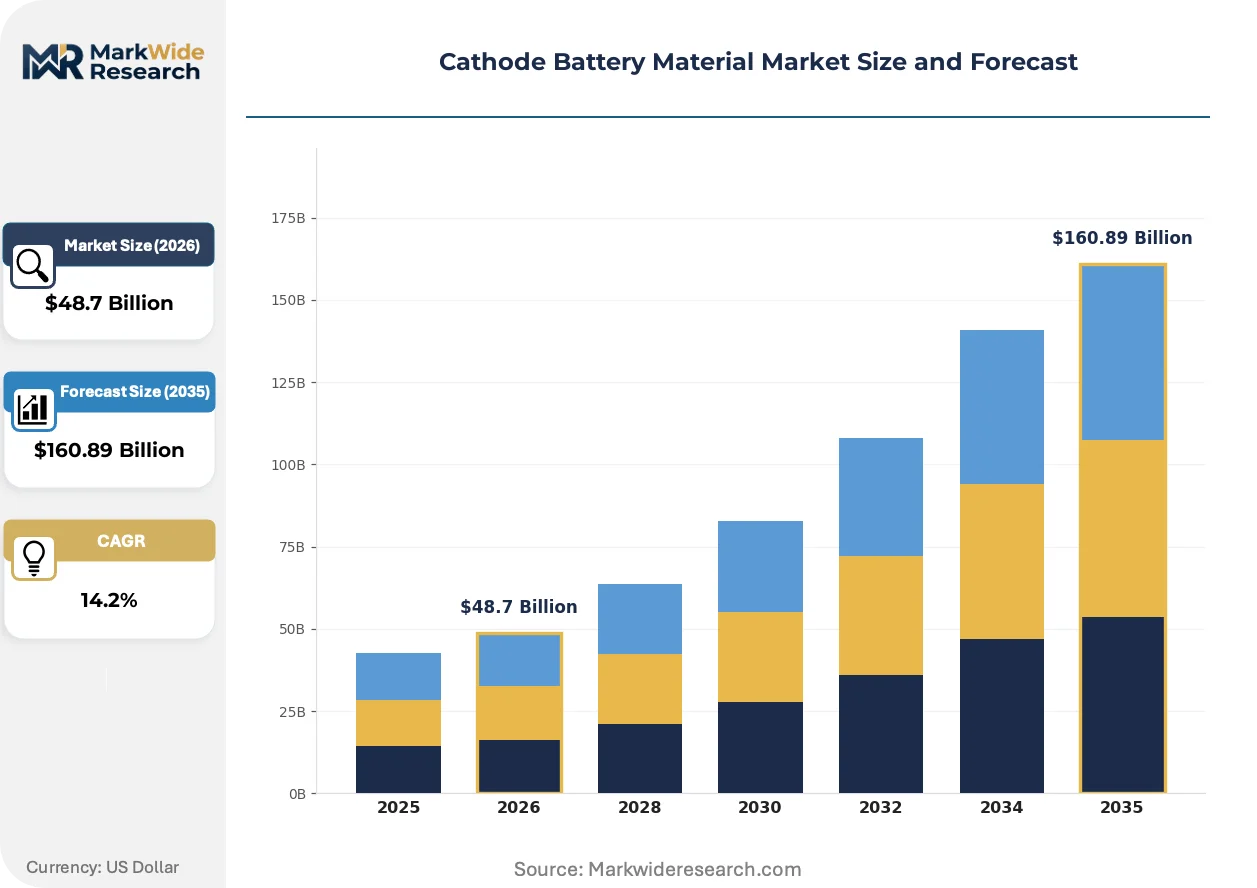
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Nickel Manganese Cobalt, Lithium Titanate Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Aerospace End User: Automotive OEMs, Electronics Manufacturers, Utility Companies, Retailers Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Outlets |
| Companies Covered | BASF SE, Umicore, POSCO FUTURE M, LG Chem, CATL, Sumitomo Metal Mining, Nichia Corporation, Targray, Ronbay Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathode Battery Material Market Emerging Trajectories
Active material engineering is pivoting toward cobalt reduction and manganese stabilization as cell chemistry roadmaps diverge across automotive and stationary applications. These technical trajectories are compressing legacy formulation shelf lives while opening new patent landscapes.
Single-crystal high-nickel cathode architectures are integrating into premium electric vehicle cell designs to suppress microcracking during extended cycling. Korean and Chinese cell producers are qualifying these morphologies for 1.5 million kilometer warranty programs. The structural consequence is compressing polycrystalline cathode pricing power in the high-end automotive segment.
Europe's REACH framework and forthcoming battery passport requirements are mandating full supply chain disclosure for cobalt, nickel, and lithium sourcing. Industrial consequence includes mandatory third-party auditing of mine sites and intermediate processing facilities. High-nickel cathode formulations for European automotive OEMs are most affected, with producers accelerating blockchain-traceability system deployment to maintain qualified supplier status.
Cell producers are consolidating cathode procurement around long-term offtake agreements with integrated precursor-to-active-material suppliers, displacing spot-market purchasing for volume programs. This behavioral shift is concentrating negotiation leverage with POSCO FUTURE M, BASF SE, and Umicore in the European and Korean automotive supply bases. The transformation is most visible in South Korea, where Hyundai-Kia and SK On are locking in decade-long supply contracts with fixed-price escalators.
Cathode Battery Material Market Segmentation
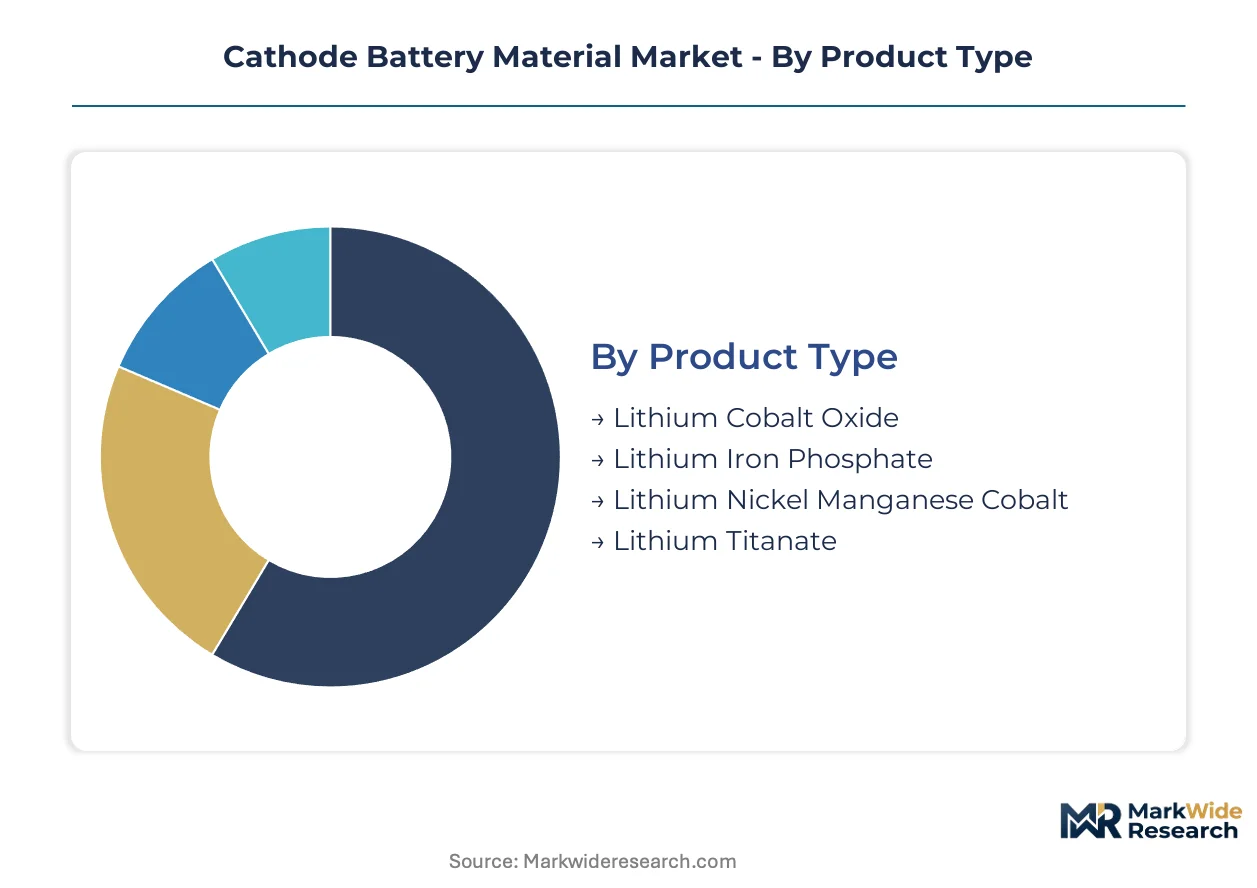
Cathode material selection determines cell energy density, thermal stability, and cost structure. Procurement patterns diverge sharply across automotive, consumer electronics, and grid storage applications. Each segment imposes distinct purity, traceability, and volume requirements on suppliers.
Product Type:
Layered oxide and olivine structures dominate cathode engineering, with nickel content and cobalt substitution driving performance differentiation.
- Lithium Nickel Manganese Cobalt:High-nickel formulations deliver superior gravimetric energy density for electric vehicle packs. Korean cell producers are scaling NCM 811 and 9-series procurement to meet 300 Wh/kg pack targets, though nickel price volatility compresses margin visibility.
- Lithium Iron Phosphate:Olivine structure provides exceptional cycle stability and thermal safety at lower material cost. Chinese battery producers dominate LFP output for energy storage systems and entry-level electric vehicles where energy density requirements relax.
- Lithium Cobalt Oxide:Layered oxide maintains highest volumetric energy density for premium consumer electronics form factors. Apple's and Samsung's smartphone battery procurement sustains limited but high-margin demand.
- Lithium Titanate:Spinel structure enables extreme fast-charging capability with minimal lithium plating risk. Niche applications in electric buses and grid frequency regulation absorb limited volumes.
Lithium Nickel Manganese Cobalt leads on scale; Lithium Iron Phosphate leads on momentum.
Application:
End-use specifications cascade backward through cathode chemistry selection, calcination standards, and certification requirements.
- Electric Vehicles:Automotive OEM qualification programs enforce 18-24 month validation cycles for new cathode formulations. High-nickel NCM dominates premium platforms; LFP penetrates mass-market segments.
- Consumer Electronics:Volumetric energy density constraints favor LCO and medium-nickel NCM for smartphones, laptops, and wearables. Cycle life requirements remain modest versus automotive.
- Energy Storage Systems:Grid-scale deployments prioritize 6,000+ cycle life and capital cost minimization. LFP captures dominant share; sodium-ion alternatives are emerging.
- Aerospace:Satellite and electric aviation applications demand extreme reliability and specific energy. Limited volumes command premium pricing with dedicated supply chains.
Electric Vehicles commands the largest procurement volumes; Energy Storage Systems shows the steepest expansion trajectory.
End User:
Customer scale and integration depth determine contract structure, pricing mechanism, and technical collaboration intensity.
- Automotive OEMs:Tesla, BYD, and Volkswagen Group negotiate multi-year offtake agreements with fixed-price escalators. Direct supplier relationships are displacing tiered procurement through cell producers.
- Electronics Manufacturers:Foxconn, Samsung SDI, and CATL's consumer divisions source cathode through qualified supplier lists with quarterly price reviews.
- Utility Companies:State Grid Corporation of China and NextEra Energy procure battery storage systems turnkey, with cathode chemistry specified at system integrator level.
- Retailers:Home energy storage and power tool battery replacement markets absorb small-format cathode through distributor channels.
Automotive OEMs drive contract innovation; Utility Companies are gaining procurement sophistication fastest.
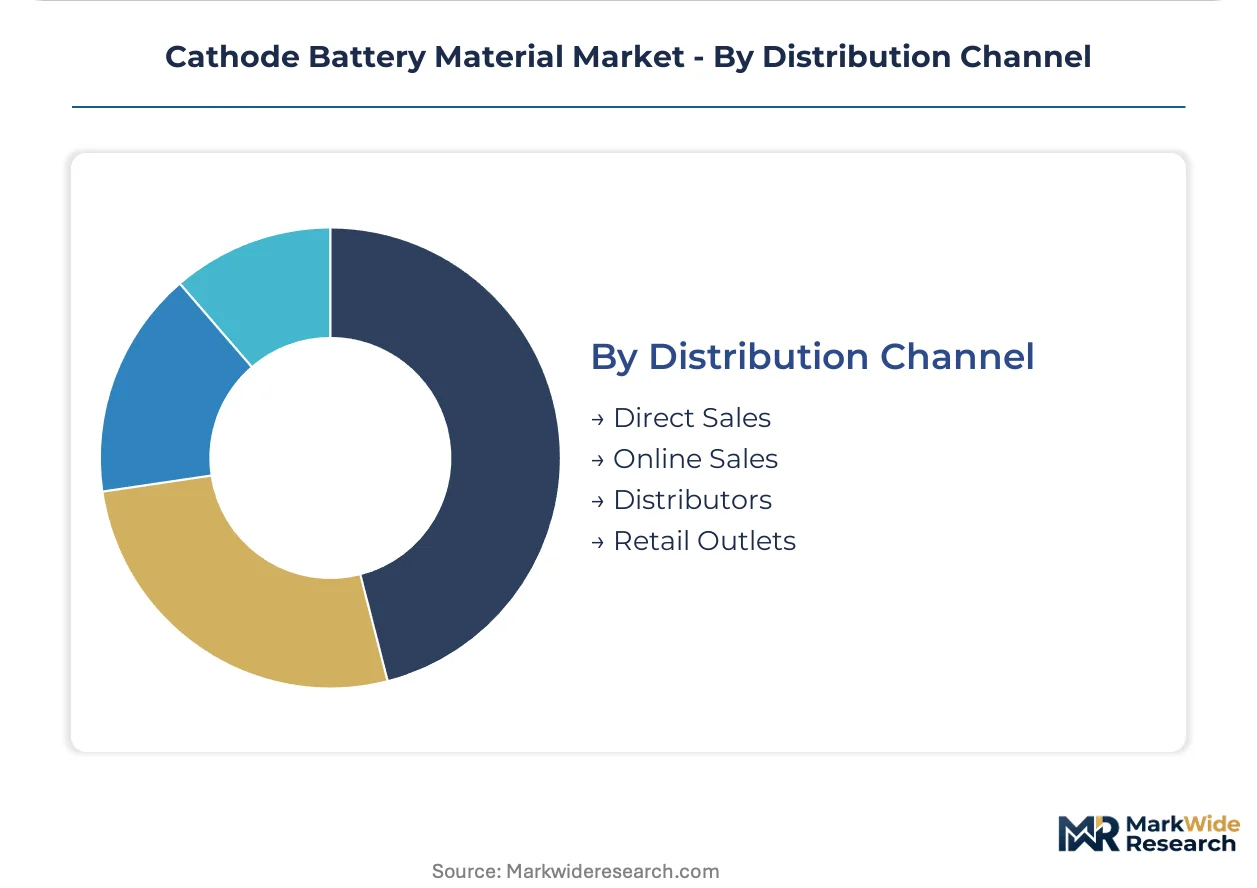
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to production.
- Direct Sales:BASF SE and Umicore maintain dedicated account teams for automotive OEM and tier-one cell producer relationships. Technical collaboration on formulation customization justifies bypass.
- Distributors:Regional chemical distributors serve mid-tier cell producers and specialty battery assemblers with standard NCM and LFP grades.
- Online Sales:Alibaba and specialized B2B platforms facilitate spot purchases for research quantities and non-qualified production.
- Retail Outlets:Limited to aftermarket battery replacement and hobbyist electronics segments.
Direct Sales captures the highest value transactions; Distributors expand geographic reach most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cathode output dwarfs German production volumes by an order of magnitude, yet South Korean suppliers command premium pricing through tighter OEM qualification relationships. Regulatory divergence across these three markets is fragmenting supply chain strategies.
China
Domestic EV procurement from BYD and CATL is absorbing NCM and LFP cathode at unprecedented scale. Beijing's dual carbon goals and GB standards enforce energy efficiency benchmarks that reshape manufacturing investment toward integrated precursor complexes. The Yangtze River Delta hosts the densest concentration of cathode-active-material capacity, with state-backed financing accelerating buildout in Jiangsu and Zhejiang provinces.
South Korea
Hyundai-Kia and SK On are locking in decade-long supply contracts with fixed-price escalators for high-nickel formulations. METI-aligned industrial policies coordinate cathode supply chain security with battery OEM expansion timelines. The Pohang-Gwangyang industrial corridor anchors nickel-rich cathode output, creating dense supplier ecosystems around POSCO FUTURE M and LG Chem operations.
Germany
Volkswagen Group and BMW are negotiating multi-year offtake agreements directly with cathode producers, displacing tiered procurement through cell makers. The EU Green Deal's carbon border adjustments and REACH frameworks incentivize low-emission production pathways. North Rhine-Westphalia and Bavaria are emerging as preferred locations for cathode precursor plants serving European automotive qualification programs.
United States
Tesla's Texas and Nevada operations are driving procurement of high-nickel cathode for 4680 cell production, with IRA domestic content requirements reshaping supplier selection. EPA and NHTSA regulatory alignment on battery safety standards is compressing qualification timelines. The Midwest industrial corridor spanning Michigan and Ohio is attracting cathode precursor investments to serve Detroit Three electrification programs.
Japan
Toyota and Panasonic are sustaining demand for medium-nickel NCM and LCO formulations in hybrid and consumer electronics applications. METI's battery supply chain security initiatives are accelerating domestic cathode recycling infrastructure deployment. The Kansai region around Osaka maintains specialized calcination expertise for premium consumer electronics cathode grades.
Cathode Battery Material Market Vendor Landscape
German and Belgian producers anchor the premium-tier supplier base; Chinese specialists hold volume leadership through integrated precursor-to-active-material complexes. Market structure consolidates around a shrinking pool of qualified suppliers capable of meeting automotive OEM purity and traceability requirements. Three archetypes dominate: integrated chemical conglomerates with captive metal supply, dedicated battery material specialists with closed-loop recycling capabilities, and state-backed Asian producers with scale advantages. Competitive intensity centers on long-term offtake negotiations and carbon-intensity certification for European market access.
Within the integrated chemical tier, BASF SE and Umicore exemplify European producers leveraging REACH-compliant production networks and recycling infrastructure to maintain qualified supplier status. POSCO FUTURE M anchors the Korean industrial corridor position, representing the state-backed scale archetype with concentrated high-nickel output capabilities. These three entities occupy positions that concentrate negotiation leverage with automotive OEMs seeking multi-year supply security.
| Leading Market Players |
|---|
| BASF SE |
| Umicore |
| POSCO FUTURE M |
| LG Chem |
| CATL |
| Sumitomo Metal Mining |
| Nichia Corporation |
| Targray |
| Ronbay Technology |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange nickel and cobalt price indices cascade through cathode material supply chains, compressing margins at precursor processing stages while amplifying pricing power for integrated producers with captive metal supply. Contract structures stratify across automotive OEM long-term offtakes, spot-market transactions for research quantities, and distributor-mediated sales for mid-tier cell producers.
Pricing Analysis
Capacity additions in Indonesia are reshaping price floors for nickel sulfate intermediates, forcing legacy producers to absorb margin compression or exit commodity-grade supply. Three-tier pricing structure across automotive-qualified, industrial-standard, and unqualified research grades reflects certification investment and volume scale. Cost compression in mid-tier NCM formulations is intensifying because Chinese state-backed financing accelerates integrated complex buildout. Utility-scale energy storage buyers exhibit highest price sensitivity; premium electric vehicle OEMs prioritize qualified supplier status over unit cost.
Supply Chain Analysis
Closed-loop hydrometallurgical recovery flows are integrating with virgin material streams, reducing dependence on mined cobalt and nickel while complicating batch consistency for automotive qualification programs. Primary supply concentrates in China, South Korea, and Indonesia, with Indonesian HPAL operations feeding nickel sulfate to East Asian cathode plants. The network draws from lithium carbonate from Chilean and Australian brine operations, cobalt hydroxide from DRC-integrated traders, and manganese sulfate from Chinese electrolytic metal production. Single-geography dependency risk in Indonesian nickel intermediate supply creates vulnerability to export restriction or environmental compliance disruption. Distribution runs through direct account teams for automotive OEMs and tier-one cell producers, with regional chemical distributors serving qualified mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU battery passport requirements and carbon border adjustment mechanisms are accelerating demand for traceable, low-emission cathode production.
For Market Incumbents: Deepen backward integration into Indonesian nickel intermediate supply to secure cost-advantaged feedstock against price volatility. Expand calcination capacity in European industrial corridors to capture EU Green Deal offtake opportunities as carbon-intensity certification hardens. Defensive positioning requires accelerating blockchain-traceability system deployment before battery passport mandates disqualify non-compliant suppliers.
For New Entrants and Emerging Players: Enter via direct recycling technology convergence, where hydrometallurgical and regeneration process expertise commands premium valuation amid virgin metal scarcity. Target stationary energy storage applications with lithium iron phosphate formulations, where cycle stability requirements relax energy density specifications and OEM qualification barriers. Go-to-market positioning should emphasize closed-loop metal recovery capabilities aligned with automotive OEM sustainability procurement criteria.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized direct recycling technology developers possessing hydrometallurgical process patents and OEM qualification relationships. Long-term viability over the next decade hinges on securing offtake agreements with integrated battery-chemical producers rather than spot-market metal traders. Monitor regulatory acceleration of battery passport implementation timelines as the critical inflection indicator for traceability-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Intermediate Supply | Captures margin compression from LME price volatility by securing HPAL offtake from Indonesian operations. |
| European Cathode Precursor Capacity Buildout | Positions producers to meet EU carbon border adjustments and REACH compliance for automotive qualification. |
| Long-term Automotive OEM Supply Agreement | Locks in volume visibility through fixed-price escalator contracts spanning decade-long electrification programs. |
| Direct Recycling Technology Licensing | Reduces virgin metal dependence while integrating with OEM closed-loop material recovery frameworks. |
| Blockchain Traceability System Deployment | Maintains qualified supplier status under EU battery passport disclosure mandates for cobalt and nickel sourcing. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cathode plant managers, automotive OEM procurement leads, battery cell R&D directors, and metals trading specialists with secondary validation. Primary inputs drew from customs and trade flow databases, SEC filings of listed chemical conglomerates, and GB standards documentation from China's MIIT. Bottom-up capacity buildout tracking across Jiangsu, Zhejiang, and Pohang-Gwangyang industrial corridors was triangulated against top-down demand modeling from electric vehicle production forecasts.
Segment-weighting approaches applied differential growth assumptions across lithium nickel manganese cobalt, lithium iron phosphate, and lithium cobalt oxide chemistries, with nickel-content tiers and end-use applications modeled separately. CAGRs were derived from regression analysis of historical capacity utilization and forward-looking OEM procurement commitments across the projection horizon. Industry-specific forecast inputs included cell energy density roadmaps, OEM qualification timeline compression effects, and regulatory milestone acceleration scenarios for battery passport implementation.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in proprietary OEM qualification pipeline data introduce uncertainty bands around market share projections. Forecasts reflect documented assumptions regarding nickel price trajectory, Chinese state-backed financing continuity, and European carbon border adjustment implementation pace. Practitioners should monitor regulatory acceleration of battery passport mandates, Indonesian export policy shifts, and silicon-anode pairing commercialization timelines for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Italy 3D Printing Construction Market
Others
Data Center CPU Market
Others
Metal Air Battery Market
Others
Lepidolite Market
Others
Europe Aircraft Lighting Systems Market
Others
Global Drug Discovery Informatics Market
Others
China Cloud Gaming Technology Market
Others
Foldable Smartphone Market
Others
Wearable Solar Devices Market
Others
Middle East and Africa Home Care Packaging Market
Others
Global Digital Caliper Market
Others
Architectural Fabrics Market
Others
Global Digital Market
Others
Cashew Kernel Market
Others
Australia Content Services Platform Market
Others
Automotive Smart Lighting Market