
 Football Sportswear Market | 2026-2036
Football Sportswear Market Size, Share, and Industry Trends Forecast 2026-2036
Football Sportswear Market Intelligence
Direct-to-consumer digital platforms is reconfiguring how football sportswear reaches end buyers, bypassing traditional wholesale gatekeepers. Nike Inc. leverages its SNKRS ecosystem and app-based drops to sustain direct relationships with club-affiliated consumers. Adidas AG anchors its three-stripes heritage through federation partnerships that dominate national team kit supply. PUMA SE differentiates via aggressive club sponsorship density across Europe's second-tier leagues.
Football sportswear encompasses technical athletic garments engineered for pitch performance, typically constructed from lightweight polyester mesh with elastane integration for four-way stretch and thermal regulation during high-intensity intermittent exercise. These products serve competitive match play, training regimens, and fan-identification commerce across amateur through professional levels. Footwear commands the deepest margin pools as innovation cycles compress and cleat technologies fragment by surface type. Jerseys drive the highest volume velocity through annual club refreshes and tournament-year national team releases. Accessories remain the most fragmented segment, with headbands, socks, and guard straps competing on price rather than technical distinction.
FIFA's Equipment Regulations govern permissible branding dimensions and fabric certifications for match-wear, while EU REACH restrictions on perfluorinated chemicals constrain water-repellent finishing chemistries across European supply chains. The US Consumer Product Safety Commission monitors youth football apparel for drawstring entanglement hazards and flammability thresholds. Stakeholders must monitor emerging extended producer responsibility frameworks in the European Union that will mandate textile collection and recycling infrastructure investments.
Market Dynamics
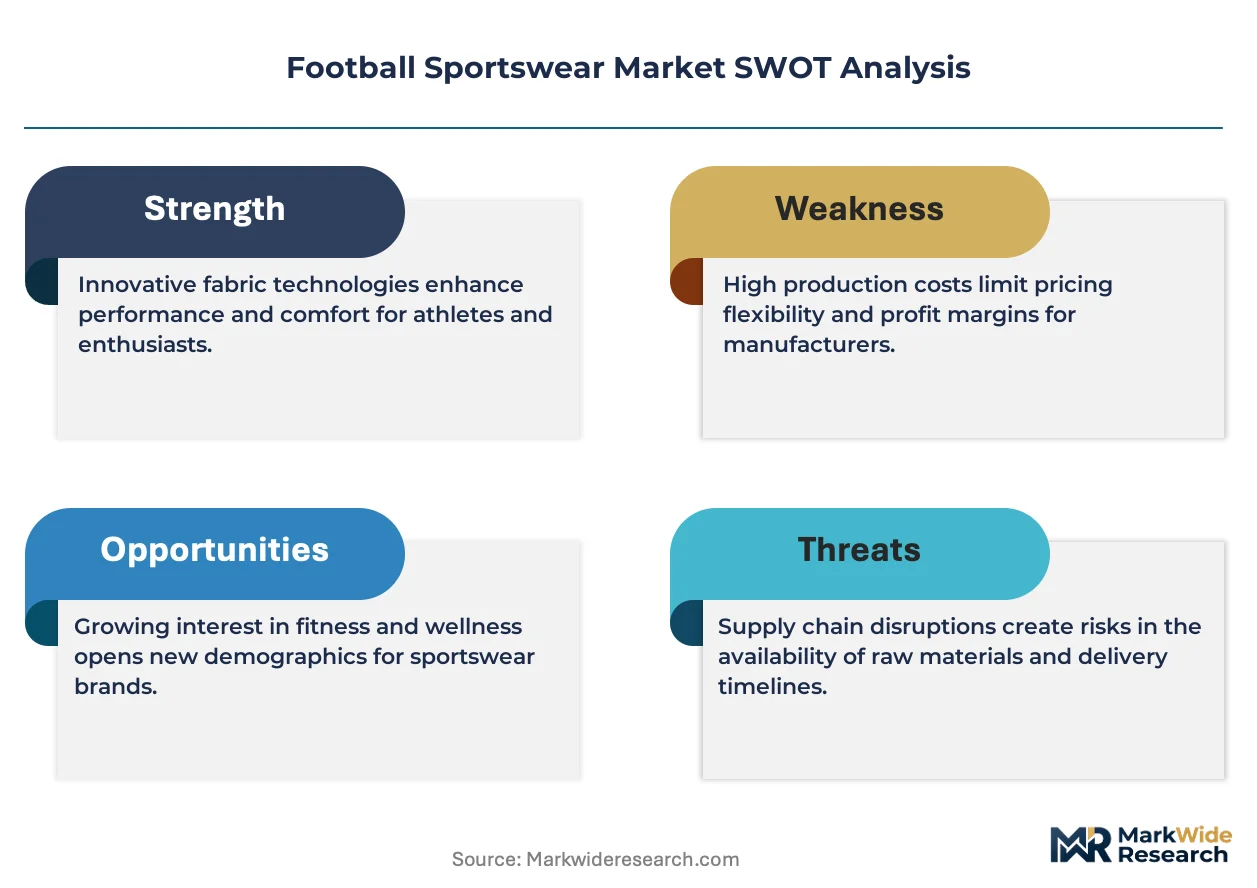
Direct-to-consumer digital platforms are reconfiguring how football sportswear reaches end buyers, bypassing traditional wholesale gatekeepers and compressing margin capture timelines from months to minutes.
Growth Catalysts
- EU Extended Producer Responsibility frameworks:Mandated textile collection infrastructure is accelerating closed-loop material sourcing across European supply chains.
- Moisture-wicking polyester blends:Performance fabric innovations are elevating technical specifications for youth academy procurement programs.
- Brazil:Football culture drives premium kit consumption across all consumer tiers, creating sustained volume velocity unmatched in other markets.
Market Restraints
- Recycled nylon feedstock volatility:Post-consumer waste collection gaps create input cost instability for sustainable product lines.
- Perfluorinated chemical restrictions:EU REACH constraints on water-repellent finishing chemistries limit functional coating options for all-weather gear.
- Footwear innovation cycles:Compressed cleat technology refresh rates strain R&D amortization across surface-specific product fragmentation.
Strategic Opportunities
- Grassroots development funding:Federation-backed youth academy expansion creates institutional procurement channels with multi-year contract potential.
- Second-tier European leagues:Underserved club sponsorship density offers partnership white space outside top-division concentration.
- App-based drop distribution:SNKRS-style release mechanics enable direct margin capture and first-party data accumulation from fan-identification buyers.
Industry Challenges
- Four-way stretch integration:Elastane blending expertise shortages constrain technical garment production scaling for emerging suppliers.
- FIFA Equipment Regulations certification:Branding dimension and fabric testing timelines delay tournament-year national kit launches.
- Legacy wholesale inventory reconciliation:Channel conflict between direct-to-consumer platforms and established retail partnerships requires careful allocation management.
Report Scope
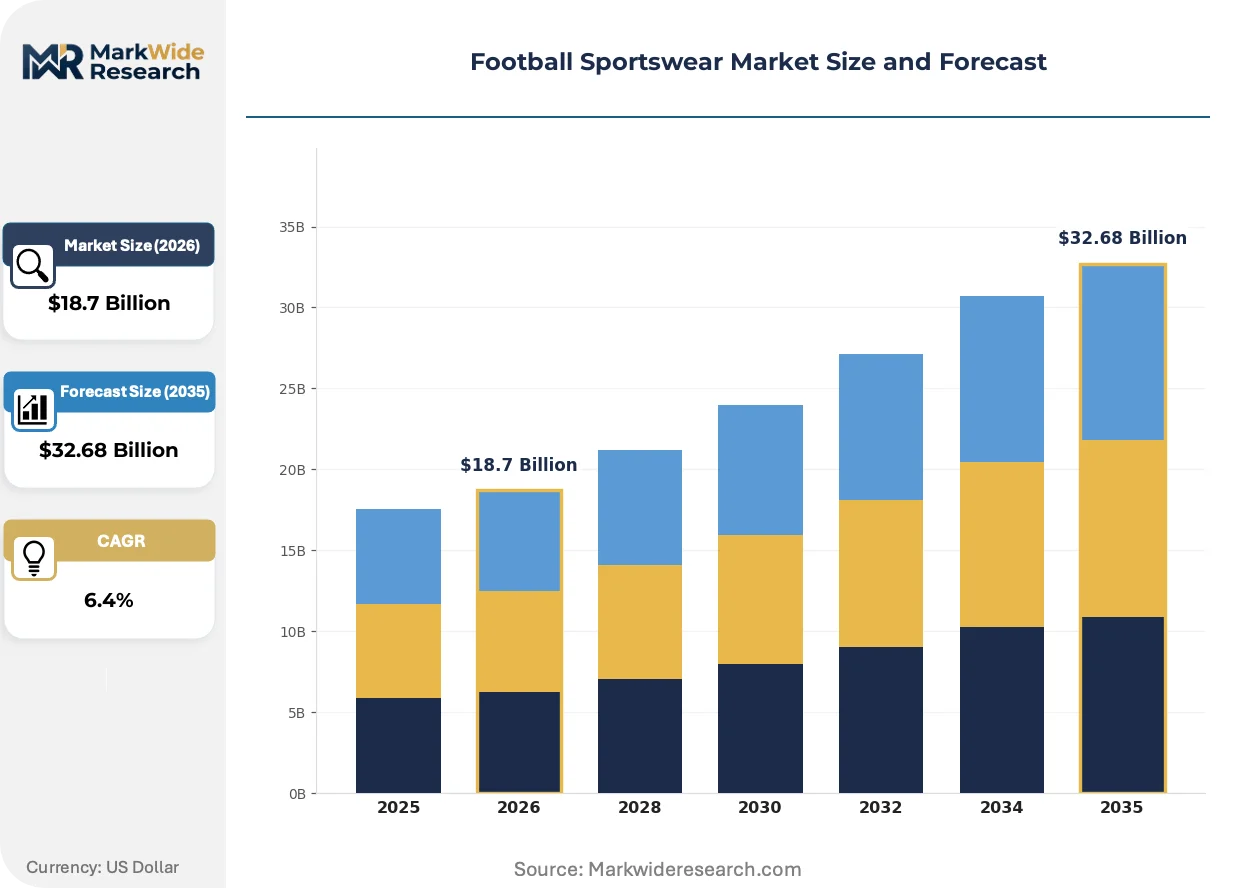
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Sportswear Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Jerseys, Shorts, Accessories Material: Polyester, Cotton, Nylon, Spandex Consumer Type: Adults, Youth, Women, Athletes Distribution Channel: Online, Retail Stores, Wholesale, Specialty Shops |
| Companies Covered | Under Armour Inc., ASICS Corp., Nike Inc., Mizuno Corp., New Balance Athletics Inc., Adidas AG, ANTA Sports Products Ltd., JOMA SPORT SA, PUMA SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Sportswear Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pressure on chemical finishing are converging to reshape product specifications across competitive and fan-commerce segments simultaneously.
Biodegradable elastane alternatives are migrating from laboratory validation to pitch-grade testing. Premium club suppliers are piloting plant-derived stretch polymers in training bibs and compression layers. This migration from petroleum-based inputs is compressing the sustainability premium that earlier recycled polyester iterations commanded.
EU REACH restrictions on perfluorinated chemicals are eliminating durable water-repellent coatings from match-wear specifications. Manufacturers are pivoting to silicone-based and bio-wax alternatives that sacrifice some weather resistance for regulatory compliance. European national team kit suppliers face the steepest reformulation timelines ahead of tournament cycles.
Fan-identification buyers are consolidating purchases around authenticated club drops rather than seasonal retail replenishment. Digital release calendars and membership-tier early access are displacing traditional wholesale preseason orders. Brazil and European club markets exhibit the most pronounced shift toward scarcity-driven purchase behavior.
Football Sportswear Market Segmentation
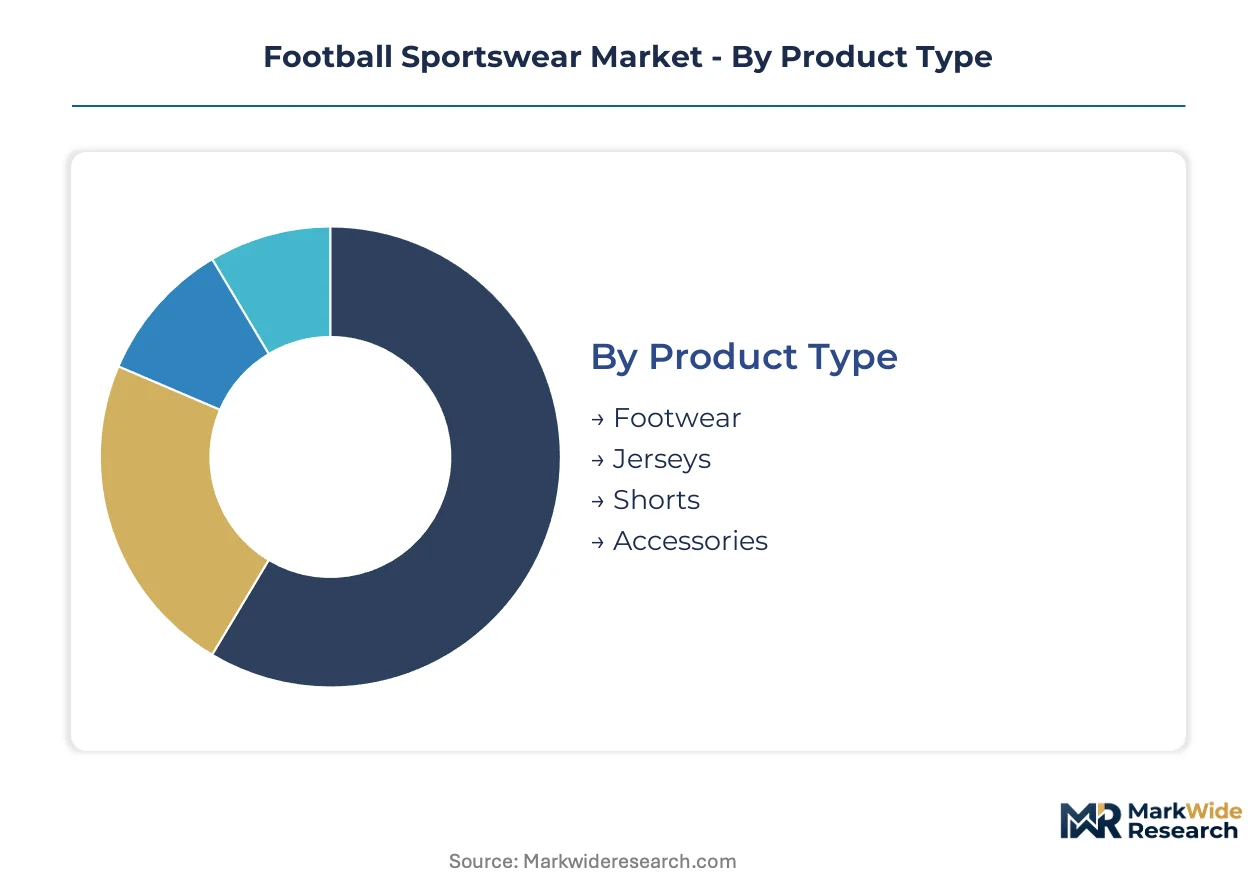
Segmentation in football sportswear determines inventory allocation rhythms and margin capture potential across fundamentally different buyer behaviors. Technical specifications diverge sharply between performance-grade match wear and fan-identification commerce, while distribution channel selection dictates brand control depth and data ownership.
Product Type:
After-sales service intensity varies dramatically across product categories, with footwear requiring sizing support and cleat replacement programs that jerseys and accessories rarely demand.
- Footwear:Technical construction integrates surface-specific stud configurations and compressed foam midsoles calibrated for high-impact directional changes. Margin concentration is deepest here as innovation cycles compress and cleat technologies fragment by pitch surface across Brazil's variegated playing conditions.
- Jerseys:Lightweight polyester mesh with elastane integration enables four-way stretch and thermal regulation during intermittent exercise. Annual club refreshes and tournament-year national team releases drive the highest volume velocity through federation-backed procurement channels.
- Shorts:Compression liners and moisture-wicking fabrics serve training regimens and match play alike.
- Accessories:Headbands, socks, and guard straps compete primarily on price with limited technical distinction.
Footwear holds the largest share; momentum sits with Jerseys as fan-identification commerce accelerates.
Material:
Cost tier stratification separates petroleum-derived synthetics from plant-based alternatives, with sustainability premiums compressing as recycled formulations scale.
- Polyester:Moisture-wicking blends dominate technical specifications for youth academy procurement programs. Post-consumer recycled feedstock is displacing virgin resin across European supply chains under extended producer responsibility mandates.
- Nylon:Durable water-repellent formulations face reformulation pressure from EU REACH restrictions on perfluorinated chemicals. Silicone-based alternatives sacrifice weather resistance for regulatory compliance in all-weather gear segments.
- Cotton:Natural fiber retains position in fan-commerce segments prioritizing comfort over performance.
- Spandex:Four-way stretch integration enables compression garments and form-fitting base layers.
Polyester holds the largest share; momentum sits with Nylon as sustainable sourcing requirements tighten.
Consumer Type:
Application context separates competitive match wear from training and lifestyle consumption, with institutional procurement creating volume anchors distinct from individual purchase patterns.
- Adults:Recreational league participation and club affiliation drive replacement cycles for match-grade and training garments.
- Youth:Grassroots development funding from federations creates institutional procurement channels with multi-year contract potential across academy systems.
- Women:Product specifications increasingly diverge from unisex scaling as fit engineering and design language address distinct biomechanical requirements.
- Athletes:Professional and semi-professional players demand FIFA Equipment Regulations certification for match-wear branding dimensions and fabric testing.
Adults hold the largest share; momentum sits with Youth as federation-backed academy expansion accelerates.
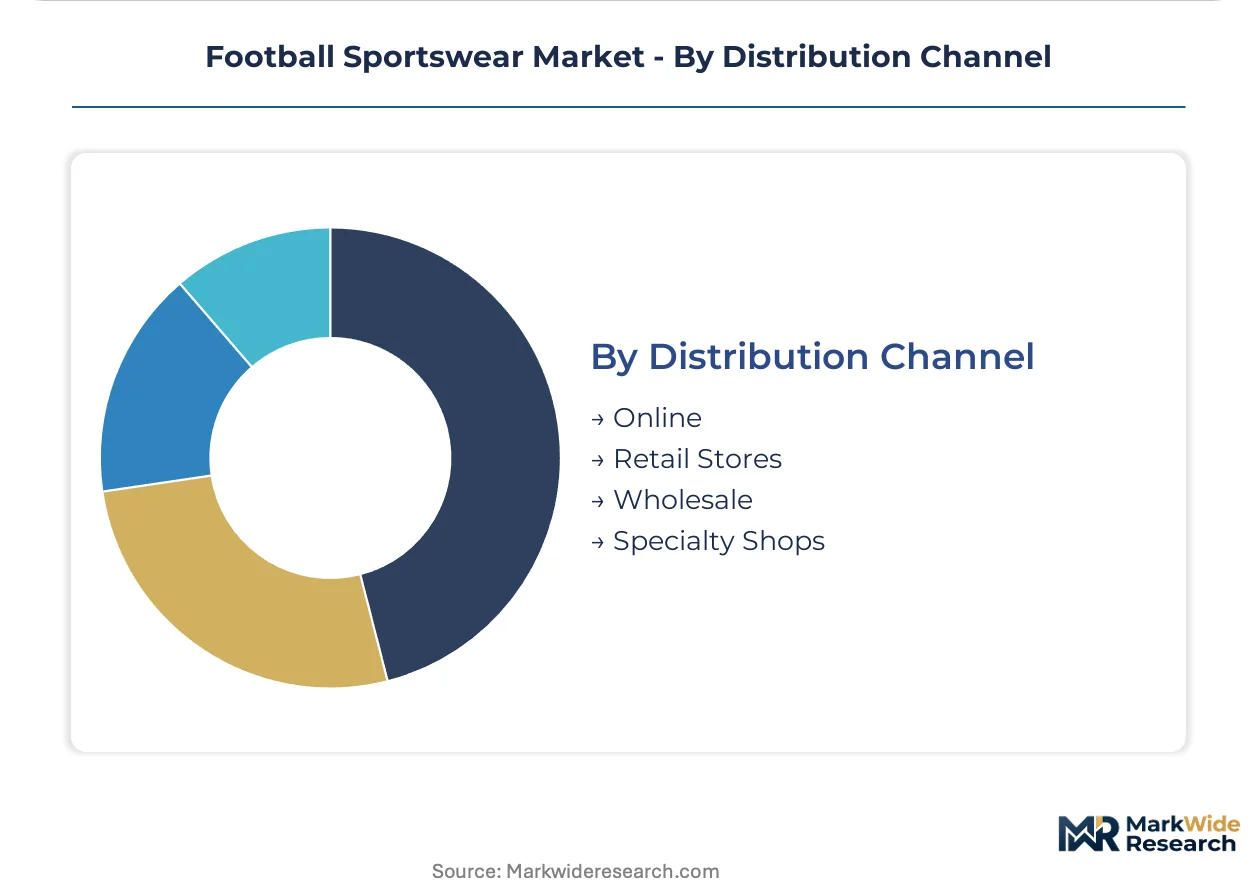
Distribution Channel:
Customer type concentration determines channel priority, with fan-identification buyers consolidating around authenticated drops while institutional procurement favors established wholesale relationships.
- Online:App-based drop distribution enables direct margin capture and first-party data accumulation from scarcity-driven purchase behavior in Brazil and European club markets.
- Retail Stores:Physical presence supports sizing verification for footwear and immediate gratification for tournament-year national kit releases.
- Wholesale:Club and federation partnerships rely on volume commitments and preseason allocation management.
- Specialty Shops:Curated assortments serve localized club affiliation density and customization services.
Online holds the largest share; momentum sits with Retail Stores as experiential commerce investments deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port of Santos throughput underwrites Brazil's dominance in football sportswear commerce, channeling premium kit imports and domestic production exports across Latin America. This logistics backbone supports the region's unmatched football culture penetration.
Brazil
Federation-backed youth academy expansion and club-affiliated fan commerce drive procurement volume across all consumer tiers. ANVISA monitors textile flammability standards for youth apparel safety compliance. São Paulo's manufacturing corridor concentrates polyester blending facilities serving domestic clubs and export markets.
Germany
EU Extended Producer Responsibility mandates accelerate closed-loop material sourcing for technical garments. ECHA REACH restrictions on perfluorinated chemicals force water-repellent coating reformulations ahead of tournament cycles. Bavaria's textile engineering clusters pilot biodegradable elastane alternatives in compression layer production.
United States
Direct-to-consumer platform adoption and recreational league participation sustain replacement cycles for match-grade footwear. The Consumer Product Safety Commission enforces drawstring entanglement hazard standards for youth football apparel. Greater Los Angeles hosts specialized cleat customization workshops serving academy and collegiate programs.
China
Domestic club sponsorship growth and manufacturing scale advantages position the market for supply chain control. SAMR oversees product safety certifications under GB standards for athletic wear imports. Guangdong Province's Pearl River Delta concentrates polyester mesh weaving operations for export-oriented jersey production.
United Kingdom
Premier League global viewership sustains fan-identification commerce through authenticated digital drops. The UK's Competition and Markets Authority reviews exclusivity arrangements in club kit supply agreements. Manchester's sportswear design studios specialize in four-way stretch integration for professional match wear.
Football Sportswear Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in fabric and closure supply. The vendor base concentrates around heritage sportswear houses with federation partnerships and digital-native challengers with direct-to-consumer infrastructure. Two strategic archetypes dominate: vertically integrated multinationals controlling design-to-retail pipelines, and specialist suppliers capturing niche performance segments through technical differentiation. Competitive moves center on exclusive club sponsorship acquisitions and proprietary app-based distribution channel construction.
Among heritage German sportswear houses, Adidas AG and PUMA SE occupy positions defined by federation anchoring and club sponsorship density respectively. Nike Inc. represents the platform-integrator archetype through its SNKRS ecosystem and direct relationship infrastructure. These three entities exemplify the competitive tension between wholesale partnership legacy and direct margin capture acceleration.
| Leading Market Players |
|---|
| Under Armour Inc. |
| ASICS Corp. |
| Nike Inc. |
| Mizuno Corp. |
| New Balance Athletics Inc. |
| Adidas AG |
| ANTA Sports Products Ltd. |
| JOMA SPORT SA |
| PUMA SE |
| Others |
Cost & Logistics Intelligence
Guangdong Province's Pearl River Delta concentrates polyester mesh weaving capacity that feeds directly into downstream pricing power for jersey suppliers. São Paulo's manufacturing corridor anchors Brazil's domestic premium kit production, creating regional cost advantages for federation procurement programs. This geographic bifurcation between Asian contract manufacturing and Latin American domestic supply shapes margin capture across fan-commerce and institutional channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates authenticated club drops from mass retail replenishment and entry-level academy procurement. Price differentiation rests on fabric certification grade and volume scale, with FIFA Equipment Regulations compliance commanding measurable premiums. Pricing pressure stems from recycled nylon feedstock volatility compressing sustainable product margins. Youth academy buyers exhibit highest price sensitivity; scarcity-driven fan-identification buyers show lowest.
Supply Chain Analysis
Contract-manufacturing concentration sits with specialized polyester blenders in China's Pearl River Delta, Vietnam's textile corridor, and Bangladesh's knitwear clusters. Raw material dependencies draw from petroleum-derived resin, post-consumer waste collection networks, and elastane polymer feedstock. Single-source vulnerability in biodegradable elastane alternatives constrains technical garment scaling. Distribution runs through direct-to-consumer platforms, wholesale club partnerships, and federation-backed institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Football sportswear sits in early-cycle expansion as federation-backed youth academy funding accelerates institutional procurement penetration across emerging football markets.
For Market Incumbents: Pre-empt direct-to-native platform challengers by deepening SNKRS-style app infrastructure for first-party data capture. Consolidate backward integration into recycled polyester feedstock to defend margin position against sustainable sourcing mandates. Lock multi-year federation partnerships before tournament cycles concentrate supplier selection windows. For New Entrants and Emerging Players: Build out second-tier European league sponsorship density where Adidas and Nike maintain lighter club coverage. Target Brazil's underserved interior states beyond São Paulo and Rio de Janeiro for grassroots academy penetration. Anchor go-to-market through digital-native scarcity drops rather than wholesale retail buildout. For Investors and Strategic Acquirers: Long-term, this sits as a brand-licensing and platform-control play because recurring federation and club relationships generate contracted revenue visibility. Acquisition focus should center on specialist suppliers with FIFA certification capabilities and biodegradable material pipelines. Monitor EU Extended Producer Responsibility implementation velocity as inflection signal for sustainable sourcing investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | SNKRS-style drops enable margin capture and first-party data ownership from Brazil's fan-identification buyers. |
| Federation Partnership Acquisition | Multi-year kit supply agreements with national teams anchor volume through tournament cycles. |
| Sustainable Material Pipeline Investment | Biodegradable elastane alternatives compress sustainability premiums as EU REACH restrictions tighten. |
| Second-Tier League Sponsorship Density | Underserved European clubs outside top divisions offer partnership white space with lower competitive intensity. |
| Youth Academy Procurement Channel Development | Grassroots funding expansion creates institutional volume anchors distinct from volatile fan-commerce. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with brand licensing directors, federation procurement officers, polyester plant managers, and retail category buyers; and secondary validation through customs records, SEC 10-K filings, EU ECHA regulatory submissions, and federation equipment tender documents. Bottom-up demand modeling triangulated against top-down market sizing across product type, material composition, consumer segment, and distribution channel dimensions.
Forecast inputs considered grassroots development funding trajectories, direct-to-consumer platform adoption curves, and sustainable material cost compression timelines across the projection horizon. Segmentation modeling captured product type, material grade tier, consumer application context, and regional regulatory cluster variations. CAGRs derived from volume elasticity analysis against price-point migration and substitution pattern assessment.
Stress conditions across recycled feedstock availability, EU Extended Producer Responsibility enforcement timing, and tournament cycle disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on federation funding continuity and platform adoption saturation. Quarterly review of youth academy contract awards and biodegradable material pilot scale-up is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Plug Market
Others
United States Air Furnaces Market
Others
Global Duty-Free Retailing Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
China Online Gambling Market
Others
Asia-Pacific Intercom Devices Market
Others
China Cloud Gaming Technology Market
Others
Advertising Intelligence Solution Market
Others
Global Telemetry Market
Others
Latin America Smart Home Market
Others
Operator Training Simulator Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Air Separation Plant Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Construction Fabrics Market
Others
Latin America Fire Sprinklers Market