
 Space Cables Market | 2026-2036
Space Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Space Cables Market Insights
Multi-source procurement for radiation-hardened interconnects is shifting toward vertically integrated suppliers with in-house polymer compounding. TE Connectivity leverages captive fluoropolymer extrusion to control outgassing consistency. W.L. Gore & Associates anchors its position through proprietary expanded PTFE dielectrics certified to ESA specifications. Axon' Cable SAS specializes in miniature harness assemblies for European science missions.
Space cables are insulated electrical conductors engineered to withstand atomic oxygen exposure, thermal cycling between -150°C and +200°C, and cumulative radiation doses exceeding 100 krad(Si), serving to transmit power and data across satellite buses and payload interfaces. Optical fiber cables and radiation-hardened coaxial products capture premium margin pools as optical inter-satellite links displace copper for high-bandwidth payloads. Flat ribbon cables retain stable demand in spacecraft wiring harnesses where mass and volume constraints dominate design trade-offs.
NASA outgassing requirements per ASTM E595, ESA ECSS-Q-ST-70-02C, and JAXA JERG-2-135A collectively dictate material selection and lot-traceability protocols for flight-qualified cables. Compliance with these standards shapes supplier qualification timelines and creates barriers for unapproved manufacturers. Stakeholders must monitor evolving debris mitigation rules and quantum communication payload requirements that will redefine cable performance benchmarks.
Market Dynamics
Radiation-hardened polymer compounding capabilities are concentrating among suppliers with captive extrusion assets, compressing qualification timelines for constellation-scale programs and reshaping procurement leverage across prime contractors.
Growth Catalysts
- ESA ECSS-Q-ST-70-02C outgassing mandates:Certification requirements for low-volatile materials are filtering supplier pools and accelerating qualification of European compounders with in-house testing infrastructure.
- LEO constellation deployment:Satellite manufacturers are scaling harness production for thousand-satellite networks, pulling demand for standardized ribbon cable configurations.
- Atomic oxygen-resistant fluoropolymers:Material advances in FEP and PFA extrusion are extending operational life for cables exposed to orbital degradation environments.
Market Restraints
- Fluoropolymer resin supply concentration:Feedstock production clusters in the United States and Japan, exposing cable manufacturers to geopolitical disruption and allocation constraints.
- Proprietary expanded PTFE dielectrics:Single-source dependency for high-performance signal cables limits second-sourcing options for science mission primes.
- Qualification timeline compression:NASA ASTM E595 lot-traceability protocols extend vendor onboarding to 18-24 months, blocking rapid supplier switching.
Strategic Opportunities
- Optical inter-satellite link expansion:Photonic payload architectures are creating white space for radiation-hardened fiber cable assemblies in high-bandwidth constellations.
- Debris mitigation compliance services:Emerging end-of-life disposal rules are opening consulting and redesign revenue streams for cable harness engineering firms.
- Japan JAXA JERG-2-135A alignment:Harmonization with European and US standards is reducing requalification burden for suppliers targeting multi-agency programs.
Industry Challenges
- Radiation-hardening polymer chemist scarcity:Formulation expertise for space-grade compounds resides with a narrow cohort of specialists approaching retirement.
- Cleanroom extrusion capacity constraints:Class 1000 manufacturing environments require capital-intensive buildouts that strain mid-tier cable producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Cables Market |
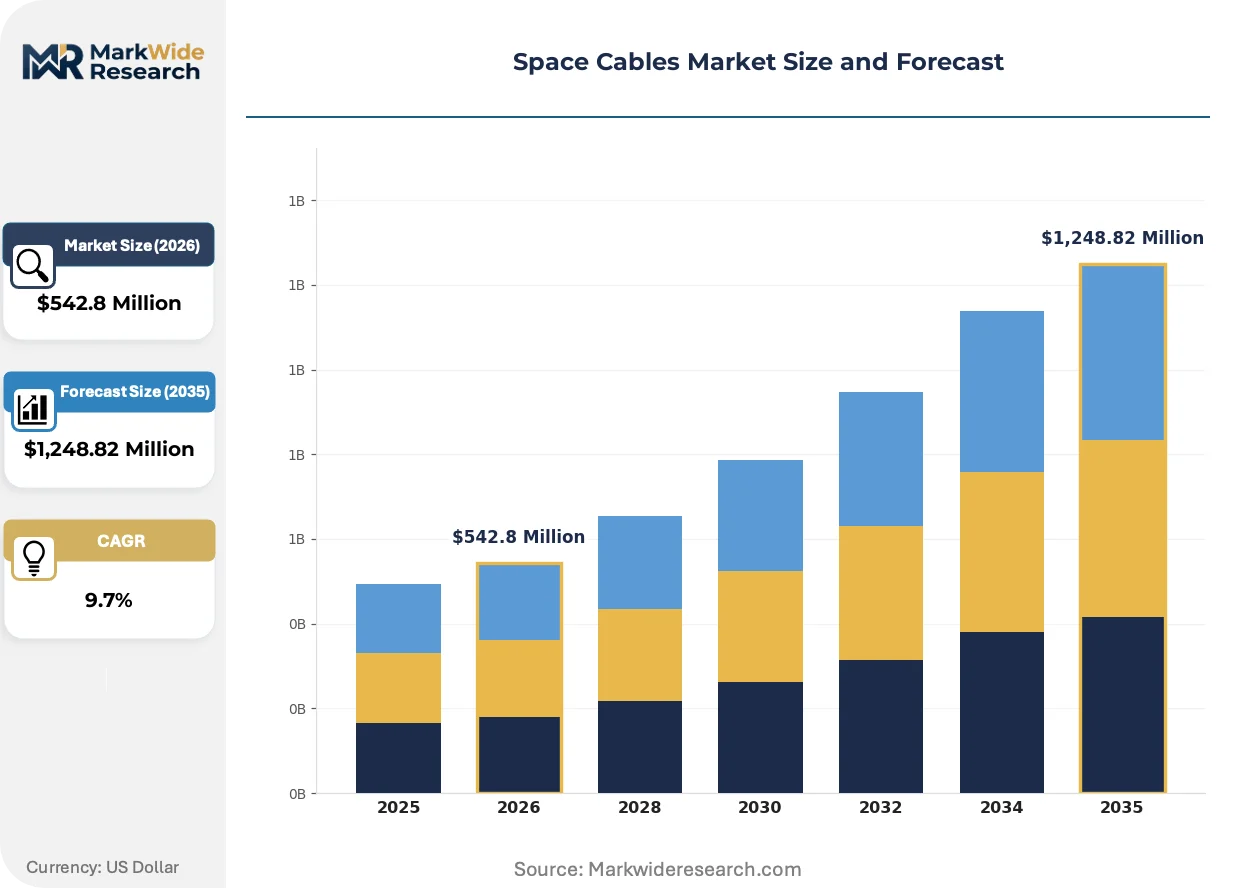
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $1,248.82 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coaxial Cables, Optical Fiber Cables, Twisted Pair Cables, Flat Ribbon Cables, Flexible Printed Circuits Application: Satellite Communication, Spacecraft Wiring, Ground Station Equipment, Space Robotics, Launch Vehicle Systems Technology: Low Outgassing, Radiation Hardened, Temperature Resistant, Lightweight Composite, High Frequency End User: Satellite Manufacturers, Space Agencies, Aerospace Contractors, Telecommunication Operators, Research Institutes |
| Companies Covered | Amphenol Corporation, TE Connectivity, Axon' Cable SAS, W.L. Gore & Associates, Nexans SA, Prysmian Group, Huber+Suhner, Cinch Connectivity Solutions, Cicoil Flat Cables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Cables Market Trends and Innovations
Material certification convergence and optical payload migration are compressing traditional copper harness architectures while elevating polymer purity standards across supply tiers.
Expanded PTFE dielectric technology is consolidating signal integrity performance for high-frequency payloads. Satellite manufacturers with optical inter-satellite link programs are specifying these materials for coaxial feeder assemblies. The technology is consolidating procurement toward suppliers with ESA-qualified compounding lines, marginalizing generalist cable producers.
REACH SVHC disclosure requirements are tightening supply chain documentation burdens for European space primes. Compounders must now certify fluoropolymer resin origins and additive packages through full material declaration. Small harness assembly houses in France and Germany are responding by consolidating supplier panels to reduce audit complexity.
Buyer concentration among mega-constellation operators is compressing contract structures from cost-plus to fixed-price with volume commitments. Prime contractors are transferring qualification cost risk to cable vendors through multi-year offtake agreements. This shift is most visible in United States procurement patterns, where Space Development Agency programs are driving standardized harness specifications.
Space Cables Market Segmentation
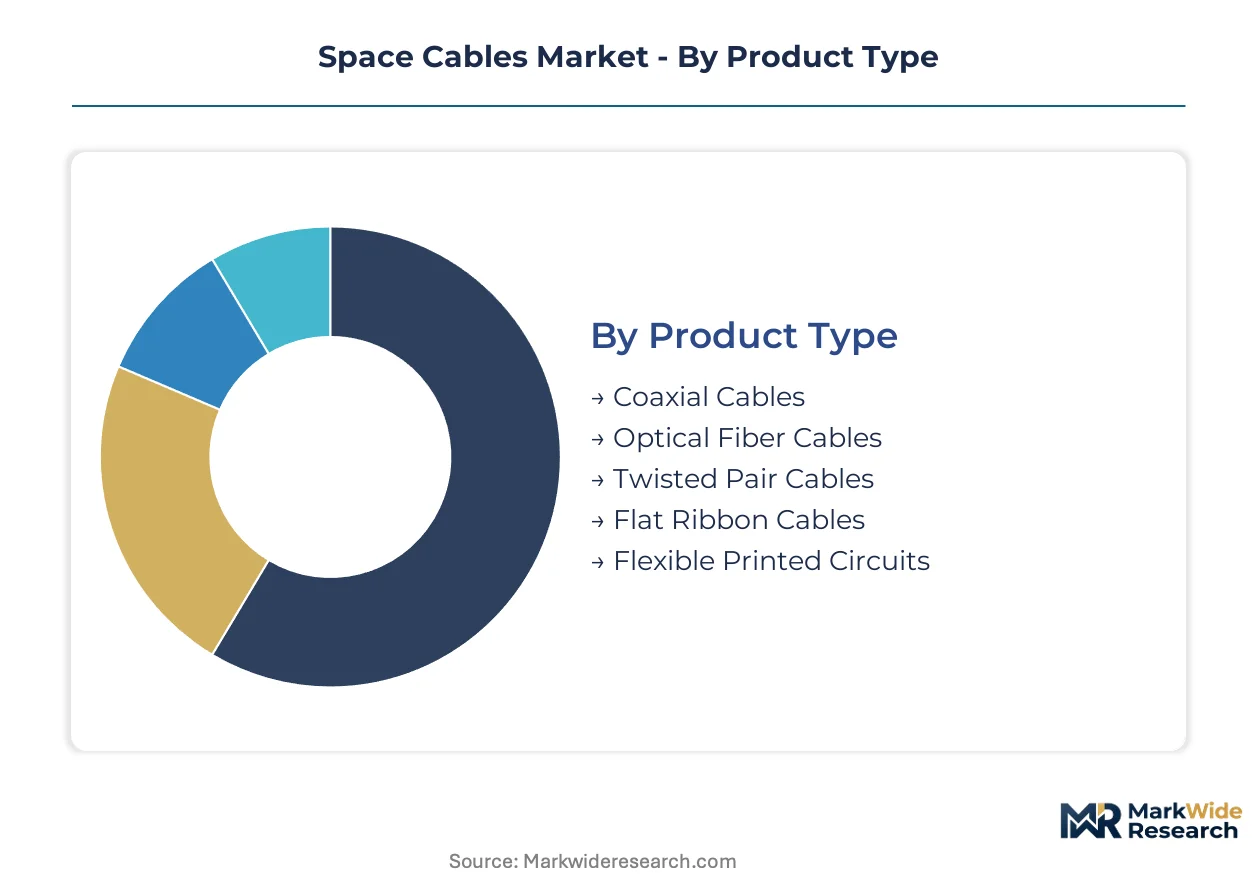
Space cable procurement decisions pivot on mission-critical performance thresholds rather than cost optimization. Buyers segment requirements across orbital environment, payload bandwidth, and agency certification standards.
Product Type:
Mass-per-meter and signal integrity specifications drive product selection for constellation manufacturers.
- Coaxial Cables:Radiation-hardened coaxial constructions with fluoropolymer dielectrics transmit RF signals across satellite buses. Demand concentrates in United States mega-constellation programs where high-frequency feeder assemblies link phased array antennas to transponders.
- Optical Fiber Cables:Single-mode and multi-mode fiber assemblies enable terabit-class inter-satellite links with immunity to electromagnetic interference. Deployment accelerates in European science missions and commercial relay networks where optical crosslinks displace copper backbones.
- Twisted Pair Cables:Shielded twisted pair configurations carry command and telemetry data at lower mass than coaxial alternatives.
- Flat Ribbon Cables:Parallel conductor arrays reduce harness volume in tight spacecraft avionics bays.
- Flexible Printed Circuits:Polyimide-based flexible circuits integrate power distribution and signal routing in deployable payload mechanisms.
Coaxial cables lead on scale; optical fiber cables lead on momentum.
Application:
Orbital altitude and mission duration dictate material qualification tiers across use cases.
- Satellite Communication:Geostationary and LEO communication satellites deploy radiation-hardened harnesses for 15-year operational lifespans. Procurement clusters with prime contractors in France and Japan building bent-pipe and regenerative payloads.
- Spacecraft Wiring:Manned and unmanned spacecraft require atomic oxygen-resistant insulation for external routing. NASA ISS resupply missions and JAXA HTV programs sustain demand for EVA-compatible cable assemblies.
- Ground Station Equipment:Terrestrial antenna farms use commercial-grade cables with reduced outgassing constraints.
- Space Robotics:Articulated manipulator arms demand high-flexure cable designs for repeated bending cycles.
- Launch Vehicle Systems:Expendable and reusable rockets specify lightweight harnesses with pyro-resistant jacketing.
Satellite communication dominates revenue contribution; spacecraft wiring commands the steepest certification premiums.
Technology:
Agency mandates and orbital environment severity determine technology adoption curves.
- Low Outgassing:Materials certified to ASTM E595 and ECSS-Q-ST-70-02C limits prevent molecular contamination of optical payloads and thermal control surfaces. ESA science missions and NASA Discovery-class programs mandate this technology for all vacuum-exposed harnesses.
- Radiation Hardened:Polymer formulations with aromatic stabilizers withstand cumulative doses exceeding 100 krad(Si) in MEO and GEO orbits. United States national security satellites and European Galileo navigation spacecraft specify hardened insulation for electronics bay routing.
- Temperature Resistant:Extended temperature range compounds operate across -150°C to +200°C thermal cycles.
- Lightweight Composite:Carbon fiber and advanced polymer matrices reduce harness mass fraction for small satellites.
- High Frequency:Controlled-impedance constructions preserve signal integrity at millimeter-wave frequencies.
Radiation-hardened technology anchors the largest installed base; low outgassing specifications are expanding most quickly.
End User:
Procurement scale and qualification burden vary sharply across customer categories.
- Satellite Manufacturers:Commercial constellation operators and geostationary satellite builders drive standardized harness specifications at volume. United States primes producing LEO broadband networks pull demand for automated ribbon cable assembly lines.
- Space Agencies:NASA, ESA, and JAXA impose lot-traceability and material declaration requirements that extend supplier qualification timelines. Science mission directorates in France and Germany sustain demand for custom harness engineering with full pedigree documentation.
- Aerospace Contractors:Tier-1 system integrators manage subcontractor cable procurement for major platform programs.
- Telecommunication Operators:Fleet owners specify replacement harnesses for in-orbit servicing and ground spare maintenance.
- Research Institutes:University and laboratory CubeSat programs purchase commercial off-the-shelf cables with reduced qualification overhead.
Satellite manufacturers capture the highest volume share; space agencies command the most stringent specification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier geography as compounders migrate toward jurisdictions with streamlined space-agency qualification protocols. The cost-of-compliance gap between established and emerging certification hubs is redirecting capital toward testing infrastructure rather than labor arbitrage.
United States
NASA's ASTM E595 outgassing mandates and Space Development Agency constellation programs anchor North American demand. The FAA regulates commercial launch integration while the FCC governs spectrum licensing for satellite operators. Colorado and California host concentrated prime contractor clusters where ribbon cable assembly lines scale for LEO broadband networks.
France
ESA's ECSS-Q-ST-70-02C certification requirements filter supplier pools toward European compounders with in-house testing infrastructure. The French national space agency CNES coordinates qualification protocols with Toulouse-based satellite manufacturers. The Occitanie region concentrates harness engineering firms serving science missions with full pedigree documentation.
Japan
JAXA's JERG-2-135A standards harmonization with ESA and NASA protocols reduces requalification burden for multi-agency suppliers. METI oversees industrial policy supporting domestic fluoropolymer resin production. The Kanto region around Tokyo hosts prime contractors building HTV resupply spacecraft and navigation satellite payloads.
Germany
German science mission directorates sustain demand for custom harness engineering with REACH SVHC disclosure compliance. The KBA regulates automotive-derived materials crossing into aerospace applications. Bavaria's industrial corridor anchors specialized cable assembly houses consolidating supplier panels to reduce audit complexity.
United Kingdom
UK Space Agency funding for satellite manufacturing clusters drives procurement of standardized harness configurations. The Health and Safety Executive governs cleanroom manufacturing standards for Class 1000 extrusion environments. Scotland's emerging spaceport infrastructure is pulling cable vendors toward launch-integration service contracts.
Space Cables Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent optical interconnect architectures. The supplier base concentrates among compounders with captive fluoropolymer extrusion assets and ESA-qualified testing infrastructure. Three archetypes dominate: vertically integrated material specialists, regional harness assembly houses, and diversified industrial cable manufacturers extending into space-grade certification. Competitive moves center on backward integration into resin compounding and multi-year offtake agreements that transfer qualification risk to vendors.
Among diversified connectivity specialists, TE Connectivity and Amphenol Corporation exemplify scale-driven archetypes with broad aerospace portfolios. W.L. Gore & Associates occupies a distinct position anchoring the premium signal-integrity tier through proprietary dielectric technology. Axon' Cable SAS represents the regional specialist model concentrated on European science mission engineering. These three patterns—scale diversification, materials science dominance, and geographic specialization—collectively define competitive positioning across procurement tiers.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Axon' Cable SAS |
| W.L. Gore & Associates |
| Nexans SA |
| Prysmian Group |
| Huber+Suhner |
| Cinch Connectivity Solutions |
| Cicoil Flat Cables |
| Others |
Pricing and Supply Chain Analysis
Radiation-hardening polymer chemist concentration in the United States and France creates labor-cost differentials that widen pricing spreads between premium ESA-qualified harnesses and standard constellation-grade ribbon cables.
Pricing Analysis
Prime contractor direct procurement discounts compress distributor margins to single-digit percentages in United States mega-constellation programs. Pricing stratifies across ESA-certified premium tiers, NASA-qualified standard tiers, and commercial off-the-shelf economy tiers based on lot-traceability depth and outgassing test documentation. Cost compression in the economy tier intensifies as Space Development Agency programs drive fixed-price contract structures with multi-year volume commitments. Research institutes purchasing CubeSat-grade cables exhibit the highest price sensitivity, while space agencies commanding full pedigree documentation accept the steepest premiums.
Supply Chain Analysis
Single-source vulnerability sits with United States and Japanese fluoropolymer resin producers, exposing cable manufacturers to geopolitical allocation constraints. Feedstock production draws from DuPont Chemours facilities in West Virginia, Daikin operations in Osaka, and Solvay compounding lines in Italy. Tariff exposure on fluoropolymer imports into the European Union threatens margin stability for French harness assemblers. Distribution runs through prime contractor-managed supplier panels with consolidated qualification protocols, bypassing traditional distributor networks for flight-critical programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as optical inter-satellite link migration pulls procurement toward radiation-hardened fiber cable assemblies with premium specification requirements.
For Market Incumbents: Acquire captive fluoropolymer extrusion assets to secure outgassing consistency against emerging compounders with ESA-qualified testing infrastructure. Consolidate supplier panels around automated ribbon cable assembly lines in Colorado and California to capture Space Development Agency program scale. Defend margin position by locking multi-year offtake agreements that transfer qualification timeline risk to constellation operators. For New Entrants and Emerging Players: Launch via debris mitigation compliance consulting services attached to end-of-life harness redesign contracts. Target United Kingdom satellite manufacturing clusters around Scotland's emerging spaceport infrastructure where qualification burden remains lighter than ESA or NASA tiers. Penetrate through optical fiber cable assembly partnerships with European science mission primes seeking second-source options for high-bandwidth payloads. For Investors and Strategic Acquirers: Diversified industrial cable manufacturers are the most active acquirer in this space, pursuing backward integration into resin compounding to replicate TE Connectivity's captive supply model. Long-term viability hinges on positioning within the optical payload migration arc rather than legacy copper harness replacement cycles. Monitor JAXA JERG-2-135A harmonization progress as the signal indicating reduced requalification burden for multi-agency suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Captive extrusion assets compress NASA ASTM E595 qualification timelines for constellation-scale programs. |
| Optical Fiber Cable Assembly Line Investment | Radiation-hardened fiber capacity captures terabit-class inter-satellite link demand from European science missions. |
| ESA-Qualified Testing Infrastructure Buildout | In-house ECSS-Q-ST-70-02C certification capability filters supplier pools toward European compounders. |
| Multi-Year Offtake Agreement Structuring | Fixed-price contracts with volume commitments transfer qualification cost risk from primes to cable vendors. |
| Debris Mitigation Compliance Service Launch | Emerging end-of-life disposal rules open consulting revenue streams for harness engineering firms in France and Germany. |
Research Methodology
Multiple input streams — satellite manufacturer procurement directors, ESA materials qualification officers, fluoropolymer resin supply specialists, and cleanroom extrusion facility managers — were reconciled against customs trade data, NASA technical standards documentation, and SEC aerospace segment filings. Primary fieldwork with harness engineering firms in Toulouse and Tokyo validated secondary intelligence on qualification timeline compression. Bottom-up build of cable assembly volumes across constellation programs was triangulated against top-down prime contractor spend estimates.
Historical shipment patterns were cross-referenced against panel input from satellite bus designers and optical payload architects to anchor growth assumptions across the projection horizon. Segmentation modeling captured product type splits, application tiers by orbital environment, technology adoption curves for low-outgassing versus radiation-hardened specifications, and end-user concentration among mega-constellation operators versus space agency science missions. CAGRs were derived from unit economics analysis of mass-per-meter specifications and signal integrity premiums.
Several conditions sit outside the modeled scope, including specific debris mitigation rule enactment dates and quantum communication payload cable performance benchmarks still under agency review. Forecasts reflect assumptions about fluoropolymer resin supply stability and cleanroom extrusion capacity expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South America Orange Market
Others
United States Bean Bags Market
Others
Vo5g Market
Others
Thermoformed Plastics Market
Others
Idaas Market
Others
Bulgur Market
Others
Dried Fruit Extracts Market
Others
Wind and Solar Hybrid Street Light Market
Others
Sound Reinforcement Market
Others
Aircraft Switches Market
Others
Global Fertility Tracking Apps Market
Others
Asia-Pacific Battery E-Commerce Market
Others
North America Printed Signage Market
Others
India Battery E-Commerce Market
Others
India Home Automation Market
Others
Electrical Calibration Equipment Market