
 Embedded Computer Market | 2026-2036
Embedded Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Computer Market Intelligence
Edge-native computing architectures is reconfiguring how embedded systems are designed, moving inference workloads closer to sensors and reducing dependency on cloud round-trips. Intel Corporation leverages its x86 ecosystem and foundry partnerships to sustain design wins in industrial gateways. NXP Semiconductors anchors automotive-grade microcontroller supply chains through its domain-specific safety portfolios. Texas Instruments differentiates by controlling analog integration at the board level, a capability that defends margin pools in medical and factory automation segments.
An embedded computer integrates a microprocessor or microcontroller with memory, I/O interfaces, and application-specific software onto a compact board or module, typically operating across temperature ranges from -40°C to 85°C for industrial reliability. Its primary purpose is to execute dedicated control, monitoring, or signal-processing tasks within larger electromechanical systems without direct human intervention. Industrial Computers occupy the highest absolute revenue tier due to longevity requirements and certification complexity in factory floors and energy infrastructure. ARM-based designs represent the fastest-expanding technology segment as licensees optimize power-performance ratios for battery-constrained IoT endpoints. Microcontrollers retain the largest volume position across Consumer Electronics and Smart Home Systems where unit economics favor highly integrated single-chip solutions.
The Federal Communications Commission shapes radio module certification pathways that gate market access for wireless-enabled embedded devices in the United States. The European Medicines Agency and FDA both enforce electromagnetic compatibility and safety standards that determine design specifications for Healthcare applications and clinical equipment interfaces. The EU AI Act introduces conformity assessment obligations for embedded systems performing automated decision-making in automotive and robotics contexts. Stakeholders must monitor how fragmentation between CE marking, FCC Part 15, and emerging AI-specific compliance frameworks affects platform standardization and regional product variants.
Market Dynamics
Edge-native inference workloads are compressing hardware refresh cycles as automotive and industrial buyers prioritize deterministic latency over cloud-dependent architectures.
Growth Catalysts
- EU AI Act compliance mandates:Automotive suppliers accelerate embedded system redesigns to satisfy conformity assessment obligations for automated decision-making in robotics and autonomous platforms.
- Electric powertrain electrification:Battery management systems and motor control units drive microcontroller procurement volumes across Germany, Japan, and United States manufacturing clusters.
- Industrial IoT sensor densification:Factory automation deployments in energy infrastructure and process industries expand ARM-based module demand for real-time condition monitoring.
Market Restraints
- Foundry capacity concentration:Advanced node availability at Taiwan and South Korea semiconductor fabricators constrains automotive-grade chip supply security.
- Analog component cost volatility:Discrete power management IC pricing fluctuation compresses board-level margin pools for medical device integrators.
- Functional safety certification burden:ISO 26262 ASIL-D compliance timelines extend product development cycles by twelve to eighteen months for safety-critical automotive applications.
Strategic Opportunities
- India industrial automation underpenetration:PLI scheme incentives for electronics manufacturing attract embedded system assembly capacity to Pune and Chennai industrial corridors.
- Healthcare edge AI convergence:Fusion of machine learning accelerators with real-time operating systems enables portable diagnostic equipment categories previously tethered to hospital infrastructure.
- CE marking harmonization tailwinds:Consolidated electromagnetic compatibility and safety standards reduce regional variant proliferation for European market entry.
Industry Challenges
- Embedded Linux security patching latency:Long-term support gaps in open-source kernel maintenance expose industrial gateways to CVE exploitation windows.
- Mixed-signal design talent scarcity:Shortage of engineers proficient in analog-digital integration constrains board-level optimization for factory automation customers.
- Legacy fieldbus integration friction:Proprietary industrial Ethernet protocols resist standardization, complicating retrofit deployments in brownfield manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Computer Market |
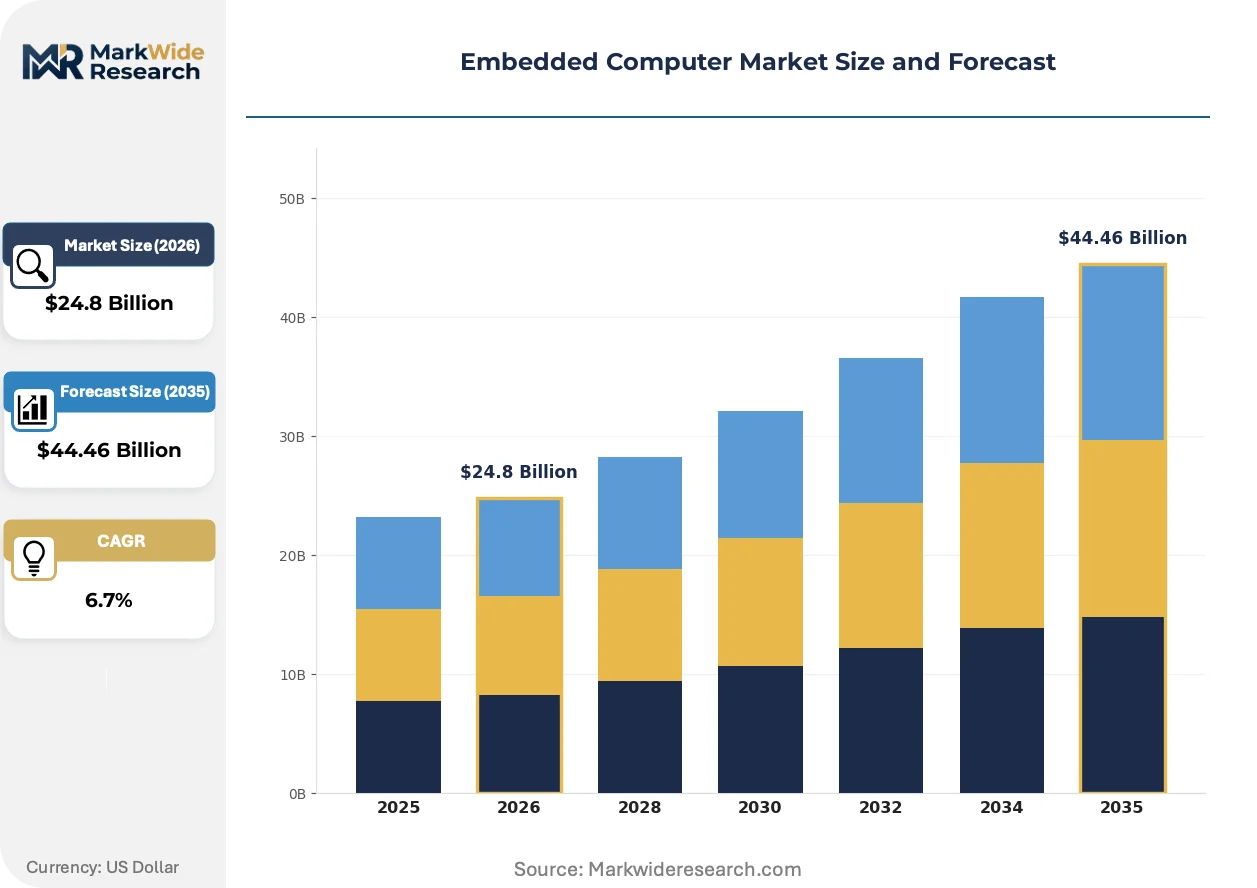
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Computers, Single-Board Computers, Microcontrollers, Embedded Processors Technology: ARM, x86, PowerPC, FPGA End User: Automotive, Consumer Electronics, Healthcare, Aerospace Application: IoT Devices, Smart Home Systems, Robotics, Telecommunications |
| Companies Covered | Intel Corporation, Texas Instruments, NXP Semiconductors, STMicroelectronics, Renesas Electronics Corporation, Advantech Co. Ltd., AAEON Technology Inc., Kontron AG, Avalue Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Computer Market Strategic Shifts & Innovations
Heterogeneous computing fabrics are dissolving the boundary between microcontrollers and application processors, enabling single-chip solutions that previously required discrete component stacks.
RISC-V open instruction set architectures are rendering obsolete proprietary microcontroller licensing models that locked automotive suppliers into single-vendor roadmaps. Tier-1 suppliers in Germany and Japan now pilot royalty-free cores for domain controller consolidation. This shift compresses semiconductor IP procurement costs while fragmenting software toolchain ecosystems.
The EU AI Act introduces mandatory conformity assessment for embedded systems performing automated decision-making in robotics and automotive contexts. Industrial equipment manufacturers must document algorithmic transparency and risk management protocols before CE marking. Medical device integrators face overlapping obligations from MDR cybersecurity amendments, forcing dual-track compliance investments.
Automotive OEMs now specify outcome-based subsystem contracts that transfer firmware maintenance liability to tier-1 suppliers. Bosch and Continental procurement teams in Stuttgart unbundle hardware from long-term software update commitments. This restructuring concentrates design-in authority at vehicle platform architects while marginalizing traditional board-level vendors.
Embedded Computer Market Segmentation
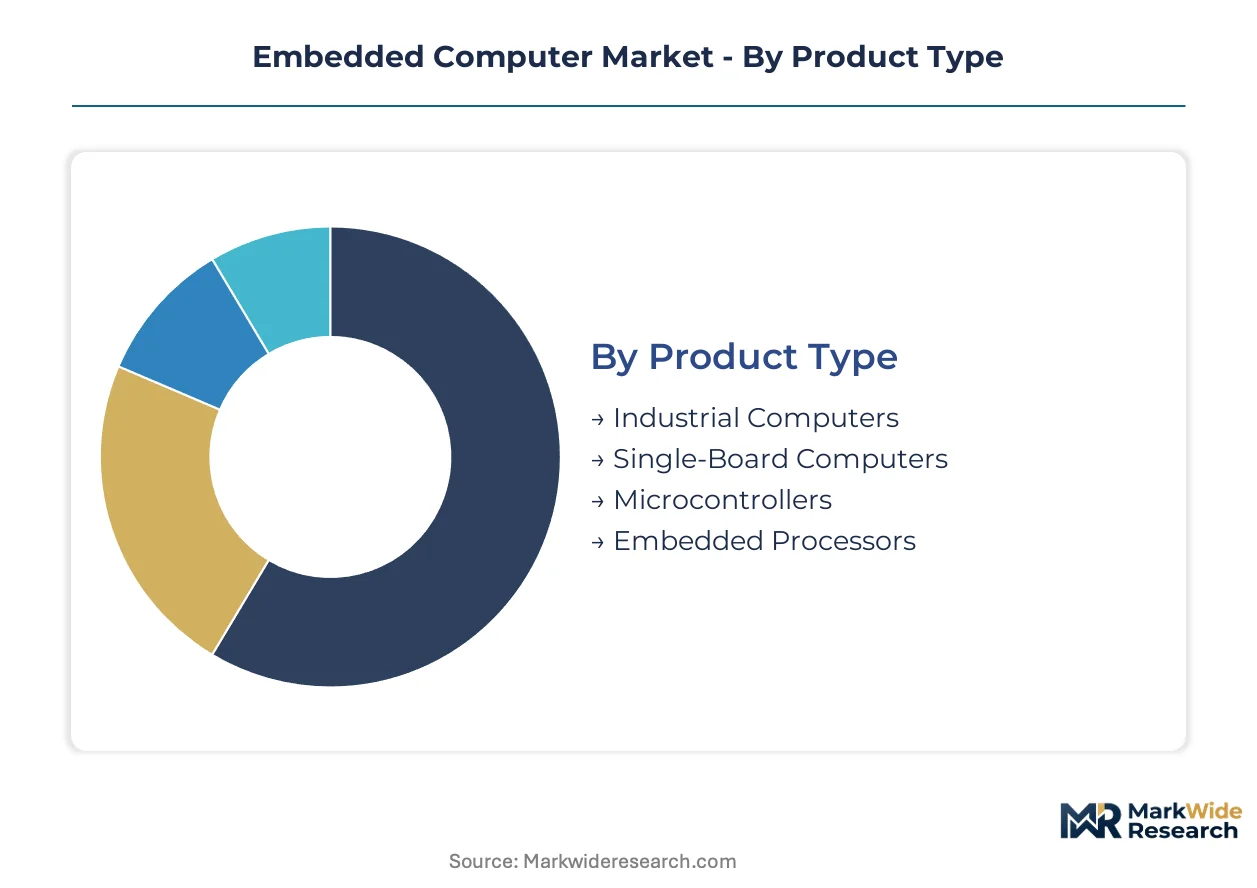
Embedded computer segmentation reveals divergent service intensity profiles across product architectures. Industrial deployments demand decade-long firmware maintenance contracts, while consumer-grade microcontrollers operate on minimal aftermarket engagement.
Product Type:
After-sales-service intensity varies dramatically across form factors, with ruggedized industrial units requiring continuous thermal monitoring and field-replaceable component programs.
- Industrial Computers:These systems integrate extended temperature-grade components, passive cooling architectures, and real-time operating system support for factory floor longevity. Demand concentrates in German automotive manufacturing clusters and US energy infrastructure, where ISO 26262 ASIL-D certification mandates extend supplier liability windows.
- Microcontrollers:Highly integrated single-chip solutions embed flash memory, analog peripherals, and low-power modes for battery-constrained endpoints. Japanese automotive tier-1 suppliers and German industrial automation OEMs anchor procurement volumes, driven by electric powertrain electrification and motor control unit densification.
- Single-Board Computers:Compact modules stack processor, memory, and I/O on standardized footprints for rapid prototyping pipelines.
- Embedded Processors:Multi-core architectures handle heterogeneous workloads in network appliances and medical imaging equipment.
Industrial Computers hold the largest share; momentum sits with Microcontrollers.
Technology:
Cost tier stratification separates royalty-bearing proprietary architectures from emerging open-source alternatives, reshaping semiconductor IP procurement economics.
- ARM:License-optimized cores dominate power-performance efficiency benchmarks for IoT endpoints and wearable devices. Design activity clusters in Cambridge, UK ecosystem partners and Austin, Texas R&D facilities, propelled by battery-constrained sensor densification in factory automation.
- x86:Intel's ecosystem sustains backward compatibility advantages for industrial gateways requiring legacy software stacks. German machinery OEMs and Japanese robotics manufacturers specify these architectures for deterministic latency workloads in brownfield retrofit deployments.
- RISC-V:Open instruction set architectures eliminate per-unit licensing fees for cost-sensitive volume applications.
- FPGA:Reconfigurable logic fabrics accelerate custom signal processing in aerospace radar and telecommunications infrastructure.
x86 commands premium pricing tiers; ARM gains share fastest across battery-constrained segments.
End User:
Application maturity cycles stretch from eighteen-month consumer refresh rates to fifteen-year automotive platform commitments, fragmenting supplier engagement models.
- Automotive:Domain controllers and zone architectures consolidate embedded computing for autonomous driving and electric powertrains. Stuttgart and Tokyo headquarters anchor design-in authority, with EU AI Act conformity assessment obligations forcing algorithmic transparency documentation.
- Healthcare:Portable diagnostic equipment and patient monitoring systems demand electromagnetic compatibility certification under FDA and EMA frameworks. German medical device integrators and Swiss precision equipment manufacturers concentrate procurement for edge-AI-enabled imaging modalities.
- Consumer Electronics:Smartphones and wearables drive microcontroller volumes on compressed development timelines.
- Aerospace:DO-178C certification requirements govern flight-critical avionics with decade-long supplier liability windows.
Automotive generates the highest absolute revenue; Healthcare shows the steepest expansion trajectory.
Application:
Customer type differentiation separates specification-driven industrial buyers from price-sensitive consumer OEMs, with telecommunications operators occupying intermediate procurement sophistication tiers.
- IoT Devices:Sensor endpoints and edge gateways aggregate telemetry for predictive maintenance in energy infrastructure. US utility operators and German manufacturing clusters deploy ARM-based modules for real-time condition monitoring, constrained by FCC Part 15 and CE marking radio certification pathways.
- Robotics:Collaborative and autonomous mobile robots integrate heterogeneous computing fabrics for simultaneous localization and mapping. Japanese automotive suppliers and German logistics equipment manufacturers specify safety-rated controllers under ISO 10218 and EU Machinery Directive obligations.
- Smart Home Systems:Voice assistants and security hubs prioritize acoustic processing and wireless connectivity integration.
- Telecommunications:Baseband processing and network function virtualization demand throughput-optimized embedded processors.
IoT Devices anchor current volumes; Robotics climbs fastest on automation capex recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tier-1 suppliers and industrial automation OEMs concentrate procurement authority in manufacturing clusters where electrification mandates and factory digitization programs intersect. Design-in activity clusters around R&D headquarters and certification-capable fabrication ecosystems.
Germany
Stuttgart anchors automotive embedded system design-in for domain controllers and electric powertrains. The EU AI Act imposes conformity assessment obligations on automated decision-making systems. Bavarian industrial corridors around Munich drive ARM-based module procurement for factory automation retrofits.
United States
Energy infrastructure operators and utility deployers generate demand for ruggedized industrial computers in substation automation. The FCC shapes radio module certification pathways under Part 15 for wireless-enabled devices. Austin and Silicon Valley R&D facilities concentrate edge-native computing architecture development.
Japan
Automotive tier-1 suppliers in Tokyo and Nagoya accelerate microcontroller procurement for battery management systems. METI industrial policy supports domestic semiconductor fabrication capacity expansion. Kyushu manufacturing clusters specialize in automotive-grade chip packaging and testing operations.
China
Industrial IoT sensor densification in Yangtze River Delta manufacturing zones expands embedded processor volumes. MIIT governs GB standards compliance for telecommunications and industrial equipment interfaces. Shenzhen ecosystem partners optimize cost-sensitive microcontroller designs for smart home export manufacturing.
India
PLI scheme incentives attract electronics manufacturing assembly capacity to Pune and Chennai industrial corridors. The country's national electronics regulator enforces BIS certification for safety-critical industrial deployments. Karnataka's Bangalore tech corridor hosts embedded software development centers serving automotive and medical device exporters.
Embedded Computer Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered engagement models. The vendor base organizes around semiconductor fabricators, board-level integrators, and subsystem contract manufacturers. Three archetypes dominate: IDM-controlled supply chains, fabless design houses with foundry partnerships, and vertically integrated industrial computer assemblers. Competitive moves concentrate on strategic partnerships for safety certification bundling and geographic expansion into underpenetrated industrial automation corridors.
Within the IDM archetype, Intel Corporation and Texas Instruments occupy positions defending x86 and analog-integrated portfolios respectively. NXP Semiconductors anchors automotive-grade microcontroller supply through domain-specific safety portfolios. These three entities exemplify how ecosystem control and certification depth determine design-win persistence in safety-critical segments.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Advantech Co. Ltd. |
| AAEON Technology Inc. |
| Kontron AG |
| Avalue Technology Inc. |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion drives freight cost volatility that propagates through automotive microcontroller supply chains, compressing margin pools for German tier-1 suppliers while amplifying price differentiation between ASIL-D certified and uncertified industrial computers.
Pricing Analysis
Cost-plus contracts indexed to Taiwan Semiconductor Manufacturing wafer pricing dominate procurement between automotive OEMs and microcontroller suppliers. Three-tier pricing structure across ASIL-D certified, industrial-grade, and commercial-grade levels reflects functional safety certification burden and after-sales service bundling. Price erosion runs through commercial-grade single-board computers as Shenzhen ecosystem partners flood export markets with cost-optimized ARM designs. Healthcare equipment manufacturers exhibit lowest price sensitivity due to FDA electromagnetic compatibility compliance requirements and decade-long liability windows.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for industrial gateway manufacturers. Taiwan, South Korea, and Japan anchor advanced node fabrication capacity for automotive-grade microcontrollers. Raw material dependencies center on silicon wafers, ABF substrate laminates, and rare-earth magnet components for motor control integration. Single-source vulnerability concentrates at TSMC's leading-edge foundry operations. Distribution runs through Arrow Electronics and Avnet for North American industrial automation customers, with direct OEM contracts prevailing in German automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded computing is approaching a platform-economics inflection where RISC-V open instruction set architectures dissolve proprietary licensing moats, forcing ecosystem interoperability investments to sustain design-win persistence.
For Market Incumbents: Pre-empt RISC-V fragmentation by anchoring safety-certified software toolchains around automotive domain controllers. Consolidate firmware maintenance liability through outcome-based subsystem contracts that transfer long-term update obligations to tier-1 suppliers. Deepen backward integration into automotive-grade packaging capacity at Kyushu manufacturing clusters to defend against foundry concentration risk.
For New Entrants and Emerging Players: Build out India industrial automation corridors around Pune and Chennai PLI scheme incentives, where embedded system assembly capacity remains underpenetrated relative to design-in activity. Target healthcare edge AI convergence for portable diagnostic equipment categories previously tethered to hospital infrastructure. Lead with CE marking harmonization tailwinds to reduce regional variant proliferation for European market entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive embedded computing divisions lacking standalone safety certification depth. Five-to-ten year viability hinges on algorithmic transparency documentation capabilities under EU AI Act conformity assessment obligations. Watch for ISO 26262 ASIL-D compliance timeline compression as inflection indicator for consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Safety Certification Bundling | Combines ISO 26262 ASIL-D with EU AI Act documentation to lock in German automotive design wins. |
| Foundry Partnership Diversification | Reduces Taiwan concentration risk through Samsung and Intel Foundry qualification for automotive nodes. |
| Firmware-as-a-Service Transition | Captures recurring revenue from Stuttgart OEM procurement teams unbundling hardware from software. |
| RISC-V Ecosystem Investment | Eliminates ARM licensing fees for cost-sensitive volume applications in smart home manufacturing. |
| India Assembly Capacity Expansion | Leverages PLI scheme incentives to serve underpenetrated industrial automation corridors. |
Research Approach
The analysis maps industrial computers, microcontrollers, single-board computers, and embedded processors, each validated through procurement directors at German automotive tier-1 suppliers, platform engineers at Japanese robotics manufacturers, and embedded software architects at Austin R&D facilities. Primary interview intelligence triangulates against SEC 10-K semiconductor disclosures, FCC Part 15 certification databases, and EU AI Act implementation guidance. Bottom-up unit economics for ARM, x86, and RISC-V designs reconcile with top-down market sizing across automotive, healthcare, and industrial automation verticals.
Assumptions hold Taiwan foundry capacity expansion within announced roadmaps and EU AI Act enforcement timelines within regulatory guidance. The forecast framework models product type, technology architecture, end-user vertical, and application density across the projection horizon. CAGRs derive from segment-level shipment trajectories and average selling price compression curves for microcontroller versus industrial computer form factors. Battery management system electrification capex and factory automation retrofit cycles inform automotive and industrial demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by RISC-V consortium members or China domestic semiconductor champions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America 3D Printing Construction Market
Others
Industrial Wearable Devices Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Industrial Hooters Market
Others
Mini Pcs Market
Others
Hardwood Market
Others
Smart Card Contactless Ticketing Market
Others
Canada Feed Additives Market
Others
Depth Gauge Market
Others
Automatic Barriers and Bollards Market
Others
Cat Dry Food Market
Others
Latin America Automotive HVAC Market
Others
Dry-Cleaning and Laundry Services Market
Others
Language Translation Device Market
Others
Aircraft Cameras Market
Others
Storage Dewar and Dry Shipper Market