
 Drum Motor Market | 2026-2036
Drum Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Motor Market Foresight
Capital-intensity divergence between in-house motor winding capabilities and outsourced assembly operations is bifurcating competitive tiers among drum motor suppliers. NORD Drivesystems leverages integrated manufacturing in Germany to control stator lamination quality and reduce lead times. Van der Graaf (VDG) anchors its position through North American service infrastructure and application engineering for bulk material conveyors. SEW-Eurodrive competes via modular platform architectures that span drum motors and conventional drive packages.
A drum motor is an enclosed electric motor whose rotor forms the shell of a cylindrical drum, with planetary or helical gearing transmitting torque to the drum surface at speeds typically ranging from 0.3 to 4.5 meters per second; this integration eliminates external drive chains, sprockets, and alignment maintenance in conveyor systems. AC drum motors dominate installed base across heavy-duty material handling due to mature supply chains and lower per-unit cost, while DC drum motors are gaining share in precision packaging lines where variable-speed control and regenerative braking improve throughput. The 1-5 HP power rating band captures the majority of margin pools because it spans the highest volume intersection of food processing and parcel sorting applications.
FDA sanitary equipment standards and EU Ecodesign Directive efficiency tiers shape product development priorities for drum motor manufacturers serving food processing and export markets. OSHA machine guarding requirements and REACH substance restrictions on insulation resins further constrain material selection and housing sealing architectures. Stakeholders must monitor how IEC efficiency class upgrades and emerging carbon border adjustments reshape sourcing decisions for laminated steel and copper windings.
Market Dynamics
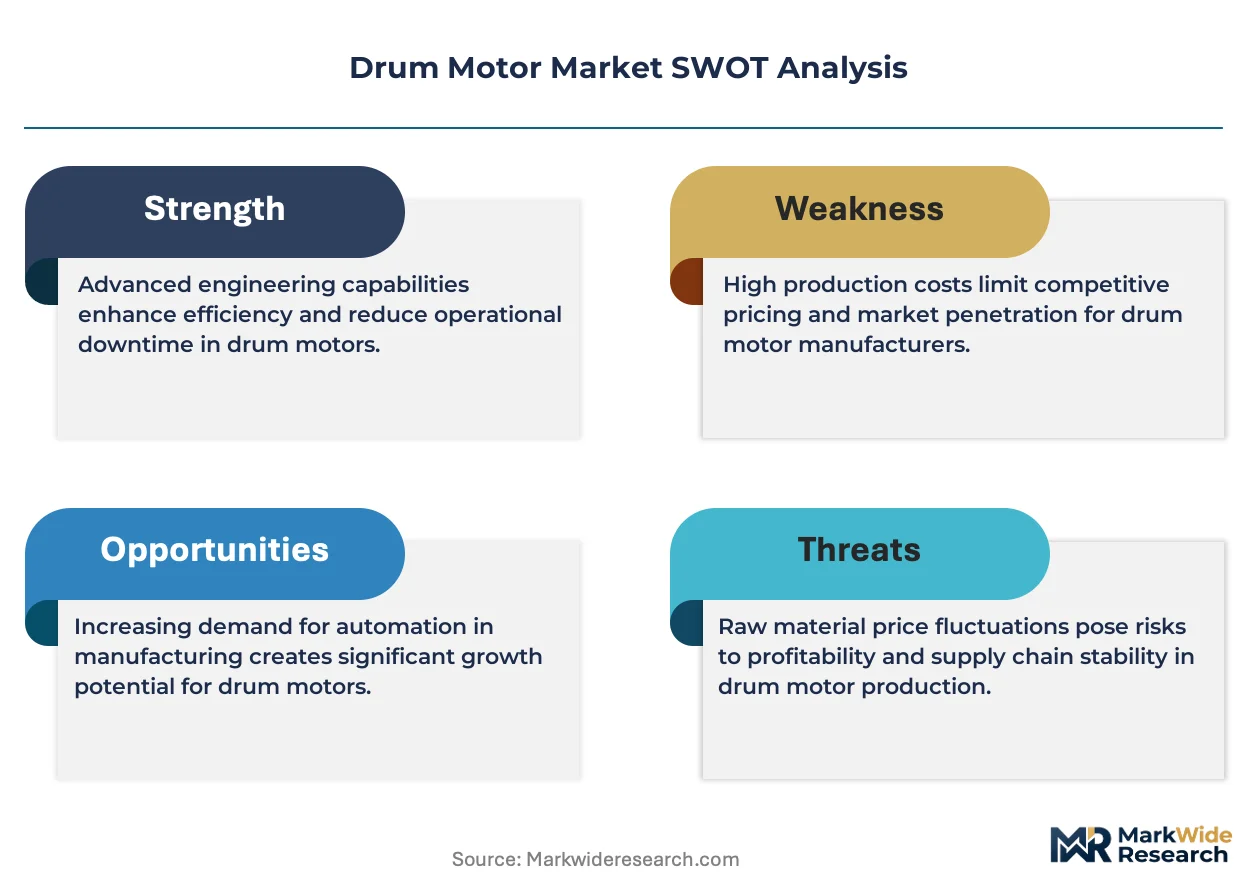
EU Ecodesign Directive efficiency tier upgrades are compressing margins for drum motor suppliers while simultaneously accelerating R&D investment in laminated steel grades and copper winding geometries. The regulatory pressure is restructuring competitive positioning between vertically integrated manufacturers and assembly-focused competitors.
Growth Catalysts
- EU Ecodesign Directive:Mandatory IE4 efficiency thresholds for motors above 0.75 kW are forcing replacement cycles in food processing and parcel handling facilities.
- Sealed stainless steel housings:FDA sanitary equipment standards are expanding specification requirements for washdown-capable drum motors in protein processing plants.
- German conveyor OEM cluster:Concentration of packaging machinery exporters around Stuttgart and Dortmund sustains localized demand pull for precision drive systems.
Market Restraints
- Copper price volatility:Winding material cost fluctuations compress margin predictability for mid-tier suppliers lacking long-term commodity hedging.
- Laminated steel supply concentration:Specialty electrical steel production concentrates in a limited number of European and Asian mills, creating input bottlenecks.
- Permanent magnet substitution threat:Rare-earth motor technologies are encroaching on efficiency-sensitive applications above 5 HP.
Strategic Opportunities
- Indian food processing expansion:FSSAI modernization and cold chain infrastructure buildout create specification windows for sealed drum motors in dairy and poultry handling.
- Regenerative braking integration:Convergence of DC drum motors with energy recovery systems opens precision packaging line retrofits.
- Direct OEM contracting:Bypassing traditional distributor channels allows margin capture in custom-engineered bulk material conveyor projects.
Industry Challenges
- IEC efficiency certification timelines:Extended testing protocols for IE4 and IE5 classifications delay product launches by 8-14 months.
- Legacy conveyor integration:Retrofitting drum motors into existing chain-drive architectures requires custom frame modifications and alignment engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Motor Market |
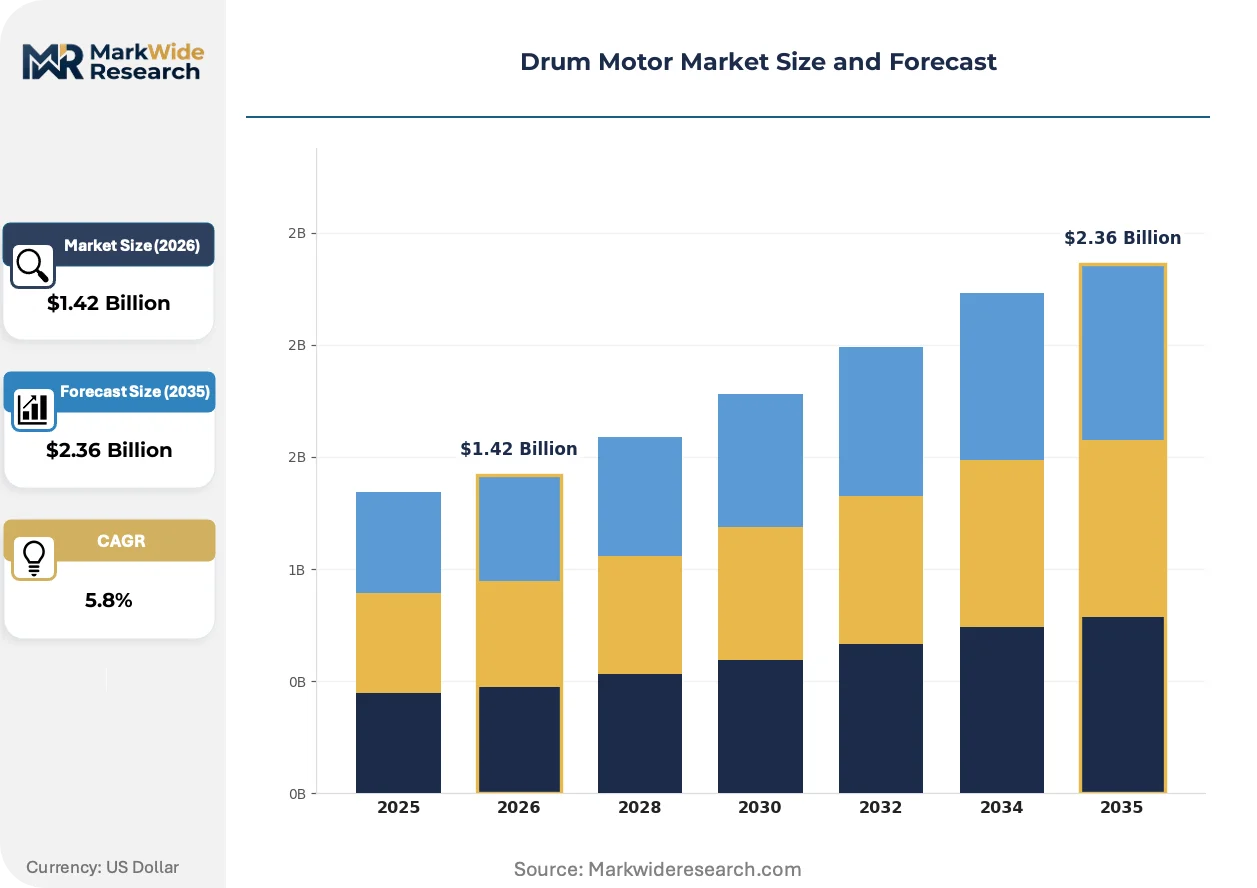
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drum Motors, DC Drum Motors, Gear Drum Motors, High Torque Drum Motors Application: Conveyor Systems, Industrial Automation, Packaging, Material Handling End User: Manufacturing, Food Processing, Mining, Agriculture Power Rating: Below 1 HP, 1-5 HP, 5-10 HP, Above 10 HP |
| Companies Covered | NORD Drivesystems, Flender, Van der Graaf (VDG), ABB, Lenze, SEW-Eurodrive, Sumitomo Heavy Industries, Conveyor Technology, Bonfiglioli Riduttori, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Motor Market Shifts & Advancements
Active magnet material substitution and digital torque monitoring are reshaping how drum motor suppliers differentiate performance tiers. The competitive frontier is shifting from pure mechanical reliability toward energy accountability and predictive maintenance integration.
Permanent magnet-assisted synchronous reluctance (PMASR) motor technology is bifurcating the efficiency-performance tradeoff in mid-power drum motors. Food processors in Northern Europe are specifying PMASR variants for conveyor lines above 2.2 kW to preempt Ecodesign tier escalations. The technology is bifurcating supplier tiers between those with in-house magnet handling capabilities and conventional induction motor assemblers.
REACH substance restrictions on insulation resins and potting compounds are constraining material selection for drum motor windings. Manufacturers serving EU export markets are reformulating encapsulation systems to eliminate restricted phthalates and brominated flame retardants. The regulatory pressure is most acute in washdown-rated motors where epoxy sealing integrity conflicts with substance compliance.
Buyer specification practices are consolidating around total cost of ownership models that weight energy consumption over acquisition price. Large parcel sorting operators in Germany and the Netherlands are unbundling after-sales service contracts from initial equipment procurement. This behavioral shift is compressing distributor margins while rewarding suppliers with direct service infrastructure.
Drum Motor Market Segmentation
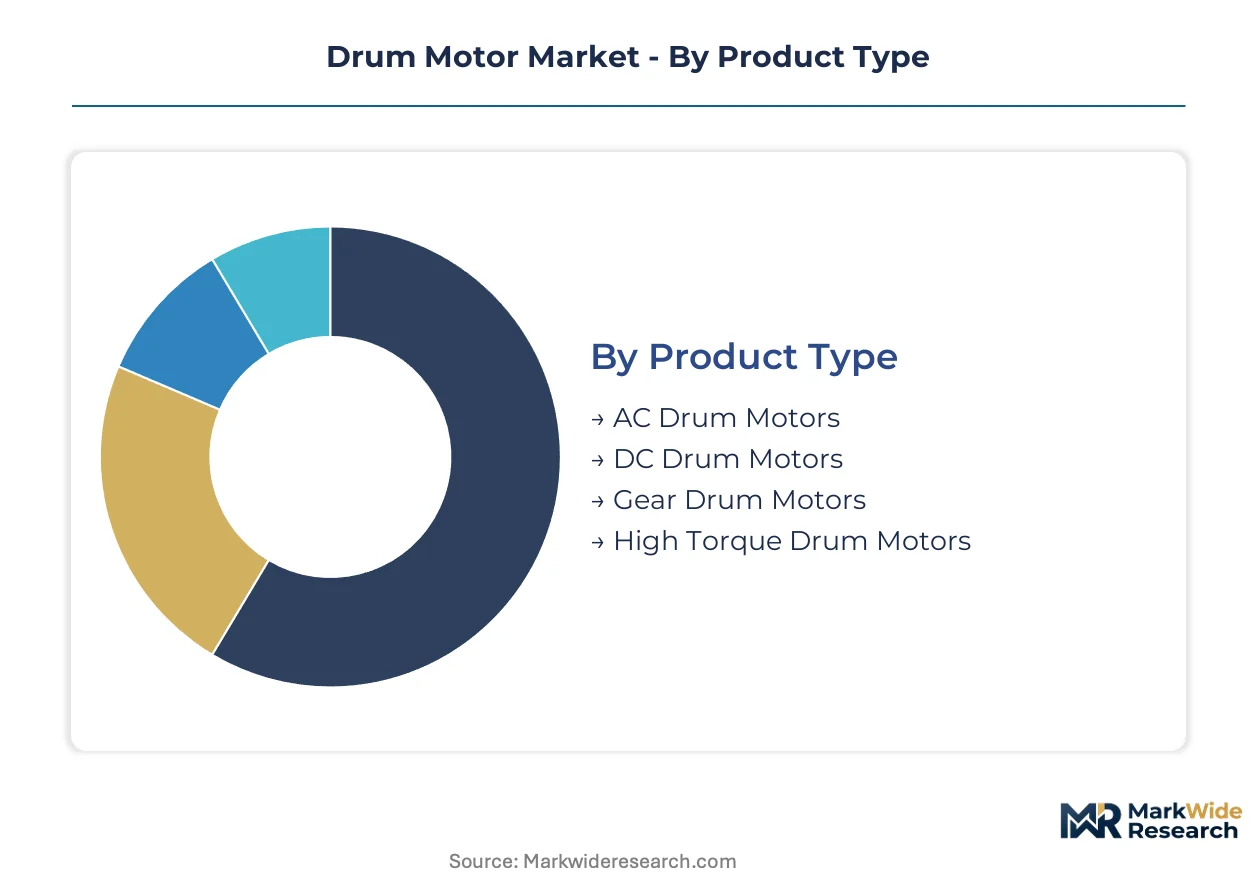
Drum motor procurement channels diverge sharply across power ratings and sanitary requirements. Specification engineers in food processing favor direct OEM contracting for sealed stainless units, while bulk material operators route standard AC models through industrial distributors.
Product Type:
Channel mix splits between specification-driven direct sales for precision DC variants and distributor-heavy flows for commodity AC units.
- AC Drum Motors:Induction motor architecture with squirrel-cage rotors integrated into steel drum housings dominates heavy-duty material handling installations. Demand concentrates in German bulk conveyor OEMs serving Ruhr Valley mining operations, constrained by Ecodesign IE4 efficiency deadlines forcing winding redesigns.
- DC Drum Motors:Permanent magnet or brushless DC configurations enable precise speed control through variable frequency drives. Precision packaging lines in Stuttgart's machinery cluster specify these for regenerative braking energy recovery, with direct contracting bypassing traditional distribution.
- Gear Drum Motors:Planetary or helical reduction stages integrated within the drum shell multiply torque output for low-speed high-force applications.
- High Torque Drum Motors:Specialized magnetic circuits and enlarged rotor diameters deliver sustained torque density for inclined conveyor installations.
By volume, AC Drum Motors leads. By growth pace, DC Drum Motors is ahead.
Application:
Cost tier stratification separates premium washdown-rated units for food contact from standard-duty models in dry material handling.
- Conveyor Systems:Belt, roller, and chain conveyor drives represent the core installation base for drum motor technology. Parcel sorting hubs in the Netherlands and cold storage facilities across Denmark specify sealed stainless variants to satisfy FDA and EFSA sanitary protocols simultaneously.
- Industrial Automation:Robotic feeding lines and automated assembly stations demand compact drive solutions with minimal maintenance intervals. German automotive component plants near Wolfsburg anchor demand for integrated motor-gearbox units with predictive maintenance connectivity.
- Packaging:Form-fill-seal machinery and case packing equipment require precise speed synchronization across multiple drive points.
- Material Handling:Bulk solids transport in mining and aggregate processing prioritizes mechanical durability over energy efficiency.
Conveyor Systems commands the largest installed base. Packaging applications are climbing the fastest as precision requirements intensify.
End User:
Customer type determines specification authority, with food safety officers overriding procurement cost targets in protein processing environments.
- Manufacturing:General industrial production facilities deploy drum motors across assembly lines and finishing operations. Automotive tier suppliers in Baden-Württemberg favor modular platforms compatible with SEW-Eurodrive and NORD Drivesystems ecosystems, consolidating spare parts inventories.
- Food Processing:Dairy, meat, and ready-meal facilities mandate washdown-capable sealed housings with smooth surfaces eliminating bacterial harborage. FSSAI modernization in India is opening specification windows for EU-certified drum motor suppliers in Bangalore and Pune dairy handling operations.
- Mining:Underground and surface extraction operations require explosion-protected variants for hazardous atmosphere compliance.
- Agriculture:Grain handling, feed processing, and livestock equipment applications favor cost-optimized standard-duty configurations.
Manufacturing holds the deepest penetration. Food Processing is gaining share fastest as sanitary regulations tighten across export markets.
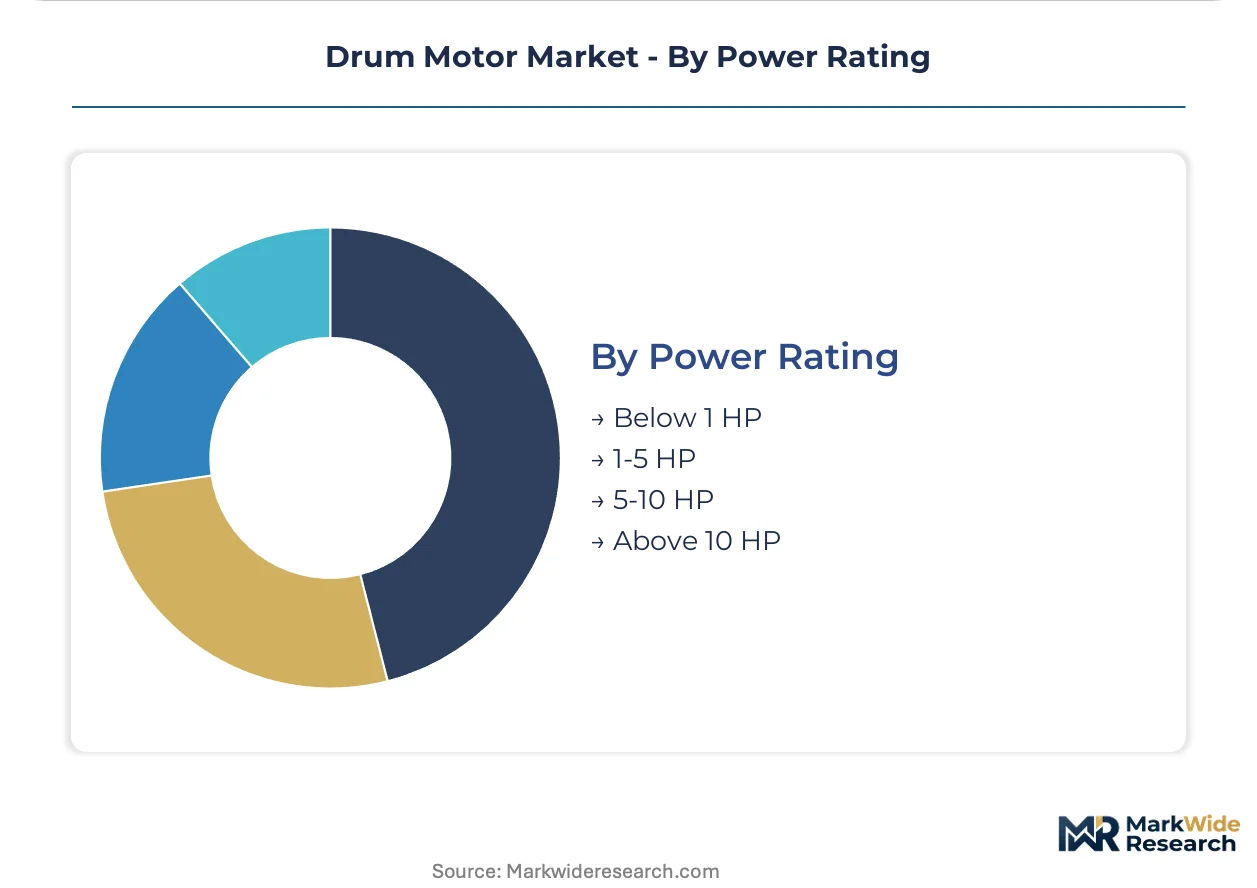
Power Rating:
Margin concentration aligns with volume scale in the mid-power band where food processing and parcel sorting specifications overlap.
- 1-5 HP:The intersection of food processing conveyors and parcel sorting systems creates sustained specification demand. This band captures premium pricing for stainless washdown units while supporting sufficient production scale for laminated steel sourcing leverage.
- Below 1 HP:Light-duty packaging machinery and small conveyor modules drive demand for compact drum motor configurations. Pharmaceutical cleanroom applications in Switzerland specify these for tablet handling lines with ISO 14644 particulate compliance.
- 5-10 HP:Heavy bulk material conveyors and industrial automation lines require enhanced thermal management and bearing capacity.
- Above 10 HP:Mining crushers, long-distance overland conveyors, and heavy process equipment push drum motor architecture toward custom-engineered solutions.
1-5 HP dominates revenue contribution. Below 1 HP shows the steepest expansion trajectory as precision packaging miniaturizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, prioritizing acquisition cost over lifecycle efficiency. German and Dutch parcel operators weight total cost of ownership models heavily, accepting 40-60% upfront premiums for IE4-rated units. This elasticity divergence fragments supplier pricing power across geographies.
Germany
Stuttgart's packaging machinery cluster and Dortmund's conveyor OEM concentration generate sustained specification demand for precision drum motors. The EU Ecodesign Directive's IE4 efficiency thresholds force replacement cycles across Ruhr Valley bulk handling facilities. NORD Drivesystems and SEW-Eurodrive anchor vertically integrated supply positions in Lower Saxony and Baden-Württemberg.
United States
FDA sanitary equipment standards drive washdown-rated drum motor specifications in protein processing plants across the Midwest. OSHA machine guarding requirements constrain housing sealing architectures for food contact applications. Van der Graaf maintains North American service infrastructure density around Chicago and Atlanta distribution corridors.
India
FSSAI modernization and cold chain infrastructure buildout create specification windows for sealed drum motors in Bangalore and Pune dairy operations. The Bureau of Indian Standards enforces efficiency labeling for motors above 0.75 kW, compressing margins for non-compliant imports. Domestic food processors prioritize stainless washdown units for export-oriented poultry handling lines.
Netherlands
Parcel sorting hubs in Rotterdam and Eindhoven unbundle after-sales service contracts from initial equipment procurement. The EU Green Deal's carbon border adjustment mechanisms reshape sourcing decisions for laminated steel windings. Dutch distribution operators specify regenerative braking integration for precision packaging line retrofits.
China
MIIT efficiency standards and dual carbon goals accelerate permanent magnet motor substitution in mid-power applications above 5 HP. Yangtze River Delta conveyor manufacturers consolidate procurement around domestic drum motor suppliers with captive electrical steel capacity. Zhengzhou-based fabricators compete on cost-optimized standard-duty configurations for bulk material handling.
Drum Motor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling stator lamination quality and the latter competing on application engineering proximity. The market structure bifurcates between German-origin conglomerates with captive motor winding facilities and regional assemblers dependent on outsourced laminated steel supply. Strategic archetypes include vertically integrated platform suppliers, North American service-heavy specialists, and Asia-Pacific cost-optimized fabricators. Dominant competitive moves center on backward integration into electrical steel sourcing and direct OEM contracting to bypass distributor margin capture.
Among German-origin integrated manufacturers, NORD Drivesystems and SEW-Eurodrive exemplify the platform-architecture archetype spanning drum motors and conventional drive packages. Van der Graaf occupies a position within the service-intensive specialist tier, anchoring competitive differentiation through North American application engineering density rather than manufacturing scale. These three represent the dominant competitive anchors against which mid-tier suppliers benchmark vertical integration depth and geographic coverage.
| Leading Market Players |
|---|
| NORD Drivesystems |
| Flender |
| Van der Graaf (VDG) |
| ABB |
| Lenze |
| SEW-Eurodrive |
| Sumitomo Heavy Industries |
| Conveyor Technology |
| Bonfiglioli Riduttori |
| Others |
Supply & Pricing Matrix
EU Ecodesign IE4 efficiency thresholds gate both supplier qualification and price differentiation, compressing margins for assembly-dependent competitors while rewarding vertically integrated manufacturers with laminated steel sourcing leverage and certification-ready product architectures.
Pricing Analysis
After-sales service contracts and spare parts revenue drive lifetime value capture, with German parcel operators unbundling maintenance agreements from initial procurement. Pricing stratifies across IE4-certified premium tiers, stainless washdown configurations for FDA compliance, and standard-duty economy units. Cost compression in mid-power AC segments intensifies as copper price volatility erodes hedging capacity among smaller suppliers. Food processors in Northern Europe exhibit lowest price sensitivity, prioritizing sanitation certification over acquisition cost, while Indian dairy operators weight upfront expenditure heavily.
Supply Chain Analysis
Inventory buffers for laminated electrical steel and copper windings have tightened, extending quoted lead times for non-integrated suppliers. Production concentrates in Germany, China, and Japan, with specialty steel mills in the Ruhr Valley and Yangtze River Delta anchoring rotor lamination supply. The chain draws from concentrated electrical steel foundries, rare-earth magnet processors, and epoxy resin formulators. Single-source vulnerability in high-grade silicon steel creates exposure to export licensing shifts. Distribution runs through conveyor OEM direct contracts in Germany and industrial distributors in North American bulk material markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor substitution above 5 HP threatens drum motor incumbents, forcing defensive positioning around efficiency-tier preemption and service infrastructure density.
For Market Incumbents: Secure captive supply of laminated electrical steel through mill partnerships or in-house lamination stamping to insulate against IE4 certification delays. Deepen application engineering presence in Indian food processing corridors before FSSAI modernization closes specification windows to late entrants. For New Entrants and Emerging Players: Predictive maintenance connectivity gaps in legacy conveyor installations offer white-space entry, with German automotive component plants near Wolfsburg showing acute under-penetration. Target precision packaging retrofits in the Netherlands with DC drum motor regenerative braking bundles, bypassing distributor channels through direct OEM contracting. For Investors and Strategic Acquirers: EU Ecodesign Directive tier escalations reshape the acquisition landscape toward suppliers with in-house magnet handling and PMASR motor capabilities. Five-to-ten year viability hinges on backward integration depth rather than assembly scale. Watch IEC efficiency certification backlog durations as the signal for margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Captive lamination supply insulates NORD and SEW-Eurodrive from specialty steel bottlenecks. |
| PMASR Technology Platform Development | Magnet-assisted synchronous reluctance architectures preempt Ecodesign IE5 tier requirements. |
| Direct OEM Contracting Expansion | Bypassing distributor channels captures margin in custom-engineered bulk conveyor projects. |
| Regenerative Braking Integration | DC drum motor energy recovery opens precision packaging line retrofit specifications. |
| Indian Service Infrastructure Buildout | FSSAI modernization in Bangalore and Pune creates specification windows for sealed stainless units. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with conveyor OEM procurement teams, food processing plant engineers, aftermarket service directors, and bulk material handling operators; and secondary validation against IEC efficiency certification databases, EU Ecodesign Directive implementation records, customs trade flows for electrical steel and copper windings, and Bureau of Indian Standards motor labeling registries. Bottom-up unit economics triangulated against top-down market sizing across power rating bands and application segments.
Across the projection horizon, the analytical framework modeled segmentation by motor architecture, power rating tier, sanitary specification level, end-use industry, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, efficiency regulation phase-in schedules, and food processing capacity expansion pipelines. Forecast inputs incorporated laminated steel price indices, rare-earth magnet supply constraints, and cold chain infrastructure investment trajectories in emerging markets.
Material uncertainties — commodity price volatility, regulatory timeline slippage, permanent magnet substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about efficiency tier adoption curves and OEM specification behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wingboards Market
Others
Durian Market
Others
Animal Feed Alternative Protein Market
Others
Solar Animal Repeller Market
Others
Interference Mitigation Filters Market
Others
Italy Feed Additives Market
Others
Europe Flow Battery Market
Others
Printing Machines Market
Others
Surface Green Mining Market
Others
Binoculars Market
Others
South America Automotive LED Lighting Market
Others
Global Digital Market
Others
Flexographic Printing Plate Market
Others
Chip Card Scanners Market
Others
Edible Insects for Animal Feed Market
Others
Global Emergency Spill Response Market