
 Palatants Market | 2026-2036
Palatants Market Size, Share, and Industry Trends Forecast 2026-2036
Palatants Market Outlook
Market Context
The divergence between premium and commodity palatant tiers is hardening around clean-label certification and species-specific formulation depth. Kemin Industries leverages its vertical integration into natural extract supply chains to sustain margin capture at the premium end. AFB International competes through dedicated R&D facilities for canine and feline taste receptor mapping. Kerry Group anchors its position via broad formulation partnerships with multinational pet food manufacturers.
Technical Definition and Structural Segments
Palatants are sensory-active feed and food additives—typically comprising hydrolyzed proteins, yeast extracts, amino acids, and nucleotides—engineered to enhance aroma, taste, and post-ingestion acceptance in target species. Their primary commercial purpose centers on improving feed conversion ratios in livestock operations and driving preference-based purchasing in companion animal diets. Amino acid-based palatants occupy the deepest margin pools due to precision dosing requirements and technical barriers in Maillard reaction control. Powder formulations lead volume throughput for dry pet food integration, while liquid palatants are displacing legacy spray-dried systems in wet food and fresh-refrigerated segments.
Regulatory Frame and Outlook
The FDA Center for Veterinary Medicine and the European Food Safety Authority enforce divergent safety assessment protocols for novel palatant substrates, with EFSA demanding extended toxico-kinetic studies that extend approval timelines. China's National Feed Industry Standardization Technical Committee is accelerating GB standard revisions for pet food flavor additives, tightening import compliance for foreign suppliers. Feed producers and palatant developers must monitor regulatory asymmetries between jurisdictions to anticipate reformulation costs and market access barriers.
Market Dynamics
Clean-label certification requirements are bifurcating procurement patterns across the palatants value chain, forcing manufacturers to rebuild formulation pipelines around natural extract substrates while maintaining cost parity with conventional hydrolyzed protein systems.
Growth Catalysts
- EU Feed Additives Regulation:The tightening approval pathway for novel flavor enhancers is accelerating R&D investment in documented natural alternatives, creating first-mover advantages for compliant suppliers.
- Canine and feline taste receptor mapping:Precision understanding of species-specific sensory biology enables differentiated product architectures that command formulation partnerships with premium pet food manufacturers.
- China's domestic pet food production scaling:Local brands are expanding high-appeal product lines, concentrating import demand for foreign palatant technologies that satisfy GB standard revisions.
Market Restraints
- Animal protein input volatility:Hydrolyzed poultry and fish protein costs fluctuate with livestock feed grain prices, compressing margin stability for mid-tier formulation suppliers.
- Extended EFSA toxico-kinetic requirements:The European Food Safety Authority mandates multi-year safety studies for novel substrates, extending approval timelines beyond typical product development cycles.
- Liquid palatant substitution threat:Wet food and fresh-refrigerated segments are displacing legacy spray-dried powder systems, stranding capital in conventional drying infrastructure.
Strategic Opportunities
- India's underpenetrated companion animal nutrition sector:Rising pet ownership in metropolitan centers creates whitespace for palatant introduction ahead of domestic manufacturing scale-up.
- Amino acid precision dosing technology:Convergence of enzymatic hydrolysis with chromatographic purification enables Maillard reaction control at commercial scale, unlocking premium margin pools.
- China GB standard acceleration:The National Feed Industry Standardization Technical Committee's revision timeline creates regulatory tailwinds for early-compliant foreign suppliers to secure import clearance advantages.
Industry Challenges
- Maillard reaction chemist scarcity:Formulation expertise in controlled thermal processing of amino acid-nucleotide systems concentrates in legacy European and North American R&D clusters, constraining talent mobility.
- Dual certification timeline compression:Simultaneous FDA Center for Veterinary Medicine and EFSA approval pathways require parallel toxicology study design, multiplying upfront capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palatants Market |
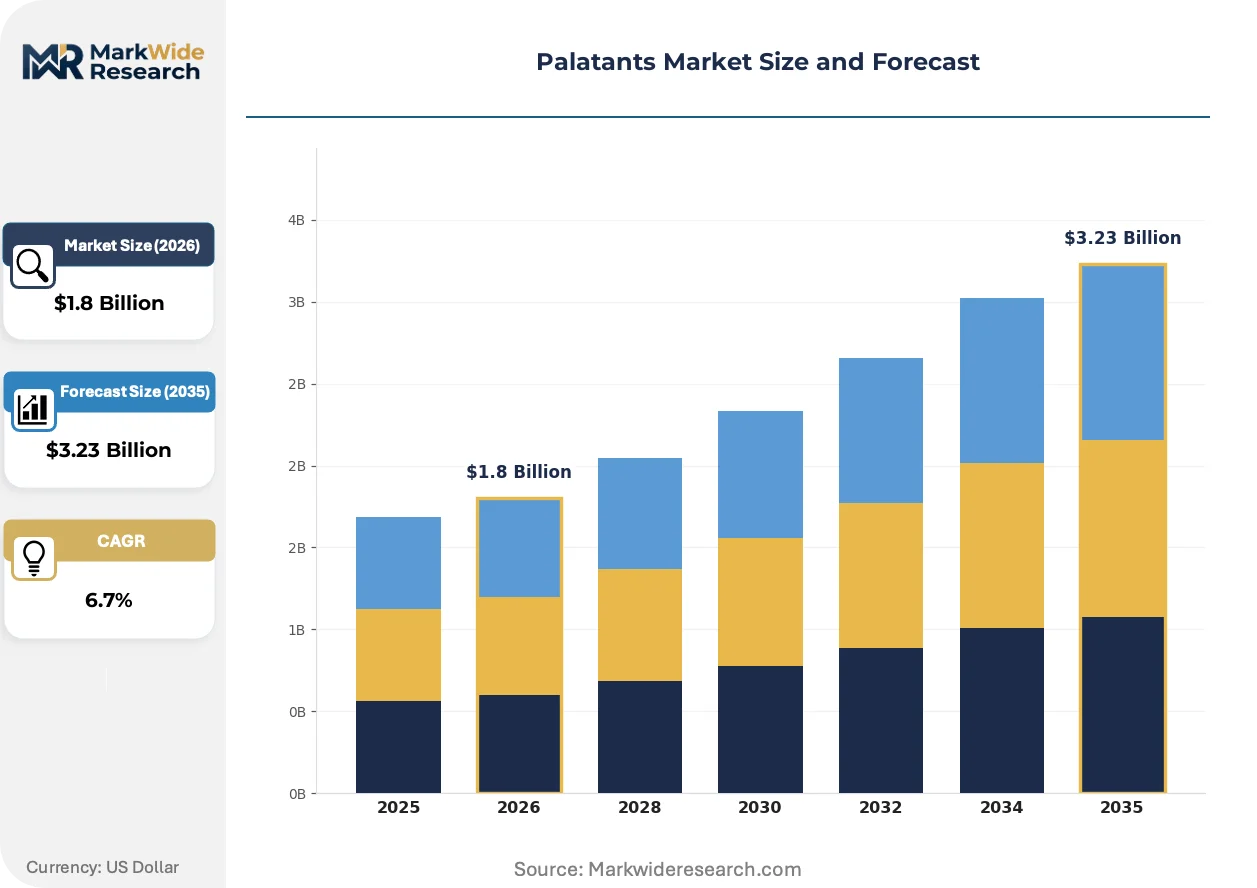
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Sweeteners, Flavor Enhancers, Acidulants Application: Pet Food, Dairy Products, Infant Nutrition, Nutraceuticals Formulation Type: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Feed Producers, Retailers, Online Sellers |
| Companies Covered | Kemin Industries, AFB International, Kerry Group, Alltech Inc, Diana Group, ADM, Nestle SA, Pancosma SA, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palatants Market Strategic Shifts
Formulation science is pivoting toward species-specific sensory architectures that replace generic palatant platforms with precision-engineered receptor-targeting systems, compressing development-to-commercialization cycles across the value chain.
Enzymatic hydrolysis technology is decentralizing protein substrate processing by enabling on-site generation of bioactive peptide fractions at smaller production scales. Regional pet food manufacturers in Brazil and Southeast Asia are adopting modular enzymatic units to reduce dependence on imported concentrate intermediates. This distributed processing architecture is compressing logistics costs and enabling faster formulation iteration cycles for local taste preferences.
REACH registration requirements for novel protein hydrolysates are extending compliance timelines for European market entry, forcing developers to front-load toxicological documentation. The industrial consequence is a shift toward pre-validated natural extract portfolios that bypass novel substance classification. Wet food specialists targeting EU distribution channels are prioritizing yeast-derived and plant-protein palatants over unregistered animal hydrolysates to maintain supply continuity.
Direct formulation partnerships between palatant developers and multinational pet food manufacturers are displacing traditional ingredient distributor intermediaries. Major buyers are consolidating supplier rosters to capture technical collaboration benefits and lock in capacity allocation. This channel restructuring is most visible in North American and Western European markets where premium dry food and fresh-refrigerated segments concentrate procurement authority among three to four integrated manufacturers.
Palatants Market Segmentation
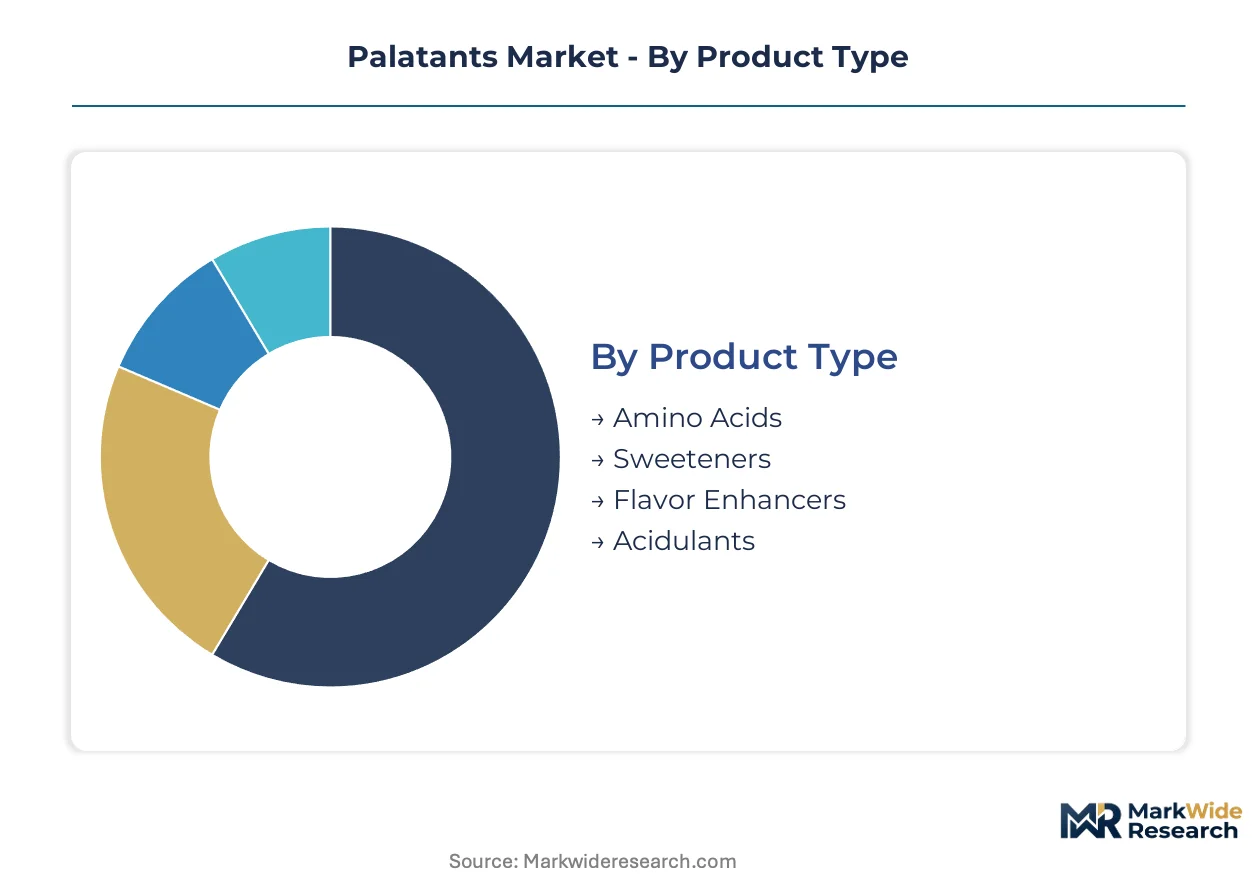
Palatant procurement patterns diverge sharply across end-use applications, with formulation complexity and regulatory compliance requirements driving supplier selection criteria. Understanding segment-level dynamics reveals where margin pools concentrate and which technical capabilities command premium positioning.
Product Type:
Buyer decisions here pivot on precision dosing requirements and Maillard reaction control sophistication, with premium formulations demanding documented efficacy data.
- Amino Acids:These comprise enzymatically processed protein substrates including taurine, lysine, and methionine derivatives engineered for species-specific receptor binding. Demand concentrates in premium canine and feline nutrition products manufactured in the United States and Germany, where clean-label certification requirements favor documented natural sourcing chains. FDA Center for Veterinary Medicine and EFSA documentation standards create compliance barriers that protect incumbent suppliers.
- Flavor Enhancers:Nucleotide-based systems (IMP, GMP) and yeast extract derivatives amplify umami perception across target species. Wet food specialists in China and fresh-refrigerated producers in France drive procurement volume as these segments displace legacy spray-dried systems. GB standard revisions in China accelerate import demand for documented foreign technologies.
- Sweeteners:Glycine, threonine, and natural extract systems modulate preference in specific companion animal formulations.
- Acidulants:Citric, phosphoric, and malic acid derivatives adjust palatability profiles in poultry and swine feed applications.
Volume sits with Flavor Enhancers; growth tilts toward Amino Acids.
Application:
End-use concentration determines formulation investment intensity, with companion animal segments commanding technical collaboration and livestock applications prioritizing cost-efficient feed conversion.
- Pet Food:Canine and feline dry, wet, and fresh-refrigerated products represent the dominant revenue concentration, with palatants driving preference-based purchasing decisions at retail. Multinational manufacturers in the United States and Western Europe consolidate supplier rosters to capture technical partnership benefits. Species-specific taste receptor mapping enables differentiated product architectures that lock in formulation relationships.
- Dairy Products:Calf milk replacers and transition feeds utilize palatants to drive intake consistency during weaning protocols. European and North American dairy operations emphasize documented safety profiles aligned with EFSA and FDA protocols.
- Infant Nutrition:Human-grade palatant systems face stringent purity requirements that limit supplier participation to pharmaceutical-grade manufacturers.
- Nutraceuticals:Functional treat and supplement applications in companion animals represent an emerging specification tier with concentrated growth in metropolitan markets.
Revenue concentrates in Pet Food; Nutraceuticals expand most quickly as functional treat segments mature.
Formulation Type:
Physical state selection tracks integration technology at the customer facility, with capital equipment decisions creating path dependencies that shape procurement continuity.
- Powder:Spray-dried and agglomerated systems dominate dry pet food volume throughput, with established coating and extrusion integration protocols across major manufacturing facilities. Legacy infrastructure investments in the United States and Brazil sustain procurement patterns despite liquid substitution pressure in adjacent segments.
- Liquid:Pumpable concentrates enable precise dosing in wet food slurries and fresh-refrigerated emulsions, displacing reconstituted powder systems. European wet food specialists and Chinese domestic brands drive adoption as equipment refresh cycles enable processing upgrades.
- Granular:Free-flowing agglomerates reduce dusting and improve handling characteristics in large-scale feed mill operations.
- Paste:High-viscosity systems serve niche fresh and raw pet food applications with limited scale but premium positioning.
Installed base favors Powder; Liquid gains share fastest as wet food segments expand.
End User:
Channel structure determines technical service intensity and contract terms, with direct relationships displacing distributor intermediaries in concentrated buyer segments.
- Food Manufacturers:Multinational pet food producers in the United States, Germany, and Thailand consolidate procurement authority and demand formulation partnership capabilities. Direct technical collaboration agreements lock in capacity allocation and co-development pipelines.
- Feed Producers:Livestock and aquaculture compounders prioritize cost efficiency and feed conversion ratio documentation over sensory precision. Brazilian and Southeast Asian operations adopt modular enzymatic processing to reduce import dependence.
- Retailers:Private-label pet food programs create specification demand for compliant palatant systems with documented supply chain transparency.
- Online Sellers:Direct-to-consumer fresh and raw pet food startups represent fragmented demand with high formulation customization requirements.
Procurement volume centers on Food Manufacturers; Online Sellers show steepest expansion trajectory as subscription fresh food models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
St. Louis anchors North American palatant innovation through concentrated R&D infrastructure and proximity to major pet food manufacturing clusters. The market distributes across four demand centers with distinct regulatory and supply chain characteristics.
United States
Premium pet food manufacturers in Missouri and Kansas expand palatant procurement for clean-label formulations, driving specification intensity. FDA Center for Veterinary Medicine maintains divergent safety assessment protocols from European counterparts, creating compliance complexity for multinational suppliers. The Midwest corridor between St. Louis and Kansas City concentrates formulation partnerships with three integrated manufacturers.
Germany
EFSA mandates extended toxico-kinetic studies for novel substrates, extending approval timelines beyond typical product development cycles. The country's feed additive sector concentrates in Lower Saxony and Bavaria, where dairy operations emphasize documented safety profiles. Munich-based technical service providers coordinate pan-European distribution for compliant natural extract portfolios.
China
Domestic pet food brands in Shanghai and Guangdong scale production of high-appeal products, concentrating import demand for foreign palatant technologies. GB standard revisions from the National Feed Industry Standardization Technical Committee tighten import compliance requirements. The Yangtze River Delta hosts the fastest-expanding enzymatic processing capacity for local taste preference iteration.
Brazil
Regional pet food manufacturers adopt modular enzymatic units to reduce dependence on imported concentrate intermediates. ANVISA oversight of feed additives remains less stringent than FDA or EFSA pathways, enabling faster formulation experimentation. São Paulo state anchors distributed processing architecture that compresses logistics costs for South American markets.
France
Wet food specialists in Brittany and the Loire Valley prioritize yeast-derived and plant-protein palatants over unregistered animal hydrolysates to maintain EU supply continuity. REACH registration requirements for novel protein hydrolysates extend compliance timelines, forcing developers toward pre-validated natural extract portfolios. Nantes hosts the largest concentration of fresh-refrigerated pet food innovation in continental Europe.
Palatants Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and species-specific receptor mapping capabilities. The vendor base concentrates among integrated multinationals with captive R&D infrastructure and regional specialists with modular processing advantages. Three archetypes dominate: vertically integrated natural extract suppliers, precision-dosing technology developers, and distributed enzymatic processors. Competitive dynamics center on direct formulation partnerships displacing distributor intermediaries, and capacity allocation agreements locking in multinational procurement relationships.
Within the integrated multinational tier, Kemin Industries, Kerry Group, and AFB International exemplify divergent strategic positioning. Kemin Industries represents backward integration into natural extract supply chains for premium-margin capture. Kerry Group anchors broad formulation partnerships across multinational pet food manufacturers. AFB International occupies the species-specific sensory biology specialization vector with dedicated canine and feline taste receptor mapping infrastructure.
| Leading Market Players |
|---|
| Kemin Industries |
| AFB International |
| Kerry Group |
| Alltech Inc |
| Diana Group |
| ADM |
| Nestle SA |
| Pancosma SA |
| Symrise AG |
| Others |
Value Chain & Pricing Dynamics
Hydrolyzed poultry protein commodity indices cascade through palatant manufacturing tiers, compressing margins at the standard-grade level while amplifying premium capture for amino acid-based formulations with documented natural sourcing chains. Input cost volatility from livestock feed grain markets feeds directly into procurement negotiations between multinational pet food manufacturers and formulation suppliers.
Pricing Analysis
Feed conversion ratio outcomes anchor value-based pricing contracts in livestock applications, while companion animal segments command premiums through species-specific receptor efficacy documentation. Three-tier pricing structure across premium, standard, and economy levels separates clean-label certified amino acid systems from conventional hydrolyzed proteins and commodity yeast extracts. Cost compression in mid-tier hydrolyzed protein formulations is intensifying because of animal protein input volatility and substitute liquid palatant displacement. Livestock feed producers exhibit highest price sensitivity; premium pet food manufacturers demonstrate lowest sensitivity due to formulation partnership lock-in.
Supply Chain Analysis
Ocean freight rate fluctuations between Southeast Asian enzymatic processing hubs and European wet food manufacturing clusters directly impact landed cost structures for concentrate intermediates. Supply concentrates in China, the United States, and Germany, with enzymatic hydrolysis capacity expanding fastest in the Yangtze River Delta and São Paulo state. Raw material dependencies rest on poultry by-product meal, fish protein hydrolysates, and brewer's yeast derivatives. Single-source vulnerability concentrates in Maillard reaction chemist expertise clustered in legacy European and North American R&D facilities. Distribution runs through direct formulation partnerships displacing traditional ingredient distributor intermediaries in concentrated buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maillard reaction chemist scarcity props pricing for precision-dosing amino acid formulations, constraining supply expansion and sustaining margin pools for qualified suppliers across the analysis window.
For Market Incumbents: Extend captive R&D infrastructure into species-specific taste receptor mapping to defend against liquid palatant substitution in wet food segments. Secure capacity allocation agreements with multinational pet food manufacturers in the United States and Germany before equipment refresh cycles enable processing upgrades. Certification investment in EFSA-compliant natural extract portfolios addresses REACH registration timeline risks for European market continuity. For New Entrants and Emerging Players: GB standard revisions in China open a window for early-compliant foreign suppliers to secure import clearance advantages ahead of domestic enzymatic processing scale-up. India's underpenetrated companion animal nutrition sector in metropolitan centers offers whitespace for palatant introduction before local manufacturing matures. Modular enzymatic processing units serve as the most penetrable go-to-market angle for regional pet food manufacturers in Brazil and Southeast Asia seeking import independence. For Investors and Strategic Acquirers: The window for entry favors precision-dosing technology developers with chromatographic purification capabilities and documented species-specific efficacy data. Long-term viability centers on suppliers capable of bridging clean-label certification requirements with cost parity against conventional hydrolyzed protein systems. Watch enzymatic hydrolysis equipment deployment rates in China's Yangtze River Delta as the inflection indicator for local taste preference iteration speed and import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extract Supply Chains | Kemin Industries demonstrates margin capture through captive sourcing of documented clean-label substrates. |
| Species-Specific Taste Receptor Mapping Infrastructure | AFB International locks in formulation partnerships with premium pet food manufacturers through dedicated canine and feline R&D facilities. |
| Modular Enzymatic Processing Unit Deployment | Brazilian and Southeast Asian regional manufacturers reduce concentrate import dependence through distributed on-site peptide generation. |
| Direct Formulation Partnership Agreements | Multinational pet food producers in North America and Western Europe consolidate supplier rosters to capture technical collaboration benefits. |
| EFSA-Compliant Natural Extract Portfolio Pre-Validation | Wet food specialists in France maintain EU supply continuity by prioritizing yeast-derived and plant-protein systems over unregistered animal hydrolysates. |
Study Parameters
Multi-period observation of palatant procurement volumes, regulatory submission timelines, and enzymatic processing capacity expansions anchored the trend analysis, supplemented by interviews with formulation scientists at multinational pet food manufacturers, regulatory affairs specialists navigating FDA Center for Veterinary Medicine and EFSA pathways, procurement directors at integrated feed compounders, and technical service leads at palatant developers. Secondary validation drew from FDA CVM submission databases, EFSA scientific opinions on feed additives, Chinese GB standard revision notices, customs trade data on protein hydrolysate imports, and SEC filings of publicly traded pet food and ingredient companies. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association reports.
Input-output matrices mapped amino acid-based, flavor enhancer, sweetener, and acidulant product flows across powder, liquid, granular, and paste formulation types to end-use applications in pet food, dairy, infant nutrition, and nutraceuticals. Segmentation dimensions included product type precision requirements, application formulation intensity, physical state integration technology, and end-user channel structure. CAGRs were derived from regression analysis of historical procurement patterns projected against capacity expansion announcements and regulatory approval pipeline visibility. Industry-specific forecast inputs incorporated Maillard reaction control technology adoption curves and species-specific sensory biology research investment trajectories.
The model assumes a particular technology adoption path; alternative pathways for liquid palatant displacement of spray-dried powder systems would alter the outlook for capital recovery timelines in legacy drying infrastructure. Forecasts reflect documented assumptions about EFSA approval timeline compression, GB standard enforcement intensity, and enzymatic hydrolysis modular unit cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Retina Services Market
Others
Digital Thermal Plates Market
Others
Global Multi Domain Controller Market
Others
Pin Mills Market
Others
South Korea Intellectual Property Market
Others
Rotary Evaporators Market
Others
South Korea Automotive LED Lighting Market
Others
Global on-Demand Laundry Service Market
Others
Digital Education Projector Market
Others
Pollen Allergy Market
Others
Canada Feed Additives Market
Others
Asia-Pacific B2B Legal Services Market
Others
Fiberglass Storage Tanks Market
Others
Safety Instrumented System (SIS) Market
Others
Allogeneic Human Chondrocyte Market
Others
Japan Indoor LBS Market