
 Server Market | 2026-2036
Server Market Size, Share, and Industry Trends Forecast 2026-2036
Server Market Intelligence
Datacenter engineering talent is collapsing across multiple regions, constraining deployment timelines for large-scale facilities. Dell Technologies leverages its direct sales force and custom configuration capabilities to sustain enterprise relationships despite lengthening delivery cycles. Hewlett Packard Enterprise competes through its GreenLake as-a-service platform, which shifts capital expenditure to operational models and reduces customer dependency on scarce internal infrastructure teams. Foxconn dominates ODM server manufacturing, occupying a critical position in the supply chain for hyperscale brands that lack captive production.
A server is a networked computing device engineered with multi-core processors, ECC memory modules, redundant power supplies, and PCIe expansion slots to process, store, and distribute data across client endpoints and cloud workloads. Rack servers, the dominant product type, lead volume shipments due to standardized form factors that maximize power density within hyperscale facilities. Blade servers represent the fastest-growing product category as enterprises consolidate legacy tower footprints into chassis-based architectures that reduce cabling complexity and improve thermal management at scale.
The EPA ENERGY STAR program and the EU Ecodesign Directive enforce minimum efficiency thresholds that disqualify legacy server generations from public sector procurement in the United States and Europe. The NIST Cybersecurity Framework and ISO 27001 standards further constrain market access for vendors lacking certified supply chain traceability and firmware integrity controls. Stakeholders must monitor how sovereign AI infrastructure programs and export licensing regimes for advanced accelerators reshape competitive access across priority deployment zones.
Market Dynamics
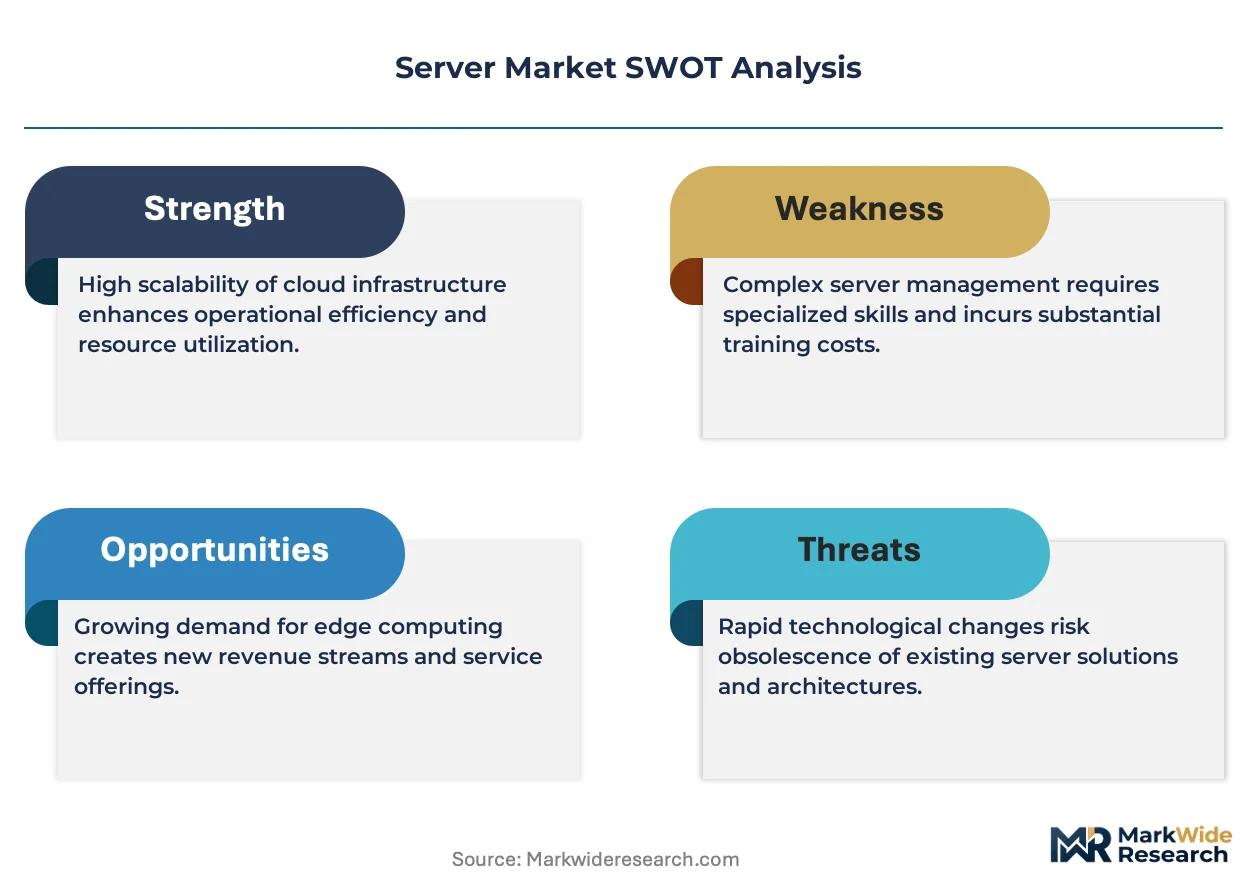
Hyperscale cloud operators are consolidating procurement power while liquid cooling architectures displace legacy air-cooled designs under tightening EU energy efficiency mandates.
Growth Catalysts
- AI Training Clusters:Generative AI workloads demand GPU-dense server configurations that refresh enterprise refresh cycles prematurely. North American hyperscalers anchor this pull.
- EU Ecodesign Directive:Minimum efficiency thresholds disqualify legacy server generations from European public sector procurement, forcing infrastructure replacement.
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling technologies unlock power densities above 50kW per rack, enabling facility consolidation.
Market Restraints
- Accelerator Export Controls:US Bureau of Industry and Security licensing regimes restrict advanced GPU shipments to designated countries, fragmenting supply access.
- Power Grid Saturation:Northern Virginia and Dallas-Fort Worth utility interconnection queues extend 36-48 months, capping facility expansion velocity.
- Memory Cost Volatility:DDR5 and HBM supply concentrates among three Korean and US suppliers, transmitting price shocks downstream.
Strategic Opportunities
- Sovereign AI Infrastructure:France, Germany, and Japan are deploying nationally controlled compute clusters with domestic vendor preference requirements.
- Modular Edge Deployments:Telco central offices and manufacturing plants demand micro-datacenter form factors with 6-12 month deployment horizons.
- Heat Reuse Integration:District heating networks in Nordic countries and the Netherlands monetize server waste heat through municipal utility partnerships.
Industry Challenges
- Datacenter Engineering Talent:Electrical and mechanical design expertise for 100MW+ facilities concentrates among contractors in Ireland, Singapore, and the United States, constraining global deployment timelines.
- Firmware Supply Chain Integrity:NIST Cybersecurity Framework and ISO 27001 certification requirements extend vendor qualification cycles for baseboard management controllers and BIOS components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Server Market |
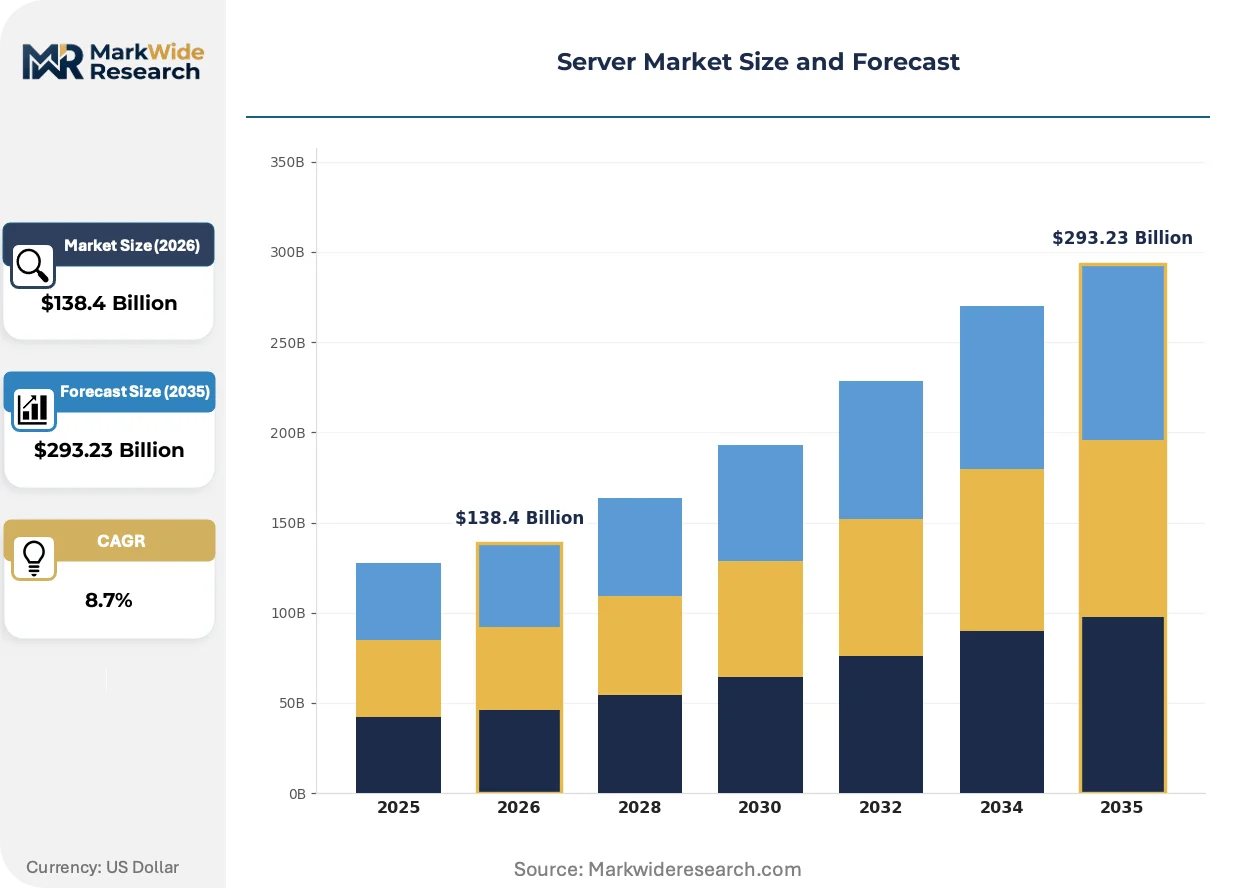
| Market Size in 2026 | $138.4 Billion |
| Market Size in 2035 | $293.23 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers End User: Data Centers, Enterprises, SMBs, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Colocation Service Type: Managed Services, Maintenance, Support, Consulting |
| Companies Covered | Super Micro Computer, IBM Corporation, Dell Technologies, Inspur, Lenovo, Hewlett Packard Enterprise, Nvidia Corporation, Cisco Systems, Foxconn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Server Market Strategic Shifts & Innovations
Compute architectures are fragmenting into workload-optimized designs as thermal constraints and regulatory mandates force abandonment of general-purpose server platforms.
Composable disaggregated infrastructure is decomposing traditional monolithic server designs into pooled CPU, memory, and accelerator resources connected via CXL fabric. Hyperscale operators in the United States and China are deploying these architectures for AI training and in-memory analytics workloads. This decomposition enables 20-30% higher resource utilization rates while reducing stranded capacity.
The EU AI Act risk-classification framework mandates conformity assessment procedures for high-risk AI systems deployed on physical infrastructure. Server vendors must implement logging, traceability, and human oversight capabilities at the hardware layer to serve European enterprise and public sector buyers. Blade and rack configurations destined for EU deployment now require documented supply chain provenance and firmware integrity attestation.
Enterprise buyers are consolidating vendor relationships and demanding as-a-service consumption models that transfer operational risk to suppliers. GreenLake-style platforms from major OEMs displace traditional capital purchase cycles for mid-market customers in Germany, the United Kingdom, and Japan. This preference shift compresses sales cycle complexity but requires vendors to maintain captive financing and field service capabilities.
Server Market Segmentation
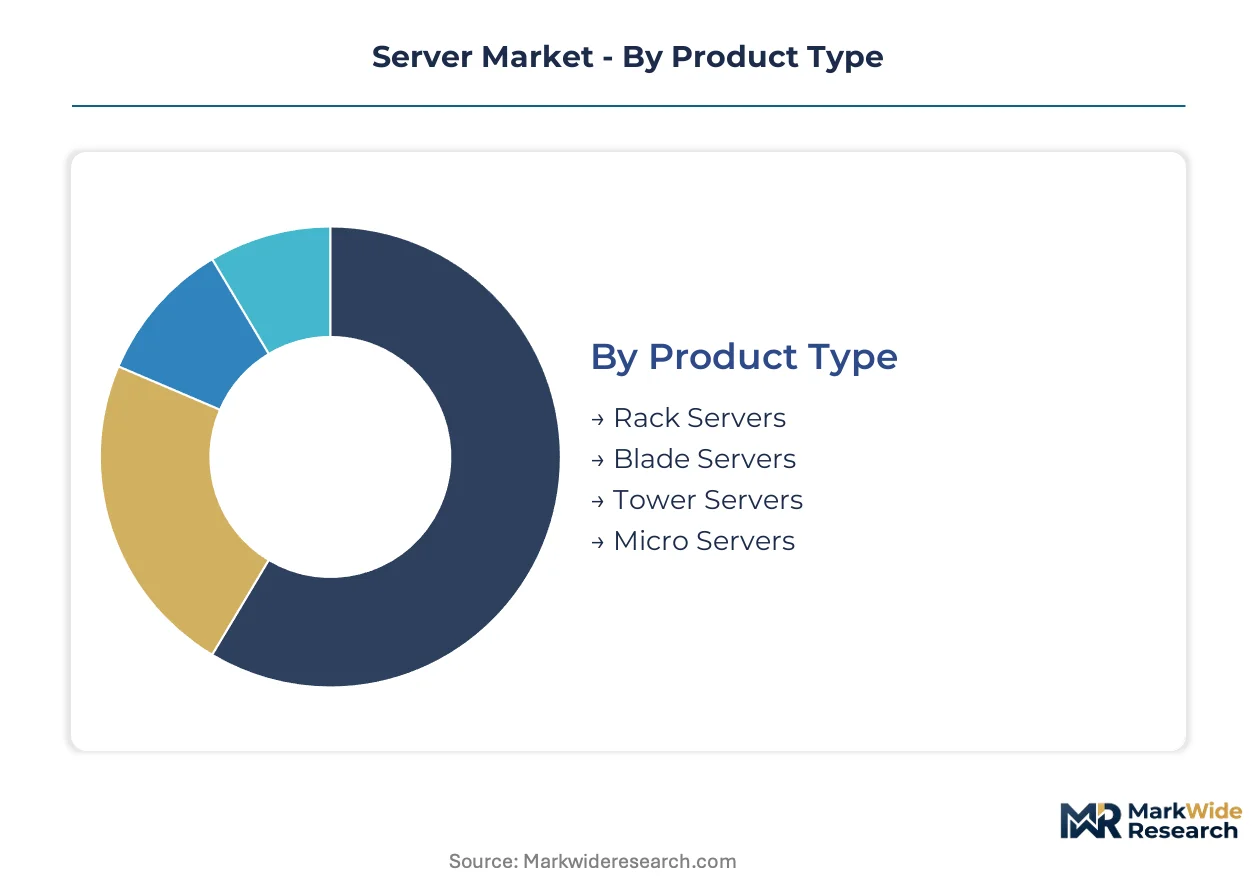
Server procurement patterns diverge sharply between hyperscale operators optimizing for power density and enterprises prioritizing workload flexibility. Segmentation reveals how vendor portfolios must bifurcate to serve these contrasting deployment economics.
Product Type:
Domestic demand concentrates in rack and blade configurations for hyperscale facilities in the United States, while tower and micro server exports serve distributed enterprise footprints across Europe and Asia-Pacific.
- Rack Servers:Standardized 1U to 4U form factors mount in 19-inch datacenter bays with hot-swappable drive bays and redundant power. Northern Virginia hyperscalers deploy these in 100,000-unit volumes for cloud compute pools, constrained only by 36-48 month utility interconnection queues.
- Blade Servers:Chassis-based architectures consolidate multiple server nodes into shared power and cooling infrastructure, reducing cabling complexity by 60% versus discrete racks. Dallas-Fort Worth operators favor these for AI training clusters where density exceeds 50kW per rack.
- Tower Servers:Standalone vertical enclosures suit branch offices and SMB server closets without dedicated datacenter infrastructure.
- Micro Servers:Compact single-socket designs address edge computing nodes and lightweight web hosting workloads with minimal power draw.
Rack servers command the established base. The steepest expansion runs through blade servers.
End User:
Cost tier separation distinguishes capital-intensive hyperscale procurement from operational expenditure models favored by mid-market buyers.
- Data Centers:Hyperscale and colocation operators purchase direct from ODMs and OEMs at 50,000-unit scale, specifying custom motherboard layouts and liquid cooling manifolds. These buyers dominate accelerator-heavy configurations for generative AI training.
- Enterprises:Fortune 500 manufacturers and financial services firms refresh on 3-4 year cycles, consolidating vendor relationships through GreenLake-style as-a-service platforms that transfer operational risk.
- SMBs:Small and medium businesses source through channel partners with 12-24 unit deployments, prioritizing price-per-core and simplified remote management over customization.
- Government Agencies:Public sector procurement in the United States and Europe requires ENERGY STAR certification and NIST Cybersecurity Framework attestation, disqualifying vendors without firmware integrity documentation.
Data centers command the established base. The steepest expansion runs through government agencies as sovereign AI programs accelerate.
Deployment:
Volume concentration follows workload latency requirements, with edge-sensitive applications resisting full cloud migration despite operational simplicity.
- On-Premises:Dedicated facilities owned and operated by end-users persist in regulated industries—healthcare systems under HIPAA and defense contractors under ITAR—where data sovereignty mandates physical control. These deployments carry 5-7 year amortization horizons.
- Cloud-Based:Public cloud consumption eliminates capital expenditure but creates dependency on hyperscaler availability zones. German and Japanese enterprises increasingly demand EU AI Act-compliant infrastructure with documented human oversight capabilities.
- Hybrid:Split architectures place sensitive workloads on-premises while bursting compute-intensive tasks to public cloud, common among pharmaceutical firms running molecular dynamics simulations.
- Colocation:Third-party datacenter leasing offers physical security and redundant power without facility ownership, attracting mid-market buyers in Singapore and Ireland where engineering talent concentrates.
On-premises commands the established base. The steepest expansion runs through hybrid deployments.
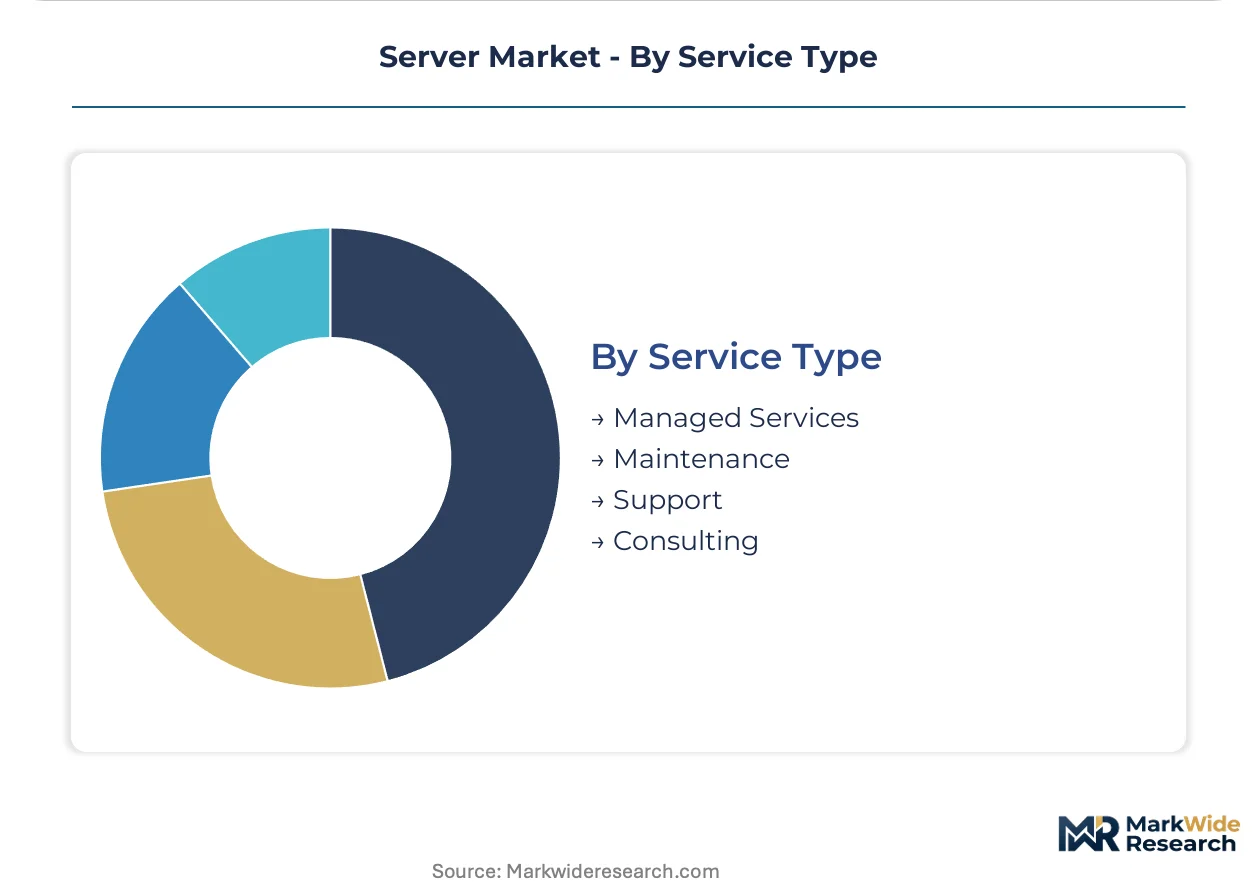
Service Type:
Margin structure inverts between commoditized break-fix maintenance and high-value consulting engagements tied to infrastructure transformation.
- Managed Services:Full operational outsourcing including monitoring, patching, and capacity planning commands premium pricing from enterprises lacking internal infrastructure teams. These contracts typically span 3-5 years with SLA-governed uptime guarantees.
- Maintenance:Hardware replacement and firmware update services generate recurring revenue streams but face downward pressure as third-party maintainers enter with compatible spare parts.
- Support:Tiered technical assistance—remote diagnostics through on-site engineering—supports heterogeneous environments where multiple server generations coexist.
- Consulting:Datacenter design and workload migration advisory captures value from complexity: liquid cooling retrofit planning, AI cluster sizing, and EU Ecodesign Directive compliance roadmapping.
Maintenance commands the established base. The steepest expansion runs through managed services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server deployment patterns diverge sharply by geography. The United States prioritizes hyperscale density for AI training clusters, while European procurement emphasizes regulatory compliance and energy efficiency above raw performance metrics.
United States
Northern Virginia and Dallas-Fort Worth anchor domestic demand with 100,000-unit hyperscale deployments. The EPA ENERGY STAR program mandates minimum efficiency thresholds for federal procurement. Utility interconnection queues in Loudoun County extend 36-48 months, constraining facility expansion velocity despite sustained cloud operator investment.
Germany
Frankfurt and Berlin concentrate sovereign AI infrastructure investment with domestic vendor preference requirements. The EU Ecodesign Directive disqualifies legacy server generations from public sector procurement. GreenLake-style as-a-service platforms capture mid-market enterprise demand as customers shift capital expenditure to operational models.
China
Beijing-Tianjin-Hebei and Yangtze River Delta clusters drive domestic accelerator deployment for AI training workloads. MIIT enforces GB standards for energy efficiency and cybersecurity in datacenter infrastructure. Local OEMs dominate procurement for nationally controlled compute programs, limiting foreign vendor access.
Japan
Tokyo and Osaka metropolitan areas host hybrid cloud deployments with strict data sovereignty requirements. METI promotes domestic semiconductor and server manufacturing through supply chain resilience initiatives. Enterprise buyers consolidate vendor relationships through managed service contracts spanning 3-5 years.
Singapore
The city-state functions as Southeast Asia's interconnection hub with limited land area driving vertical facility construction. The Infocomm Media Development Authority enforces sustainability standards for datacenter licensing. Engineering talent concentration attracts regional headquarters for major OEMs and ODMs serving Asia-Pacific demand.
Server Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in server manufacturing. The upper tier combines captive component sourcing with direct hyperscale relationships, while specialists focus on liquid-cooled configurations or edge-optimized form factors. Three archetypes dominate: full-stack OEMs with financing arms, ODMs serving cloud operator specifications, and component suppliers extending into systems integration. Competitive moves center on backward integration into accelerator supply and geographic diversification of manufacturing footprints.
Among Taiwan-based ODMs, Foxconn occupies a critical supply chain position for hyperscale brands lacking captive production. Within the integrated OEM tier, Dell Technologies and Hewlett Packard Enterprise exemplify divergent go-to-market strategies—direct sales force customization versus as-a-service platform delivery. These three companies anchor the competitive structure through their respective control of manufacturing scale, enterprise relationships, and operational model innovation.
| Leading Market Players |
|---|
| Super Micro Computer |
| IBM Corporation |
| Dell Technologies |
| Inspur |
| Lenovo |
| Hewlett Packard Enterprise |
| Nvidia Corporation |
| Cisco Systems |
| Foxconn |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements between hyperscale operators and ODM manufacturers lock in both supply allocation and price visibility across multi-year deployment horizons. These contracts insulate procurement teams from DDR5 and HBM memory cost volatility while constraining flexibility to pivot toward emerging liquid-cooled architectures.
Pricing Analysis
Contract-based long-term offtake dominates hyperscale procurement, with pricing stratifying across premium liquid-cooled, standard air-cooled rack, and economy refurbished tiers. Price differentiation hinges on ENERGY STAR certification tier and customization depth for AI accelerator density. Cost compression in the standard tier is intensifying because Foxconn and competing ODMs are expanding captive motherboard manufacturing capacity. SMB channel buyers exhibit highest price sensitivity, while sovereign AI programs in France and Germany demonstrate lowest sensitivity due to domestic vendor preference mandates.
Supply Chain Analysis
Strategic stockpiling of high-bandwidth memory and advanced accelerators characterizes hyperscale procurement strategies, contrasting with just-in-time component flows for enterprise rack configurations. Manufacturing concentrates in Taiwan, China, and Mexico, with critical dependencies on Korean-sourced DDR5, Taiwanese-sourced advanced packaging substrates, and US-sourced AI accelerators subject to Bureau of Industry and Security licensing. Single-source vulnerability around HBM supply from Korean manufacturers presents structural risk. Distribution runs through direct OEM relationships for hyperscale buyers and channel partner networks for mid-market enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services and as-a-service consumption models are expanding faster than hardware shipments, transforming vendor economics toward recurring revenue streams with higher margin profiles and lower customer churn.
For Market Incumbents: Consolidate field service capabilities and captive financing arms to defend against GreenLake-style platform competitors eroding traditional capital purchase relationships. Deepen backward integration into liquid cooling manifold production to capture margin from AI cluster deployments. Prioritize NIST Cybersecurity Framework certification investment to maintain public sector procurement eligibility as firmware integrity requirements tighten.
For New Entrants and Emerging Players: Anchor in modular edge micro-datacenter deployments for telco central offices and manufacturing plants, where 6-12 month deployment horizons and simplified thermal constraints reduce engineering talent barriers. Target European mid-market enterprises seeking EU Ecodesign Directive compliance without internal infrastructure teams. Pursue white-label ODM partnerships to bypass direct hyperscale procurement relationships controlled by incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist liquid-cooling component suppliers and firmware integrity verification platforms serving NIST and ISO 27001 compliance requirements. Long-term viability favors vendors with demonstrated hyperscale reference architectures and captive service delivery capabilities. Watch accelerator export licensing expansion as the inflection signal for geographic demand fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liquid Cooling Components | Captures margin from 50kW+ rack densities demanded by Dallas-Fort Worth AI clusters. |
| GreenLake-Style As-a-Service Platform Launch | Transfers operational risk to vendors while locking in 3-5 year enterprise contracts. |
| NIST Cybersecurity Framework Certification | Preserves federal and defense contractor procurement eligibility under tightening firmware rules. |
| Modular Edge Micro-Datacenter Development | Addresses telco and manufacturing demand with reduced engineering talent requirements. |
| Strategic Partnership with Korean Memory Suppliers | Secures DDR5 and HBM allocation amid supply concentration and price volatility. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with datacenter procurement directors, cloud infrastructure engineers, OEM sales executives, and channel distribution partners; and secondary validation through hyperscaler capex disclosures, SEC filings, customs trade data, and EPA ENERGY STAR certification databases. Bottom-up triangulation across server unit shipment estimates and top-down reconciliation against facility power consumption projections anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled demand by product type, end-user scale tier, deployment architecture, and regional regulatory cluster. CAGRs were derived from segment-level growth trajectories weighted by installed base replacement cycles and AI training cluster expansion rates. Key inputs included utility interconnection queue timelines for Northern Virginia and Dallas-Fort Worth, EU Ecodesign Directive implementation schedules, and accelerator export licensing regime changes.
Material uncertainties — sovereign AI program funding shifts, HBM supply disruptions, and datacenter engineering talent migration patterns — sit outside the modeled envelope. Forecasts reflect assumptions about sustained hyperscale investment and regulatory compliance trajectory stability. Revision becomes warranted when utility interconnection delays exceed current queue projections or when accelerator licensing restrictions expand to additional destination countries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable Translator Market
Others
Fabric Based Computing Market
Others
Smart Home Water Softener Market
Others
Sound Reinforcement Market
Others
Residential Electrical Conduit Market
Others
8K Technology Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Stichtite Market
Others
Ultra Mobile Devices (UMD) Market
Others
Duty Free Retail Market
Others
Singapore Retail Market
Others
Prunes Market
Others
Cashew Kernel Market
Others
Sandbags Market
Others
Super Computer Market
Others
Smart-Connected Power Plug Socket Market