
 Nuclear Power Cables Market | 2026-2036
Nuclear Power Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Power Cables Market Insights
Specialized nuclear cable engineering talent is rotating toward Asia-Pacific manufacturing hubs as European and North American utilities defer new build decisions. Prysmian Group leverages its vertical integration into polymer compounding to sustain qualification advantages for safety-class cables. Nexans anchors its position through decades of regulatory track record with EDF and other incumbent fleet operators. Jiangsu Shangshang Cable Group competes on manufacturing scale, having expanded capacity to serve China's domestic reactor construction pipeline.
Nuclear power cables are purpose-built electrical conductors engineered to maintain circuit integrity under extreme thermal, radiation, and seismic conditions, typically employing cross-linked polyethylene or ethylene-propylene rubber insulation rated for 60-year service life alongside redundant shielding layers. These cables transmit control signals, instrument readings, and electrical power within containment structures where failure could disable safety systems. Power cables and control cables together command the dominant share of replacement spending as aging plants in France, Japan, and the United States face obsolescence-driven procurement cycles. Fiber optic cables represent the fastest-growing product category as digital instrumentation and distributed temperature sensing displace legacy copper-based monitoring networks in modern reactor designs.
The International Atomic Energy Agency sets baseline safety standards that national regulators including the NRC in the United States, ASN in France, and the NRA in Japan transpose into legally binding cable qualification protocols. China's National Nuclear Safety Administration enforces GB standards that increasingly align with RCC-E and IEEE 383, creating compliance complexity for multinational suppliers. Stakeholders must monitor how divergent national certification timelines affect project scheduling and inventory positioning across reactor new-build and life-extension programs.
Market Dynamics
Reactor fleet aging across France, Japan, and the United States is generating replacement-driven procurement cycles that now dominate cable demand, while China's new-build program absorbs the bulk of greenfield supply capacity and concentrates engineering talent migration toward Asia-Pacific manufacturing hubs.
Growth Catalysts
- IEEE 383 qualification protocols:The United States NRC mandates these cable fire-resistance and radiation-aging standards for safety-related circuits, compelling utilities to upgrade legacy installations and sustain replacement demand.
- Digital instrumentation architectures:Fiber optic distributed temperature sensing systems are displacing copper thermocouple networks in modern reactor designs, creating new cable specification requirements.
- China's reactor construction pipeline:The National Nuclear Safety Administration's GB standards alignment with RCC-E and IEEE frameworks is accelerating domestic procurement while drawing qualified suppliers into captive supply relationships.
Market Restraints
- Cross-linked polyethylene resin concentration:Specialty polymer compounding capacity clusters among European and Japanese chemical suppliers, exposing cable manufacturers to input cost volatility and qualification disruption.
- 60-year service life certification:Accelerated thermal and radiation aging tests required for safety-class cable qualification extend development timelines and freeze out unproven material formulations.
- Regulatory divergence friction:China's GB standards, France's RCC-E, and the United States IEEE 383 maintain non-harmonized test protocols, forcing multinational suppliers to maintain parallel inventory and certification tracks.
Strategic Opportunities
- Small modular reactor deployment:The United States Department of Energy's Advanced Reactor Demonstration Program is creating first-of-a-kind cable specification opportunities for factory-fabricated plant designs.
- Life extension beyond 60 years:France's ASN and the United States NRC are developing cable aging management guidelines for 80-year operating licenses, opening replacement and monitoring system markets.
- Silicone rubber insulation convergence:The combination of silicone elastomer chemistry with fiber optic sensing is enabling integrated cable-sensor products for containment monitoring applications.
Industry Challenges
- Radiation effects engineering expertise:The specialized knowledge base for predicting polymer degradation under mixed neutron-gamma fields is concentrating among retiring specialists at national laboratories in France and the United States.
- Seismic qualification test capacity:Shake-table facilities capable of simulating safe-shutdown earthquake conditions for full cable assemblies operate at limited sites in Japan, France, and the United States, creating certification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Power Cables Market |
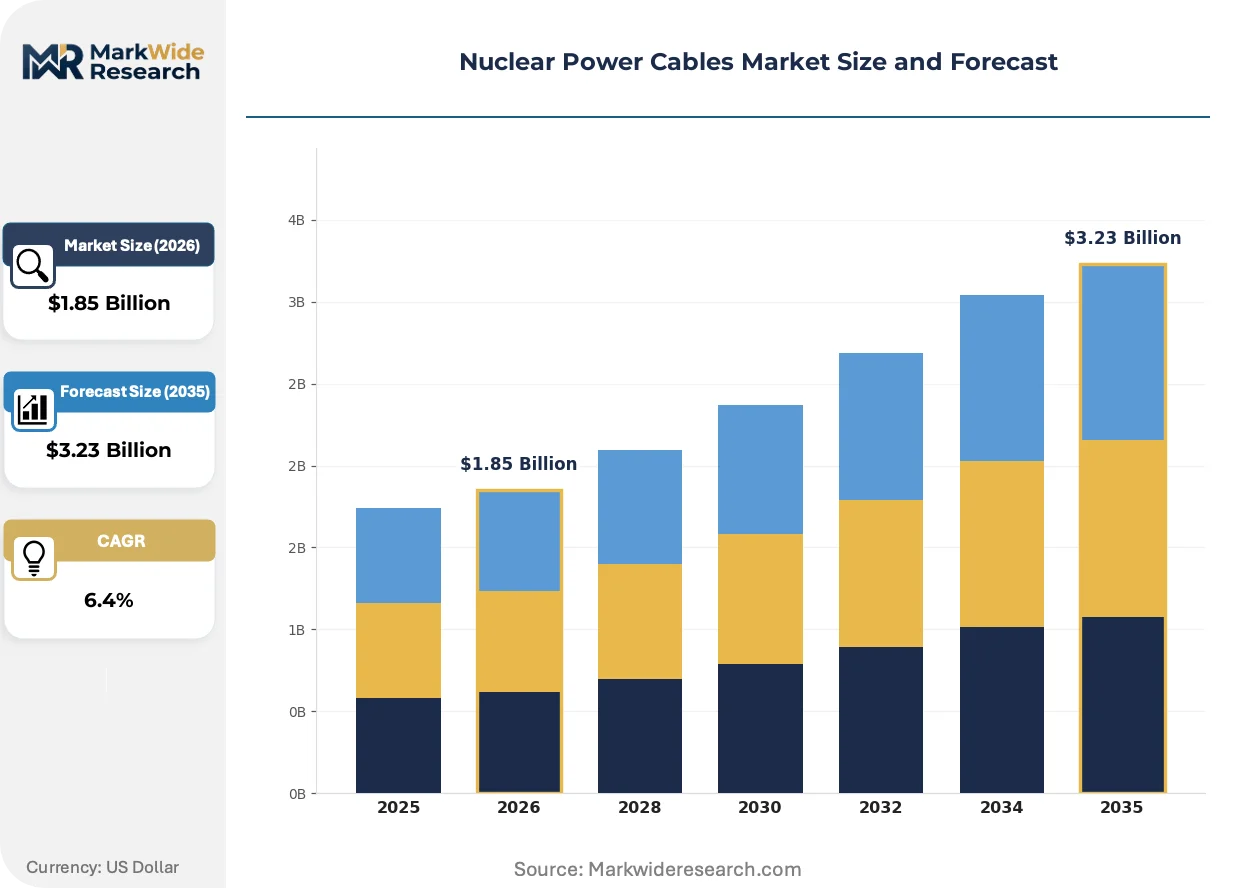
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrumentation Cables, Control Cables, Power Cables, Fiber Optic Cables Material: Copper, Aluminum, Polyethylene, Cross-Linked Polyethylene Application: Reactor Control, Safety Systems, Communication, Power Distribution End User: Nuclear Power Plants, Research Facilities, Defense, Industrial |
| Companies Covered | Jiangsu Shangshang Cable Group, Shandong Hualing Cable, Prysmian Group, AnHui TianKang Group, Qingdao Hanhe Cable, Nexans, Sunway, Habia Cable, Anhui Cable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Power Cables Market Trends and Innovations
Material science advances and regulatory technology mandates are restructuring how cable systems are specified, tested, and deployed across reactor new-build and life-extension programs.
Low-smoke zero-halogen jacketing compounds are displacing traditional chlorinated polyethylene sheaths in containment applications. EDF and Framatome specify these formulations for their EPR reactor fleet. The technology is bifurcating the supplier base between qualified compounders with radiation-aging expertise and commodity cable producers lacking certification track records.
France's ASN has tightened cable fire-resistance testing protocols following post-Fukushima stress tests. The regulator now requires demonstration of circuit integrity under simultaneous thermal, radiation, and flooding conditions. Safety-class cable procurement in France and Belgium is responding with expanded qualification testing budgets and extended vendor pre-approval timelines.
Long-term service agreements are displacing transactional spot purchasing for safety cable replacement programs. EDF's fleet operators in France and the United States utility Exelon now favor multi-year supply contracts with embedded technical support and aging management services. This pattern is most visible in the United States, where merchant plant economics favor predictable maintenance cost structures over capital-intensive inventory positions.
Nuclear Power Cables Market Segmentation
Nuclear power cable procurement splits across four distinct dimensions, each carrying different qualification burdens and margin profiles. Product type and material chemistry determine regulatory certification pathways, while application and end-user context shape volume concentration and replacement cycles.
Product Type:
Instrumentation and control cables face the most acute substitution pressure as digital fiber optic architectures displace legacy copper signaling networks in modern reactor designs.
- Power Cables:Heavy-gauge conductors rated for medium-voltage distribution within containment structures, employing cross-linked polyethylene insulation with redundant metallic shielding. Demand concentrates in China's new-build reactor pipeline where State Power Investment Corporation and China General Nuclear Power Group specify 60-year qualified cable systems for primary power distribution.
- Control Cables:Multi-conductor assemblies transmitting safety system actuation signals, featuring twisted-pair geometry with individual and overall shields. France's EDF fleet renewal program and Japan's Tokyo Electric Power Company life-extension projects dominate replacement procurement as aging plants face IEEE 383 and RCC-E requalification deadlines.
- Instrumentation Cables:Low-capacitance pairs for sensor signal transmission from reactor core thermocouples and pressure transmitters.
- Fiber Optic Cables:Silica-based distributed temperature sensing systems replacing copper thermocouple networks.
Power cables anchor the volume base while fiber optic cables gain share at the steepest rate.
Material:
Cost tier stratification separates qualified radiation-resistant compounds from commodity conductor metals, with polymer chemistry commanding premium positioning.
- Cross-Linked Polyethylene:Thermoset insulation formed through electron-beam or silane cross-linking, delivering 60-year thermal aging resistance and radiation tolerance up to 200 Mrad. China's GB standards alignment with IEEE 383 is accelerating domestic compounding capacity expansion as Jiangsu Shangshang and Far East Cable qualify in-house formulations.
- Copper:Oxygen-free high-conductivity wire serving as the baseline conductor for safety-class applications, with specific surface area and annealing protocols specified in RCC-E and IEEE 383. United States NRC mandates copper for all safety-related circuits, freezing out aluminum alternatives in containment applications despite cost penalties.
- Aluminum:Lightweight conductor restricted to non-safety power distribution outside containment due to oxidation susceptibility and lower mechanical strength.
- Polyethylene:Uncross-linked insulation limited to temporary installations and non-safety circuits with shorter service life requirements.
Copper conductors dominate safety-class procurement while cross-linked polyethylene compounds capture the highest value per kilogram.
Application:
Customer type stratification reveals divergent procurement patterns between fleet operators with captive engineering staff and project developers reliant on turnkey suppliers.
- Safety Systems:Cable circuits for reactor trip, emergency core cooling, and containment isolation, subject to the most stringent IEEE 383 and RCC-E qualification protocols including loss-of-coolant accident simulation. France's ASN post-Fukushima stress tests have tightened fire-resistance requirements, extending vendor pre-approval timelines to 18-24 months for safety-class suppliers.
- Reactor Control:Signal and power paths for rod control, neutron monitoring, and process control systems. Japan's Nuclear Regulation Authority mandates seismic qualification to JEAC 4601 standards, concentrating demand among suppliers with shake-table certification from Japanese testing facilities.
- Power Distribution:Medium-voltage feeders for auxiliary systems and non-safety loads.
- Communication:Voice, data, and video transmission for control room and emergency response coordination.
Safety systems command the longest qualification cycles while reactor control applications generate the most recurring replacement volume.
End User:
Geographic concentration of reactor construction and fleet aging patterns determines regional demand distribution across end-user categories.
- Nuclear Power Plants:Commercial electricity generation facilities requiring 60-year qualified cable systems for safety-related circuits, with procurement split between new-build projects in China and life-extension programs in France, Japan, and the United States. EDF's fleet in France and Exelon's United States plants are transitioning to multi-year service agreements with embedded technical support.
- Research Facilities:Test reactors and materials irradiation facilities with specialized cable requirements for high-flux environments. Oak Ridge National Laboratory in the United States and CEA's Cadarache facility in France specify custom cable designs for experimental applications.
- Defense:Naval propulsion reactors and military fuel cycle facilities with classified procurement channels.
- Industrial:Non-nuclear process industries adopting nuclear-grade cable standards for extreme environment applications.
Nuclear power plants absorb the dominant procurement volume while research facilities present the most specialized specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes nuclear power cables primarily for new reactor construction, while France, Japan, and the United States orient procurement toward aging fleet replacement and safety system upgrades. This consumption-mix differential shapes supplier qualification priorities across geographies.
China
State Power Investment Corporation and China General Nuclear Power Group drive cable procurement for the world's fastest reactor construction pipeline. The National Nuclear Safety Administration enforces GB standards that increasingly align with RCC-E and IEEE 383, accelerating domestic supplier qualification. Jiangsu Shangshang Cable Group has expanded manufacturing capacity in Jiangsu Province to serve captive supply relationships with state-owned utilities.
France
EDF's fleet renewal program dominates replacement demand as aging reactors face RCC-E requalification deadlines. The Autorité de Sûreté Nucléaire tightened fire-resistance testing protocols following post-Fukushima stress tests, extending vendor pre-approval timelines to 18-24 months. Framatome and EDF specify low-smoke zero-halogen formulations from qualified compounders at nuclear engineering clusters around Paris and Grenoble.
United States
Exelon and other merchant plant operators favor multi-year service agreements with embedded technical support over spot purchasing. The Nuclear Regulatory Commission mandates IEEE 383 qualification protocols for safety-related circuits, compelling utilities to upgrade legacy installations. Oak Ridge National Laboratory in Tennessee specifies custom cable designs for research reactor applications with specialized high-flux requirements.
Japan
Tokyo Electric Power Company and Kansai Electric Power Company drive life-extension procurement cycles for aging Fukushima-era fleets. The Nuclear Regulation Authority mandates seismic qualification to JEAC 4601 standards, concentrating demand among suppliers with shake-table certification from Japanese testing facilities. Manufacturing clusters in Osaka and Nagoya host cable assembly operations serving domestic reactor operators.
South Korea
Korea Hydro and Nuclear Power maintains steady replacement procurement for its standardized reactor fleet. The country's nuclear safety regulator enforces quality assurance protocols aligned with IEEE standards while supporting domestic supplier development. Cable engineering talent concentrates around Seoul and Daejeon, where Korea Atomic Energy Research Institute facilities anchor specialized qualification expertise.
Nuclear Power Cables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in nuclear power cable supply. European and Japanese chemical suppliers cluster specialty polymer compounding capacity, exposing cable manufacturers to input cost volatility and qualification disruption. Three strategic archetypes dominate: vertically integrated compounders with radiation-aging expertise, fleet-incumbent suppliers with decades of regulatory track record, and scale-driven Asian manufacturers serving domestic new-build pipelines. Competitive moves concentrate on backward integration into polymer formulation and captive supply relationships with state-owned reactor operators.
Among European-integrated suppliers, Prysmian Group and Nexans occupy positions sustained by qualification advantages and regulatory relationships with incumbent fleet operators. Jiangsu Shangshang Cable Group exemplifies the scale-driven archetype, having expanded manufacturing capacity to serve China's domestic reactor construction pipeline. These three represent distinct competitive vectors: compounder integration, regulatory track record, and manufacturing scale.
| Leading Market Players |
|---|
| Jiangsu Shangshang Cable Group |
| Shandong Hualing Cable |
| Prysmian Group |
| AnHui TianKang Group |
| Qingdao Hanhe Cable |
| Nexans |
| Sunway |
| Habia Cable |
| Anhui Cable |
| Others |
Pricing and Supply Chain Analysis
IEEE 383 qualification protocols gate both supplier entry and price tier formation in nuclear power cable procurement, compressing margins for uncertified producers while embedding technical service premiums in multi-year fleet agreements. The interaction between 60-year certification requirements and captive supply relationships with state-owned utilities concentrates pricing power among qualified compounders.
Pricing Analysis
Long-term service agreements with embedded technical support dominate procurement for aging fleet operators, displacing spot purchasing for safety-class cable replacement programs. Price differentiation hinges on radiation-aging qualification tier and seismic certification grade, with shake-table tested assemblies commanding substantial premiums over baseline IEEE 383 compliance. Cost compression in standard power distribution cables is intensifying as Chinese manufacturers expand cross-linked polyethylene compounding capacity. Merchant plant operators in competitive electricity markets exhibit the highest price sensitivity, while state-owned utilities in new-build programs prioritize qualification track record over unit cost.
Supply Chain Analysis
Container availability constraints on European-Japanese chemical trade lanes elevate inbound logistics costs for specialty polymer formulations, compounding input cost volatility for cable manufacturers. Specialty compounding capacity clusters in Germany, Japan, and the United States, drawing from ethylene-propylene rubber feedstocks and radiation-stabilized resin systems. Single-source vulnerability concentrates in electron-beam cross-linking equipment where two Japanese suppliers anchor global qualification capacity. Distribution runs through direct technical partnerships with reactor operators, bypassing commodity distributors for safety-class applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across IEEE 383, RCC-E, and China's GB standards fragments qualification pathways, creating specialist niches for compounders with multi-jurisdictional certification capabilities. Fiber optic instrumentation substitution and small modular reactor deployment open additional white-space segments.
For Market Incumbents: Secure backward integration into silicone rubber formulation to capture integrated cable-sensor product margins as distributed temperature sensing displaces copper thermocouple networks. Lock in captive supply relationships with China's State Power Investment Corporation and China General Nuclear Power Group before domestic competitors complete GB standards alignment. Extend vendor pre-approval timelines through embedded aging management services to freeze out unqualified entrants.
For New Entrants and Emerging Players: Accelerated GB-IEEE 383 harmonization pathways offer the fastest route to qualified supplier status for China's new-build pipeline. Target fiber optic containment monitoring applications where silicone elastomer chemistry convergence lowers legacy radiation-effects engineering barriers. Partner with Oak Ridge National Laboratory or CEA Cadarache for custom research reactor specifications that bypass fleet-incumbent track record requirements.
For Investors and Strategic Acquirers: France's ASN post-Fukushima stress test implementation reshapes the acquisition landscape toward compounders with demonstrated loss-of-coolant accident simulation capabilities. Five-to-ten year viability favors vertically integrated specialists with in-house polymer formulation rather than assembly-only cable producers. Monitor EDF multi-year service agreement renewal rates as the inflection signal for replacement cycle durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | In-house cross-linked polyethylene formulation locks in qualification advantages against resin supply disruption. |
| Multi-Jurisdictional Certification Investment | Parallel IEEE 383, RCC-E, and GB standards alignment opens access to China, France, and United States reactor projects. |
| Silicone-Fiber Optic Convergence R&D | Integrated cable-sensor products capture distributed temperature sensing substitution in EPR and SMR designs. |
| Long-Term Service Agreement Expansion | Embedded aging management services with Exelon and EDF convert transactional replacement into recurring revenue. |
| Shake-Table Certification Capacity Expansion | Seismic qualification testing facilities in Japan and France alleviate JEAC 4601 and RCC-E certification bottlenecks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IAEA safety standards documentation, national regulatory filings with the NRC and ASN, and reactor operator procurement disclosures. Cable manufacturer executives, nuclear safety regulator technical leads, utility engineering procurement officers, and polymer compounding R&D directors provided structured input. Customs trade data, reactor construction project databases, and IEEE qualification registry records furnished validation anchors. Bottom-up cable demand modeling triangulates against top-down reactor fleet aging projections.
Segmentation dimensions modeled span product type, material chemistry, application safety classification, and end-user geography across the projection horizon. Power cable, control cable, instrumentation cable, and fiber optic cable volumes derive from reactor new-build and life-extension program tracking. Cross-linked polyethylene, silicone rubber, and copper conductor demand splits reflect qualification protocol alignment trends. CAGRs emerge from reactor construction pipeline analysis and replacement cycle timing rather than extrapolation.
Underlying assumptions cover GB standards harmonization velocity, small modular reactor deployment pace, and radiation-effects engineering specialist availability, with deviation risk concentrated in regulatory timeline slippage and seismic qualification test capacity constraints. Recalibration cycles align with material shifts in national nuclear safety administration policy announcements and fleet operator procurement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Ultraviolet Disinfection Equipment Market
Others
Balsa Wood Market
Others
Handheld Mobile Computers Market
Others
Rugged Tablet Market
Others
Hopper Dryers Market
Others
Smart Home Water Softener Market
Others
Underwater Light Market
Others
Tote Bags Market
Others
Defense Optronics Market
Others
Metal Air Battery Market
Others
Smart Badge Market
Others
Italy 3D Printing Construction Market
Others
Global Healthcare/Medical Simulation Market
Others
Wind and Solar Hybrid Street Light Market
Others
Cat Food and Snacks Market
Others
Semiconductor Gas Filters Market