
 Crystal Growth Equipment Market | 2026-2036
Crystal Growth Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Growth Equipment Market Insights
Semiconductor manufacturers are collapsing the traditional buyer mix that research institutions once dominated in crystal growth equipment procurement. PVA TePla AG leverages its vertical integration across vacuum and crystal growth technologies to anchor European supply chains for compound semiconductors. Ferrotec competes through its dominance in magnetic fluid seals and thermal management subsystems that sustain high-purity melt environments. Naura differentiates by controlling the largest installed base of Czochralski pullers within China's expanding silicon wafer ecosystem.
Crystal growth equipment encompasses furnaces, pullers, and reactors designed to achieve controlled solidification from melt, vapor, or solution phases, typically operating at temperatures exceeding 1,400 degrees Celsius with precision thermal gradients measured in Kelvin per centimeter. These systems produce single-crystal ingots for semiconductor wafers, optical substrates, and piezoelectric elements where atomic lattice uniformity determines functional performance. The Czochralski segment leads in installed capacity for silicon and sapphire production, while the Floating Zone segment occupies the highest margin pool for ultra-high-purity semiconductor-grade silicon used in power devices. Vapor Transport systems specialize in wide-bandgap materials including silicon carbide, where equipment utilization rates correlate directly with substrate diameter transitions.
REACH and RoHS frameworks in Europe restrict hazardous substances in furnace heating elements and crucible coatings, while China's GB standards and MIIT directives mandate energy efficiency thresholds for industrial thermal equipment. The EPA in the United States enforces emissions controls on fluorinated gases used in certain vapor-phase crystal growth processes. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment equipment design standardization and reshape supplier qualification timelines.
Market Dynamics
Silicon carbide substrate transitions from 150mm to 200mm diameter are forcing synchronous equipment upgrades across wafer fabrication ecosystems, compressing replacement cycles and redistributing competitive advantage toward vendors with proven thermal uniformity at larger melt volumes.
Growth Catalysts
- Power Electronics Fabrication:Electric vehicle traction inverters and renewable energy converters require silicon carbide substrates that only advanced physical vapor transport systems can yield at commercial scale.
- REACH Material Purity Mandates:European equipment purchasers now specify furnace components free of restricted substances, filtering supplier pools toward RoHS-certified crucible and heater manufacturers.
- China's Wafer Fab Buildout:Domestic capacity expansion for compound semiconductors under MIIT directives sustains puller demand from Naura and regional equipment integrators.
Market Restraints
- High-Purity Graphite Supply Concentration:Crucible and susceptibility materials for silicon carbide growth depend on limited Japanese and Chinese suppliers, exposing equipment manufacturers to input cost volatility.
- Technical Limitation in Defect Density:Micropipe and dislocation reduction in wide-bandgap crystals remains below thresholds for certain RF and power device tiers, constraining addressable substrate yield.
- F-Gas Regulation Friction:European F-Gas restrictions on fluorinated process gases complicate vapor-phase growth chemistries and extend equipment qualification timelines for new reactor designs.
Strategic Opportunities
- India's Emerging Fab Ecosystem:PLI scheme subsidies for semiconductor manufacturing create first-mover positioning for Czochralski and directional solidification equipment vendors before domestic supply chains mature.
- Photonics Substrate Convergence:Lithium niobate and gallium arsenide growth systems adapted from telecom applications now serve quantum computing and sensing markets with modified thermal profiles.
- Digital Twin Integration:Real-time melt interface modeling combined with predictive maintenance contracts is creating new recurring revenue streams separate from equipment hardware sales.
Industry Challenges
- Specialized Thermal Engineer Scarcity:Crystal growth process optimization requires rare expertise in computational fluid dynamics and phase boundary control that outpaces university pipeline output.
- Extended Customer Qualification Cycles:Semiconductor wafer manufacturers demand 12-18 month validation periods for new puller installations, delaying revenue recognition and straining working capital.
- Legacy System Integration Complexity:Brownfield fab retrofits must synchronize new growth equipment with existing SCADA and MES architectures, inflating commissioning costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Growth Equipment Market |
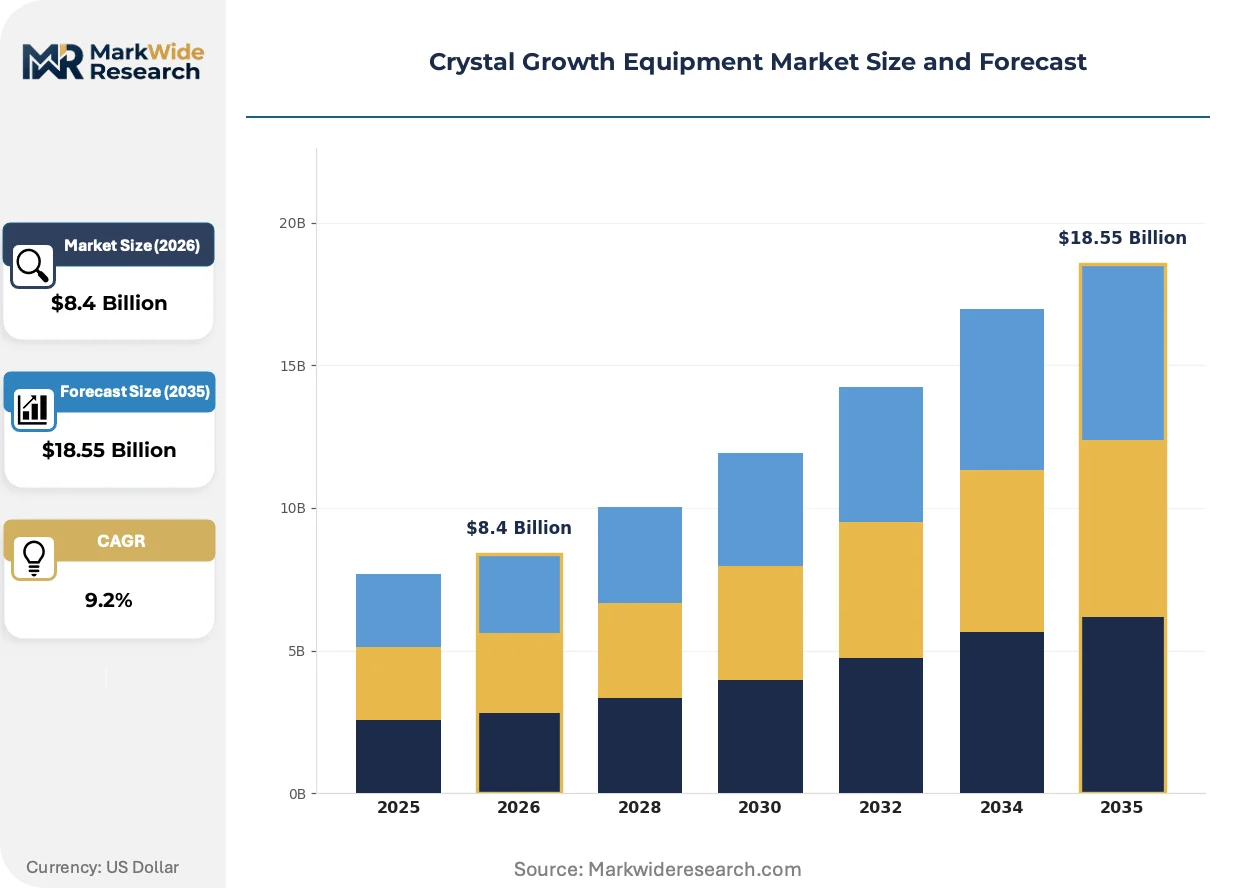
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridgman, Czochralski, Floating Zone, Vapor Transport End User: Semiconductor Manufacturers, Research Institutions, Solar Cell Producers, Optical Device Manufacturers Application: Electronics, Photonics, Renewable Energy, Aerospace Technology: Hydrothermal, Melt Growth, Sublimation, Chemical Vapor Deposition |
| Companies Covered | PVA TePla AG, S-TECH Co., Ltd., ECM Technologies, Ferrotec, Naura, Thermal Technology, CVD Equipment Corporation, Nissin Giken, Wuxi Autowell Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Growth Equipment Market Trends and Innovations
Equipment architectures are converging around closed-loop thermal management and AI-assisted process control, collapsing the historical separation between hardware vendors and software-enabled service providers.
Hot zone designs incorporating advanced carbon-carbon composites and isostatic graphite grades are miniaturizing thermal mass while maintaining gradient precision. Semiconductor wafer manufacturers in Japan and South Korea are adopting these configurations for 200mm silicon carbide pilot lines. The structural compression of heater element volume is enabling faster thermal ramp rates and reduced energy consumption per growth run.
EPA enforcement actions against fluorinated gas emissions are tightening process chemistry documentation requirements for US-based vapor transport equipment operators. Equipment manufacturers must now certify alternative carrier gas protocols and capture systems to maintain market access. Power device substrate producers with US fabrication footprints are accelerating dry etch and closed-loop scrubber retrofits to preempt regulatory displacement.
After-sales service unbundling is fragmenting traditional equipment procurement into hardware, software license, and predictive maintenance subscription components. Chinese wafer fabs are leading this decomposition, negotiating thermal field calibration and spare part logistics as separate line items. Compound semiconductor manufacturers in Xiamen and Hefei now benchmark total cost of ownership across multi-year service contracts rather than upfront capital expenditure alone.
Crystal Growth Equipment Market Segmentation
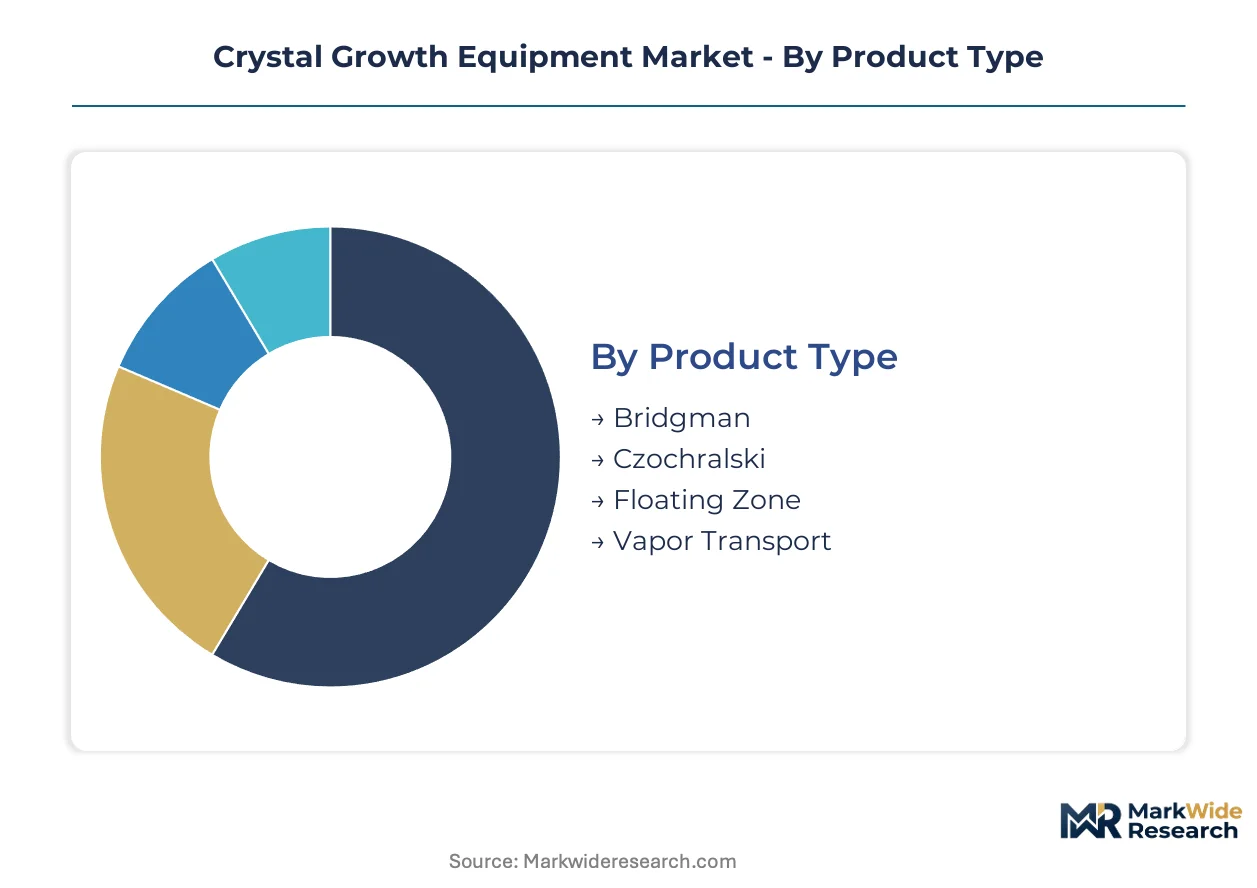
Crystal growth equipment serves fundamentally different thermal regimes and purity requirements across semiconductor, optical, and energy applications. Segmentation reveals where equipment architectures diverge and where process technologies converge across customer types.
Product Type:
Substitution pressure runs highest against legacy Bridgman systems as compound semiconductor manufacturers migrate toward vapor-phase methods for wide-bandgap materials.
- Czochralski:Puller systems rotate seed crystals from silicon melts exceeding 1,400 degrees Celsius to produce single-crystal ingots for mainstream semiconductor wafers. Chinese wafer fabs under MIIT directives sustain the largest installed base expansions for 200mm and 300mm silicon production.
- Vapor Transport:Physical vapor transport reactors sublime source material onto seed crystals in controlled temperature gradients to yield silicon carbide substrates. Demand concentrates with electric vehicle traction inverter manufacturers requiring 150mm and 200mm SiC wafers for power module integration.
- Bridgman:Directional solidification furnaces for compound semiconductors and scintillation crystals face displacement by gradient-freeze alternatives in high-purity applications.
- Floating Zone:Contactless melting using RF coils produces ultra-high-purity silicon for power discrete devices with minimal contamination from crucible materials.
Czochralski retains volume leadership; Vapor Transport holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive semiconductor fabs from research institutions operating smaller-batch systems.
- Semiconductor Manufacturers:Wafer fabs demand continuous throughput systems with automated diameter control and real-time defect monitoring. Chinese compound semiconductor foundries in Xiamen and Hefei drive qualification timelines for 200mm SiC puller installations.
- Research Institutions:Universities and national laboratories operate versatile multi-material furnaces for novel crystal synthesis and process development. Funding constraints limit batch sizes and thermal uniformity specifications compared to production-scale equipment.
- Solar Cell Producers:Silicon ingot growth for photovoltaic applications prioritizes crucible volume and energy efficiency over the atomic perfection required for microelectronics.
- Optical Device Manufacturers:Sapphire and YAG crystal producers for laser and LED substrates require precise optical homogeneity control during solidification.
Semiconductor Manufacturers dominate capital deployment; Research Institutions maintain the most diverse equipment portfolios.
Application:
Geography-driven demand clusters separate mature electronics markets from emerging renewable energy installations.
- Electronics:Silicon and compound semiconductor substrates for integrated circuits and discrete devices constitute the core revenue base. Japanese and South Korean memory and logic manufacturers anchor demand for 300mm Czochralski systems.
- Renewable Energy:Silicon carbide substrates for solar inverters and wind converter stations expand addressable equipment markets beyond traditional microelectronics. European wind turbine manufacturers under EU Green Deal procurement standards specify wide-bandgap power modules.
- Photonics:Lithium niobate and nonlinear optical crystals for telecommunications and quantum applications require specialized thermal profiles distinct from semiconductor growth.
- Aerospace:Radiation-hardened silicon and sapphire windows for sensor applications demand certified traceability and extreme purity documentation.
Electronics commands the largest installed base; Renewable Energy is climbing the fastest.
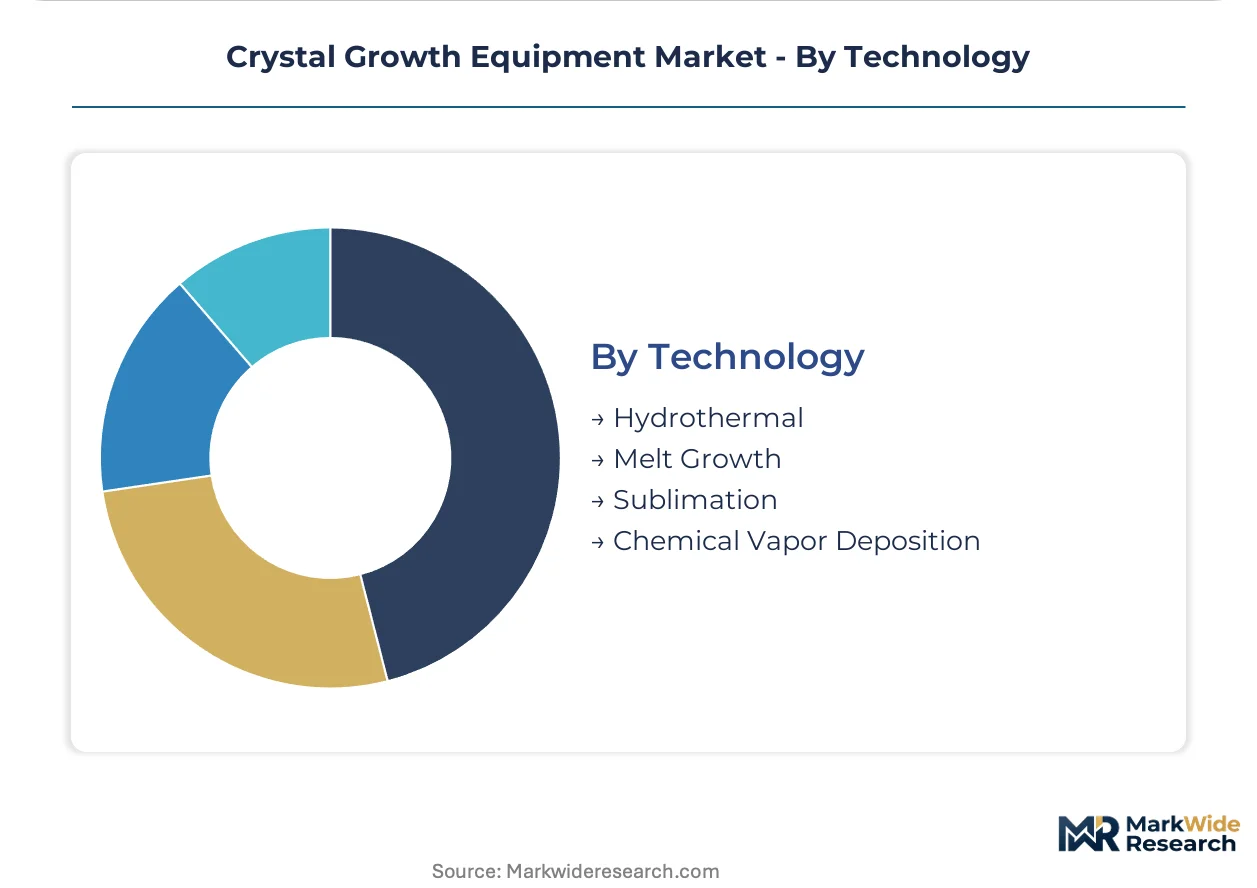
Technology:
Supply concentration among high-purity graphite and crucible suppliers disproportionately constrains melt growth methods versus vapor-phase alternatives.
- Chemical Vapor Deposition:CVD reactors deposit epitaxial layers from precursor gases to produce diamond and wide-bandgap semiconductor films. Japanese equipment vendors lead in multi-wafer planetary reactor designs for gallium nitride LED production.
- Sublimation:Modified Lely processes and seeded sublimation dominate commercial silicon carbide crystal production. Chinese manufacturers are scaling 200mm sublimation reactor capacity under domestic substrate self-sufficiency mandates.
- Melt Growth:Czochralski, Bridgman, and gradient-freeze methods depend on crucible materials facing REACH and RoHS purity restrictions in European markets.
- Hydrothermal:High-pressure aqueous solutions synthesize quartz and oxide crystals for frequency control and piezoelectric applications at lower temperatures than melt-based methods.
Melt Growth retains the broadest installed footprint; Sublimation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor wafer fabs now dominate equipment procurement, displacing research institutions as the primary buyer archetype. China anchors volume demand through domestic capacity buildouts. Germany and Japan sustain premium-tier supply chains for high-purity components. South Korea and the United States concentrate advanced compound semiconductor pilot lines.
China
Domestic wafer fabs under MIIT directives drive the largest installed base expansion for 200mm and 300mm silicon production. GB standards mandate energy efficiency thresholds for industrial thermal equipment. Xiamen and Hefei compound semiconductor foundries qualify 200mm SiC puller installations with compressed timelines.
Germany
Automotive power module manufacturers demand silicon carbide substrates for electric vehicle traction inverters. REACH and RoHS frameworks restrict hazardous substances in furnace heating elements and crucible coatings. Bavaria-based equipment integrators anchor European supply chains for compound semiconductor growth systems.
Japan
Memory and logic manufacturers sustain demand for 300mm Czochralski systems with automated diameter control. METI oversees industrial standards for high-purity graphite and carbon-carbon composite materials. Kyushu fabrication clusters pilot 200mm silicon carbide substrate production with modified thermal profiles.
South Korea
Chaebol-affiliated wafer fabs expand gallium nitride capacity for RF and power electronics applications. MFDS and national technology programs support wide-bandgap semiconductor substrate self-sufficiency. Seoul Capital Area facilities adopt closed-loop thermal management with AI-assisted process control.
United States
EPA enforcement actions tighten fluorinated gas emissions documentation for vapor transport equipment operators. Power device substrate producers accelerate dry etch and closed-loop scrubber retrofits. Greater Boston and Pacific Northwest research clusters maintain multi-material furnace portfolios for novel crystal synthesis.
Crystal Growth Equipment Market Competitive Landscape
Player mix skews toward integrated vacuum technology specialists and regional equipment fabricators with captive thermal engineering capabilities. The vendor base separates into three strategic archetypes: European precision equipment houses with vertical control over vacuum subsystems, Asian scale manufacturers with dominant installed bases in domestic wafer ecosystems, and mid-tier specialists competing on hot zone retrofit and after-sales service unbundling. M&A activity concentrates on magnetic fluid seal and high-purity graphite suppliers. Geographic expansion into India's PLI-subsidized fab ecosystem represents the dominant competitive move.
Among European precision equipment houses, PVA TePla AG and ECM Technologies exemplify the vacuum-integrated archetype with in-house production of thermal management subsystems. Ferrotec occupies a position within the component-specialist tier, anchoring supply for magnetic fluid seals that sustain high-purity melt environments. Naura represents the Asian scale-driven archetype, sitting within China's expanding silicon wafer ecosystem with the largest installed base of Czochralski pullers. These three company types illustrate the structural divergence between premium-tier integrated suppliers and volume-focused regional fabricators.
| Leading Market Players |
|---|
| PVA TePla AG |
| S-TECH Co., Ltd. |
| ECM Technologies |
| Ferrotec |
| Naura |
| Thermal Technology |
| CVD Equipment Corporation |
| Nissin Giken |
| Wuxi Autowell Technology |
| Others |
Pricing and Supply Chain Analysis
200mm silicon carbide capacity utilization rates above 85 percent in Chinese and Japanese wafer fabs are compressing thermal component lead times and elevating price floors for high-purity graphite susceptors and carbon-carbon composite heaters. This scale concentration simultaneously concentrates bargaining power among crucible suppliers and forces equipment purchasers into multi-year offtake contracts indexed to energy and raw material baskets.
Pricing Analysis
Cost-plus contracts with graphite and isostatic carbon indexation dominate procurement for Czochralski and vapor transport hot zone assemblies. Three-tier pricing structure across premium, standard, and economy levels separates RoHS-certified European suppliers from Asian volume manufacturers and refurbished equipment brokers. Pricing pressure stems from China's MIIT-mandated energy efficiency thresholds that inflate compliance engineering costs. Research institutions exhibit highest price sensitivity due to fixed grant funding, while automotive power module manufacturers accept premium tiers for traceability documentation.
Supply Chain Analysis
Japan and China anchor high-purity graphite production for crucibles and susceptors, with German carbon-carbon composite specialists feeding European REACH-compliant equipment integrators. Raw material flows draw from needle coke refineries in Shandong and Osaka, isostatic pressing facilities in Bavaria, and rare earth heating element coatings from Jiangxi. Single-source vulnerability concentrates in 200mm silicon carbide seed crystal supply. Distribution runs through direct OEM relationships for semiconductor manufacturers and regional integrator networks for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystal growth equipment procurement is fragmenting across service-unbundled contracts and digital twin subscriptions, creating white-space niches for specialized thermal engineering boutiques and predictive maintenance platforms.
For Market Incumbents: Consolidate captive supply of high-purity graphite through backward integration into Japanese or Chinese carbon processing assets. Lock in multi-year service contracts with Chinese wafer fabs before domestic competitors achieve 200mm SiC qualification. Defend against emerging Indian equipment integrators by pre-empting PLI scheme partnerships with Mumbai and Bengaluru fab developers.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized semiconductor ecosystem before domestic supply chains mature, targeting Czochralski puller installations for 200mm silicon pilot lines. Penetrate the lithium niobate photonics substrate segment where telecom equipment vendors seek quantum computing thermal profile adaptations. Lead with AI-assisted process control software licensing rather than capital equipment sales to compress customer qualification cycles.
For Investors and Strategic Acquirers: Magnetic fluid seal specialists with semiconductor-grade certification and installed base relationships represent the most defensible acquisition archetype. Long-term viability hinges on exposure to wide-bandgap substrate transitions rather than legacy silicon puller replacement cycles. Watch for inflection when 200mm silicon carbide defect density thresholds cross below 1 cm⁻² in commercial production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Processing | Captive supply of high-purity crucibles insulates margins from Japanese and Chinese carbon price volatility. |
| Digital Twin Platform Launch | Real-time melt interface modeling creates recurring revenue separate from hardware procurement cycles. |
| 200mm SiC Qualification Partnership | Xiamen and Hefei foundry certifications establish reference installations for regional market penetration. |
| India PLI Scheme Joint Venture | Domestic assembly partnerships with Bengaluru equipment integrators preempt tariff exposure and accelerate market entry. |
| REACH-Compliant Hot Zone Retrofit Program | European automotive power module manufacturers mandate RoHS-certified heater replacements under EU Green Deal procurement standards. |
Research Methodology
Initial hypotheses were tested against primary input from thermal process engineers at wafer fabs, procurement directors at compound semiconductor foundries, and aftermarket service managers at equipment OEMs, then refined against secondary validation from SEC 10-K filings, METI industrial statistics, MIIT capacity announcements, and customs trade data for high-purity graphite imports. Bottom-up equipment shipment tallies by product type and geography were triangulated against top-down semiconductor capital expenditure forecasts.
Variance decomposition across product type, end user tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented unit economics and capacity expansion announcements rather than aggregate demand proxies. Industry-specific forecast inputs included silicon carbide substrate diameter transition timelines and MIIT energy efficiency mandate compliance costs.
Material uncertainties — abrupt F-Gas regulatory tightening in Europe, graphite export restriction implementation in China, or 200mm SiC defect density plateauing — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology diffusion rates and customer qualification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Emergency Spill Response Market
Others
Spain Feed Additives Market
Others
Asia-Pacific Eyelash Serum Market
Others
Spain Automotive LED Lighting Market
Others
APAC Machine Vision Systems Market
Others
DIY Smart Home Market
Others
Silicone Molding Machinery Market
Others
UK 3D Printing Construction Market
Others
North America Automotive LED Lighting Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Hot Air System Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Metal Ore Mining Market
Others
South America Automotive LED Lighting Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Operator Training Simulator Market