
 Safety Instrumented System (SIS) Market | 2026-2036
Safety Instrumented System (SIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Instrumented System (SIS) Market Insights
IEC 61508 certification is redrawing competitive boundaries for safety system suppliers. Honeywell International leverages its distributed control heritage to anchor large-scale refinery projects. Emerson Electric sustains engineering intensity through embedded safety logic in its DeltaV platform. Yokogawa Electric Corporation dominates Asia-Pacific process industries with SIL-certified field instruments.
A safety instrumented system comprises sensors, logic solvers, and final control elements engineered to achieve specified safety integrity levels for risk reduction in hazardous processes. Emergency shutdown systems represent the most mature product category with established replacement cycles, while safety PLC architectures capture expanding margin pools as facilities consolidate discrete and process safety under unified platforms. Oil and gas end users generate the largest absolute demand, though pharmaceutical facilities are expanding SIS scope driven by batch process containment requirements.
OSHA process safety management rules, EPA risk management program mandates, and IEC 61511 functional safety standards collectively shape product specifications and procurement qualification. The EU AI Act introduces emerging compliance dimensions for machine-learning-based anomaly detection in safety loops. Stakeholders must monitor how cybersecurity overlays on functional safety reshape system architecture and vendor qualification criteria.
Market Dynamics
Consolidation of discrete and process safety architectures under unified programmable logic platforms is compressing procurement cycles and elevating vendor qualification barriers across hazardous process industries.
Growth Catalysts
- IEC 61511 mandates:European and North American regulators enforce functional safety compliance, forcing replacement of obsolete relay-based systems with certified safety PLCs in legacy refineries and chemical plants.
- Upstream oil and gas expansion:Offshore platform electrification and shale processing facility buildouts in the United States generate concentrated demand for SIL-rated emergency shutdown systems.
- Cybersecurity overlay requirements:NERC CIP and IEC 62443 standards compel integrated safety and security architectures, expanding scope for vendors with dual-certification capabilities.
Market Restraints
- Semiconductor input volatility:Safety PLC manufacturing depends on industrial-grade microcontrollers and isolated analog-to-digital converters subject to allocation constraints and price swings.
- Specialized engineering labor scarcity:Functional safety certification for TÜV Rheinland or exida requires scarce expertise, extending project timelines and inflating implementation costs.
- Proprietary protocol lock-in:Major automation vendors maintain closed communication stacks, creating switching costs that deter multi-vendor architectures and limit buyer negotiation leverage.
Strategic Opportunities
- Pharmaceutical batch containment:Sterile processing facilities in Germany and Switzerland are expanding SIS scope beyond traditional chemical hazards to include biological containment integrity.
- EU AI Act compliance:Machine-learning-based anomaly detection in safety loops creates new certification service revenue streams for testing laboratories and system integrators.
- Modular skid integration:Pre-engineered process units for hydrogen and carbon capture applications demand compact, pre-certified safety packages that bypass field engineering bottlenecks.
Industry Challenges
- SIL verification complexity:Proof testing intervals and failure rate calculations for diverse sensor technologies strain maintenance organizations and compliance documentation systems.
- Legacy DCS integration friction:Brownfield installations require protocol gateways and engineering overlays to bridge decades-old control platforms with modern safety architectures.
- Cyber-physical attack surface expansion:Network-connected safety systems introduce new failure modes that functional safety standards did not originally anticipate, complicating risk assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Instrumented System (SIS) Market |
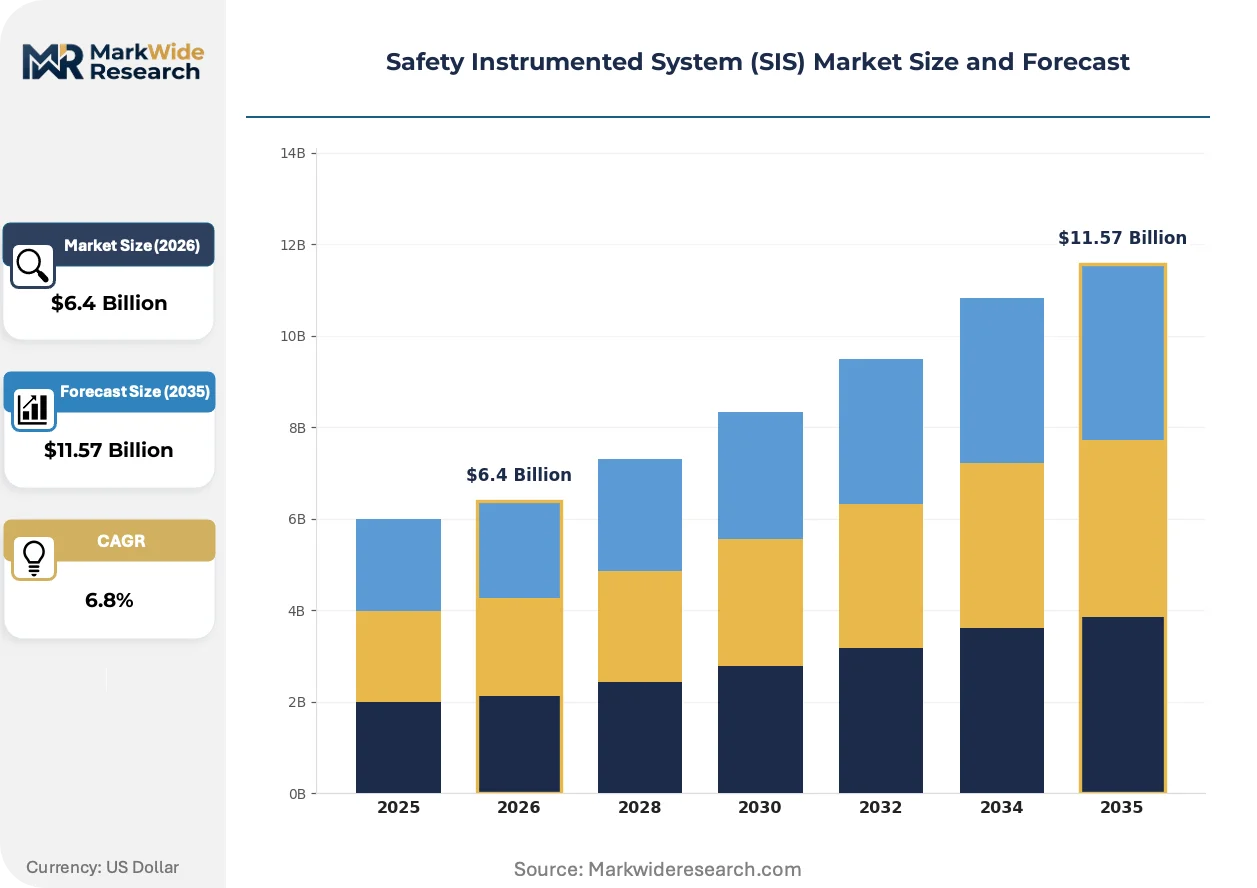
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Shutdown System, Fire & Gas Monitoring System, Process Control System, Safety PLC End User: Oil & Gas, Chemical, Power Generation, Pharmaceuticals Technology: Software Solutions, Sensor Technology, Smart Instrumentation, Control Systems Application: Process Safety, Industrial Automation, Hazard Detection, Regulatory Compliance |
| Companies Covered | Honeywell International, Emerson Electric, Schneider Electric, Siemens AG, Rockwell Automation, Yokogawa Electric Corporation, ABB Ltd., HIMA, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Instrumented System (SIS) Market Trends and Innovations
Digital twin technology and machine learning inference at the edge are redefining how safety systems validate operational states and predict instrument degradation before functional failure occurs.
WirelessHART and ISA100.11a sensor networks are miniaturizing field device footprints while eliminating conduit and cable tray infrastructure in hazardous area classifications. Offshore platform operators in the North Sea and Gulf of Mexico are piloting these architectures to reduce topside weight and accelerate commissioning schedules. The shift is compressing traditional hardwired installation timelines and enabling retrofits in space-constrained brownfield facilities.
The EU AI Act introduces conformity assessment obligations for machine-learning components embedded in safety loops, requiring documented training data provenance and algorithmic transparency. Chemical manufacturers operating under SEVESO III directives must now reconcile functional safety certification with emerging AI governance frameworks. German process industries are responding by segregating deterministic safety logic from probabilistic anomaly detection in separate hardware layers.
Buyer organizations are unbundling hardware procurement from lifecycle service contracts, creating direct commercial relationships with specialized safety engineering consultancies. This disintermediation pressures traditional automation vendors who historically captured margin through bundled maintenance agreements. The pattern is most pronounced among independent refiners in the United States seeking exida-certified verification services separate from original equipment supplier channels.
Safety Instrumented System (SIS) Market Segmentation
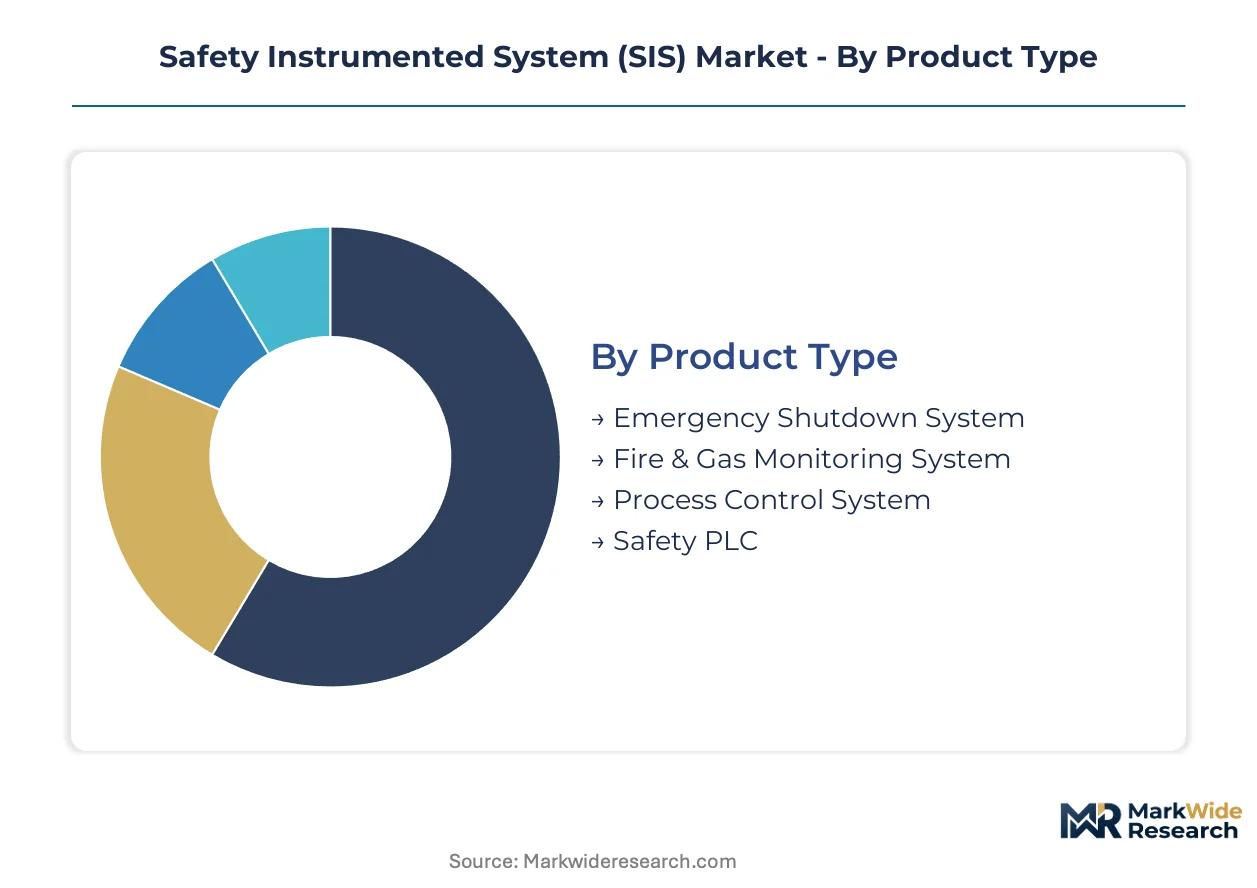
Segmentation in the Safety Instrumented System market reveals distinct procurement patterns across product architectures, end-user risk profiles, and technology integration levels. Buyers prioritize certified safety integrity levels over hardware cost, creating tiered vendor qualification barriers that reshape competitive positioning.
Product Type:
Emergency shutdown systems face accelerating substitution pressure from integrated safety PLC platforms that consolidate discrete protection functions under unified programmable architectures.
- Emergency Shutdown System:Hardwired relay and solid-state trip circuits engineered for SIL 3-rated isolation of hazardous energy sources. Demand concentrates in United States Gulf Coast refineries where OSHA process safety management mandates force replacement of obsolete pneumatic trip systems.
- Safety PLC:Certified programmable controllers executing safety logic with diagnostic coverage exceeding 99 percent per IEC 61508 requirements. German chemical manufacturers in Ludwigshafen and Leverkusen drive specification intensity as they consolidate legacy burner management and compressor protection under single-platform architectures.
- Fire & Gas Monitoring System:Point and open-path detectors with voting logic for combustible and toxic gas release scenarios.
- Process Control System:Basic process control systems with safety instrumented function overlays in hybrid configurations.
Emergency shutdown systems retain volume leadership; Safety PLC holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive greenfield projects from brownfield retrofit budgets, with oil and gas operators commanding premium specification authority.
- Oil & Gas:Upstream offshore platforms and downstream refining complexes requiring SIL-rated protection against hydrocarbon release scenarios. United States shale processing facilities in the Permian Basin generate concentrated demand for compact safety packages that withstand arid temperature cycling.
- Pharmaceuticals:Sterile batch processing suites requiring biological containment integrity beyond traditional chemical hazard protection. Swiss facilities in Basel and German operations in Sinsheim expand SIS scope to include cleanroom pressure differential monitoring under EU GMP Annex 1 revisions.
- Chemical:Continuous and batch processing plants with SEVESO III directive compliance obligations.
- Power Generation:Turbine protection and boiler control systems in conventional and nuclear facilities.
Oil and gas commands the largest procurement budgets; pharmaceuticals is expanding most quickly as containment requirements broaden.
Technology:
Application context determines technology selection, with hazardous area classifications dictating sensor architecture and communication protocol choices.
- Sensor Technology:Pressure, temperature, level, and flow transmitters with HART or Foundation Fieldbus diagnostics for predictive maintenance integration. North Sea offshore operators pilot WirelessHART architectures to eliminate cable tray weight and accelerate commissioning schedules.
- Smart Instrumentation:Devices with embedded edge computing for partial stroke testing and device verification without process interruption. Japanese process industries under METI energy efficiency directives specify these for reduced manual proof testing labor.
- Control Systems:Safety-certified controllers with redundant processor architectures.
- Software Solutions:Lifecycle management platforms for safety requirement specification and verification documentation.
Sensor technology anchors installed base volumes; smart instrumentation is gaining share fastest through predictive capability integration.
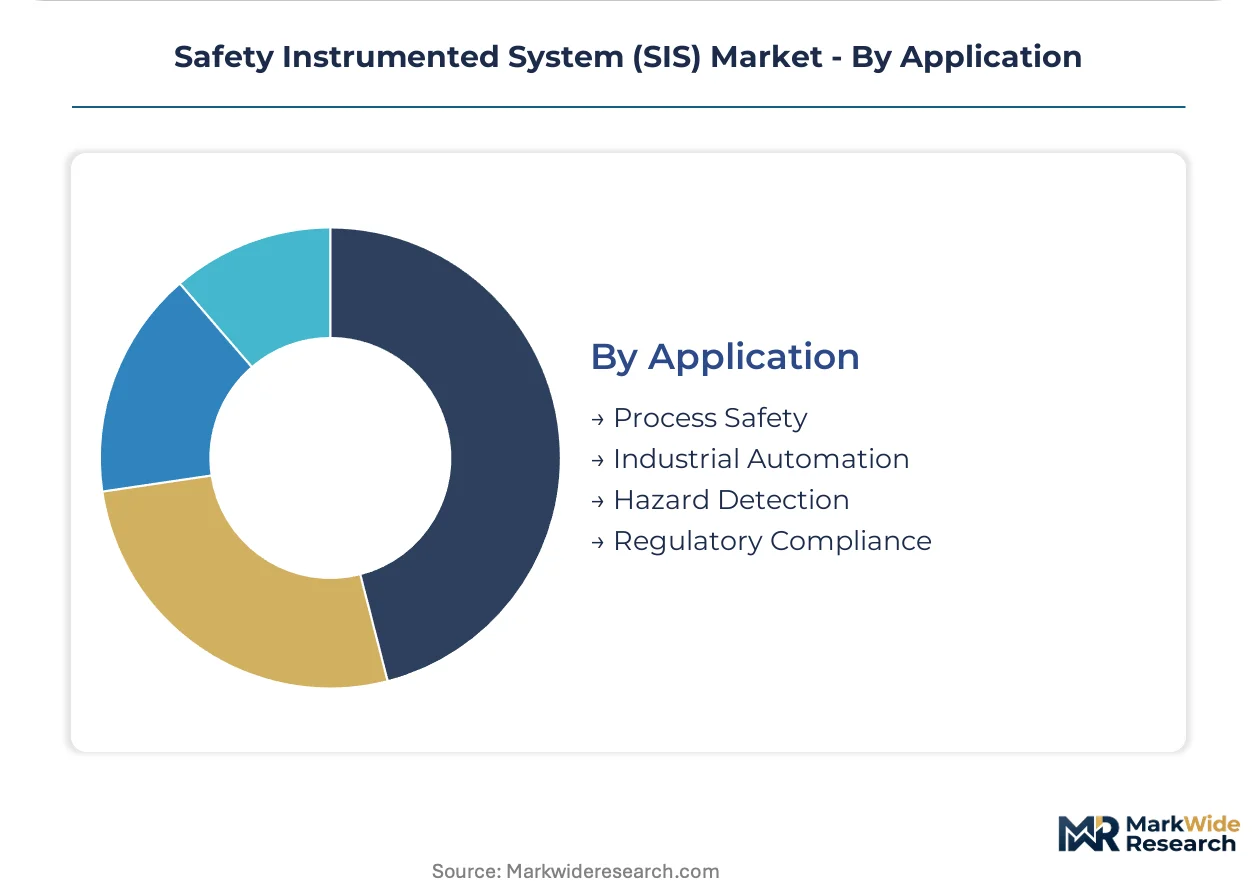
Application:
Customer type segmentation separates owner-operators with internal engineering capability from project developers relying on system integrator partnerships.
- Process Safety:Risk reduction systems engineered to achieve target safety integrity levels for specific hazardous events. Independent United States refiners in Texas and Louisiana drive demand for exida-certified verification services separate from original equipment supplier channels.
- Regulatory Compliance:Systems mandated under IEC 61511, OSHA PSM, or EPA RMP with documented proof testing records. Chinese chemical clusters under MEE environmental enforcement accelerate replacement cycles for pre-2010 relay-based installations.
- Industrial Automation:Integration of safety and basic process control under unified operator interfaces.
- Hazard Detection:Early warning systems for gas release, fire, or structural failure scenarios.
Process safety retains specification authority; regulatory compliance is climbing the fastest as enforcement intensifies across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA process safety management enforcement and IEC 61511 compliance deadlines are forcing replacement cycles across mature industrial economies. Emerging economies under MEE and SEVESO III directives accelerate greenfield specification intensity.
United States
Permian Basin shale processing facilities demand compact SIL-rated packages for arid temperature cycling. EPA risk management program mandates drive documented proof testing records at Texas and Louisiana refineries. Gulf Coast petrochemical clusters replace obsolete pneumatic trip systems with certified safety PLCs.
Germany
Ludwigshafen and Leverkusen chemical manufacturers consolidate legacy burner management under single-platform architectures. EU AI Act conformity assessment obligations reshape machine-learning component certification. BASF-anchored Rhine-Neckar industrial region pilots segregated deterministic safety logic layers.
China
MEE environmental enforcement accelerates replacement of pre-2010 relay-based installations in chemical clusters. Dual carbon goals drive hydrogen and carbon capture facility buildouts requiring modular skid safety packages. Yangtze River Delta process industries specify WirelessHART architectures to reduce installation timelines.
Japan
METI energy efficiency directives specify smart instrumentation for reduced manual proof testing labor. Chubu region process manufacturers anchor demand for embedded edge computing devices. Nagoya industrial corridor leads partial stroke testing adoption without process interruption.
Switzerland
Swissmedic and EU GMP Annex 1 revisions expand SIS scope to cleanroom pressure differential monitoring. Basel sterile processing facilities require biological containment integrity beyond chemical hazard protection. Sinsheim pharmaceutical operations drive batch containment specification intensity.
Safety Instrumented System (SIS) Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and vertical integration breadth. The vendor base stratifies into three tiers: diversified automation conglomerates with distributed control heritage, safety-focused specialists with TÜV-certified portfolios, and emerging digital-native entrants with edge-computing capabilities. Dominant competitive moves include strategic partnerships for AI-enabled anomaly detection and geographic expansion through modular skid pre-certification.
Within the diversified automation tier, Honeywell International and Emerson Electric exemplify platform consolidation strategies that embed safety logic within unified control architectures. Yokogawa Electric Corporation occupies a distinct position as a Asia-Pacific-anchored specialist with SIL-certified field instrument depth. These three entities represent contrasting archetypes: the North American full-line supplier, the integrated safety-process platform vendor, and the regional instrument-dominated player.
| Leading Market Players |
|---|
| Honeywell International |
| Emerson Electric |
| Schneider Electric |
| Siemens AG |
| Rockwell Automation |
| Yokogawa Electric Corporation |
| ABB Ltd. |
| HIMA |
| Baker Hughes |
| Others |
Pricing and Supply Chain Analysis
Solid-state relay substitution for electromechanical trip circuits redraws procurement economics as German and Japanese component suppliers capture premium positioning while Chinese manufacturers compress mid-tier price bands through scaled microcontroller integration.
Pricing Analysis
Certification level (IEC 61508 SIL-grade) creates the primary spread between premium safety PLC architectures and commodity emergency shutdown modules. Project-based contracting dominates, with TÜV Rheinland certification adding substantial engineering overhead that least price-sensitive oil and gas majors absorb while independent refiners gravitate toward pre-certified skid packages. Cost compression in standard-tier sensor assemblies is intensifying because semiconductor allocation constraints force vendors to prioritize high-margin logic solver production.
Supply Chain Analysis
Germany and Japan anchor precision analog-to-digital converter fabrication for safety-certified instruments, while China dominates isolated power supply module assembly. Industrial-grade microcontrollers draw from Taiwan and South Korea foundries, creating single-source vulnerability around automotive-qualified silicon nodes. Distribution runs through authorized system integrator channels that bundle field engineering with hardware procurement, limiting direct OEM access for smaller facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as pharmaceutical batch containment requirements splinter historically unified chemical-process safety specifications, creating certification niches beyond traditional hydrocarbon applications.
For Market Incumbents: Secure SIL 3 certification depth in wireless sensor architectures before emerging digital-native entrants achieve TÜV endorsement. Backward integration into industrial-grade microcontroller supply buffers semiconductor allocation volatility that threatens project delivery timelines. Channel control through captive engineering consultancies defends margin pools against disintermediation by independent verification specialists.
For New Entrants and Emerging Players: TÜV Rheinland fast-track partnerships for machine-learning anomaly detection modules open pharmaceutical cleanroom applications where incumbent automation vendors lack AI governance expertise. White-space concentration centers on Swiss and German sterile processing facilities expanding biological containment scope under EU GMP Annex 1 revisions. Go-to-market leverage rests on pre-certified modular skid packages that bypass field engineering bottlenecks plaguing traditional project delivery.
For Investors and Strategic Acquirers: Capital is best deployed toward safety engineering consultancies with exida-certified verification capabilities that capture margin migration from bundled OEM maintenance contracts. Long-term viability favors specialists with dual IEC 62443 cybersecurity and IEC 61508 functional safety credentials as regulatory overlays converge. Watch EU AI Act enforcement intensity as inflection indicator for machine-learning safety component demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Combined IEC 61508 and IEC 62443 credentials unlock integrated safety-security procurement budgets at NERC CIP-regulated utilities. |
| Modular Skid Pre-certification | Pre-engineered safety packages accelerate hydrogen facility commissioning timelines under China's dual carbon goals. |
| Edge Computing Partnership | Embedded partial stroke testing devices reduce manual verification labor for METI-directed Japanese process manufacturers. |
| Pharmaceutical Containment Expansion | Biological integrity monitoring captures Swissmedic-enforced cleanroom specification intensity beyond chemical hazard scope. |
| WirelessHART Architecture Pilot | Eliminated cable infrastructure reduces topside weight for North Sea offshore platform electrification projects. |
Research Methodology
The analysis maps emergency shutdown systems, safety PLC architectures, fire and gas monitoring, and smart instrumentation segments, each validated through safety engineering directors, TÜV certification specialists, pharmaceutical facility engineers, and system integrator procurement leads. Primary interview intelligence triangulates against IEC 61511 implementation filings, EPA risk management program enforcement records, SEVESO III directive compliance databases, and customs trade data for safety-certified instrument imports. Bottom-up installed base estimates reconcile with top-down end-use industry capital expenditure patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-user risk profile, safety integrity level tier, and regional regulatory enforcement intensity. CAGRs derive from replacement cycle analysis of relay-based legacy systems and greenfield specification rates for unified safety-process platforms. Forecast inputs incorporate semiconductor allocation constraints and functional safety engineering labor availability.
Decision-makers should treat outputs as directional under assumptions of sustained IEC 61511 enforcement and stable industrial microcontroller supply; material deviation in either would warrant model refresh. Specific risks include EU AI Act implementation delays and cybersecurity overlay standard fragmentation. Recalibration cycles align with material shifts in regulatory enforcement intensity and semiconductor supply normalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Tobacco Market
Others
Bird Food Market
Others
Spinner Flask Market
Others
Global Military Apparel Market
Others
Tanned Fish Skin Leather Market
Others
Ceramic Machinery Market
Others
High Voltage Measuring Equipment Market
Others
Super Computer Market
Others
APAC Smart Home Market
Others
Air Separation Plant Market
Others
Augmented Reality in Energy and Utilities Market
Others
Brazil Cane Sugar Market
Others
Global ESD Protection Devices Market
Others
North America IT Device Market
Others
United States Bean Bags Market
Others
Global Digital Market