
 Global Military Apparel Market | 2026-2036
Global Military Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Apparel Market Outlook
Special Forces procurement is bifurcating from conventional branch purchasing as units demand mission-adaptive systems with integrated load-bearing architecture. Crye Precision dominates technical garment development through its proprietary stretch-panel designs and direct-to-operator sales channel. Propper International sustains volume contracts across multiple service branches via its long-standing Defense Logistics Agency relationships. Jihua Group anchors Asian supply through captive textile mills and state-directed military modernization programs in China.
Military apparel encompasses combat-ready garments engineered to ballistic protection standards, moisture-wicking base layers, and flame-resistant fabrics treated with NIR-signature management coatings for multispectral concealment. The category serves force protection, operational endurance, and identity differentiation across land, maritime, and air domains. Tactical Gear commands premium margins as Special Forces units specify modular plate carriers and scalable equipment architectures. Uniforms remain the volume foundation but face margin compression from cotton-blend standardization across conscript forces. Kevlar-reinforced segments attract R&D concentration as manufacturers integrate soft-armor panels directly into garment substrates rather than external vests.
FDA textile flammability standards intersect with NHTSA material testing protocols for military vehicle crew garments in the United States, while REACH chemical restrictions in Europe constrain certain dye and finish chemistries used in camouflage treatments. The EU AI Act introduces emerging compliance dimensions for smart-textile garments with embedded biometric monitoring. Stakeholders must monitor how dual-use export control expansions affect cross-border component flows for advanced fabric technologies.
Market Dynamics
NATO technical requirement revisions are fragmenting procurement pathways between conventional forces and Special Forces units, forcing suppliers to maintain dual certification tracks for flame-resistant fabrics and NIR-signature management systems.
Growth Catalysts
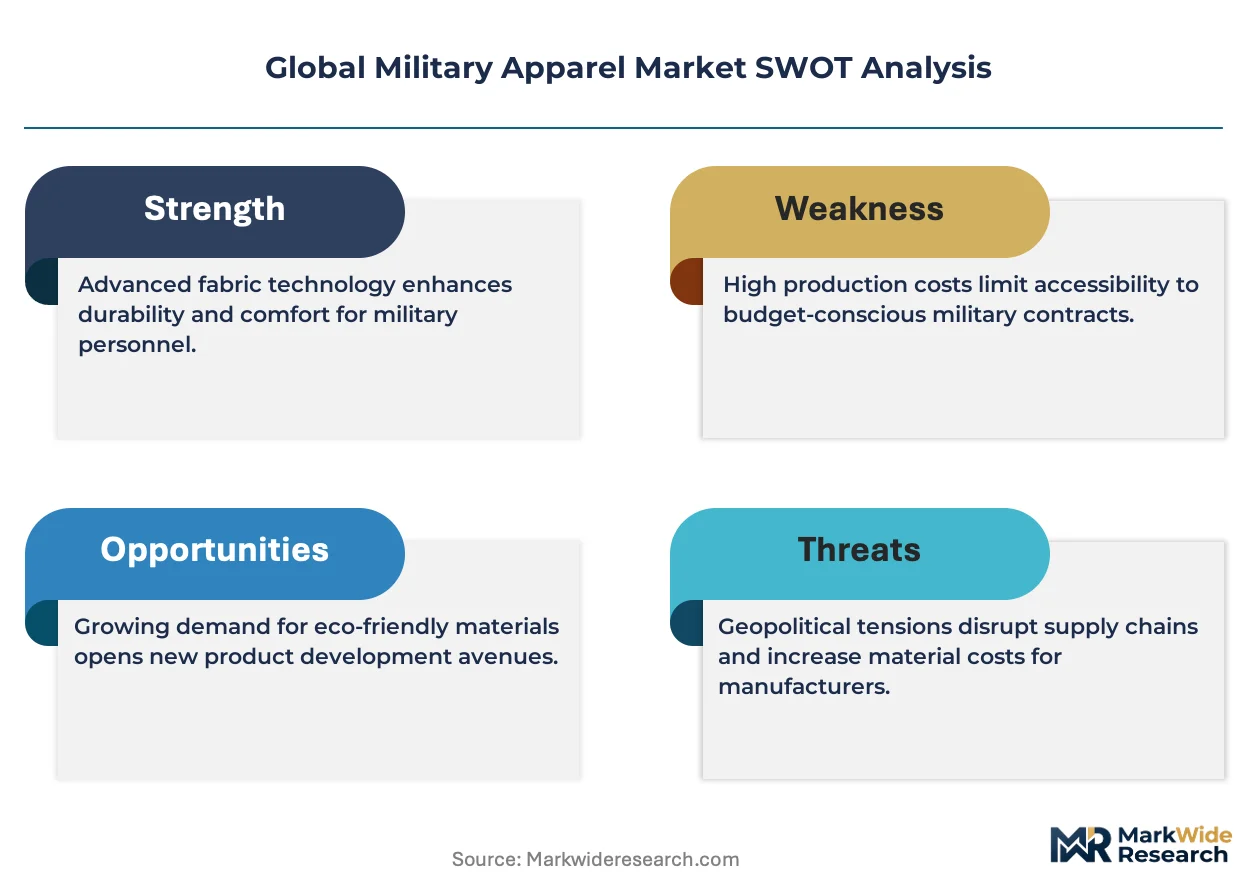
- REACH chemical compliance expansion:European ECHA restrictions on legacy dye chemistries are accelerating substitution toward bio-based finishes that simultaneously satisfy NIR-concealment protocols.
- Multi-year uniform replacement cycles:Pentagon sustainment budgets under the US Defense Logistics Agency create predictable demand anchors for domestic textile contractors.
- Kevlar substrate integration:Soft-armor panel embedding directly into garment layers eliminates external vest dependency for vehicle crews and dismounted operators.
Market Restraints
- Aramid fiber supply concentration:DuPont and Teijin control 70%+ of para-aramid raw material, exposing finished goods producers to input price volatility and allocation rationing.
- Dual-use export control expansion:US Commerce Department Entity List restrictions complicate cross-border component flows for advanced ballistic fabric technologies.
- Cotton-blend standardization:Conscript forces in price-sensitive jurisdictions favor basic cotton-polyester mixes that compress margins for technical garment specialists.
Strategic Opportunities
- Smart-textile biometric integration:EU AI Act compliance frameworks create first-mover advantage for manufacturers embedding physiological monitoring without triggering algorithmic transparency mandates.
- India defense indigenization:Ministry of Defence Make-in-India procurement preferences open captive demand for domestic producers meeting BIS textile standards.
- Direct-to-operator channels:Special Forces units bypassing traditional defense procurement are creating premium bypass markets for mission-adaptive kit configurations.
Industry Challenges
- NIR-signature certification timelines:Multispectral concealment testing protocols require 18-24 month validation cycles that delay product commercialization.
- Flame-resistant chemistry workforce scarcity:Specialized textile finishing expertise concentrates among aging technicians in US and European mill operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Apparel Market |
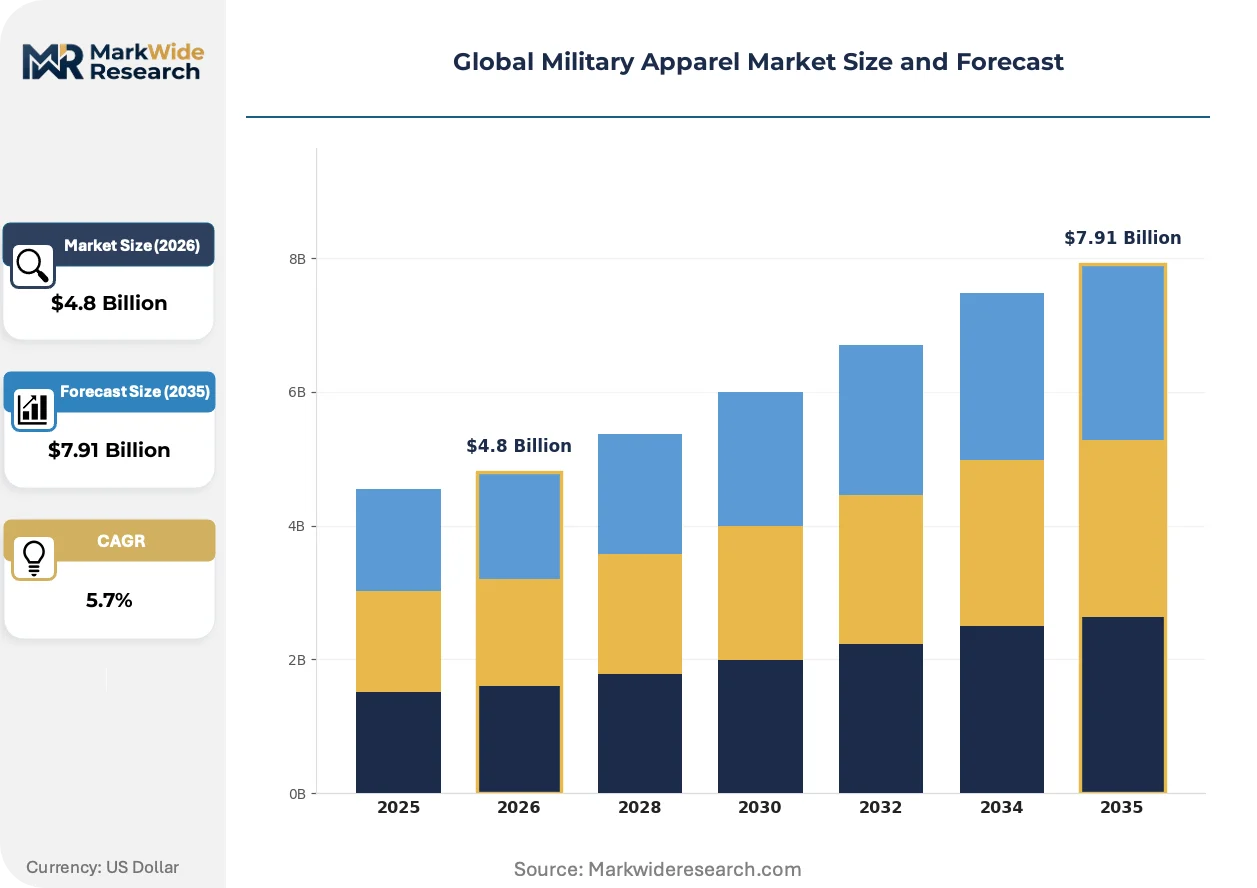
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uniforms, Tactical Gear, Footwear, Accessories End User: Army, Navy, Air Force, Special Forces Material: Cotton Blend, Polyester, Kevlar, Ripstop Fabric Distribution Channel: Contractors, Retail, Online, Direct Sales |
| Companies Covered | Crye Precision, Propper International, 5.11 Tactical, UF PRO, TRU-SPEC, Helikon-Tex, Jihua Group, Wyedean, NFM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Apparel Market Strategic Shifts
Technical garment architecture is converging with wearable systems engineering, as fabric substrates become platforms for power distribution, sensor integration, and thermal management rather than passive protection layers.
Stretch-panel load-bearing systems are supplanting traditional MOLLE webbing configurations in Special Forces kit designs. Crye Precision and comparable technical developers specify integrated suspension mechanics that redistribute plate carrier weight across the shoulders and hips. This construction methodology is compressing demand for standalone tactical belts and external harness systems.
EU AI Act algorithmic transparency requirements are forcing recalibration of smart-textile development roadmaps. Manufacturers embedding biometric monitoring must now document decision logic for health-alert triggering, adding compliance overhead to R&D budgets. German and French defense procurement offices are issuing preliminary guidance that favors simpler sensor architectures with localized processing over cloud-dependent analytics.
Unit-level purchasing authority is displacing centralized defense procurement for tactical apparel in NATO special operations commands. Individual operators and team leaders now specify mission-adaptive configurations through discretionary equipment allowances, fragmenting volume concentration that previously favored single-source national contracts. This pattern is most pronounced in US Army Special Forces and British Special Air Service regimental supply chains.
Global Military Apparel Market Segmentation
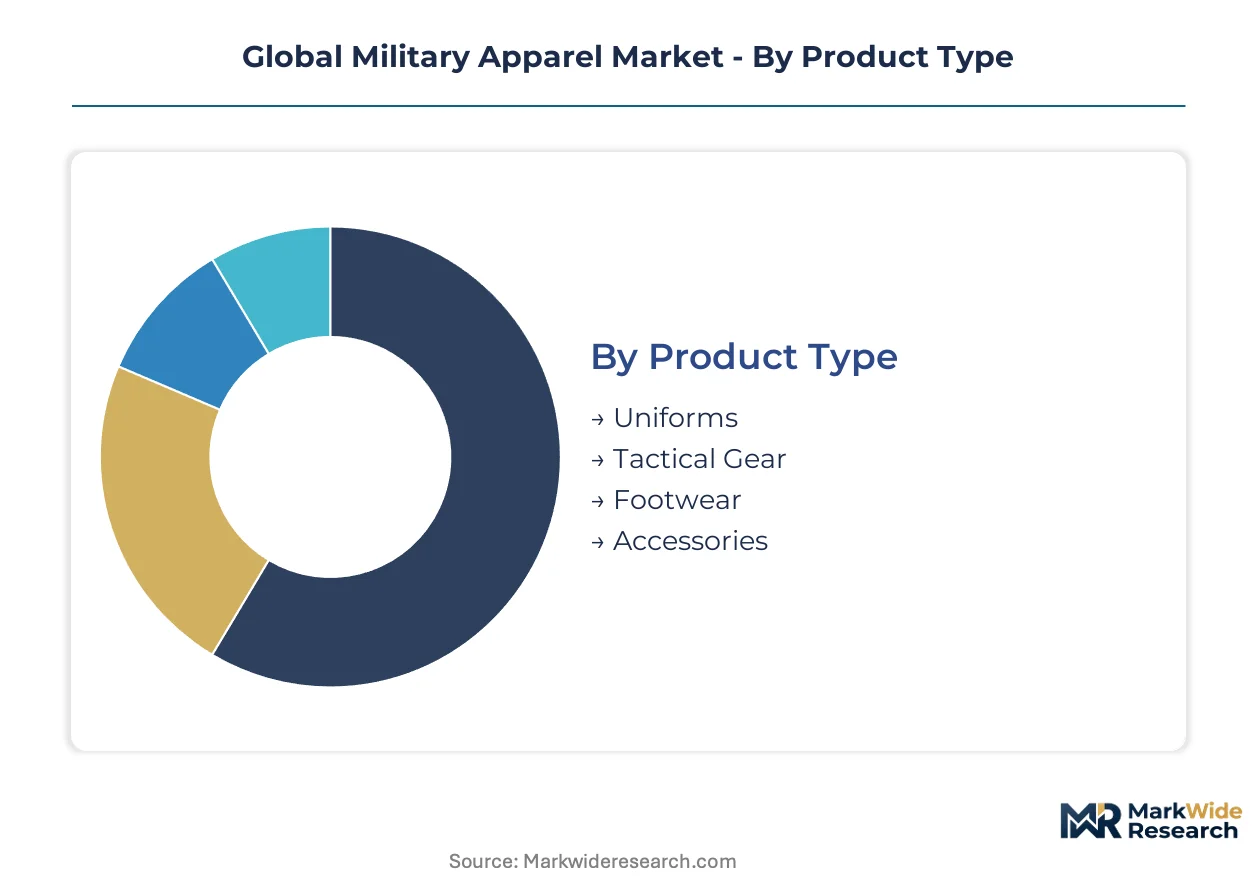
Military apparel segmentation tracks how procurement authority, material specifications, and distribution access determine margin capture across force structures. Technical garment categories concentrate value in mission-adaptive configurations, while volume flows through standardized uniform programs.
Product Type:
Premium margins pool in modular load-bearing systems where Special Forces units specify integrated architectures rather than discrete components.
- Uniforms:Cotton-polyester and flame-resistant fabric assemblies form the procurement foundation for conventional forces. Pentagon multi-year replacement cycles under Defense Logistics Agency contracts anchor volume demand in the United States, though margin compression from cotton-blend standardization limits profitability for technical specialists.
- Tactical Gear:Plate carriers, scalable equipment architectures, and integrated suspension mechanics command price premiums through direct-to-operator channels. Crye Precision stretch-panel designs redistribute weight across shoulders and hips, displacing standalone MOLLE webbing configurations in NATO special operations procurement.
- Footwear:Combat boots engineered to moisture-wicking and ankle-stability specifications serve dismounted operations across varied terrain.
- Accessories:Gloves, balaclavas, and load-bearing pouches complete mission-adaptive kit configurations.
Uniforms hold installed capacity. Tactical Gear is rotating up the share rankings.
End User:
Procurement fragmentation accelerates where unit-level purchasing authority displaces centralized defense contracts.
- Special Forces:Mission-adaptive systems with integrated biometric monitoring and NIR-signature management coatings attract R&D concentration. EU AI Act compliance frameworks for smart-textile algorithmic transparency are recalibrating development roadmaps in Germany and France toward localized sensor processing.
- Army:Volume concentration in land forces sustains predictable demand for flame-resistant fabrics and ballistic protection standards, though conscript forces in price-sensitive jurisdictions favor basic cotton-polyester mixes.
- Navy:Maritime-domain garments emphasize moisture management and salt-corrosion resistance for extended vessel deployments.
- Air Force:Flight suits and vehicle-crew garments intersect with NHTSA material testing protocols and FDA textile flammability standards in the United States.
Army maintains volume dominance. Special Forces is expanding most quickly through discretionary equipment allowances.
Material:
Input cost volatility concentrates in para-aramid supply chains where DuPont and Teijin control raw material allocation.
- Kevlar:Soft-armor panel embedding directly into garment substrates eliminates external vest dependency for vehicle crews. REACH chemical restrictions on legacy finish chemistries are accelerating substitution toward bio-based alternatives that satisfy NIR-concealment protocols.
- Ripstop Fabric:Reinforced weave constructions resist tearing in field conditions while maintaining breathability for operational endurance.
- Cotton Blend:Standardized compositions dominate conscript force procurement, compressing margins for technical garment developers.
- Polyester:Synthetic base layers provide moisture-wicking performance for extended operational timelines.
Kevlar anchors technical value. Ripstop Fabric is gaining share fastest in load-bearing applications.
Distribution Channel:
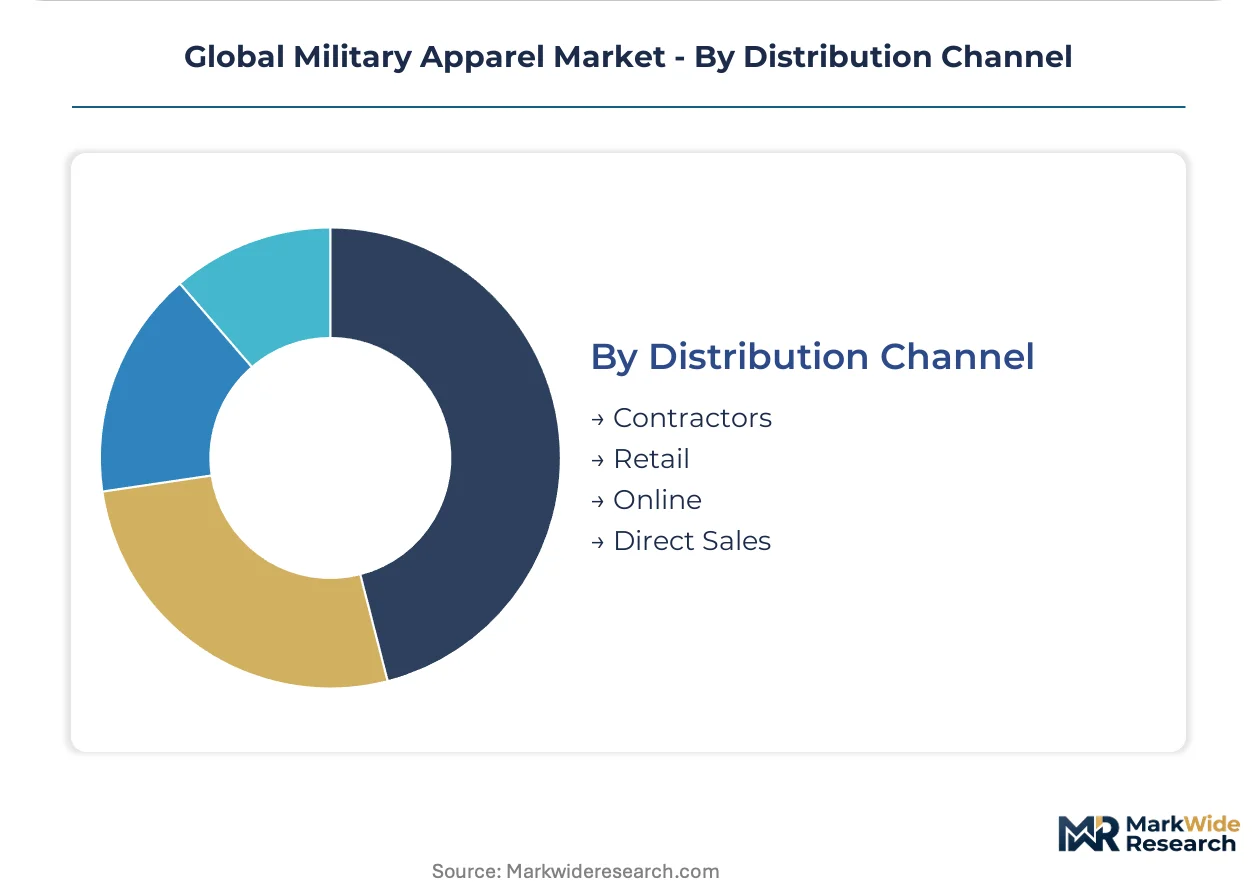
Channel selection determines certification burden and pricing autonomy across defense procurement systems.
- Contractors:Long-standing Defense Logistics Agency relationships sustain volume contracts for domestic textile producers. Dual-use export control expansions under US Commerce Department Entity List restrictions complicate cross-border component flows for advanced ballistic technologies.
- Direct Sales:Special Forces units bypass traditional procurement through discretionary allowances, creating premium bypass markets for mission-adaptive configurations.
- Retail:Commercial tactical outlets serve reserve components and private security end-uses.
- Online:Digital channels expand access for individual operators seeking specialized kit components.
Contractors hold institutional lock-in. Direct Sales is climbing the fastest as unit purchasing authority fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Charleston's military logistics infrastructure underwrites United States dominance in defense textile distribution, while NATO standardization protocols synchronize procurement across allied European forces.
United States
Pentagon multi-year uniform replacement cycles sustain predictable demand anchors through Defense Logistics Agency contracts. FDA textile flammability standards intersect with NHTSA material testing protocols for vehicle crew garments. The Carolina textile corridor spanning Charlotte to Fayetteville concentrates flame-resistant fabric finishing capacity for domestic military suppliers.
China
State-directed military modernization programs drive captive demand through Jihua Group's integrated mill operations. MIIT textile standards and GB certification requirements govern domestic procurement specifications. The Yangtze River Delta manufacturing cluster around Shanghai coordinates raw material sourcing with finished garment production for People's Liberation Army contracts.
Germany
Bundeswehr technical requirement revisions accelerate substitution toward bio-based finishes satisfying NIR-concealment protocols. REACH chemical restrictions through ECHA constrain legacy dye chemistries in camouflage treatments. The Bavarian textile belt surrounding Munich hosts specialized finishing operations for Bundeswehr flame-resistant garment contracts.
United Kingdom
British Special Air Service regimental supply chains fragment procurement through discretionary equipment allowances at unit level. Ministry of Defence procurement guidelines increasingly favor mission-adaptive configurations over standardized uniform programs. The Midlands manufacturing corridor around Birmingham retains technical weaving capacity for Ministry of Defence technical garment requirements.
India
Ministry of Defence Make-in-India procurement preferences open captive demand for domestic producers meeting BIS textile standards. Army modernization budgets prioritize indigenization of combat uniform supply chains. The Tamil Nadu textile cluster around Coimbatore expands technical finishing capacity to capture defense procurement opportunities.
Global Military Apparel Market Competitive Environment
Concentration sits with technical garment specialists serving Special Forces direct-to-operator channels alongside volume contractors maintaining Defense Logistics Agency relationships. The vendor base splits between premium mission-adaptive developers and standardized uniform producers. Three archetypes dominate: proprietary stretch-panel designers, long-standing defense agency contractors, and state-integrated textile conglomerates. Strategic moves center on dual certification tracks for NATO flame-resistant standards and NIR-signature management systems.
Within the technical specialist tier, Crye Precision and Propper International occupy distinct positioning vectors. Crye Precision exemplifies the proprietary design archetype through direct-to-operator sales channels bypassing traditional procurement. Propper International anchors the institutional contractor segment via sustained Defense Logistics Agency volume relationships. Jihua Group represents the state-integrated model, leveraging captive textile mills and directed military modernization programs.
| Leading Market Players |
|---|
| Crye Precision |
| Propper International |
| 5.11 Tactical |
| UF PRO |
| TRU-SPEC |
| Helikon-Tex |
| Jihua Group |
| Wyedean |
| NFM Group |
| Others |
Value Chain & Pricing Dynamics
Bio-based finish substitution for legacy flame-resistant chemistries is redrawing procurement geography and compressing margin structures across European and North American defense textile markets. REACH-driven chemistry transitions force simultaneous reformulation investments and certification retesting, amplifying working capital demands for mid-tier finishers while concentrating contract awards among vertically integrated compounders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments military apparel procurement. Premium tiers attach to NIR-signature certified garments with embedded soft-armor substrates, while economy tiers serve conscript forces through cotton-polyester standardization. Price differentiation hinges on certification grade and volume scale, with bulk Defense Logistics Agency contracts commanding 15-20 point discounts off list. Cost compression in standard uniform tiers is intensifying because Chinese state-directed producers leverage captive textile mills to undercut Western finishers on base fabric supply.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores petroleum-derived fiber dependency for aramid and polyester feedstocks. Raw material sourcing draws from DuPont and Teijin para-aramid operations in the United States and Japan, coupled with Chinese petrochemical complexes for polyester staple. Single-source vulnerability concentrates in Teijin's meta-aramid filament supply for vehicle-crew flame-resistant garments. Distribution runs through Defense Logistics Agency central contracting for conventional forces, while Special Forces units source through direct-to-operator channels bypassing institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs military apparel value capture as fabric substrates evolve from passive protection layers to integrated power-and-sensor distribution systems. Interoperability standards for biometric data exchange between garment-embedded monitors and squad-level tactical networks are reshaping procurement specifications across NATO special operations commands.
For Market Incumbents: Secure dual-certification tracks for NATO flame-resistant standards and NIR-signature management systems before competitor lock-in hardens. Crye Precision's direct-to-operator channel control and Propper's Defense Logistics Agency relationships demonstrate how certification moats defend against Chinese state-subsidized entrants. Backward integration into para-aramid weaving capacity insulates margin structures from DuPont-Teijin allocation rationing.
For New Entrants and Emerging Players: Lead with mission-adaptive configurations for British Special Air Service and US Army Special Forces discretionary equipment allowances, the most penetrable white-space segment. India's Ministry of Defence Make-in-India procurement preferences offer second-mover entry through BIS-certified technical finishing partnerships with Tamil Nadu textile clusters. Go-to-market execution should emphasize rapid NIR-signature certification completion to compress 18-24 month validation timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed technical garment specialists holding Crye Precision-type proprietary stretch-panel IP and direct-to-operator channel infrastructure. Long-term viability over a five-to-ten year horizon rests on smart-textile biometric integration capabilities compliant with EU AI Act algorithmic transparency mandates. Watch for Bundeswehr and Pentagon guidance shifts favoring localized sensor processing over cloud-dependent analytics as the inflection signal for platform architecture winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous NATO flame-resistant and NIR-signature validation opens Pentagon and Bundeswehr contract access. |
| Smart-Textile Platform Development | EU AI Act-compliant biometric monitoring integration positions suppliers for next-generation Special Forces procurement. |
| Direct-to-Operator Channel Buildout | Discretionary equipment allowance capture bypasses Defense Logistics Agency pricing compression for premium margins. |
| Backward Integration into Aramid Weaving | In-house para-aramid capacity reduces DuPont-Teijin supply concentration risk for vehicle-crew garment producers. |
| India Technical Finishing Partnership | Ministry of Defence Make-in-India compliance through Tamil Nadu cluster alliances secures captive modernization demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Defense Logistics Agency contracting officers, Special Forces equipment sergeants, technical textile mill managers, and flame-resistant chemistry formulators. Secondary validation drew from Pentagon budget justification documents, ECHA REACH restriction updates, EU AI Act implementation guidance, and NATO standardization office technical specifications. Bottom-up contract aggregation and top-down defense expenditure allocation models were triangulated against disclosed vendor revenue footprints.
Across the analysis window, segmentation modeling tracked product type, end user force structure, material substrate, and distribution channel authority. CAGRs were derived from defense budget trajectory analysis, replacement cycle timing, and procurement policy shift probability weighting. Forecast inputs incorporated Pentagon multi-year uniform replacement scheduling, EU chemical restriction phase-in timelines, and India defense indigenization policy implementation pacing.
Forecasts assume regulatory continuity in ECHA REACH enforcement and EU AI Act implementation; material policy shifts would require re-modeling of bio-based finish substitution rates and smart-textile compliance cost structures. Commodity price volatility in petroleum-derived fibers, para-aramid allocation disruptions, and dual-use export control expansions represent specific revision triggers. Practitioners should keep alternative scenarios live as NATO technical requirement revisions and Pentagon discretionary equipment allowance policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Australia Content Services Platform Market
Others
Edge Computing in Healthcare Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Global Sports and Fitness Wears Market
Others
Europe Military 4D Printing Market
Others
Hopper Dryers Market
Others
Storage Dewar and Dry Shipper Market
Others
Solar Animal Repellent Market
Others
Linseed Oil Market
Others
Industrial Tablet PC Market
Others
Construction Wearables Market
Others
Coriolis Meters Market
Others
Global Radar Systems Market
Others
Quadrant Scale Market
Others
Hypersensitivity Market