
 Thailand Commercial Vehicles Lubricants Market | 2026-2036
Thailand Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Commercial Vehicles Lubricants Market Analytics
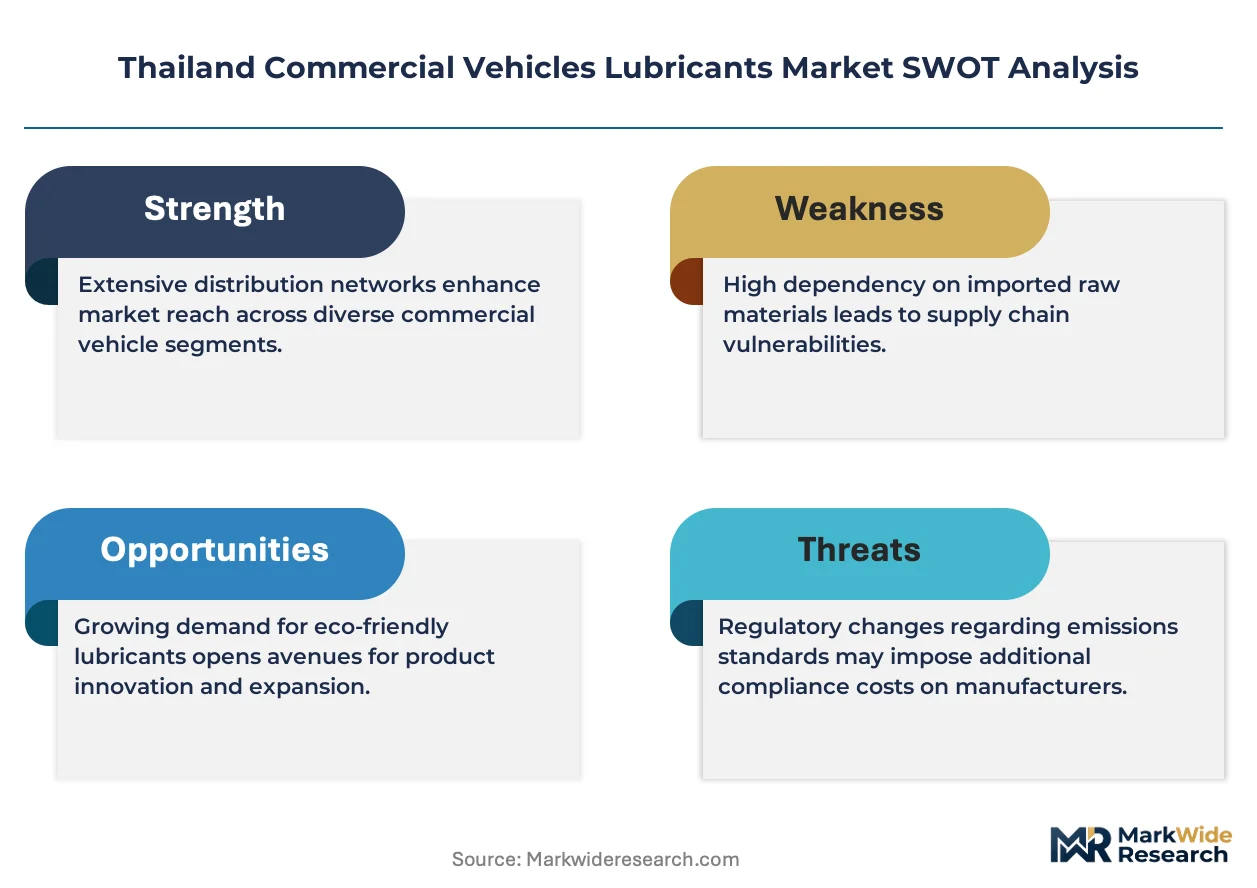
Capital intensity divergence between integrated refiners and blenders is reorganizing competitive tiers in Thailand's commercial lubricants sector. PTT Lubricants leverages captive feedstock from upstream refining to sustain margin advantages across distribution networks. Bangchak Corporation anchors its position through bio-based product development aligned with national sustainability targets. Chevron Corporation competes on technical service depth for fleet customers operating along major freight corridors.
Thailand commercial vehicles lubricants comprise formulated oils and functional fluids engineered to reduce friction, dissipate heat, and protect powertrain components under severe duty cycles, with viscosity grades typically spanning SAE 15W-40 to 10W-30 for diesel engines and incorporating API CK-4 or FA-4 performance specifications. These formulations serve the operational continuity of long-haul trucks, urban buses, and delivery fleets where drain interval extension directly lowers total cost of ownership. Engine oil commands the dominant share of product value given high consumption rates and specification complexity, while synthetic and semi-synthetic materials capture expanding share as OEM drain intervals lengthen and operating temperatures rise. Heavy-duty trucks represent the most structurally significant application segment, absorbing disproportionate volume due to extended annual mileage and severe loading profiles.
Thailand's Department of Industrial Works enforces waste oil disposal protocols under the Factory Act, while the Thai Industrial Standards Institute mandates TISI certification for lubricant quality claims, and the Department of Land Transport imposes vehicle fitness standards that indirectly condition fluid change frequencies. These regulatory layers elevate compliance costs for smaller blenders while creating specification barriers that favor technically resourced suppliers. Fleet managers and lubricant distributors must monitor evolving OEM service fill specifications and emerging carbon intensity disclosure requirements to align procurement with operational and environmental accountability demands.
Market Dynamics
Thailand's Eastern Economic Corridor freight density is compressing drain intervals and forcing specification upgrades across heavy-duty fleets, while Bangkok's logistics corridors drive preventive maintenance intensity that reshapes volume concentration and product mix requirements.
Growth Catalysts
- Extended drain interval specifications:OEM service fill requirements for API CK-4 and FA-4 performance standards are pulling synthetic and semi-synthetic formulations into mainstream fleet procurement. Heavy-duty trucks operating along Laem Chabang-Bangkok corridors absorb disproportionate volume.
- Factory Act waste oil enforcement:Thailand's Department of Industrial Works tightened disposal protocols, elevating compliance costs for informal blenders and consolidating procurement toward certified suppliers with documented chain-of-custody systems.
- Eastern Economic Corridor infrastructure buildout:Deep-sea port expansion and industrial zone clustering around Rayong and Chonburi are generating concentrated demand from new logistics entrants seeking technical service partnerships.
Market Restraints
- Base oil supply concentration:Captive feedstock access among integrated refiners limits blender margin flexibility, particularly for Group II and Group III materials where PTT Group controls domestic supply nodes.
- TISI certification timeline friction:Thai Industrial Standards Institute quality claim mandates impose 12-18 month validation cycles that freeze product launch velocity for reformulated or imported additive packages.
- Bio-based formulation cost premium:Bangchak Corporation's renewable feedstock investments face 15-25% raw material cost deltas against mineral alternatives, compressing addressable market penetration without mandate support.
Strategic Opportunities
- Underserved provincial fleet networks:Chiang Mai and Khon Kaen logistics hubs lack technical service depth, creating white space for mobile oil analysis and on-site drain interval optimization programs.
- Carbon intensity disclosure alignment:Emerging Scope 3 reporting requirements from Thai-listed conglomerates are conditioning lubricant procurement toward suppliers with verified lifecycle emissions data and renewable content certification.
- Telematics-fluid integration:Convergence of engine monitoring systems with predictive oil degradation algorithms enables condition-based maintenance contracts that bundle lubricant supply with uptime guarantees.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise for high-ash, low-SAPS diesel packages concentrates among Bangkok-based technical centers, constraining regional blender R&D scale-up.
- Legacy fleet specification fragmentation:Pre-2010 trucks operating on API CI-4 or older standards resist premium product migration, forcing parallel inventory management across incompatible viscosity and performance tiers.
- Drain interval education gaps:Owner-operator segments misinterpret OEM extension guidelines, generating premature fluid replacement that inflates apparent volume while eroding total cost of ownership credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Commercial Vehicles Lubricants Market |
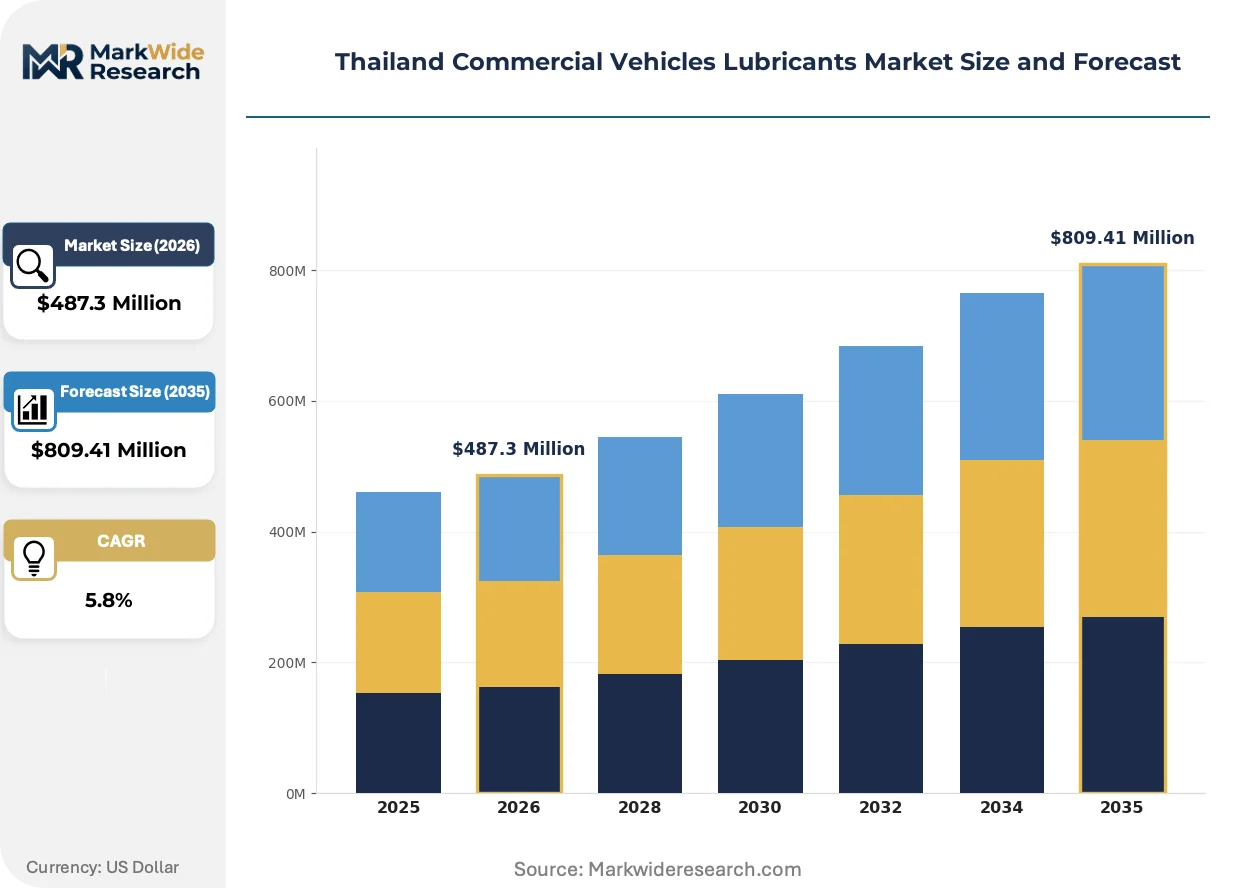
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Application: Heavy-Duty Trucks, Buses, Light Commercial Vehicles, Two-Wheelers Material: Synthetic, Mineral, Semi-Synthetic, Bio-Based Distribution Channel: Retail, Wholesalers, Direct Sales, Online |
| Companies Covered | Bangchak Corporation, PTT Lubricants, Chevron Corporation, ExxonMobil Corporation, Royal Dutch Shell Plc, BP PLC (Castrol), Idemitsu Kosan Co Ltd, Siam Pan Group Public Co Ltd, Thai Petroleum & Trading Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic base oil technology is penetrating Thailand's commercial vehicle segment through specification-driven fleet procurement, while regulatory disclosure requirements and channel restructuring compress traditional distributor roles.
Polyalphaolefin and Group III base stocks are decomposing mineral oil dominance in 15W-40 and 10W-30 heavy-duty segments. Fleet operators with centralized procurement functions are specifying synthetics for 50,000+ kilometer drain intervals. This technology shift is decomposing volume-based distributor margins and compressing the addressable market for conventional formulations.
Thailand's Department of Industrial Works Factory Act amendments imposed mandatory waste oil tracking documentation on all lubricant handlers. Industrial users must now certify disposal chain integrity or face facility operating permit suspension. Manufacturing and logistics facilities in Samut Prakan and Pathum Thani industrial zones are consolidating supplier relationships to reduce compliance audit burden.
Direct procurement from blenders is displacing traditional multi-tier distribution for large fleet accounts. Bangkok-based logistics operators with 200+ unit fleets now negotiate annual volume contracts with technical service attachments. This pattern concentrates most visibly in express delivery and cold-chain segments where uptime penalties exceed lubricant cost differentials.
Thailand Commercial Vehicles Lubricants Market Segmentation
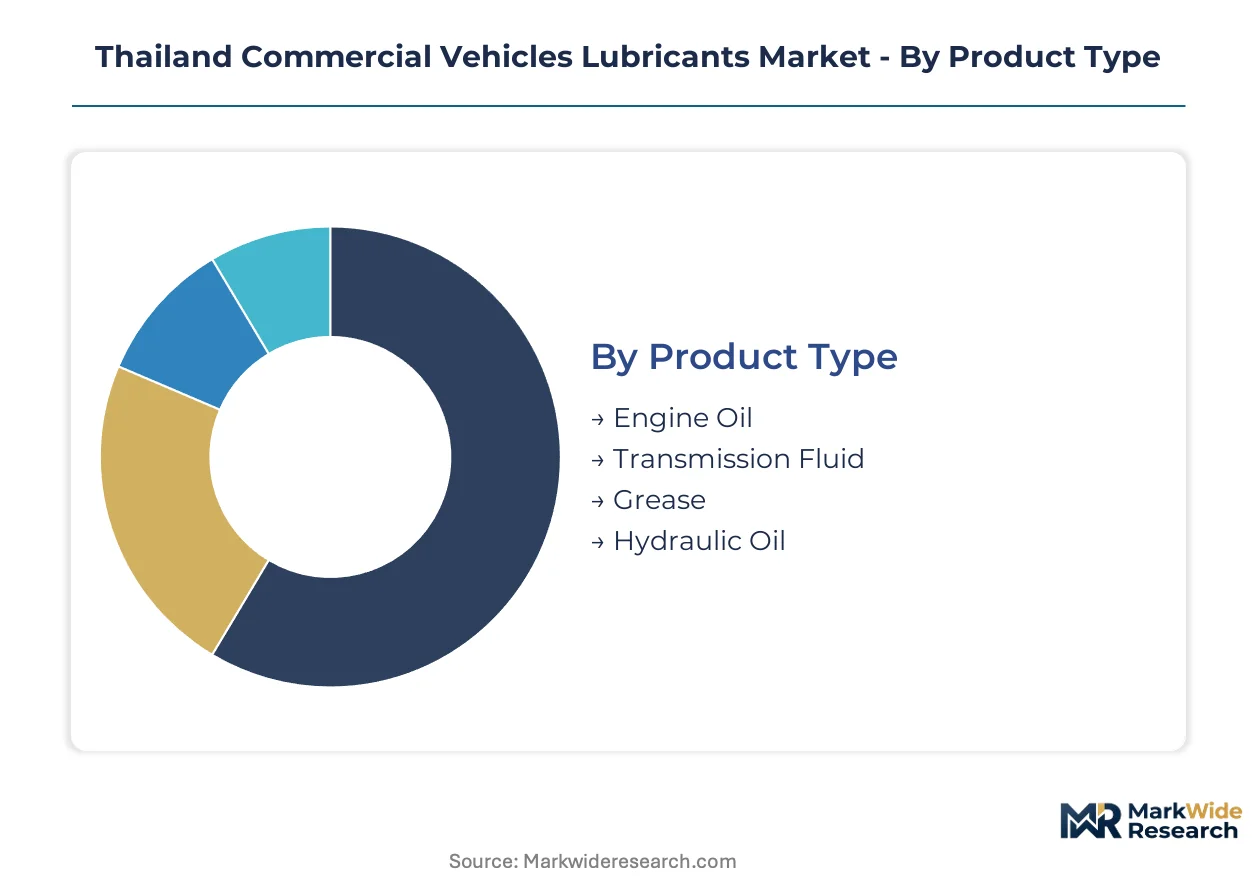
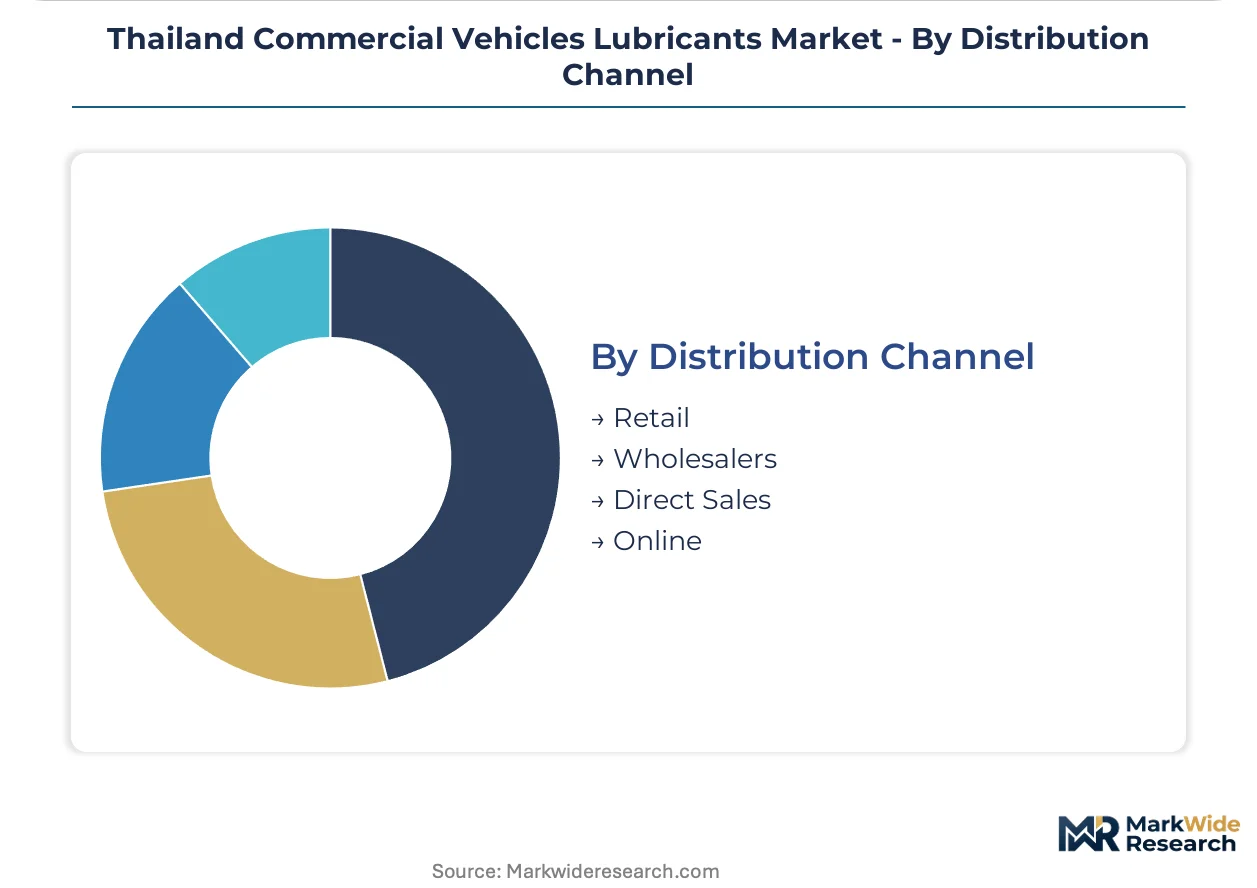
Segmentation in Thailand's commercial lubricants market reveals how specification pressures and channel economics concentrate value capture. Fleet procurement centralization and regulatory compliance requirements reshape which product categories and distribution modes absorb disproportionate margin.
Product Type:
Substitution pressure from extended drain interval technologies and fluid life monitoring systems threatens conventional formulations most acutely in high-volume categories.
- Engine Oil:Formulated lubricants meeting API CK-4 and FA-4 specifications for diesel powertrains, incorporating detergent-dispersant and anti-wear additive packages. Bangkok-based logistics fleets with centralized procurement specify synthetics for 50,000+ kilometer intervals, compressing conventional volume share.
- Transmission Fluid:Functional fluids engineered for synchronized manual and automated manual transmissions in commercial duty cycles. Heavy-duty trucks operating Laem Chabang-Bangkok corridors drive demand for OEM-approved fill specifications with documented friction durability.
- Grease:Thickened lubricants for chassis, wheel bearing, and fifth-wheel applications requiring mechanical stability under high-load, low-speed conditions.
- Hydraulic Oil:Anti-wear formulated fluids for power steering and auxiliary hydraulic systems in commercial vehicle configurations.
Engine oil retains volume leadership; transmission fluid holds the steepest expansion curve.
Application:
Cost tier stratification separates premium synthetic adoption from mineral-based volume procurement across fleet ownership structures.
- Heavy-Duty Trucks:Class 8 and regional haul vehicles absorbing disproportionate lubricant volume through extended annual mileage and severe loading profiles. Eastern Economic Corridor freight density compresses drain intervals and forces specification upgrades among logistics entrants.
- Buses:Urban and intercity passenger transport with high-idle operational patterns driving thermal stress on lubricant formulations.
- Light Commercial Vehicles:Pickup trucks and delivery vans with fragmented owner-operator ownership resisting premium product migration.
- Two-Wheelers:Commercial motorcycle fleets for last-mile delivery with high consumption frequency but price-sensitive procurement.
Heavy-duty trucks dominate absolute volume; light commercial vehicles face the sharpest margin compression from specification fragmentation.
Material:
Supply concentration around Group II and Group III base stocks conditions blender access and margin structure across formulation tiers.
- Synthetic:Polyalphaolefin and Group III base stocks enabling 50,000+ kilometer drain intervals. Fleet operators with technical service partnerships specify synthetics for total cost of ownership optimization.
- Mineral:Solvent-refined Group I base oils serving price-sensitive segments and legacy fleet specifications resistant to premium migration.
- Semi-Synthetic:Blended formulations capturing mid-tier procurement with partial performance benefits at moderated cost deltas.
- Bio-Based:Renewable feedstock formulations aligned with national sustainability targets but facing 15-25% raw material cost premiums without mandate support.
Mineral formulations retain volume leadership; bio-based materials face the steepest adoption constraints from cost structure.
Distribution Channel:
Customer type stratification separates enterprise fleet direct procurement from fragmented retail and service station volume.
- Direct Sales:Annual volume contracts with technical service attachments negotiated by Bangkok-based logistics operators with 200+ unit fleets. Condition-based maintenance bundles displace transactional purchasing in express delivery and cold-chain segments.
- Wholesalers:Regional distributors serving provincial fleet networks with inventory aggregation and credit terms.
- Retail:Service stations and automotive workshops capturing owner-operator and small fleet procurement with immediate availability.
- Online:Emerging platform-based procurement for standardized specifications with transparent pricing and documented chain-of-custody compliance.
Direct sales channels gain share fastest; retail retains volume leadership in fragmented ownership segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Bangkok's logistics corridors while provincial markets absorb margin compression from fragmented procurement. Thailand's sub-regional lubricant demand clusters around freight density gradients and industrial zone proximity.
Bangkok Metropolitan Region
Fleet centralization in Bangkok drives synthetic specification adoption through 200+ unit operators negotiating direct contracts. The Department of Industrial Works enforces Factory Act waste oil documentation across Samut Prakan and Pathum Thani industrial zones. Express delivery and cold-chain segments in Lat Krabang logistics parks bundle lubricant supply with uptime guarantees.
Eastern Economic Corridor
Deep-sea port expansion at Laem Chabang and industrial clustering around Rayong generate concentrated demand from new logistics entrants. Thailand's Board of Investment incentives attract automotive and electronics manufacturers with captive fleet requirements. Heavy-duty trucks operating Laem Chabang-Bangkok corridors absorb disproportionate synthetic volume through specification upgrades.
Northern Region
Chiang Mai logistics hubs lack technical service depth, creating white space for mobile oil analysis programs. Provincial fleet networks operate on extended drain interval misinterpretations that inflate apparent volume. Owner-operator segments in Lampang and Phitsanulok resist premium product migration due to specification fragmentation.
Northeastern Region
Khon Kaen freight corridors connect to Lao PDR and Vietnamese border trade, conditioning lubricant procurement toward durability-focused formulations. The Department of Land Transport imposes vehicle fitness standards that indirectly condition fluid change frequencies across Nakhon Ratchasima commercial hubs. Regional distributors serve agricultural machinery fleets with price-sensitive mineral oil procurement.
Southern Region
Songkhla and Hat Yai logistics nodes handle cross-border trade with Malaysia, generating demand from dual-registered commercial vehicles. Coastal humidity and salt exposure accelerate corrosion protection requirements in chassis grease applications. Fishing fleet conversions to commercial transport create specification hybridization challenges for blenders.
Thailand Commercial Vehicles Lubricants Market Competitive Landscape
Concentration sits with integrated refiners controlling captive feedstock access. PTT Group's vertical integration into base oil production limits blender margin flexibility, particularly for Group II and Group III materials. Three archetypes dominate: upstream-integrated national champions, global majors competing on technical service depth, and regional blenders surviving on price-sensitive provincial accounts. Competitive moves center on direct procurement displacement of distributors and bio-based formulation differentiation aligned with sustainability disclosure requirements.
Among Thailand-based integrated players, PTT Lubricants and Bangchak Corporation anchor the national champion tier with backward integration advantages. Chevron Corporation occupies a position among global majors competing through fleet technical partnerships. These three exemplify how feedstock control, sustainability positioning, and service depth respectively define competitive differentiation in a market where Bangkok-based logistics operators increasingly bypass traditional distribution tiers.
| Leading Market Players |
|---|
| Bangchak Corporation |
| PTT Lubricants |
| Chevron Corporation |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| BP PLC (Castrol) |
| Idemitsu Kosan Co Ltd |
| Siam Pan Group Public Co Ltd |
| Thai Petroleum & Trading Co Ltd |
| Others |
Value Network & Pricing Analysis
TISI certification timelines gate both supply qualification and price differentiation simultaneously. Thailand's Department of Industrial Works Factory Act enforcement compresses informal blender margins while elevating certified suppliers with documented chain-of-custody systems. Fleet procurement centralization in Bangkok's logistics corridors amplifies this bifurcation.
Pricing Analysis
The customization-premium spread separates fleet-configured synthetic formulations from standard mineral products. Three-tier pricing structure across premium, standard, and economy levels reflects API specification tier, volume scale, and technical service bundling. Price compression runs through conventional mineral tiers as synthetic adoption accelerates in centralized procurement. Owner-operators in provincial markets exhibit highest price sensitivity; express delivery fleets with uptime penalties show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate Bangkok-based fleet operators with predictable consumption patterns, while strategic stockpiling persists among provincial distributors managing credit-constrained customers. Base oil supply draws from Thailand's integrated refiners, South Korean Group III exporters, and Singapore trading hubs. Additive packages rest on US and European specialty chemical imports. Single-source vulnerability concentrates around PTT Group's domestic Group II and Group III production. Distribution runs through direct sales for large fleets, wholesaler networks for provincial accounts, and retail service stations for fragmented owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's commercial lubricants market functions as a service-attach opportunity where condition-based maintenance contracts and oil analysis programs expand faster than transactional fluid sales. Technical service bundling now determines procurement decisions for fleet operators with uptime-critical operations.
For Market Incumbents: Fortify direct procurement relationships with Bangkok-based logistics operators through predictive maintenance software integration. Deepen backward integration into additive formulation capabilities to reduce import dependency. Capture mobile oil analysis white space in Chiang Mai and Khon Kaen before regional blenders consolidate provincial fleet networks.
For New Entrants and Emerging Players: Lead with carbon intensity disclosure capabilities targeting Thai-listed conglomerates with emerging Scope 3 reporting requirements. Penetrate the Northeastern Region's cross-border freight corridors through durability-focused formulation partnerships with Lao PDR-registered fleets. Deploy platform-based procurement with transparent pricing and documented waste oil chain-of-custody compliance.
For Investors and Strategic Acquirers: Factory Act waste oil enforcement reshapes the acquisition landscape toward certified suppliers with compliance infrastructure. Long-term viability centers on blenders with technical service depth and direct fleet relationships rather than volume-dependent distributors. Watch for TISI certification backlog resolution as inflection indicator for product launch velocity and market share redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Reduces 12-18 month TISI validation cycles for reformulated packages. |
| Mobile Oil Analysis Service Deployment | Captures underserved provincial fleet networks in Northern and Northeastern Regions. |
| Carbon Intensity Certification Investment | Aligns procurement with Thai-listed conglomerate Scope 3 disclosure requirements. |
| Condition-Based Maintenance Contracts | Bundles lubricant supply with uptime guarantees for express delivery segments. |
| Direct Sales Channel Expansion | Displaces traditional distributors for Bangkok-based 200+ unit fleet operators. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation. Fleet procurement managers, lubricant technical service directors, Department of Industrial Works compliance officers, and provincial distributor operators provided operational perspective. Secondary sources encompassed Thai Industrial Standards Institute certification records, Department of Land Transport vehicle fitness documentation, customs trade data for base oil imports, and integrated refiner disclosure filings. Bottom-up volume modeling triangulated against top-down market sizing.
Across the analysis window, forecasts incorporated product type, application segment, material formulation, and distribution channel dimensions. CAGRs derived from segment-level growth trajectory modeling anchored in fleet expansion patterns and specification upgrade cycles. Drain interval extension assumptions and synthetic penetration curves conditioned volume projections. Eastern Economic Corridor infrastructure buildout timelines and Factory Act enforcement intensity shaped regional demand distribution.
The analysis sits within stated boundaries; outcomes outside sustained freight corridor expansion or altered waste oil enforcement severity would require recalibration. Forecasts reflect assumptions around OEM specification adoption rates and fleet procurement centralization momentum. Revision becomes warranted when bio-based formulation cost deltas compress below threshold levels or telematics-fluid integration adoption crosses critical mass.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Liquid-Cooled Heat Sink Market
Others
Cashew Kernel Market
Others
Global Military Apparel Market
Others
Global Process Equipment Market
Others
Digital Media Adaptor (DMA) Market
Others
Cat Dry Food Market
Others
North America Smart Homes Market
Others
Africa Cotton Market
Others
Global Drug Discovery Informatics Market
Others
Surface Green Mining Market
Others
Content Experience Platforms Market
Others
China Cloud Gaming Technology Market
Others
Dried Fruit Extracts Market
Others
Global Microcontroller Embedded Systems Market
Others
Safety Critical Software Testing Market
Others
ASEAN Smart Homes Market