
 North America Underwater Communication Systems Market | 2026-2036
North America Underwater Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Underwater Communication Systems Market Analytics
Buyer concentration among defense and energy contractors is recalibrating procurement dynamics across the North America Underwater Communication Systems Market. Teledyne Technologies Incorporated leverages its vertical integration across sensors and telemetry to sustain long-term naval contracts. L3Harris Technologies Inc anchors its position through classified program relationships and secure manufacturing protocols. Kongsberg Gruppen ASA competes on sonar integration depth, differentiating its offerings from point-product rivals.
North America underwater communication systems encompass hardware and software platforms that transmit data through acoustic, optical, or electromagnetic carriers in submerged environments, typically operating at frequencies below 100 kHz for acoustic links to overcome seawater attenuation. These systems serve military command-and-control, subsea asset monitoring, and scientific data collection where radio propagation fails. Acoustic modems dominate installed base revenue due to proven reliability in turbid waters, while optical systems represent the fastest-expanding technology segment for short-range, high-bandwidth applications. Military applications command the largest end-user budget allocation, though oceanographic research is gaining procurement traction as federal science agencies modernize observatory networks.
The US Federal Communications Commission and the Canadian Department of National Defence shape equipment standards through spectrum coordination and interoperability mandates, respectively. The International Organization for Standardization provides underwater acoustic networking protocols that vendors must adopt for cross-border system compatibility. Stakeholders must monitor how evolving FCC acoustic spectrum rulings and Canadian Arctic sovereignty investments reshape certification requirements and deployment timelines.
Market Dynamics
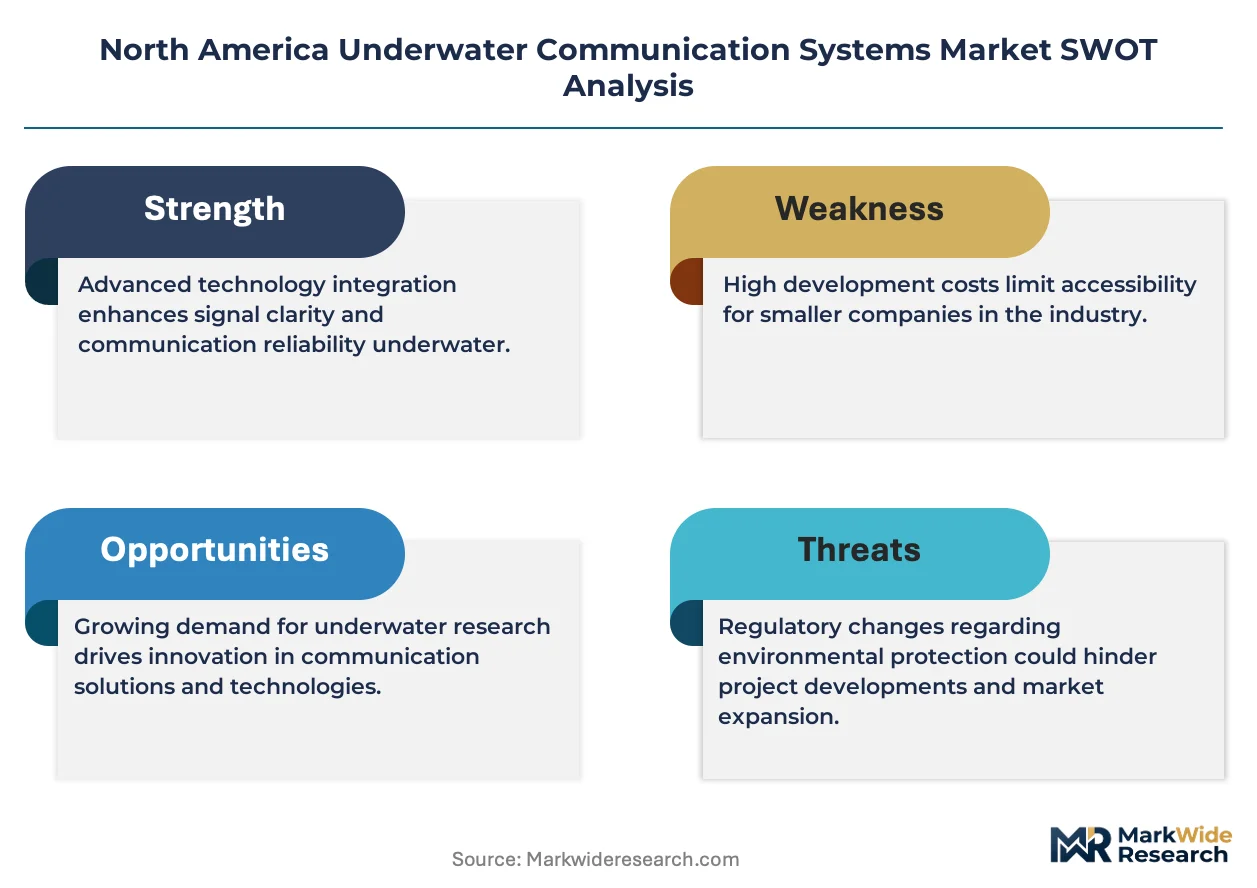
The US Federal Communications Commission's tightening acoustic spectrum certification rules are compressing vendor timelines and elevating R&D spend requirements across North American underwater communication systems procurement.
Growth Catalysts
- Defense procurement modernization:The US Navy and Canadian maritime forces are mandating interoperable command-and-control platforms, forcing vendors to standardize acoustic modem architectures for joint operations.
- Offshore energy infrastructure expansion:Gulf of Mexico subsea asset monitoring networks are driving demand for reliable acoustic telemetry in high-pressure, turbid environments where optical links fail.
- Federal science agency investment:Modernization of oceanographic observatory networks by US and Canadian research institutions is expanding procurement budgets for long-duration, deep-sea data collection systems.
Market Restraints
- Acoustic spectrum scarcity:FCC coordination requirements for underwater channels below 100 kHz are lengthening equipment certification cycles and raising compliance costs for new market entrants.
- Seawater attenuation physics:Electromagnetic carrier propagation remains impractical beyond extremely short ranges, locking the installed base into acoustic technology with inherent bandwidth limitations.
- California-Gulf supply concentration:Component manufacturing and system integration cluster in two coastal corridors, creating geographic vulnerability to climate disruption and logistics congestion.
Strategic Opportunities
- Canadian Arctic sovereignty investments:The Department of National Defence is funding under-ice communication infrastructure for extended continental shelf operations, opening procurement channels for cold-rated acoustic systems.
- Optical-acoustic hybrid convergence:Short-range optical modems paired with long-range acoustic relays are enabling high-bandwidth data bursts in clear-water applications previously served by pure acoustic links.
- Integrated service contracting:Energy majors are unbundling hardware purchase from lifecycle maintenance, creating recurring revenue streams for vendors with field service presence in the Gulf of Mexico basin.
Industry Challenges
- Specialized acoustic engineering talent scarcity:The intersection of underwater physics, signal processing, and marine hardware design draws from a limited labor pool concentrated in coastal research universities.
- Legacy system integration complexity:Navy and energy operators require backward compatibility with decades-old acoustic protocols, forcing vendors to maintain multi-generation firmware architectures.
- Extended certification timelines:FCC equipment authorization and Canadian military interoperability testing create 18-24 month gaps between prototype completion and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Underwater Communication Systems Market |
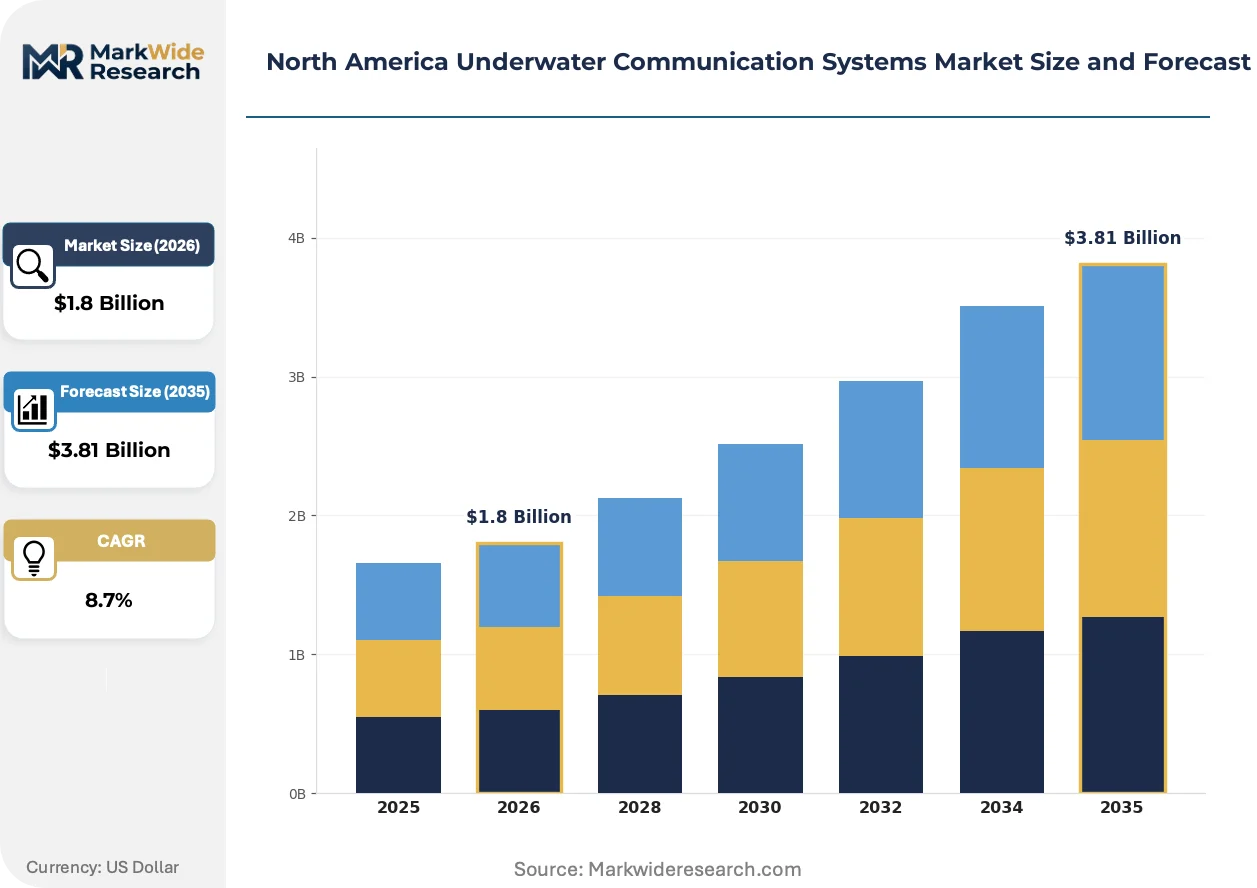
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Modems, Optical Systems, Wireless Nodes, Communication Cables End User: Military Applications, Oceanographic Research, Oil & Gas Exploration, Aquaculture Technology: Sonar Systems, Radio Frequency, Underwater Wireless, Fiber Optics Installation Type: Permanent Installations, Temporary Deployments, Underwater Networks, Mobile Systems |
| Companies Covered | Teledyne Technologies Incorporated, L3Harris Technologies Inc, Kongsberg Gruppen ASA, Sonardyne International Ltd, Ultra Electronics Maritime Systems Inc, Thales, Saab AB, EvoLogics GmbH, Moog Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Underwater Communication Systems Market Evolving Landscape
Acoustic modem architectures are fragmenting into application-specific variants as end-users reject one-size-fits-all platforms. Vendors are responding with modular hardware and software-defined signal processing.
Optical underwater communication systems are expanding into subsea inspection robotics and diver support operations where turbidity permits. Offshore energy contractors in the Gulf of Mexico are piloting these systems for wellhead monitoring at ranges under 100 meters. The technology is expanding into niches previously dominated by high-frequency acoustic links, compressing addressable market assumptions for legacy modem suppliers.
The FCC's 2024 equipment authorization framework for underwater acoustic devices is mandating interference testing in shared marine mammal frequency bands. This regulatory shift is extending pre-market approval timelines by eight to twelve months. Military and scientific procurement segments are absorbing these delays through advance contracting, while commercial energy buyers are deferring upgrade cycles.
Buyer concentration among defense primes and supermajor energy companies is consolidating vendor relationships around multi-year framework agreements. Teledyne Technologies and L3Harris are capturing attached service revenue through embedded technical support clauses. This pattern is most visible in California's coastal technology corridor, where naval R&D contracts lock in preferred supplier status for subsequent production awards.
North America Underwater Communication Systems Market Segmentation
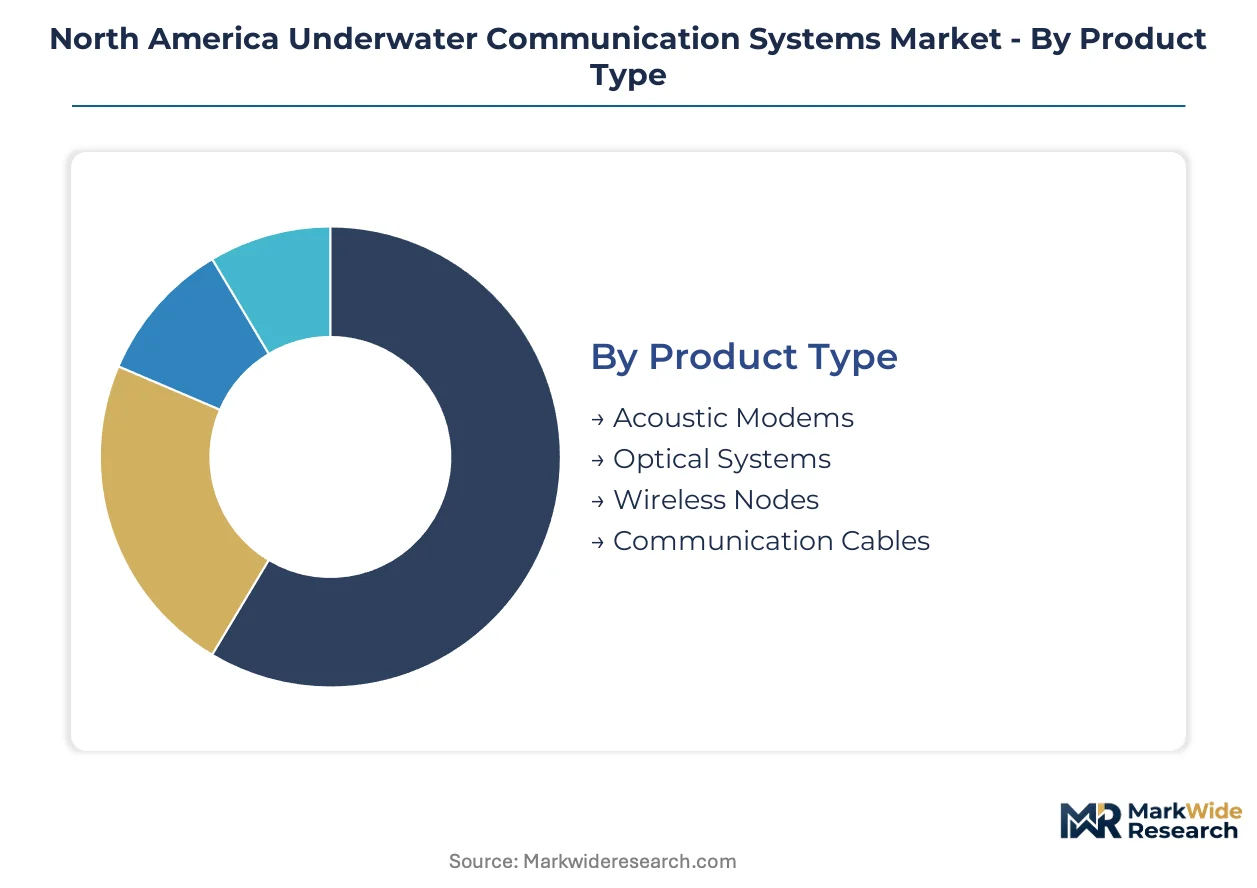
Segmentation in underwater communication systems reveals distinct upgrade cycles across hardware platforms and end-use environments. Procurement patterns diverge sharply between defense primes seeking decade-long platform compatibility and energy contractors prioritizing rapid deployment flexibility.
Product Type:
Replacement cycles vary dramatically across product categories, with acoustic hardware demanding 7-10 year refresh timelines versus optical systems on 3-5 year technology cadences.
- Acoustic Modems:These devices encode data onto pressure waves typically below 100 kHz to overcome seawater attenuation. US Navy procurement concentrates demand in California's coastal technology corridor, where Teledyne and L3Harris maintain secure manufacturing protocols for classified programs. The installed base dominance here reflects proven reliability in turbid Gulf of Mexico conditions where optical alternatives fail.
- Optical Systems:Short-range, high-bandwidth links using blue-green laser or LED carriers operate effectively in clear-water environments. Gulf of Mexico offshore energy contractors are piloting these for wellhead monitoring at ranges under 100 meters, compressing addressable market assumptions for legacy modem suppliers. FCC equipment authorization timelines for optical devices run shorter than acoustic certification cycles.
- Wireless Nodes:Battery-powered relay stations enabling mesh network architectures for distributed sensing.
- Communication Cables:Tethered copper or fiber links providing high-reliability backbone connectivity for permanent infrastructure.
Volume placements concentrate in Acoustic Modems; the faster expansion belongs to Optical Systems.
End User:
Customer procurement maturity spans from rigid defense specification regimes to flexible commercial leasing arrangements.
- Military Applications:Command-and-control platforms for submarines, autonomous underwater vehicles, and seabed sensor grids dominate budget allocation. Canadian Arctic sovereignty investments are opening procurement channels for cold-rated acoustic systems capable of under-ice operation. Interoperability mandates between US and Canadian forces standardize modem architectures.
- Oil & Gas Exploration:Subsea asset monitoring in high-pressure environments drives demand for ruggedized telemetry. Gulf of Mexico operators are unbundling hardware purchase from lifecycle maintenance, creating recurring revenue streams for vendors with regional field service presence. Temporary deployment models predominate over permanent installations here.
- Oceanographic Research:Federal science agency modernization of observatory networks expands procurement for long-duration, deep-sea data collection.
- Aquaculture:Emerging demand from offshore fish farm operators for environmental monitoring and feeding system control.
Defense budgets anchor volume; energy sector procurement is climbing fastest as offshore infrastructure expands.
Technology:
Technology selection tracks directly against range requirements and water clarity conditions in target deployment zones.
- Sonar Systems:Active acoustic ranging and communication integrated into unified sensor packages. Military end-users in the US and Canada prioritize sonar-communication integration depth over point-product solutions, favoring Kongsberg's unified platform approach. Dual-use scientific and defense procurement creates economies of scale for specialized transducer manufacturing.
- Underwater Wireless:Protocol stacks enabling ad-hoc network formation between mobile nodes and fixed infrastructure. Research institutions along California's coast are deploying these for dynamic oceanographic sampling arrays. Standardization around ISO underwater acoustic networking protocols ensures cross-border compatibility.
- Radio Frequency:Extremely limited applicability due to seawater attenuation physics; confined to diver communications at surface-proximate depths.
- Fiber Optics:Tethered high-bandwidth links for permanent installations where cable laying is economically viable.
Sonar Systems capture the largest installed base; Underwater Wireless protocols are expanding most quickly through research network modernization.
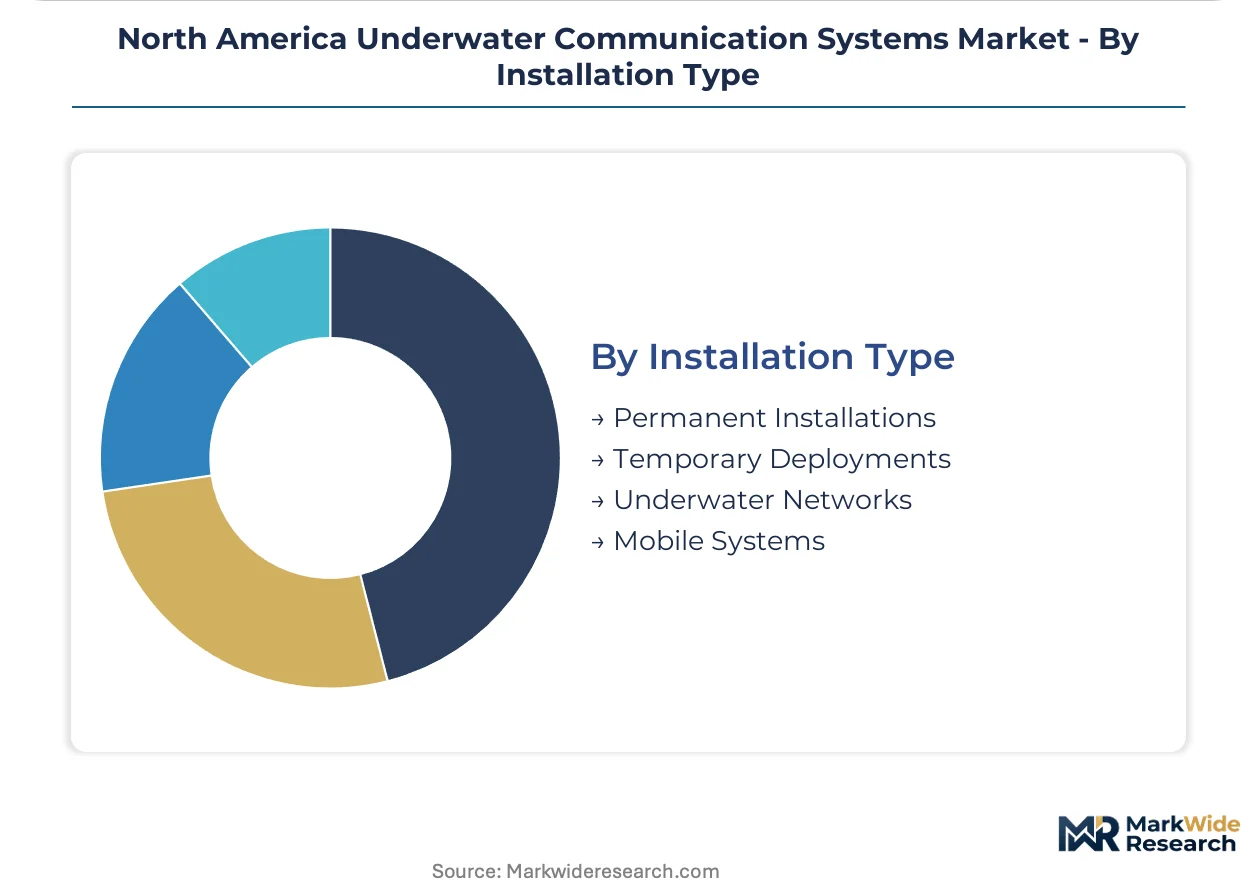
Installation Type:
Deployment duration and mobility requirements segment vendor capabilities between fixed infrastructure specialists and rapid-response service providers.
- Permanent Installations:Cabled seabed observatories and defense sensor grids requiring decade-long operational lifespans. FCC spectrum coordination for shared acoustic channels complicates multi-user permanent deployments in congested coastal zones. Extended certification timelines of 18-24 months favor incumbent vendors with established authorization histories.
- Mobile Systems:AUV-mounted and vessel-towed communication packages enabling adaptive mission profiles. US Navy procurement modernization emphasizes interoperable mobile platforms for joint operations with Canadian maritime forces. Battery endurance and acoustic signature management drive hardware specification here.
- Temporary Deployments:Seasonal or campaign-based equipment rental models for exploration and research.
- Underwater Networks:Multi-node architectures combining fixed and mobile elements for area coverage.
Permanent Installations dominate capital expenditure; Mobile Systems are gaining share fastest through autonomous platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement from the US Navy and Canadian maritime forces concentrates demand in coastal technology corridors, while offshore energy operators in the Gulf of Mexico drive commercial deployment timelines.
United States
California's coastal technology corridor hosts concentrated naval R&D contracts and secure manufacturing protocols for classified acoustic modem programs. The Federal Communications Commission's 2024 equipment authorization framework mandates interference testing in marine mammal frequency bands, extending certification timelines by eight to twelve months. Gulf of Mexico offshore energy contractors pilot optical systems for wellhead monitoring at ranges under 100 meters.
Canada
The Department of National Defence funds under-ice communication infrastructure for extended continental shelf operations, opening procurement channels for cold-rated acoustic systems. Canadian Arctic sovereignty investments require interoperability mandates with US forces, standardizing modem architectures across joint operations. Atlantic Canada harbors emerging oceanographic research networks modernizing observatory infrastructure.
Mexico
Pemex offshore exploration activities in the Bay of Campeche generate demand for ruggedized subsea asset monitoring telemetry in turbid, high-pressure environments. The country's national petroleum regulator oversees equipment standards for deepwater infrastructure deployment. Gulf Coast port modernization around Veracruz creates ancillary demand for harbor security communication networks.
North America Underwater Communication Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue optical-acoustic hybrid convergence and integrated service contracting models. The vendor base stratifies between defense-anchored primes with classified program relationships and commercial specialists serving energy sector procurement. Three archetypes dominate: vertically integrated sensor-telemetry conglomerates, sonar-integration platform providers, and point-product modem manufacturers. Competitive moves center on multi-year framework agreements with embedded technical support clauses and field service presence consolidation in the Gulf of Mexico basin.
Within the defense-anchored tier, Teledyne Technologies Incorporated and L3Harris Technologies Inc exemplify vertically integrated conglomerates with secure manufacturing protocols. Kongsberg Gruppen ASA occupies a position representing sonar-integration depth, differentiating from point-product rivals through unified platform approaches. These three entities anchor the competitive structure, with Teledyne and L3Harris capturing attached service revenue through advance contracting mechanisms while Kongsberg competes on integration breadth rather than standalone component sales.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| L3Harris Technologies Inc |
| Kongsberg Gruppen ASA |
| Sonardyne International Ltd |
| Ultra Electronics Maritime Systems Inc |
| Thales |
| Saab AB |
| EvoLogics GmbH |
| Moog Inc |
| Others |
Value Network & Pricing Analysis
Defense-grade certification tiers bifurcate the North America Underwater Communication Systems Market into premium-classified and commercial-off-the-shelf segments, with FCC equipment authorization timelines and secure manufacturing protocols driving cost divergence across both pricing structures and supplier qualification requirements. Buyers in California's coastal technology corridor absorb 18-24 month certification delays through advance contracting mechanisms, while Gulf of Mexico energy contractors trade certification depth for deployment speed.
Pricing Analysis
Volume placements concentrate in commoditized acoustic modems where margins compress under standardized NATO interoperability mandates, while classified program relationships sustain premium pricing for vendors with embedded technical support clauses. Price differentiation hinges on FCC authorization history and cold-rated operational certification for under-ice deployment. Cost compression in commercial energy tiers intensifies as optical-acoustic hybrid alternatives displace legacy pure-acoustic links. Defense primes exhibit lowest price sensitivity due to decade-long platform compatibility requirements; aquaculture operators demonstrate highest sensitivity, deferring upgrades when certification costs exceed operational savings.
Supply Chain Analysis
Dual-sourcing requirements from the US Navy and Canadian Department of National Defence mandate multi-supplier qualification for critical acoustic transducer components, preventing single-source lock-in despite geographic concentration. Manufacturing draws from the United States, Canada, and Norway for specialized piezoelectric ceramics and signal processing hardware. Supply chain risk centers on California-Gulf corridor climate vulnerability disrupting component logistics. Distribution runs through defense primes with field service presence in the Gulf of Mexico basin and authorized integrators serving oceanographic research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Underwater Communication Systems Market sits in an optical-acoustic hybrid transition, with short-range optical modems displacing high-frequency acoustic links in clear-water applications previously dominated by legacy telemetry.
For Market Incumbents: Cement multi-year framework agreements with embedded lifecycle maintenance clauses before FCC certification timelines extend further under marine mammal frequency band testing mandates. Prioritize backward compatibility engineering to preserve installed base revenue against modular entrant architectures. Deepen in-house production of cold-rated transducer assemblies to capture Canadian Arctic sovereignty procurement. For New Entrants and Emerging Players: Enter via aquaculture environmental monitoring and offshore fish farm automation, where defense-grade certification requirements do not apply and price sensitivity creates rapid adoption potential. Target temporary deployment service models in Gulf of Mexico exploration campaigns, unbundling hardware from field support to bypass incumbent entrenched relationships. Lead with software-defined signal processing platforms that outpace legacy firmware upgrade cycles. For Investors and Strategic Acquirers: Re-rating potential sits with sonar-integration platform providers given Canadian-US interoperability standardization and unified sensor-communication procurement consolidation. Long-term viability favors vendors with captive supply of piezoelectric ceramics and established FCC authorization histories. Watch FCC acoustic spectrum rulings as the inflection signal—tightening coordination requirements would accelerate incumbent consolidation and strand emerging entrant R&D.| Strategic Initiative | Industry Significance |
|---|---|
| Optical-Acoustic Hybrid Platform Development | Enables high-bandwidth data bursts in Gulf of Mexico wellhead monitoring below 100 meters. |
| Cold-Rated Acoustic System Certification | Unlocks Canadian Department of National Defence under-ice infrastructure procurement channels. |
| Integrated Service Contracting Model | Captures recurring revenue from energy majors unbundling hardware purchase from lifecycle maintenance. |
| FCC Equipment Authorization Pre-Investment | Compresses 18-24 month certification gaps through advance regulatory engagement and testing protocols. |
| Software-Defined Signal Processing Architecture | Accelerates firmware iteration beyond legacy multi-generation compatibility constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving acoustic engineering directors at defense primes, procurement leads at Gulf of Mexico energy contractors, oceanographic research facility managers, FCC equipment authorization specialists, and Canadian Department of National Defence interoperability testing officers. Secondary sources included US Navy budget justification documents, Canadian public accounts committee defense expenditure reports, SEC 10-K filings from listed sensor-telemetry conglomerates, and ISO underwater acoustic networking protocol drafts. Bottom-up vendor shipment estimates triangulated against top-down defense and energy sector procurement budgets.
Granularity-level modeling disaggregated volume and value across product type, end user, technology, and installation type dimensions, with additional segmentation by certification tier and operational depth rating. CAGRs derived from regression analysis of historical procurement cycles and projected defense modernization schedules. Industry-specific forecast inputs incorporated FCC equipment authorization pipeline data and Canadian Arctic sovereignty investment announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC acoustic spectrum reallocation or extended marine mammal interference testing mandates. Deviation in Canadian-US joint procurement standardization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Italy Telecom Market
Telecommunications
Oman Telecommunication Market
Telecommunications
GPON Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Peru Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Oman Telecom Market
Telecommunications
DWDM System Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
5G Radio Access Network Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Medical 5G Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
IP PBX Market