
 Disposable Non Woven Sponge Market | 2026-2036
Disposable Non Woven Sponge Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Non Woven Sponge Market Insights
Hospital procurement consolidation across North America is restructuring purchasing patterns toward contract-based volume agreements. Cardinal Health leverages its distribution scale to anchor multi-year supply contracts with integrated delivery networks. Medline Industries competes through private-label manufacturing capacity and direct-to-facility logistics. 3M Company differentiates via proprietary adhesive-bonding technology in antimicrobial sponge variants.
Disposable non woven sponges are single-use fibrous pads manufactured from thermally or chemically bonded synthetic or natural fibers, typically measuring 2x2 to 4x4 inches with absorbency rates calibrated for clinical exudate management. Polypropylene-based sponges dominate institutional procurement due to low linting and thermal bonding compatibility, while antimicrobial-coated variants command premium positioning in surgical applications. Cellulose segments sustain demand in food processing environments where biodegradability requirements shape material selection. The cosmetics application channel is expanding fastest as aesthetic clinics adopt single-use protocols for infection control.
FDA sterilization validation requirements and EU MDR biocompatibility testing frameworks elevate compliance costs for market entry, filtering smaller manufacturers from hospital tenders. The EPA regulates antimicrobial additive claims in cleaning applications, creating separate formulation pathways for industrial versus clinical grades. India's CDSCO and BIS standards increasingly align with ISO 13485 quality management protocols, reshaping export qualification for domestic producers. Stakeholders must monitor evolving sterilization modality preferences—gamma irradiation versus ethylene oxide—as hospital sustainability mandates restructure supply specifications.
Market Dynamics
Hospital procurement consolidation across North America is compressing supplier margins while elevating volume-scale requirements, forcing manufacturers to restructure production economics around multi-year contract commitments rather than spot-market sales.
Growth Catalysts
- Surgical Site Infection Protocols:Joint Commission accreditation standards mandate single-use sponge protocols in US ambulatory surgery centers, expanding replacement demand for reusable textile alternatives.
- EU MDR Biocompatibility Testing:Enhanced pre-market clinical evaluation requirements for Class I medical devices accelerates qualification of antimicrobial-coated sponge variants in European hospital tenders.
- India's Hospital Network Expansion:Ayushman Bharat health infrastructure investments drive institutional procurement of polypropylene-based surgical sponges in tier-2 and tier-3 cities.
Market Restraints
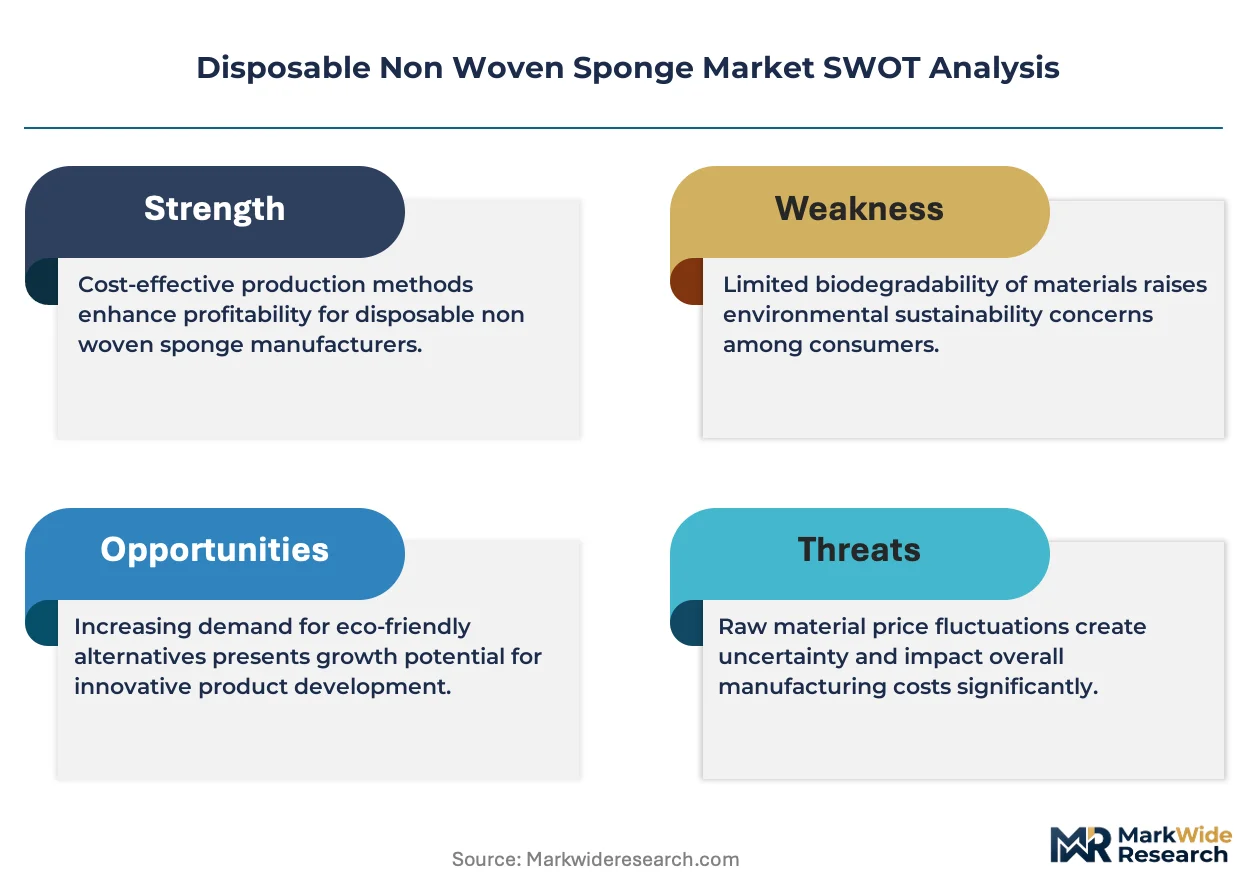
- Raw Material Concentration:Polypropylene resin supply concentrates among Gulf Coast petrochemical complexes, exposing sponge manufacturers to hurricane-season price volatility and force majeure disruptions.
- Sterilization Validation Costs:FDA 510(k) clearance pathways for novel sterilization modalities require capital-intensive bioburden testing, filtering smaller producers from hospital vendor lists.
- Cellulose Fiber Substitution:Biodegradable cellulose sponges face performance limitations in high-exudate surgical applications, constraining material pivot options for sustainability-focused buyers.
Strategic Opportunities
- Aesthetic Clinic Channel:Dermatology and cosmetic surgery practices in South Korea and Brazil adopt premium antimicrobial sponges for post-procedure wound care, creating price-insensitive demand pockets.
- Gamma Irradiation Infrastructure:Hospital sustainability mandates favor electron beam and gamma sterilization over ethylene oxide, rewarding suppliers with captive irradiation capacity.
- Home Healthcare Transition:Post-acute care discharge protocols in Germany expand direct-to-patient sponge distribution through pharmacy and durable medical equipment channels.
Industry Challenges
- Sterilization Technician Shortage:Hospital central sterile processing departments face 18% vacancy rates in the US, delaying contract onboarding for new sponge suppliers.
- Legacy ERP Integration:Integrated delivery networks require EDI-compliant inventory management systems that smaller manufacturers lack, creating procurement friction despite product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Non Woven Sponge Market |
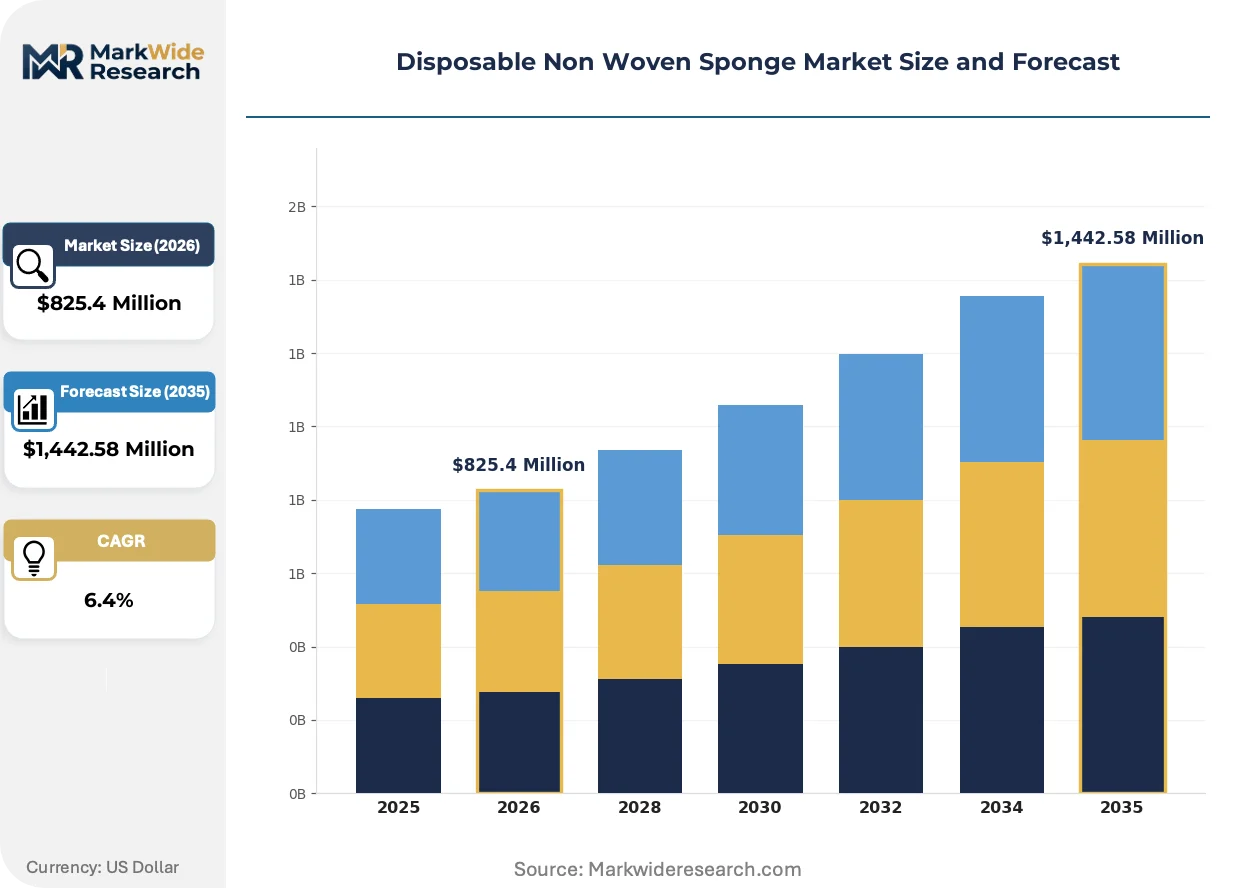
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,442.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sponge, Antimicrobial Sponge, Absorbent Sponge, Surgical Sponge Application: Healthcare, Cosmetics, Cleaning, Food Processing Material: Polypropylene, Rayon, Polyester, Cellulose End User: Hospitals, Clinics, Households, Industrial |
| Companies Covered | Cardinal Health, Medline Industries, McKesson Medical-Surgical, Dukal Corporation, Dynarex Corporation, B. Braun Melsungen AG, 3M Company, Mölnlycke Health Care, Allmed Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Non Woven Sponge Market Trends and Innovations
Thermal bonding automation and antimicrobial additive formulation are compressing production cycle times while elevating functional performance thresholds across clinical and industrial applications.
Ultrasonic welding technology is automating fiber-bonding processes in polypropylene sponge manufacturing, eliminating adhesive residues that compromise biocompatibility testing outcomes. German surgical instrument manufacturers specify ultrasonically bonded sponges for instrument cleaning protocols. This automation is compressing defect rates below 0.3% while enabling 40% faster line speeds than thermal calendar bonding.
EU MDR Article 10 post-market surveillance obligations now require sponge manufacturers to maintain clinical follow-up data for antimicrobial efficacy claims. The regulation forces reformulation of silver-ion and PHMB additives to demonstrate sustained release profiles under ISO 10993 biocompatibility frameworks. German notified bodies enforce the strictest interpretation, delaying market access for non-EU producers by 8-14 months relative to legacy Medical Device Directive timelines.
Integrated delivery networks in the US now mandate vendor-managed inventory programs with consignment stocking at the point-of-use. Hospital material managers cede forecasting responsibility to Cardinal Health and Medline distribution arms, compressing direct manufacturer relationships. This concentration is most visible in the Southeast US, where HCA Healthcare and Tenet Health systems have consolidated 60% of acute care purchasing under three distribution contracts.
Disposable Non Woven Sponge Market Segmentation
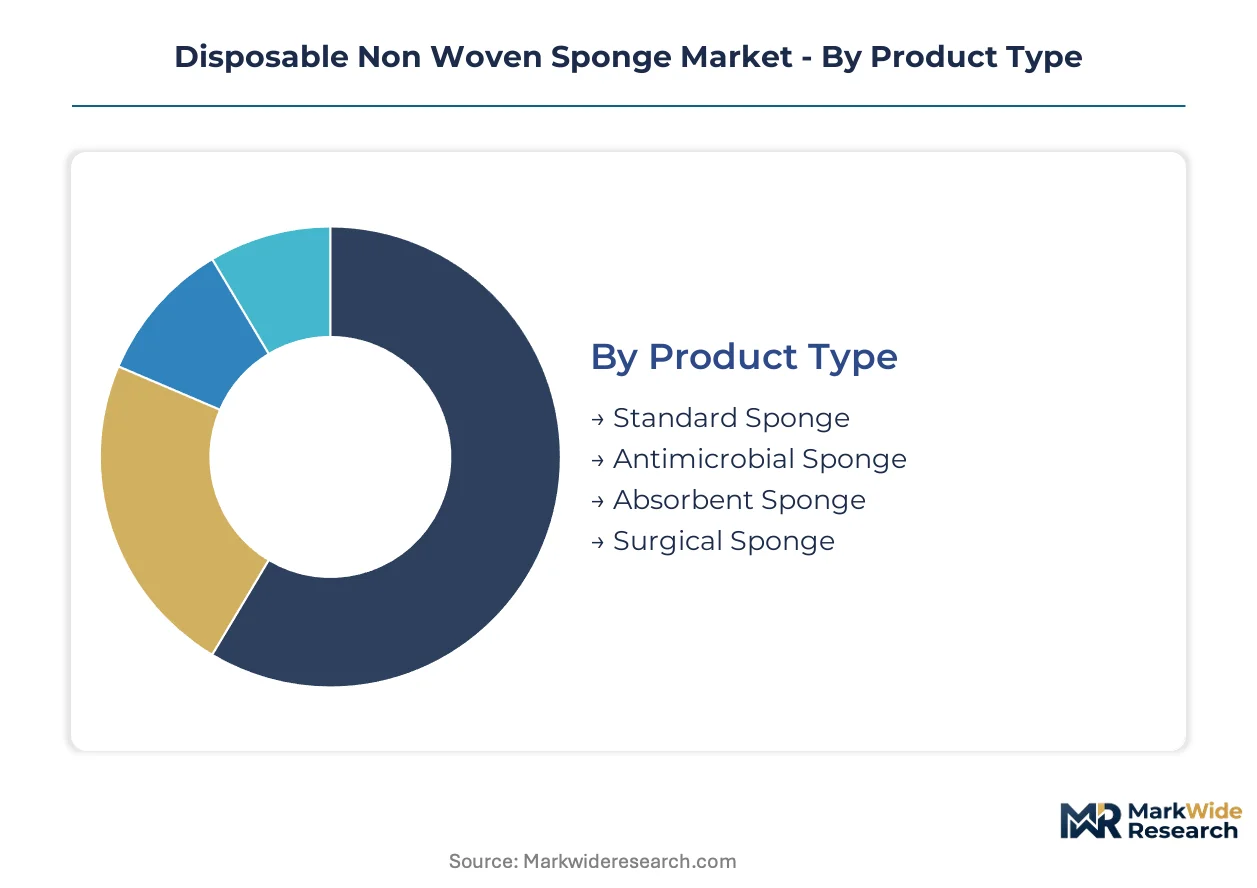
Segmentation in disposable non woven sponges reveals how material science, regulatory pathways, and end-use sterilization requirements create distinct commercial battlegrounds. Procurement managers navigate trade-offs between polypropylene's clinical performance and cellulose's sustainability positioning across divergent application channels.
Product Type:
Standardization dominates high-volume hospital contracts, while antimicrobial variants command premium positioning through FDA 510(k) qualification barriers and proprietary additive formulations.
- Standard Sponge:Thermally bonded polypropylene or rayon fibers deliver baseline absorbency for general wound cleaning and instrument preparation. Hospital procurement consolidation across the US Southeast favors these SKUs for multi-year IDN contracts where price-per-unit drives vendor selection.
- Antimicrobial Sponge:Silver-ion or PHMB-impregnated variants require EU MDR biocompatibility dossiers and sustained-release validation under ISO 10993 frameworks. German notified bodies enforce the strictest clinical follow-up obligations, delaying market access for non-EU producers.
- Absorbent Sponge:Higher-density fiber matrices target exudate-heavy applications in post-acute and home healthcare settings.
- Surgical Sponge:Gamma-sterilized, low-linting specifications for operating room use with radiopaque thread options for retained foreign object prevention.
Leading the category by volume: Standard Sponge. Growing fastest: Antimicrobial Sponge.
Application:
Clinical sterilization protocols impose capital-intensive qualification costs that filter participation, while cosmetics and food processing channels reward material biodegradability over thermal bonding precision.
- Healthcare:Operating rooms, ambulatory surgery centers, and emergency departments drive demand for sterile, single-use sponges meeting Joint Commission infection control standards. US ASC accreditation mandates displace reusable textile alternatives.
- Cosmetics:Aesthetic clinics in South Korea and Brazil adopt premium single-use protocols for post-procedure wound care, creating price-insensitive demand pockets outside hospital procurement systems.
- Cleaning:Industrial and institutional surface disinfection applications favor cellulose-based sponges where EPA antimicrobial claim regulations shape formulation pathways.
- Food Processing:Biodegradability requirements and HACCP compliance favor cellulose fiber selection over synthetic alternatives in processing facility sanitation protocols.
Healthcare dominates absolute volume. Cosmetics climbs the fastest as aesthetic medicine expands.
Material:
Petrochemical supply concentration on the US Gulf Coast shapes polypropylene economics, while cellulose sourcing responds to EU Green Deal circularity mandates and food-grade biodegradability specifications.
- Polypropylene:Low-linting thermal bonding compatibility makes this the default for surgical and sterile applications. Hurricane-season force majeure disruptions at Texas and Louisiana resin complexes expose margin vulnerability.
- Cellulose:Natural fiber biodegradability satisfies food processing and sustainability-focused buyer segments, though high-exudate performance limitations constrain surgical adoption.
- Rayon:Semi-synthetic alternative balancing absorbency and cost in non-sterile cleaning applications.
- Polyester:Durable fiber option for industrial cleaning where reuse cycles are tolerated before disposal.
Polypropylene leads procurement volume. Cellulose gains share fastest on sustainability tailwinds.
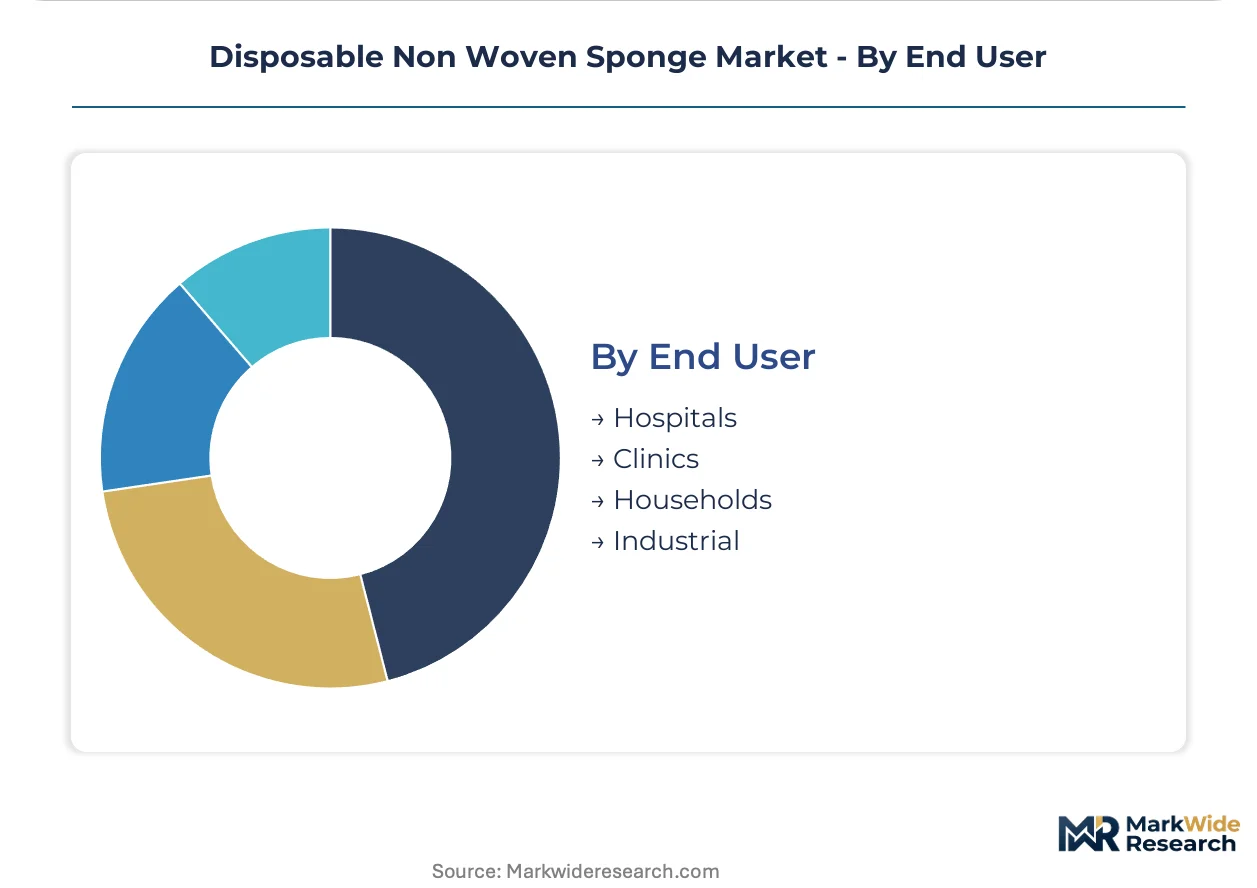
End User:
Hospital procurement centralization compresses supplier margins through multi-year volume contracts, while household and industrial channels preserve spot-market pricing flexibility.
- Hospitals:Integrated delivery networks in North America consolidate 60% of acute care purchasing under distribution contracts with Cardinal Health and Medline, forcing manufacturers to absorb vendor-managed inventory costs.
- Clinics:Dermatology and cosmetic surgery practices operate outside IDN procurement systems, enabling direct manufacturer relationships and premium pricing for antimicrobial variants.
- Households:Retail pharmacy and durable medical equipment channels expand in Germany's post-acute care discharge protocols.
- Industrial:Food processing and manufacturing facilities source through industrial distributors with less stringent sterilization validation requirements.
Hospitals command the volume lead. Clinics show the steepest expansion trajectory as aesthetic medicine decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates demand in the United States, while manufacturing corridors in Germany and India reshape supply geography through divergent regulatory pathways and infrastructure investments.
United States
Integrated delivery networks in the Southeast consolidate acute care purchasing under distribution contracts, compressing direct manufacturer relationships. FDA sterilization validation requirements for 510(k) clearance filter smaller producers from hospital vendor lists. Cardinal Health anchors multi-year supply agreements with HCA Healthcare and Tenet Health systems across Florida and Texas.
Germany
Surgical instrument manufacturers in Baden-Württemberg specify ultrasonically bonded sponges for cleaning protocols, driving premium material demand. EU MDR Article 10 post-market surveillance obligations delay market access for non-EU producers by 8-14 months. German notified bodies enforce strictest biocompatibility interpretations for antimicrobial efficacy claims.
India
Ayushman Bharat health infrastructure investments drive institutional procurement in tier-2 and tier-3 cities beyond metropolitan hospital networks. CDSCO and BIS standards increasingly align with ISO 13485 quality management protocols, reshaping export qualification for domestic producers. Tamil Nadu and Maharashtra manufacturing clusters expand polypropylene sponge capacity for regional supply.
South Korea
Dermatology and cosmetic surgery practices adopt premium single-use protocols for post-procedure wound care, creating price-insensitive demand pockets outside hospital procurement systems. MFDS medical device regulations govern antimicrobial additive claims in aesthetic applications. Seoul-based aesthetic clinics source directly from manufacturers, bypassing consolidated distribution channels.
Brazil
ANVISA medical device registration requirements structure market entry for imported sponge variants, favoring established multinational documentation capabilities. Cosmetic surgery volume in São Paulo and Rio de Janeiro drives consumption of premium antimicrobial sponges. Local distributors navigate complex import licensing for gamma-sterilized surgical specifications.
Disposable Non Woven Sponge Market Competitive Landscape
North American distributors anchor one tier; European and Asian manufacturers hold specialized production positions. The market structures around three tiers: large-scale distributors with captive logistics networks, mid-cap specialists with proprietary bonding technologies, and regional fabricators serving price-sensitive institutional segments. Consolidation pressures favor multi-year contract scale over spot-market flexibility. Capacity expansion and vendor-managed inventory programs represent dominant competitive moves.
Within the distributor tier, Cardinal Health and Medline Industries exemplify scale-driven consolidation strategies, while 3M Company occupies a position defined by proprietary technology differentiation. B. Braun Melsungen AG represents European manufacturing integration, and Mölnlycke Health Care anchors Nordic hygiene specialization. These four entities collectively illustrate the competitive archetypes reshaping procurement relationships across hospital networks, aesthetic clinics, and industrial channels.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| McKesson Medical-Surgical |
| Dukal Corporation |
| Dynarex Corporation |
| B. Braun Melsungen AG |
| 3M Company |
| Mölnlycke Health Care |
| Allmed Medical Products |
| Others |
Pricing and Supply Chain Analysis
Thermal bonding automation and gamma irradiation sterilization are compressing unit economics while concentrating production scale among manufacturers with captive processing capacity, forcing price discipline through capital efficiency rather than input arbitrage.
Pricing Analysis
High-volume hospital contracts trade margin for multi-year commitment security, while antimicrobial variants capture premium positioning through FDA 510(k) qualification barriers and proprietary additive formulations. Price differentiation hinges on sterilization modality certification and vendor-managed inventory bundling. Cost compression in standard polypropylene tiers is intensifying because integrated delivery networks consolidate purchasing under distribution contracts. Food processing buyers exhibit highest price sensitivity due to cellulose substitution options, whereas aesthetic clinics in South Korea and Brazil show lowest sensitivity for post-procedure antimicrobial specifications.
Supply Chain Analysis
Dual-sourcing mandates from North American hospital procurement committees require manufacturers to qualify secondary resin suppliers and backup sterilization facilities, elevating working capital requirements. Polypropylene resin feeds from Texas and Louisiana petrochemical complexes, with cellulose pulp anchored in Nordic and Canadian forestry operations. Supply chain risk centers on hurricane-season force majeure disruptions at Gulf Coast resin complexes. Distribution runs through Cardinal Health and Medline captive logistics networks for hospital contracts, while direct manufacturer relationships persist in cosmetic clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is filtering smaller manufacturers from vendor lists, leaving scale and certification as the primary survival mechanisms.
For Market Incumbents: Deploy vendor-managed inventory programs to deepen IDN relationships and defend contract renewal rates. Secure captive gamma irradiation capacity to meet hospital sustainability mandates displacing ethylene oxide sterilization. Invest in EU MDR notified body pre-submission pathways to compress the 8-14 month access delay for antimicrobial variants in German tenders. For New Entrants and Emerging Players: Enter via direct-to-clinic distribution in Brazil and South Korea aesthetic medicine corridors, bypassing consolidated hospital procurement systems. Target food processing cellulose segments where biodegradability requirements create procurement autonomy from clinical sterilization standards. Pursue white-label manufacturing partnerships with established distributors lacking private-label bonding capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by distribution platforms seeking backward integration into sponge manufacturing. Mid-term viability favors producers with ISO 13485 certification and multi-modal sterilization assets. Monitor IDN contract renewal cycles as inflection indicators for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Gamma Irradiation Capacity Expansion | Hospital sustainability mandates favor electron beam and gamma sterilization over ethylene oxide residues. |
| EU MDR Notified Body Pre-Submission | German notified bodies enforce strictest biocompatibility interpretations, delaying non-EU producer access. |
| Vendor-Managed Inventory Programs | IDNs cede forecasting responsibility to distribution arms, compressing direct manufacturer relationships. |
| Antimicrobial Additive Reformulation | Silver-ion and PHMB sustained-release validation under ISO 10993 frameworks elevates qualification barriers. |
| Direct-to-Clinic Distribution Buildout | Aesthetic medicine in São Paulo and Seoul operates outside consolidated procurement, preserving premium pricing. |
Research Methodology
Multi-period observation of hospital procurement contract awards, sterilization modality adoption rates, and raw material price indices anchored the trend analysis, supplemented by interviews with central sterile processing directors, GPO contracts managers, biomedical engineers, and distribution channel partners. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and customs trade records. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Input-output matrices mapped polypropylene resin throughput, bonding automation capital deployment, and sterilization capacity utilization against end-user demand segmentation across healthcare, cosmetics, food processing, and industrial channels. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted projection scenarios. Modeled inputs incorporated Joint Commission accreditation mandates, Ayushman Bharat infrastructure rollout pace, and EU Green Deal circularity requirements shaping cellulose substitution patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under force majeure disruptions at Gulf Coast petrochemical complexes and accelerated IDN consolidation beyond current Southeast concentration. Deviation in FDA sterilization validation timelines or EU MDR notified body backlog severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Social Media Engagement Applications Market
Others
North America Automotive LED Lighting Market
Others
Global Pregnancy Tracker Apps Market
Others
AC Switchgear Market
Others
Cat Dry Food Market
Others
Fire Sprinkler Market
Others
Foldable Smartphone Market
Others
UAE Location-Based Services Market
Others
Global Wireless Asset Management Market
Others
North America IT Device Market
Others
Mobile Computer Market
Others
Folding Screen Mobile Phone Market
Others
South Asia Geosynthetics Market
Others
Badminton Apparel Market
Others
Voice Controlled Devices Market
Others
Europe Travel Retail Market