
 Underwater Lighting Market | 2026-2036
Underwater Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Lighting Market Analysis
Asset-light leasing models for marine lighting retrofits are reshaping how mid-size fleet operators access premium LED systems without capital outlay. Signify Holding leverages its component scale to supply standardized modules across multiple vessel classes. Eaton Corporation anchors its position through captive distribution to commercial marina developers. Lumishore specializes in through-hull marine fixtures with integrated thermal management for saltwater immersion.
Underwater lighting encompasses sealed luminaires engineered for continuous submersion, typically rated at IP68 or equivalent ingress protection with pressure-compensated housings and corrosion-resistant alloys. These systems illuminate aquatic environments for safety navigation, biological observation, and architectural display where surface-mounted alternatives fail. LED product types lead value contribution due to lumen-per-watt efficiency gains and multi-spectrum programmability. Swimming pool applications sustain the largest installed base though fountain and decorative lighting segments generate premium pricing. Residential end users dominate unit volumes while commercial and government buyers concentrate in specification-driven tenders with extended warranty requirements.
FAA marine lighting guidelines, EPA Clean Water Act discharge standards for vessel maintenance, and UAE MOHAP electrical safety certifications collectively constrain product design and market entry pathways. CE marking under EU RoHS and REACH frameworks limits hazardous substance content in luminaire housings sold across European marinas. Stakeholders must monitor evolving efficiency mandates from multiple national regulators to anticipate retrofit cycles and certification investment requirements.
Market Dynamics
IMO environmental guidelines are tightening vessel energy efficiency mandates, forcing marine superyacht refit yards across the Mediterranean to accelerate LED retrofits and triggering cascading specification changes throughout the supply chain.
Growth Catalysts
- IMO Energy Efficiency Standards:Maritime environmental regulations compel fleet operators to replace legacy halogen fixtures with pressure-compensated LED arrays, creating mandatory replacement cycles across European superyacht refit yards.
- Dubai Waterfront Developments:The United Arab Emirates concentrates architectural fountain and pool lighting demand as megaproject developers specify IP68-rated luminaires for landmark installations.
- Biological Observation Applications:Research institutions deploy multi-spectrum programmable LEDs for marine ecosystem monitoring, expanding addressable demand beyond traditional decorative and safety applications.
Market Restraints
- Corrosion-Resistant Alloy Costs:Titanium and marine-grade stainless steel price volatility compresses fixture margins, particularly for through-hull installations requiring pressure-compensated housings.
- Supply Concentration in East Asian Electronics:LED driver and control module sourcing depends on concentrated semiconductor fabrication capacity, exposing lead times to geopolitical friction.
- Saltwater Immersion Technical Limits:Thermal management in sealed housings constrains lumen output per fixture, requiring more units to achieve equivalent illumination versus surface-mounted alternatives.
Strategic Opportunities
- Asset-Light Leasing Models:Mid-size fleet operators access premium LED systems without capital outlay, expanding addressable demand among operators previously priced out of retrofit markets.
- EPA Clean Water Act Compliance:Vessel maintenance discharge standards create regulatory tailwinds for sealed, low-maintenance LED fixtures that reduce chemical cleaning frequency and effluent volumes.
- Smart Marina Integration:Convergence of LED controls with IoT-enabled dock management systems enables remote diagnostics and predictive maintenance contracts, shifting revenue toward recurring service streams.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:Simultaneous FAA marine lighting compliance, EPA discharge standards, and UAE MOHAP electrical safety approvals extend product launch timelines and inflate testing budgets.
- Integration with Legacy Vessel Electrical:Retrofit installations must interface with aging DC distribution systems and proprietary control protocols, requiring custom engineering that erodes standardization gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Lighting Market |
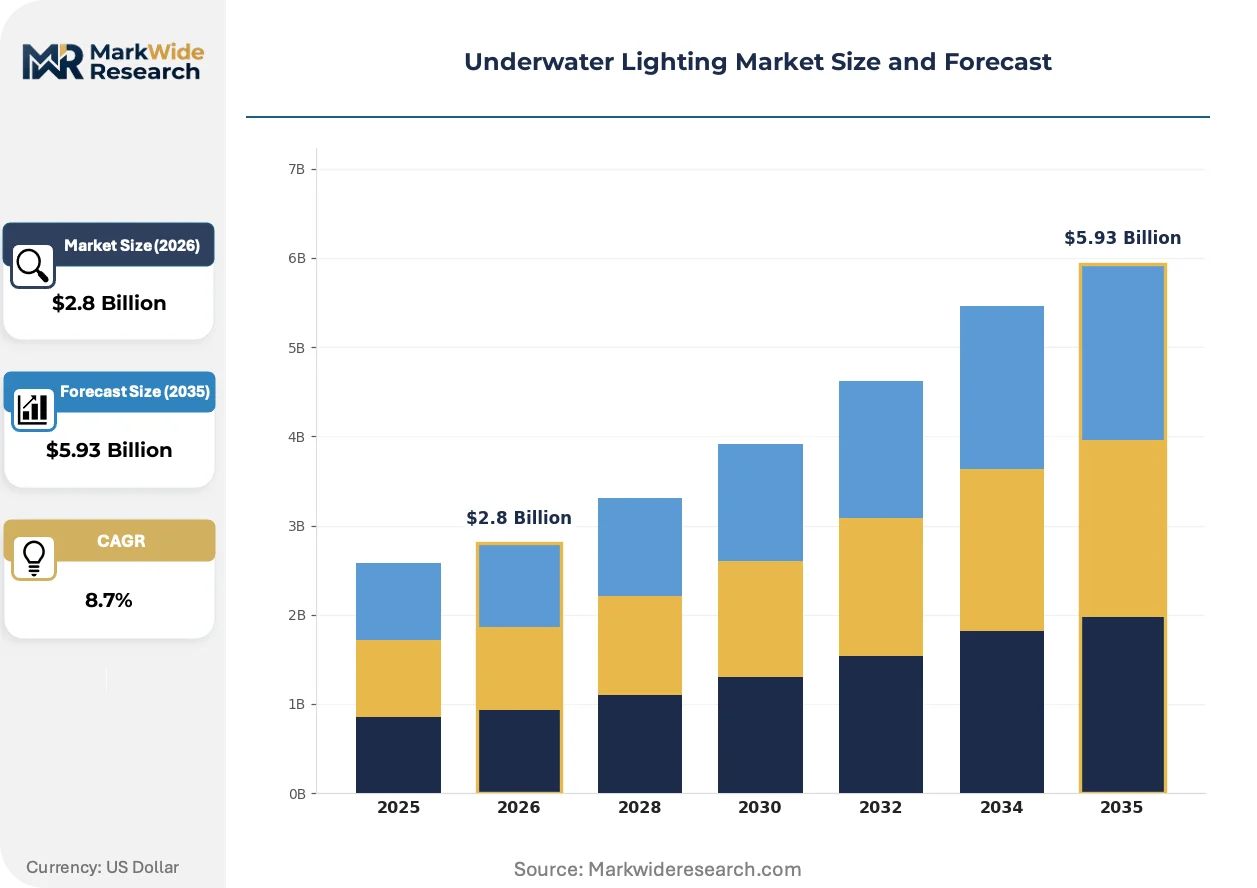
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Fluorescent, Xenon Application: Aquariums, Swimming Pools, Fountains, Decorative Lighting End User: Residential, Commercial, Government, Industrial Installation Type: Fixed, Portable, Modular, Integrated |
| Companies Covered | Signify Holding, Eaton Corporation, Acuity Brands, Hayward Industries, Lumishore, Aqualuma LED Lighting, T-H Marine Supplies, OceanLED Marine, Shadow Caster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Lighting Market Emerging Trajectories
Digital control architectures are displacing analog dimming circuits across marine and architectural applications, enabling spectrum programmability and remote diagnostics that reshape how operators manage submerged illumination assets.
Multi-channel LED drivers with integrated microcontrollers are digitizing fixture-level control, allowing real-time spectrum adjustment for biological research and architectural display applications. Superyacht owners and municipal fountain operators are adopting these systems at accelerating rates, replacing fixed-output halogen banks with addressable arrays. This digitization is compressing specification cycles as designers iterate color temperatures and intensity profiles without physical hardware changes.
EU RoHS and REACH frameworks now constrain hazardous substance content in luminaire housings sold across European marinas, with CE marking requirements extending to corrosion-resistant alloy compositions. The industrial consequence is a forced migration toward compliant material suppliers and documented supply chain transparency. Swimming pool and fountain segments in Mediterranean markets are absorbing the highest compliance costs, with specification engineers prioritizing pre-certified fixture families to accelerate project approvals.
Marina developers are consolidating vendor relationships around full-service lighting contractors who bundle installation, commissioning, and extended warranty coverage. This consolidation displaces traditional distributor channels where fixture-only transactions dominated. The United Arab Emirates exhibits this pattern most visibly, with Dubai waterfront developers issuing single-source tenders to contractors capable of delivering IP68-rated systems with decade-long performance guarantees.
Underwater Lighting Market Segmentation
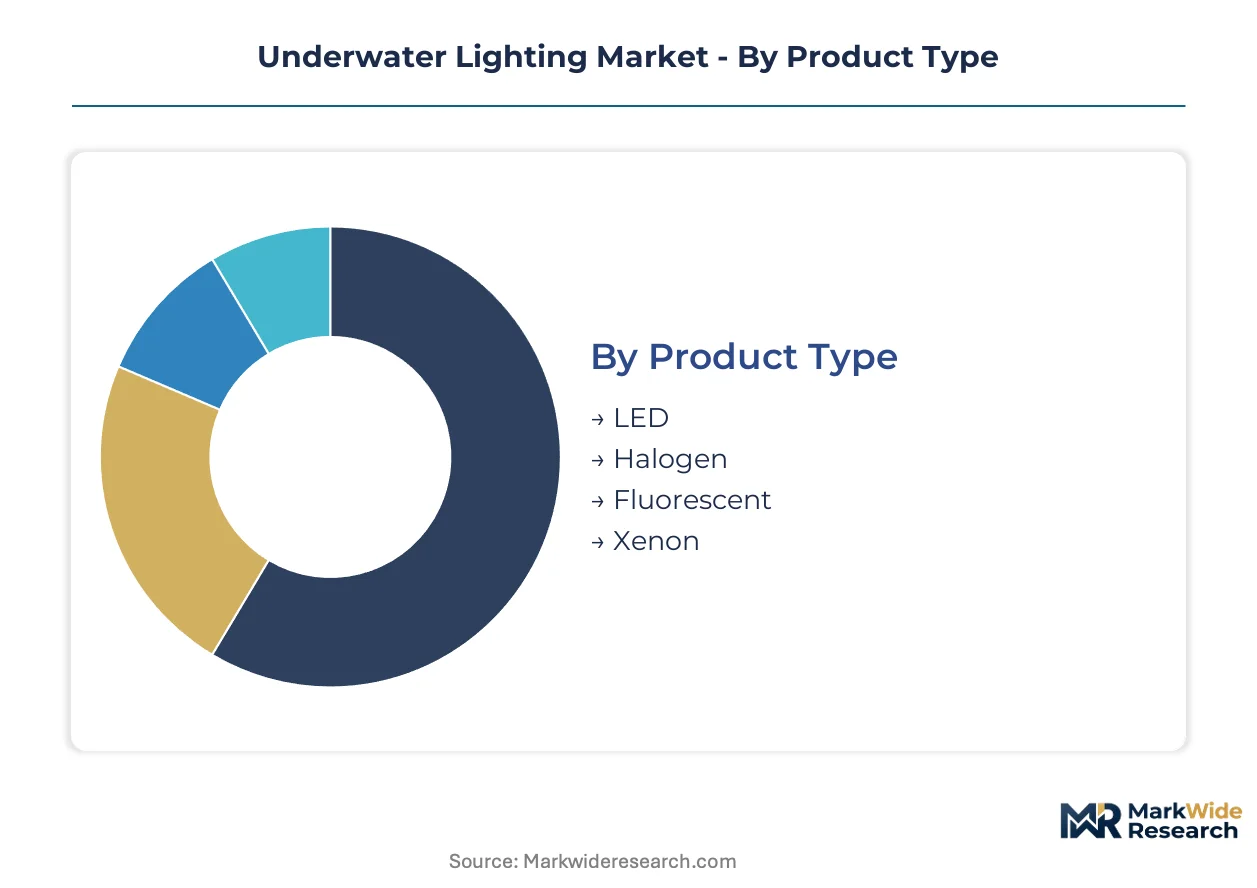
Segmentation in underwater lighting reveals distinct replacement cycles and specification requirements across technologies and use cases. Understanding these patterns enables suppliers to align inventory, certification investments, and service models with where demand concentrates.
Product Type:
Replacement cycles vary dramatically across lighting technologies, with some segments turning over every 3-5 years while others persist for 15+ years in saltwater environments.
- LED:Solid-state arrays with pressure-compensated housings and multi-channel drivers dominate new specifications. Mediterranean superyacht refit yards specify these for IMO compliance, while Dubai fountain developers demand spectrum programmability for landmark displays.
- Halogen:Tungsten-halogen lamps in sealed quartz envelopes persist in legacy vessel installations where electrical retrofits prove cost-prohibitive. Operators in older Mediterranean fleets delay replacement until mandatory efficiency deadlines force upgrades.
- Fluorescent:Compact fluorescent tubes with marine-rated ballasts occupy niche aquarium applications where diffuse, broad-spectrum illumination supports coral photosynthesis.
- Xenon:High-intensity discharge arc lamps deliver concentrated beam output for deep-hull inspection and military submersible lighting.
LED anchors the volume base while halogen retains installed presence in aging fleets; LED gains share at the steepest rate as regulatory deadlines compress replacement windows.
Application:
Cost tiers separate commodity specification from premium engineering, with price multiples spanning 10x between basic pool lighting and custom fountain installations.
- Swimming Pools:Standardized IP68-rated fixtures with ABS housings and epoxy potting serve residential and commercial pool operators. Unit volumes concentrate in North American and Australian residential construction, with replacement demand following 7-10 year product lifecycles.
- Fountains:Architectural-grade systems with DMX control integration and corrosion-resistant alloy housings command premium pricing. UAE megaproject developers in Dubai specify these for waterfront landmarks, requiring decade-long performance guarantees and on-site commissioning support.
- Aquariums:Multi-spectrum programmable arrays support marine ecosystem research and public exhibit lighting. Research institutions in Japan and Germany deploy these for biological observation applications.
- Decorative Lighting:Submersible accent fixtures for landscape and hospitality applications prioritize aesthetic flexibility over extreme depth rating.
Swimming pools sustain the broadest installed base while fountain applications generate the highest revenue per fixture; fountain specification is expanding most quickly in Middle Eastern architectural developments.
End User:
Procurement authority and warranty requirements diverge sharply between individual buyers and institutional tender processes.
- Residential:Individual homeowners and pool contractors purchase through distributor channels with standard warranty terms. Volume concentrates in suburban construction markets across the United States and Australia.
- Commercial:Hospitality operators, marina developers, and retail property managers issue specification-driven tenders with extended warranty requirements. Dubai waterfront developers exemplify this segment's procurement consolidation around full-service contractors.
- Government:Municipal fountain projects, naval vessel retrofits, and research institution procurements mandate multi-jurisdiction certification compliance and documented supply chain transparency.
- Industrial:Offshore platform operators and aquaculture facilities prioritize thermal management and pressure rating over aesthetic programmability.
Residential drives unit volumes while commercial concentrates value; government specification is climbing the fastest as infrastructure stimulus and environmental monitoring budgets expand.
Installation Type:
Supply concentration favors integrated system providers over component suppliers as marina developers consolidate vendor relationships.
- Fixed:Permanent through-hull and niche-mounted fixtures with hardwired electrical connection dominate marine and pool construction. Mediterranean superyacht builders specify these during new construction and major refits.
- Modular:Field-replaceable LED engines and driver modules enable upgrade without full fixture replacement. This architecture supports asset-light leasing models for mid-size fleet operators.
- Portable:Battery-powered and magnetically mounted units serve temporary inspection, maintenance, and emergency lighting needs.
- Integrated:Factory-sealed luminaires with embedded controls and IoT connectivity enable remote diagnostics and predictive maintenance contracts.
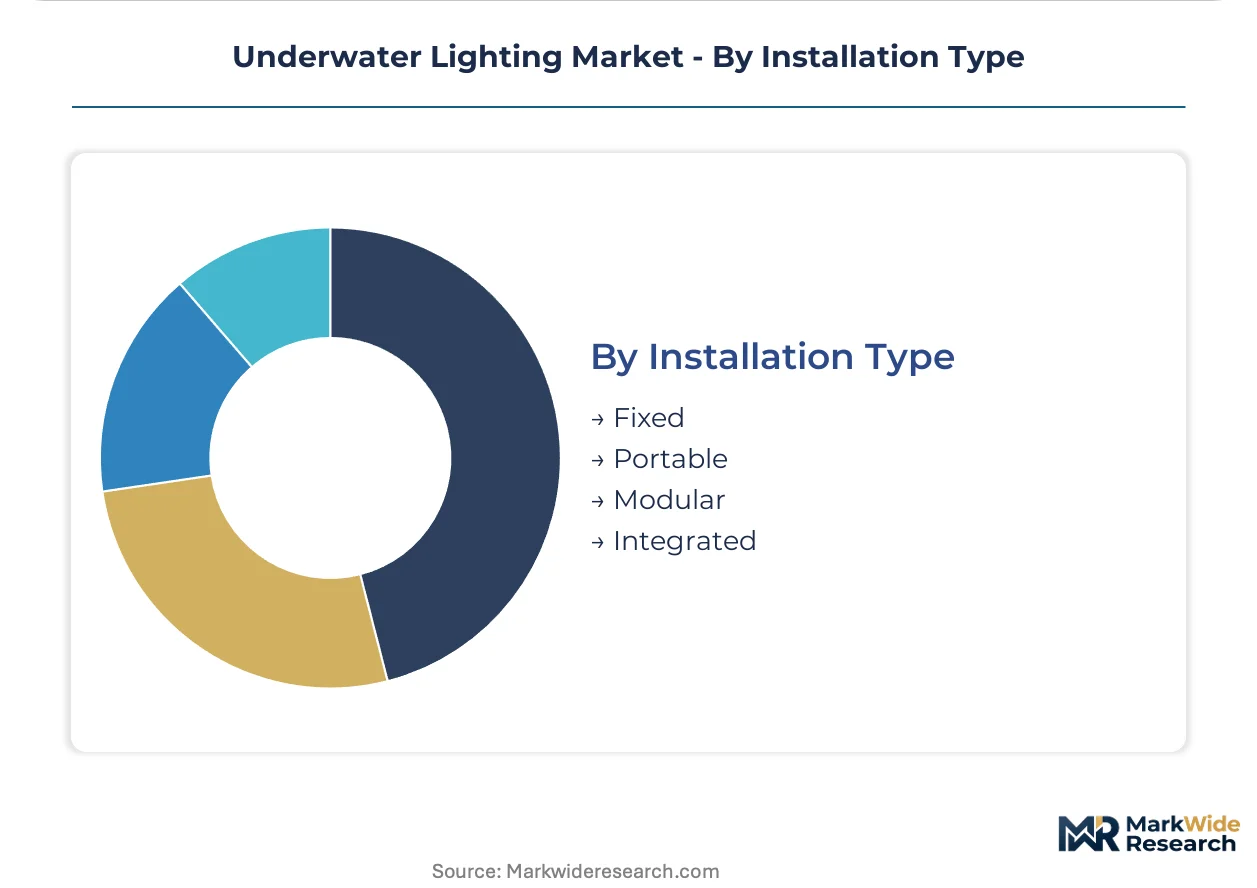
Fixed installation retains the largest installed base while integrated systems are gaining share fastest as smart marina convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United Arab Emirates exceeds that of Mediterranean refit yards by substantial margins, driven by megaproject scale and single-source tendering. Dubai waterfront developers command decade-long performance guarantees that compress supplier margins elsewhere. This asymmetry shapes how manufacturers allocate certification investments and inventory across geographies.
United Arab Emirates
Dubai's waterfront megaprojects generate concentrated demand for IP68-rated architectural fountain systems with DMX control integration. MOHAP electrical safety certifications mandate documented supply chain transparency for all luminaire imports. Developers in the Dubai Marina and Palm Jumeirah districts issue single-source tenders to full-service contractors capable of delivering integrated lighting with predictive maintenance contracts.
United States
Residential pool construction across Florida, Texas, and California sustains standardized fixture volumes with 7-10 year replacement cycles. EPA Clean Water Act discharge standards for vessel maintenance create regulatory tailwinds for sealed LED retrofits that reduce chemical cleaning frequency. Miami-Dade marina operators are consolidating vendor relationships around IoT-enabled dock management systems with remote diagnostics capabilities.
Italy
Mediterranean superyacht refit yards in Genoa and Viareggio accelerate LED installations as IMO environmental guidelines tighten vessel energy efficiency mandates. CE marking under EU RoHS and REACH frameworks constrains hazardous substance content in corrosion-resistant alloy housings. Italian marine lighting contractors are absorbing compliance costs by prioritizing pre-certified fixture families to accelerate project approvals.
Australia
Residential pool markets in New South Wales and Queensland drive standardized IP68 fixture volumes with ABS housings and epoxy potting. The country's national electrical safety regulator enforces stringent ingress protection standards for submersible luminaires in saltwater environments. Sydney-based distributors are expanding modular LED engine offerings to support field-replaceable upgrades without full fixture replacement.
Germany
Research institutions in Hamburg and Kiel deploy multi-spectrum programmable LED arrays for marine ecosystem monitoring and biological observation applications. ECHA REACH compliance requirements extend to corrosion-resistant alloy compositions in luminaire housings sold across European marinas. German marine lighting specialists are digitizing fixture-level control architectures to enable real-time spectrum adjustment for scientific deployments.
Underwater Lighting Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying standardized modules across multiple vessel classes. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates with captive distribution networks, marine-specialized fixture manufacturers with saltwater immersion expertise, and lighting-focused technology companies leveraging component scale. Competitive moves concentrate on vendor relationship consolidation with marina developers and certification pre-positioning for multi-jurisdiction compliance.
Among diversified electrical conglomerates, Signify Holding and Eaton Corporation exemplify contrasting approaches to market access. Signify leverages component scale advantages to supply standardized LED modules across vessel classes and architectural applications. Eaton anchors its position through captive distribution relationships with commercial marina developers. Marine-specialized fixture manufacturers including Lumishore occupy positions defined by through-hull engineering capabilities and integrated thermal management systems for continuous saltwater immersion.
| Leading Market Players |
|---|
| Signify Holding |
| Eaton Corporation |
| Acuity Brands |
| Hayward Industries |
| Lumishore |
| Aqualuma LED Lighting |
| T-H Marine Supplies |
| OceanLED Marine |
| Shadow Caster |
| Others |
Supply Flow & Price Mechanics
Dongguan electronics clusters anchor LED driver and control module fabrication, with capacity utilization swings in Guangdong Province transmitting directly into fixture pricing power across Mediterranean refit yards and Dubai waterfront developers. Pressure-compensated housing costs hinge on titanium and marine-grade stainless steel availability from specialty alloy mills, compressing margins when raw material volatility spikes.
Pricing Analysis
The customization-premium spread spans 3-5x between standard IP68 pool fixtures and architect-configured fountain systems with DMX integration and decade-long performance guarantees. Project-based pricing dominates fountain and superyacht segments, while per-unit transactional models serve residential pool replacement cycles. Price differentiation rests on certification tier—CE marking under REACH versus basic IP68 compliance—and after-sales service bundling. Cost compression in standard residential tiers is intensifying because ABS housing suppliers compete on volume scale. Commercial marina developers exhibit lowest price sensitivity; individual homeowners through distributor channels show highest.
Supply Chain Analysis
Export-control regimes limiting semiconductor fabrication equipment constrain LED driver chip availability from Taiwanese and South Korean foundries, extending lead times for multi-channel programmable arrays. Component sourcing draws from China for ABS housings and epoxy potting, Japan for high-reliability LEDs, and Germany for corrosion-resistant alloy formulations. Single-source vulnerability concentrates in specialized pressure-compensated sealing technologies. Distribution runs through full-service lighting contractors in commercial segments, with traditional distributors retaining residential pool channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as IMO environmental deadlines force mandatory LED retrofit waves across aging Mediterranean superyacht fleets. Replacement cycles compress when regulatory compliance windows narrow.
For Market Incumbents: Entrench position through backward integration into pressure-compensated housing production and captive certification investment for simultaneous FAA marine lighting, EPA discharge standard, and UAE MOHAP compliance. Consolidate vendor relationships with Dubai waterfront developers around predictive maintenance contracts to lock out modular competitors. Threat substitution from asset-light leasing models erodes traditional fixture-only margins.
For New Entrants and Emerging Players: Build out modular LED engine architectures targeting mid-size fleet operators priced out of full fixture replacement, penetrating the asset-light retrofit white space in Mediterranean marinas. Field-replaceable thermal management modules offer lowest barrier to specification entry. Go-to-market through marine electrical contractors rather than distributor channels.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because multi-jurisdiction certification complexity creates durable moats around pre-approved fixture families. Target acquisition archetype: marine-specialized manufacturers with through-hull saltwater immersion expertise and existing CE marking documentation. Signal to watch: IMO efficiency mandate acceleration triggering superyacht refit yard capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | Simultaneous FAA, EPA, and UAE MOHAP approvals compress competitor launch timelines by 18-24 months. |
| Backward Integration into Housing | In-house production of pressure-compensated titanium enclosures insulates margin from alloy price volatility. |
| Predictive Maintenance Contracts | IoT-enabled remote diagnostics shift revenue from transactional fixture sales to recurring service streams with Dubai developers. |
| Modular LED Engine Architecture | Field-replaceable thermal management modules enable asset-light leasing models for mid-size Mediterranean fleet operators. |
| Smart Marina Platform Integration | Convergence with dock management systems in Miami-Dade and Dubai Marina creates specification lock-in for integrated suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from superyacht refit yard procurement directors, marine lighting specification engineers, commercial marina developers, and UAE waterfront project managers, and refined through secondary validation. Primary interviews explored IMO compliance timelines, fixture replacement cycle compression, and certification investment thresholds. Secondary sources included customs trade data for LED fixture imports, SEC filings from diversified electrical conglomerates, EU RoHS and REACH regulatory databases, and Dubai South development authority procurement records. Bottom-up unit demand modeling triangulated against top-down market value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and installation architecture. Modeled variables included LED penetration rates by vessel class, fountain specification intensity by megaproject scale, and modular upgrade adoption curves. CAGRs derived from replacement cycle acceleration under tightening environmental mandates and biological observation application expansion. Industry-specific forecast inputs incorporated superyacht refit yard capacity utilization and Dubai waterfront development pipeline visibility.
Stress conditions across titanium alloy price volatility, semiconductor lead time extension, and IMO deadline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and megaproject completion schedules. Material shifts in IMO environmental guideline implementation timelines or UAE MOHAP electrical safety certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Massive Machine Type Communication in Healthcare Market
Others
Pickup Truck Market
Others
Liposomes Market
Others
Middle East Location-Based Services Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Global Solder Balls Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
South America Halal Food and Beverages Market
Others
Global Video Processing Platform Market
Others
Propanil Market
Others
China Automotive LED Lighting Market
Others
Cloud Broadcasting Solutions Market
Others
Triathlon Clothing Market
Others
Infant Fever Stickers Market
Others
DIY Smart Home Market
Others
Printed Leather Market