
 Global Surface Analysis Market | 2026-2036
Global Surface Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surface Analysis Market Foresight
Japanese instrument manufacturing is restructuring capacity around advanced-node semiconductor metrology. Thermo Fisher Scientific leverages its mass spectrometry portfolio to anchor North American academic and industrial laboratories. Bruker Corporation sustains R&D intensity in scanning probe techniques, while JEOL Ltd. dominates electron microscopy supply to Asian fabrication facilities.
Surface analysis encompasses techniques that probe elemental composition, topography, and chemical states at interfaces from angstroms to microns in depth. X-ray photoelectron spectroscopy detects binding energy shifts to identify oxidation states and thin-film stoichiometry with detection limits near parts per thousand. Scanning electron microscopes lead installed base volumes across semiconductor inspection workflows, where defect review at sub-ten-nanometer resolution commands premium pricing. Mass spectrometry segments grow fastest in pharmaceutical surface chemistry applications, driven by biosimilar characterization and impurity profiling mandates.
FDA device-quality regulations and EU MDR material-biocompatibility standards force pharmaceutical and aerospace OEMs to document surface chemistry with traceable analytical chains. ISO 17025 accreditation requirements shape laboratory procurement criteria, privileging vendors with embedded compliance architectures. Stakeholders must weigh capital intensity against outsourcing trends as contract analytical services expand in East Asian manufacturing corridors.
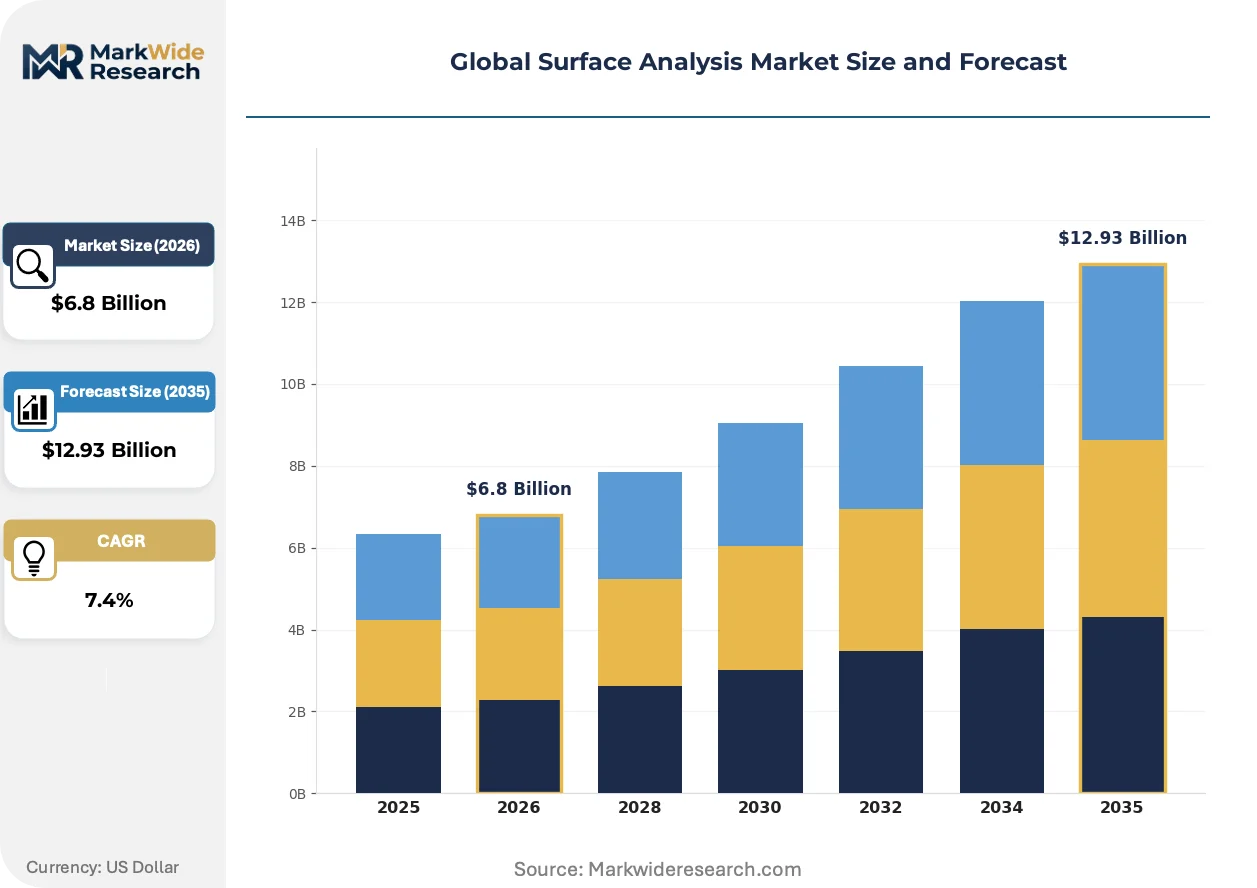
Market Dynamics
Semiconductor node shrinkage below three nanometers is forcing fabrication plants to triple metrology sampling density, compressing instrument utilization cycles and accelerating replacement timelines for legacy electron microscopy suites.
Growth Catalysts
- EU MDR material-biocompatibility mandates:Medical device manufacturers must document surface chemistry with traceable analytical chains, expanding contract laboratory demand for X-ray photoelectron spectroscopy verification.
- Taiwan and South Korea fabrication clusters:Concentrated capital expenditure on advanced-node production is concentrating metrology procurement in East Asian manufacturing corridors.
- Pharmaceutical biosimilar characterization:FDA impurity profiling requirements for generic injectables are driving secondary ion mass spectrometry adoption for surface chemistry mapping.
Market Restraints
- Helium supply concentration:Mass spectrometry and cryogenic sample preparation depend on concentrated extraction from Qatar and Algeria, creating input cost volatility and allocation risk.
- Electron microscope technical limitation:Charging artifacts on non-conductive pharmaceutical polymers require conductive coating workflows that degrade native surface chemistry data.
- ISO 17025 accreditation friction:Laboratory certification timelines stretch twelve to eighteen months, delaying revenue recognition for new analytical service entrants.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO tightening of active pharmaceutical ingredient surface purity standards creates first-mover advantage for accredited contract laboratories in Hyderabad and Ahmedabad clusters.
- Time-of-flight secondary ion mass spectrometry convergence:Integration with cluster ion sources enables molecular depth profiling for three-dimensional pharmaceutical distribution mapping.
- Remote diagnostics channel innovation:Instrument vendors are unbundling predictive maintenance from hardware sales, creating recurring revenue streams through cloud-connected vacuum system monitoring.
Industry Challenges
- Surface scientist skill scarcity:Specialized expertise in binding energy interpretation and charge compensation protocols is concentrating in senior cohorts nearing retirement.
- Ultra-high vacuum system capex intensity:Chamber conditioning and pump infrastructure consume forty percent of instrument lifecycle cost, straining mid-tier laboratory capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surface Analysis Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomic Force Microscopes, Scanning Electron Microscopes, X-ray Photoelectron Spectroscopy, Secondary Ion Mass Spectrometry, Auger Electron Spectroscopy, Optical Profilers Technology: Electron Microscopy, Mass Spectrometry, Spectroscopy, Optical Imaging, Scanning Probe Techniques, Chromatography Application: Semiconductor Inspection, Material Characterization, Thin Film Analysis, Forensic Examination, Corrosion Study, Surface Chemistry Industry Vertical: Electronics Manufacturing, Aerospace Engineering, Pharmaceuticals, Chemicals Production, Academic Research, Automotive OEMs |
| Companies Covered | Shimadzu Corporation, HORIBA Ltd., Thermo Fisher Scientific Inc., Oxford Instruments plc, JEOL Ltd., KLA Corporation, Bruker Corporation, Agilent Technologies Inc., Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surface Analysis Market Shifts & Advancements
Automation architectures are displacing manual sample handling in high-throughput semiconductor inspection, while regulatory data integrity requirements are reshaping instrument software validation protocols across pharmaceutical quality control laboratories.
Time-of-flight secondary ion mass spectrometry is modularizing around interchangeable ion source architectures. Semiconductor failure analysis laboratories in Taiwan and South Korea are adopting source-switching configurations to toggle between gallium cluster and gas cluster modes within single analytical sequences. This modularity is compressing capital expenditure duplication across separate instruments for organic and inorganic surface characterization.
EU MDR Annex I general safety and performance requirements are mandating surface characterization for all implantable devices with patient contact exceeding thirty days. German and French notified bodies are rejecting submissions lacking X-ray photoelectron spectroscopy oxidation state documentation for metallic components. Orthopedic manufacturers are responding by embedding surface analysis protocols into design control files earlier in product development cycles.
After-sales service unbundling is fragmenting traditional instrument procurement. Pharmaceutical quality control departments in Switzerland and the United States are separating hardware acquisition from application support contracts, soliciting third-party method development from specialized consultancies. This disintermediation is pressuring original equipment manufacturers to defend recurring revenue through captive reagent and consumable lock-in rather than bundled service agreements.
Global Surface Analysis Market Segmentation
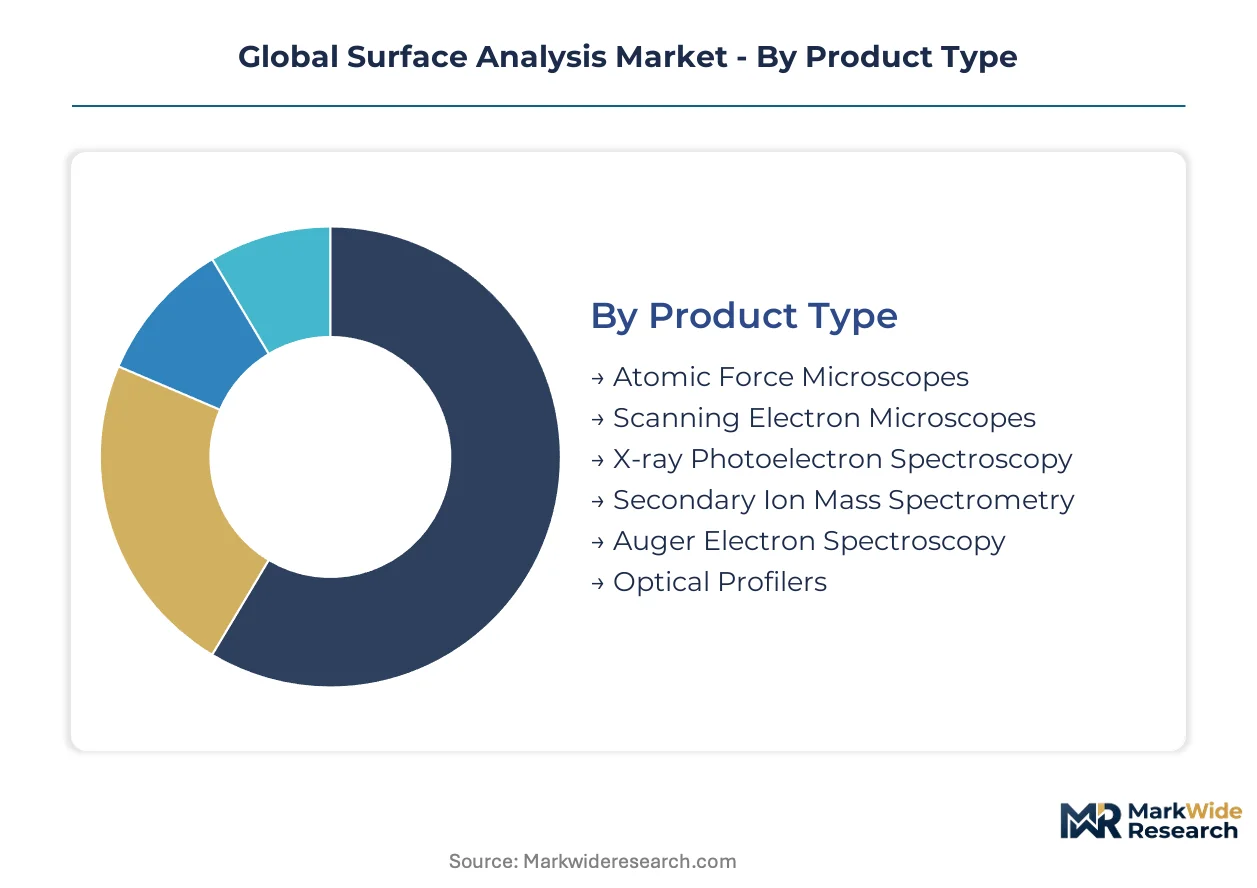
Surface analysis instrumentation procurement patterns diverge sharply across technology generations, with semiconductor fabs prioritizing resolution upgrades while pharmaceutical laboratories emphasize regulatory compliance architectures. Understanding these segment boundaries clarifies where replacement cycles concentrate and which modalities capture expanding metrology budgets.
Product Type:
Upgrade cycles across product categories reflect diverging resolution requirements and vacuum system complexity, with legacy electron microscopy suites facing accelerated replacement timelines below three-nanometer node production.
- Scanning Electron Microscopes:These systems dominate installed base volumes through sub-ten-nanometer defect review capabilities. Taiwan and South Korea fabrication clusters command premium pricing for immersion lens configurations that resolve charging artifacts on non-conductive layers.
- X-ray Photoelectron Spectroscopy:Binding energy detection enables oxidation state identification and thin-film stoichiometry quantification. FDA and EU MDR material-biocompatibility mandates are expanding pharmaceutical and medical device procurement of these systems for traceable analytical chains.
- Atomic Force Microscopes:Scanning probe techniques resolve angstrom-scale topography for thin film metrology.
- Secondary Ion Mass Spectrometry:Surface chemistry mapping with parts-per-million detection limits serves pharmaceutical impurity profiling requirements.
- Auger Electron Spectroscopy:Elemental microanalysis at nanometer spatial resolution supports semiconductor failure analysis workflows.
- Optical Profilers:Non-contact three-dimensional surface measurement addresses mid-tier laboratory capital constraints.
Scanning Electron Microscopes sits at the top of the volume ranking, with X-ray Photoelectron Spectroscopy climbing the fastest.
Technology:
Technology selection in procurement decisions tracks the tension between capital intensity and analytical specificity, with mass spectrometry segments gaining share in pharmaceutical applications while electron microscopy retains semiconductor dominance.
- Electron Microscopy:Scanning and transmission configurations provide morphological imaging with nanometer resolution. East Asian fabrication corridors concentrate demand for aberration-corrected systems that resolve atomic lattice structures.
- Mass Spectrometry:Time-of-flight and quadrupole analyzers enable molecular identification with high mass accuracy. Biosimilar characterization requirements from FDA impurity profiling protocols are accelerating Secondary Ion Mass Spectrometry adoption for surface chemistry mapping.
- Spectroscopy:X-ray and ultraviolet techniques probe electronic structure and elemental composition.
- Optical Imaging:Confocal and interferometric methods serve rapid screening applications with lower vacuum requirements.
- Scanning Probe Techniques:Atomic force and scanning tunneling modalities resolve surface topography without electron beam damage.
- Chromatography:Surface-sensitive separations support pharmaceutical quality control workflows.
Electron Microscopy commands the largest installed base, though Mass Spectrometry is expanding most quickly in pharmaceutical surface chemistry applications.
Application:
Application prioritization follows end-use regulatory intensity, with semiconductor inspection workflows demanding highest sampling density and medical device surface characterization requiring ISO 17025-accredited analytical chains.
- Semiconductor Inspection:Defect review and metrology sampling at sub-three-nanometer nodes triples instrument utilization cycles. Taiwan and South Korea fabrication plants are compressing replacement timelines for legacy electron microscopy suites.
- Surface Chemistry:Oxidation state documentation and molecular distribution mapping satisfy FDA device-quality and EU MDR material-biocompatibility standards. German and French notified bodies are rejecting submissions lacking X-ray photoelectron spectroscopy verification for implantable devices.
- Material Characterization:Grain boundary analysis and phase identification support aerospace alloy development.
- Thin Film Analysis:Stoichiometry and thickness measurements guide semiconductor process control.
- Forensic Examination:Trace evidence surface analysis requires non-destructive multi-modal approaches.
- Corrosion Study:Oxide layer characterization informs pipeline and infrastructure maintenance schedules.
Semiconductor Inspection leads procurement volume, while Surface Chemistry is gaining share fastest on regulatory mandate expansion.
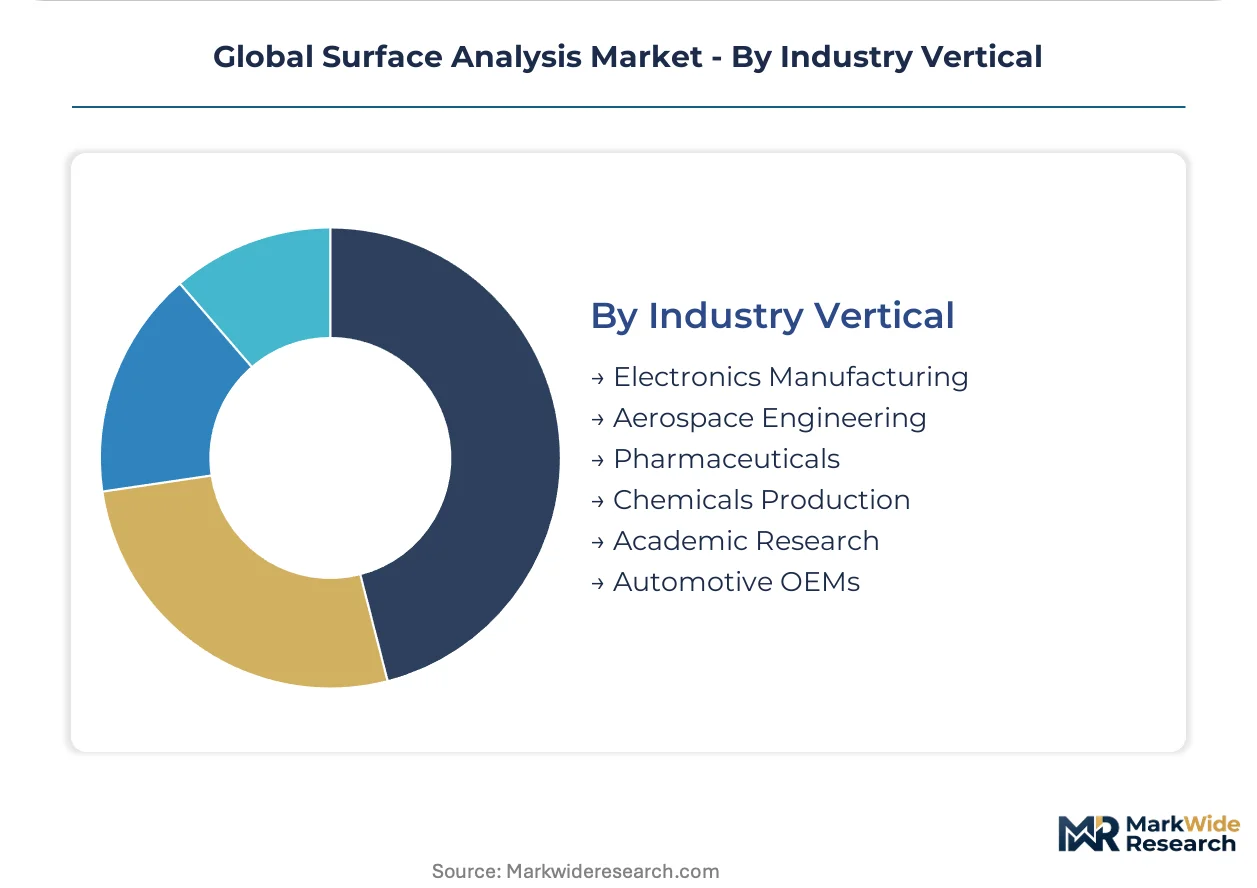
Industry Vertical:
Vertical demand patterns reflect diverging compliance architectures, with electronics manufacturing prioritizing throughput automation and pharmaceutical laboratories emphasizing method validation documentation.
- Electronics Manufacturing:Advanced-node production in Taiwan and South Korea concentrates capital expenditure on automated inspection workflows. Node shrinkage below three nanometers is forcing fabrication plants to triple metrology sampling density.
- Pharmaceuticals:Biosimilar characterization and impurity profiling mandates from FDA regulations are driving Secondary Ion Mass Spectrometry adoption. CDSCO tightening of active pharmaceutical ingredient surface purity standards in India is creating first-mover opportunities for accredited contract laboratories.
- Aerospace Engineering:Material verification for turbine alloys and composite interfaces requires traceable analytical chains.
- Chemicals Production:Catalyst surface characterization supports process optimization and yield improvement.
- Academic Research:Thermo Fisher Scientific mass spectrometry portfolios anchor North American university laboratories.
- Automotive OEMs:Battery electrode surface analysis supports electric vehicle manufacturing scale-up.
Electronics Manufacturing dominates capital deployment, with Pharmaceuticals expanding most quickly on regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pharmaceutical surface analysis contracts toward jurisdictions where ISO 17025 accreditation costs compress margins less severely than in Western Europe. Fabrication clusters in East Asia exploit this compliance-cost gap to capture medical device metrology work.
United States
FDA device-quality mandates and IRA pharmaceutical manufacturing incentives are expanding metrology procurement. EPA emission standards for vacuum pump systems add operational compliance layers. Boston and San Diego biotechnology corridors are concentrating X-ray photoelectron spectroscopy capacity for implantable device characterization.
Germany
EU MDR Annex I requirements are forcing orthopedic manufacturers to document oxidation states for metallic implants. ANSM and notified body scrutiny in France and Germany is rejecting submissions lacking traceable analytical chains. Bavarian medical technology clusters around Munich are embedding surface analysis into design control protocols earlier in development cycles.
Taiwan
Advanced-node semiconductor production below three nanometers is tripling metrology sampling density. Ministry of Economic Affairs capital subsidies support aberration-corrected electron microscopy procurement. Hsinchu Science Park fabrication facilities are compressing replacement timelines for legacy inspection suites.
South Korea
MFDS pharmaceutical impurity profiling standards and semiconductor export controls are bifurcating instrumentation demand. Government R&D tax credits offset ultra-high vacuum system capex intensity. Seoul and Yongin manufacturing corridors are concentrating time-of-flight secondary ion mass spectrometry adoption for biosimilar surface chemistry mapping.
India
CDSCO tightening of active pharmaceutical ingredient surface purity standards is creating first-mover opportunities for accredited contract laboratories. PLI scheme incentives for medical device manufacturing are expanding metrology requirements. Hyderabad and Ahmedabad pharmaceutical clusters are attracting ISO 17025 certification investment ahead of enforcement deadlines.
Global Surface Analysis Market Competitive Landscape
Japanese and American producers anchor one tier; European specialists hold differentiated positions in spectroscopy and microscopy niches. The vendor base concentrates around five instrument archetypes, with electron microscopy and mass spectrometry commanding premium pricing power. Diversified conglomerates, focused instrument specialists, and contract analytical service providers represent the dominant strategic archetypes. Competitive moves center on unbundling after-sales service from hardware sales and expanding cloud-connected predictive maintenance offerings.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies exemplify scale-driven positioning across mass spectrometry portfolios. Bruker Corporation occupies a specialist position in scanning probe techniques. These three entities represent contrasting approaches to recurring revenue defense: captive consumable lock-in versus third-party method development partnerships versus embedded compliance architectures.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| HORIBA Ltd. |
| Thermo Fisher Scientific Inc. |
| Oxford Instruments plc |
| JEOL Ltd. |
| KLA Corporation |
| Bruker Corporation |
| Agilent Technologies Inc. |
| Carl Zeiss AG |
| Others |
Supply & Pricing Matrix
Semiconductor fabrication clusters in Taiwan and South Korea demanding aberration-corrected electron microscopy configurations are compressing lead times for ultra-high vacuum system components and elevating premium-tier pricing power for qualified suppliers.
Pricing Analysis
Distributor margins on mass spectrometry systems range from twelve to eighteen percent, while direct-to-OEM procurement of scanning electron microscopes commands volume discounts exceeding twenty percent. Three-tier pricing structure across premium, standard, and economy levels stratifies by vacuum system sophistication and embedded compliance software. Cost compression in mid-tier laboratory capital budgets is intensifying because helium supply volatility feeds into cryogenic sample preparation add-ons. Academic research institutions exhibit highest price sensitivity; semiconductor fabs show least sensitivity given node-shrinkage imperatives.
Supply Chain Analysis
ISO 17025 accreditation requirements for vacuum chamber conditioning and pump infrastructure create qualification gating that privileges incumbent Japanese and American instrument manufacturers. Ultra-high vacuum system assembly concentrates in Japan, Germany, and the United States; electron source fabrication rests on tungsten and lanthanum hexaboride supply from China and Russia. Single-source vulnerability in helium extraction from Qatar and Algeria threatens mass spectrometry input costs. Distribution runs through authorized regional service centers that bundle installation with method validation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surface analysis instrumentation hinges on unbundling predictive maintenance from hardware sales and capturing recurring revenue through cloud-connected vacuum system monitoring contracts.
For Market Incumbents: Extend captive consumable lock-in strategies to defend against third-party method development consultancies disintermediating application support contracts. Accelerate ISO 17025 accreditation investment in Indian contract laboratory partnerships ahead of CDSCO enforcement deadlines. Backward integration into ion source manufacturing reduces exposure to gallium and gas cluster supply concentration. For New Entrants and Emerging Players: The price-point gap between premium aberration-corrected systems and economy optical profilers creates entry space for modular time-of-flight secondary ion mass spectrometry configurations with interchangeable source architectures. Target pharmaceutical quality control departments in Switzerland and the United States separating hardware acquisition from service bundles. Lead with remote diagnostics channel innovation to bypass entrenched field service networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized consultancies possessing ISO 17025-accredited analytical chains and embedded relationships with German and French notified bodies. Five-to-ten year viability favors service providers over pure hardware manufacturers given after-sales unbundling trends. Watch for MFDS pharmaceutical impurity profiling standard revisions as inflection indicator for secondary ion mass spectrometry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Predictive Maintenance Unbundling | Transforms vacuum system monitoring into recurring revenue streams for instrument vendors. |
| ISO 17025 Accreditation Investment in India | Captures CDSCO-driven contract laboratory demand in Hyderabad and Ahmedabad clusters. |
| Modular Ion Source Architecture Development | Enables source-switching between gallium cluster and gas cluster modes within single sequences. |
| Third-Party Method Development Partnership | Defends position against pharmaceutical quality control departments separating hardware from support. |
| Helium Supply Diversification Program | Mitigates input cost volatility from concentrated Qatar and Algeria extraction. |
Research Methodology
Direct dialogue with semiconductor metrology directors, pharmaceutical quality control managers, contract laboratory operations heads, and vacuum system maintenance engineers grounded segmentation assumptions. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, SEC instrument manufacturer 10-K disclosures, and Taiwan Ministry of Economic Affairs capital subsidy records. Bottom-up and top-down triangulation reconciled instrument shipment data with fabrication cluster capex announcements.
Bottom-up modeling aggregated product-type, technology, application, and industry vertical dimensions across the analysis window. Top-down cross-checks applied semiconductor node-shrinkage timelines and pharmaceutical regulatory mandate expansion rates. CAGRs derived from regression against metrology sampling density multipliers and ISO 17025 accreditation timeline compression. Helium supply concentration indices and electron microscope replacement cycle data informed scenario weighting.
The model assumes a particular technology adoption path; alternative pathways for time-of-flight secondary ion mass spectrometry convergence with cluster ion sources would alter the outlook. Forecasts reflect assumptions about EU MDR enforcement intensity and East Asian fabrication cluster capital deployment sequencing. A model refresh is warranted upon material change in FDA device-quality regulation scope or helium allocation policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Canada 3D Printing Construction Market
Others
Global Hair Loss Treatment Products Market
Others
Smart Home Service Market
Others
South Korea Intellectual Property Market
Others
CAR T Cell Therapy Market
Others
Pet Care Packaging Market
Others
North America Video Conferencing Hardware Market
Others
Roasted Wheat Market
Others
Asia-Pacific Social Media Management Market
Others
Pediatric Measuring Devices Market
Others
United States Bean Bags Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Radar Speed Signs Market
Others
Europe Electric Forklift Market
Others
Asia-Pacific Road Safety Market
Others
Surface Green Mining Market