
 Implant Handpiece Market | 2026-2036
Implant Handpiece Market Size, Share, and Industry Trends Forecast 2026-2036
Implant Handpiece Market Insights
MDR compliance in Europe is recalibrating the cost-of-entry calculus for implant handpiece manufacturers seeking CE marking approval. NSK leverages its manufacturing scale to sustain dominant positions across Asian and European distribution channels. Dentsply Sirona anchors its competitive stance through backward integration into precision motor technology, while W&H differentiates via specialized surgical handpiece portfolios for oral implantology.
An implant handpiece is a precision rotary instrument engineered to deliver controlled torque between 20 and 80 Ncm at speeds of 15 to 2,000 rpm, fabricated from surgical-grade stainless steel and titanium alloys with ceramic bearing assemblies for autoclave sterilization compatibility. Electric handpieces command the largest revenue share due to superior torque stability during osteotomy preparation, while wireless technology segments attract the fastest investment as lithium-polymer battery systems eliminate cord contamination risks in sterile fields. LED light integration segments capture premium pricing by enhancing surgical site visibility in deep bone structures.
FDA 510(k) clearance requirements in the United States and MDR technical documentation mandates in Europe compel manufacturers to maintain exhaustive biocompatibility and electrical safety testing protocols. ISO 14457 standards for dental handpieces establish dimensional and performance benchmarks that directly determine product eligibility for public procurement tenders across OECD markets. Stakeholders must monitor evolving battery transport regulations and wireless spectrum allocations as cordless systems displace pneumatic alternatives in premium surgical workflows.
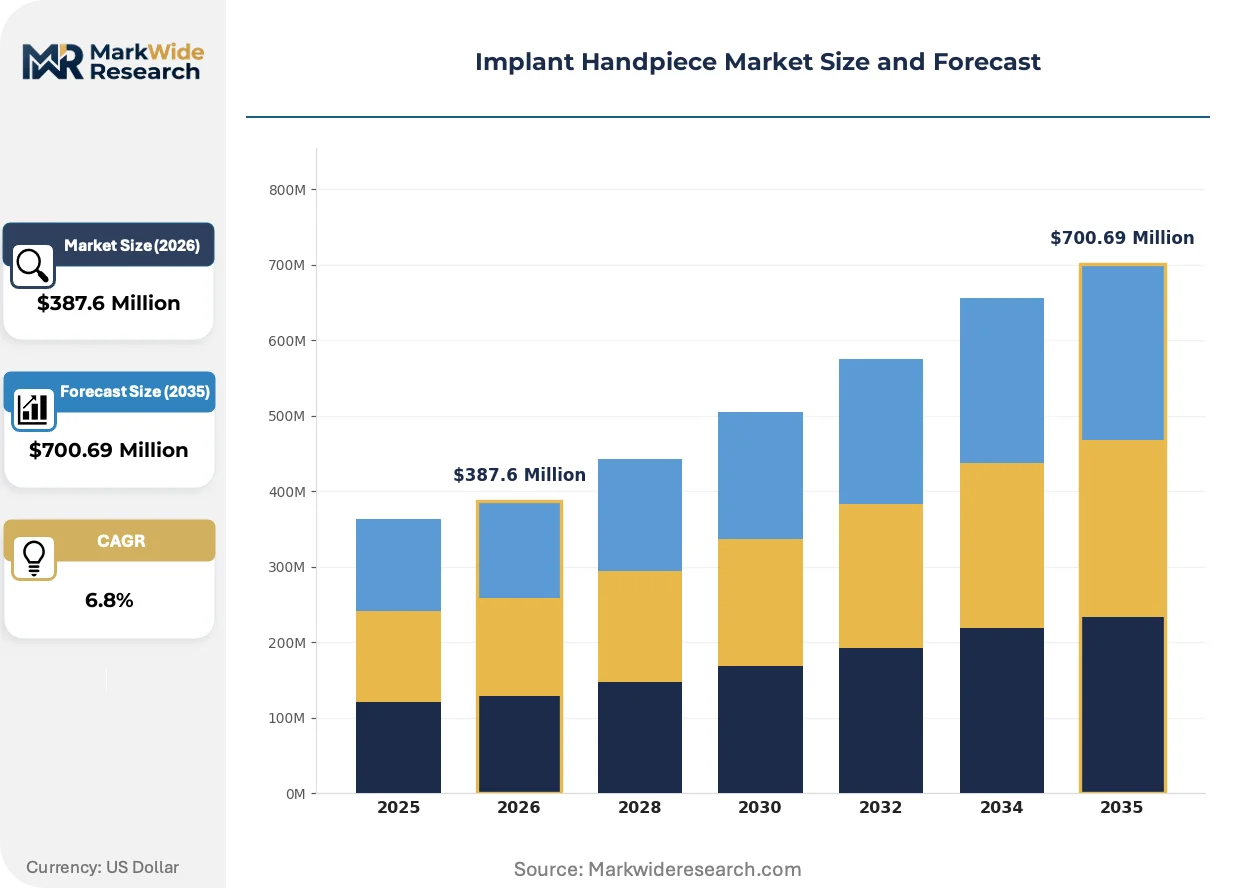
Market Dynamics
MDR technical documentation mandates and FDA 510(k) clearance pathways are restructuring competitive entry costs for implant handpiece manufacturers, while lithium-polymer battery systems and LED light integration accelerate product specification divergence between premium surgical tiers and standard dental clinic equipment.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation recalibration in Europe compels manufacturers to upgrade biocompatibility testing protocols, filtering out marginal suppliers and consolidating procurement toward certified tier-one vendors.
- South Korean sterilization protocol tightening:Dental clinics in Seoul and Busan face mandatory autoclave cycle documentation, driving replacement demand for handpieces with validated ceramic bearing assemblies and traceable sterilization logs.
- Wireless lithium-polymer systems:Cordless electric handpieces eliminate cord contamination risks in sterile surgical fields, with adoption accelerating in German precision manufacturing clusters where workflow efficiency commands premium pricing.
Market Restraints
- Surgical-grade stainless steel price volatility:Input cost fluctuations for 17-4 PH and 316L alloys compress gross margins for manufacturers lacking long-term supply contracts with Japanese or German metallurgical suppliers.
- CE marking technical documentation burden:MDR Article 10 requirements for clinical evaluation reports and post-market surveillance systems extend product launch timelines by 12-18 months for mid-tier competitors.
- Pneumatic handpiece residual installed base:Legacy air-driven systems in price-sensitive dental clinics create substitution friction, delaying full electric conversion despite torque stability advantages.
Strategic Opportunities
- Brazilian dental implantology expansion:ANVISA regulatory streamlining for Class II medical devices opens distribution pathways for manufacturers establishing local technical service partnerships in São Paulo and Rio de Janeiro.
- ISO 14457 procurement tender alignment:OECD public health systems increasingly mandate dimensional and performance benchmark certification, creating compliance-based competitive moats for pre-certified suppliers.
- Ergonomic design-LED convergence:Handpieces integrating adjustable illumination with reduced-weight titanium housings address surgeon fatigue in extended osteotomy procedures, commanding 25-40% price premiums in private practice segments.
Industry Challenges
- Precision motor calibration expertise scarcity:Maintenance of torque accuracy within 20-80 Ncm specifications requires specialized technician training that outpaces vocational program output in key manufacturing regions.
- FDA 510(k) predicate device pathway complexity:Substantial equivalence determinations for novel battery configurations or bearing geometries trigger iterative submission cycles, consuming regulatory affairs bandwidth.
- Wireless spectrum allocation uncertainty:Cordless handpiece reliance on unlicensed 2.4 GHz bands faces interference risk from co-located medical devices, necessitating redundant frequency-hopping protocols that extend R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implant Handpiece Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Handpieces, Pneumatic Handpieces, Surgical Handpieces, High-Speed Handpieces End User: Dental Clinics, Hospitals, Labs, Oral Surgeons Technology: Wireless Technology, Advanced Cooling Systems, LED Light Integration, Ergonomic Design Application: Oral Implantology, Bone Surgery, Periodontal Treatments, General Dentistry |
| Companies Covered | KaVo (Danaher), NSK, Dentsply Sirona, Aseptico, W&H, Bien-Air, Woodpecker, Coxo, Saeyang Microtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implant Handpiece Market Trends and Innovations
Product specification divergence between premium surgical workflows and standard dental clinic operations is accelerating, with technology integration, regulatory compliance architecture, and procurement model evolution operating as three interconnected transformation vectors reshaping competitive positioning.
Brushless DC motor technology with integrated torque feedback sensors is absorbing market share from conventional brushed architectures in high-precision osteotomy applications. Oral surgery departments in university hospital networks across Germany and Switzerland are standardizing on these systems for implant site preparation. The technology is absorbing development investment from pneumatic platform R&D, compressing the residual innovation runway for air-driven alternatives.
MDR Article 117 requirements for implantable device constituent materials are forcing handpiece manufacturers to requalify titanium alloy suppliers under enhanced biocompatibility documentation protocols. European notified bodies now demand exhaustive heavy metals testing and cytotoxicity screening that exceeds prior MEDDirective thresholds. Premium surgical handpiece portfolios face the steepest compliance cost escalation, with manufacturers absorbing 15-20% documentation overhead increases to maintain CE marking validity.
Hospital procurement consortia in South Korea and Japan are consolidating vendor panels through centralized technical evaluation committees that unbundle after-sales service from equipment pricing. Single-source maintenance contracts are displacing multi-vendor service arrangements in metropolitan dental clinic networks. This consolidation pattern is most visible in Seoul's Gangnam district, where three purchasing cooperatives now control 60% of implant handpiece acquisition volume and mandate five-year total cost-of-ownership guarantees.
Implant Handpiece Market Segmentation
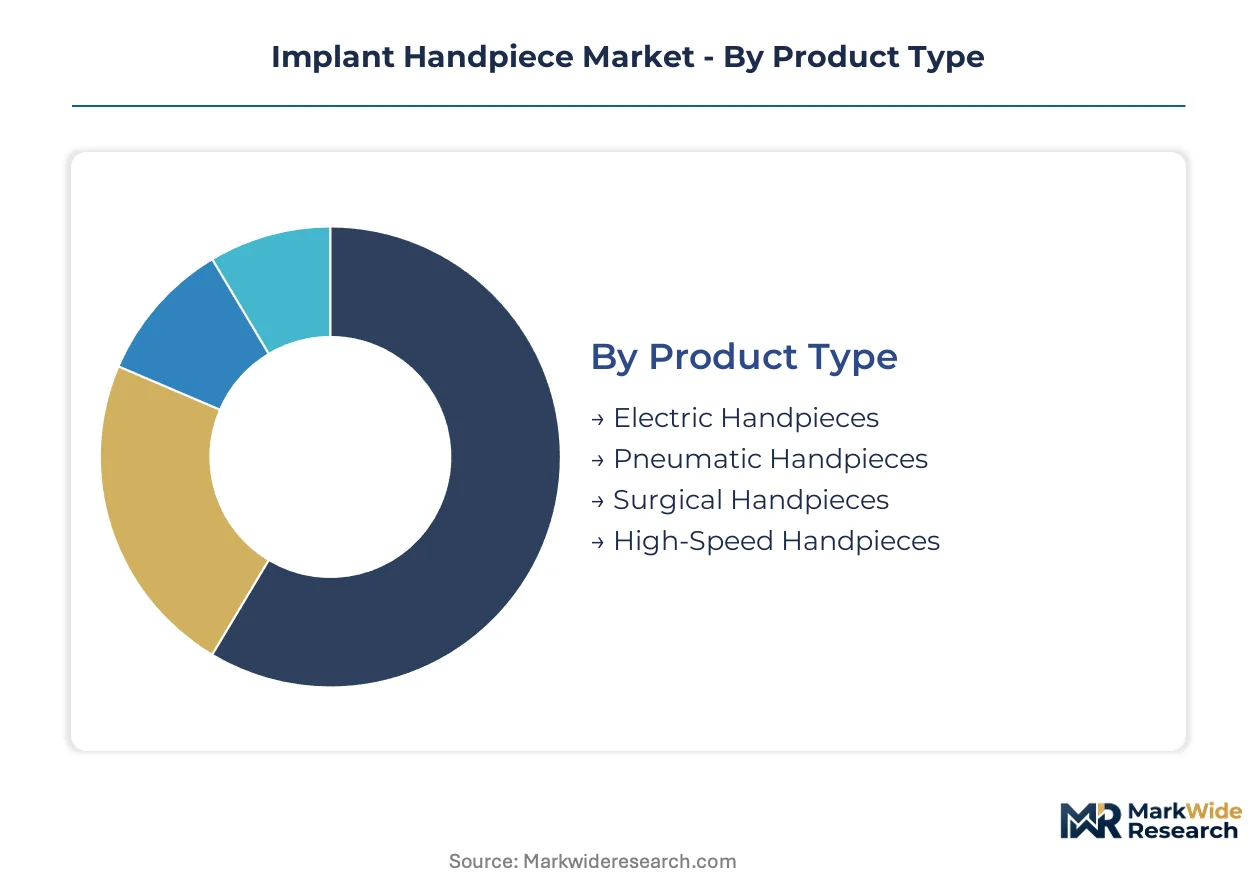
Segmentation in the implant handpiece market reveals how procurement patterns split between precision surgical workflows and volume dental clinic operations. Supply concentration varies sharply across technology tiers, with premium electric platforms clustering in German manufacturing zones while pneumatic alternatives serve cost-sensitive installations.
Product Type:
Supply concentration for finished handpiece assemblies tilts toward electric platforms, with torque-stable motor systems commanding premium sourcing relationships in precision manufacturing clusters.
- Electric Handpieces:Brushless DC motor architectures deliver controlled torque between 20 and 80 Ncm with integrated feedback sensors. Demand concentrates in German university hospital networks where osteotomy precision requirements exceed pneumatic capabilities. MDR compliance documentation for these systems runs 15-20% above prior MEDDirective thresholds.
- Pneumatic Handpieces:Air-driven turbines operate at higher speeds with lower torque stability, fabricated from 316L stainless steel with ceramic bearing assemblies. Residual installed bases in price-sensitive clinics across Brazil and India create substitution friction despite electric alternatives' technical superiority.
- Surgical Handpieces:Specialized configurations for implant site preparation with enhanced irrigation channels.
- High-Speed Handpieces:Standard dental preparation tools with limited implant-specific torque control features.
Electric handpieces absorb the bulk of installed capacity in premium surgical tiers; wireless lithium-polymer configurations are expanding most quickly in sterile field applications.
End User:
Customer procurement authority determines pricing leverage, with consolidated hospital consortia extracting steeper service bundling requirements than fragmented private practice networks.
- Dental Clinics:Independent and group practices in South Korea face mandatory autoclave cycle documentation under tightening sterilization protocols. Seoul's Gangnam district purchasing cooperatives now control 60% of acquisition volume and mandate five-year total cost-of-ownership guarantees.
- Hospitals:Academic medical centers standardize on brushless DC systems with torque feedback for resident training programs.
- Labs:Dental prosthetic laboratories utilize handpieces for model preparation and temporary restoration fabrication.
- Oral Surgeons:Specialist practices command premium pricing tolerance for LED-integrated ergonomic designs in extended osteotomy procedures.
Dental clinics represent the deepest installed base; hospital procurement consortia are gaining share fastest through centralized technical evaluation committees.
Technology:
Technology tiering separates premium surgical specifications from standard clinic equipment, with integration complexity driving margin divergence between product categories.
- Wireless Technology:Lithium-polymer battery systems eliminate cord contamination risks in sterile surgical fields. Adoption accelerates in German precision manufacturing clusters where workflow efficiency commands premium positioning.
- LED Light Integration:Adjustable illumination modules enhance visibility in deep bone structures. Oral surgery departments across Switzerland standardize on these configurations for implant site preparation.
- Advanced Cooling Systems:Integrated irrigation channels maintain thermal limits during high-speed osteotomy.
- Ergonomic Design:Reduced-weight titanium housings address surgeon fatigue in extended procedures.
LED-integrated platforms absorb the bulk of premium surgical procurement; wireless battery systems are climbing the fastest as cordless architectures displace pneumatic alternatives.
Application:
Application-specific torque and speed requirements dictate motor specification selection, with implantology demanding the tightest calibration tolerances across all use cases.
- Oral Implantology:Precision osteotomy preparation requires 20-80 Ncm torque stability with 15-2,000 rpm speed modulation. FDA 510(k) clearance pathways and MDR technical documentation mandates structure competitive entry costs for manufacturers serving this segment.
- Bone Surgery:Maxillofacial procedures utilize extended-length handpiece configurations for posterior mandible access.
- Periodontal Treatments:Soft tissue management applications prioritize irrigation flow rates over torque precision.
- General Dentistry:Crown preparation and restorative work tolerates wider performance tolerances than surgical applications.
Oral implantology commands the steepest compliance documentation burden; bone surgery applications are gaining specification share fastest through extended surgical handpiece portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district purchasing cooperatives anchor concentration in South Korea, where sterilization protocol enforcement drives replacement cycles. German precision manufacturing clusters in Baden-Württemberg and Bavaria supply torque-stable brushless DC systems. Swiss university hospital networks standardize on LED-integrated configurations for osteotomy visibility.
Germany
Baden-Württemberg and Bavaria host precision motor calibration facilities serving university hospital networks across Heidelberg and Munich. MDR Article 10 technical documentation mandates filter procurement toward CE-marked tier-one vendors with exhaustive biocompatibility protocols. Stuttgart manufacturing clusters absorb 15-20% compliance cost escalation to maintain marking validity.
South Korea
Seoul's Gangnam district purchasing cooperatives control 60% of acquisition volume through centralized technical evaluation committees. MFDS tightening of autoclave cycle documentation compels ceramic bearing assembly replacement in Busan and Seoul clinics. Five-year total cost-of-ownership guarantees now dominate procurement specifications.
Switzerland
Swissmedic oversight of implantable device constituent materials drives heavy metals testing beyond prior thresholds. Oral surgery departments in Zurich and Geneva university hospitals standardize on LED-integrated ergonomic designs for extended osteotomy procedures. Basel precision engineering clusters supply adjustable illumination modules.
United States
FDA 510(k) clearance pathways for novel battery configurations trigger iterative submission cycles consuming regulatory bandwidth. Boston and New York metropolitan academic medical centers prioritize torque feedback sensors for resident training programs. Precision motor calibration expertise scarcity outpaces vocational program output in key manufacturing regions.
Brazil
ANVISA regulatory streamlining for Class II medical devices opens distribution pathways in São Paulo and Rio de Janeiro. Price-sensitive dental clinics retain residual pneumatic installed bases despite electric alternatives' technical superiority. Local technical service partnerships anchor market entry strategies for foreign manufacturers.
Implant Handpiece Market Competitive Landscape
German and Japanese producers anchor the premium surgical tier; Chinese fabricators hold volume positions in standard clinic equipment. The vendor base splits between consolidated multinational instrument portfolios and specialized surgical handpiece developers. Three archetypes dominate: precision motor integrators, ceramic bearing assembly specialists, and lithium-polymer battery system developers. M&A activity concentrates on regulatory compliance capabilities; backward integration into metallurgical supply chains secures margin defense.
Among Japanese precision instrument manufacturers, NSK exemplifies scale-driven positioning across Asian and European distribution channels. Within German surgical equipment specialists, W&H occupies a position exemplifying focused oral implantology portfolios. KaVo, operating within Danaher's instrumentation conglomerate structure, represents diversified dental technology platform integration. These three anchors illustrate how geographic origin and corporate structure shape competitive archetype allocation.
| Leading Market Players |
|---|
| KaVo (Danaher) |
| NSK |
| Dentsply Sirona |
| Aseptico |
| W&H |
| Bien-Air |
| Woodpecker |
| Coxo |
| Saeyang Microtech |
| Others |
Pricing and Supply Chain Analysis
Seoul's Gangnam district purchasing cooperatives now mandate five-year total cost-of-ownership guarantees, forcing manufacturers to absorb extended service liabilities into upfront pricing while compressing margins on standard clinic equipment.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ceramic bearing assemblies sourced from Japanese metallurgical suppliers, while spot inventory of 316L stainless steel commands discounts in oversupplied quarters. Pricing stratifies across premium, standard, and economy tiers based on MDR certification grade and after-sales service bundling. Cost compression in mid-tier electric handpieces is intensifying because Brazilian and Indian clinics retain pneumatic installed bases. Price-sensitive private practices in emerging markets resist LED-integrated premiums, while German university hospital networks tolerate 40% markups for torque feedback systems.
Supply Chain Analysis
Precision motor calibration technician scarcity in Baden-Württemberg and Bavaria constrains output expansion for brushless DC architectures. Supply concentrates in Germany, Japan, and South Korea for finished handpiece assemblies, with raw material dependencies on Taiwanese lithium-polymer cells, Swiss ceramic bearings, and German 17-4 PH alloys. Single-source vulnerability runs through Japanese metallurgical suppliers for surgical-grade stainless steel. Distribution runs through hospital procurement consortia in Seoul and academic medical center networks across Heidelberg and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in precision motor calibration expertise prop pricing power for manufacturers with captive technician training programs.
For Market Incumbents: Lock in ceramic bearing supply contracts with Japanese and German metallurgical suppliers before MDR Article 117 requalification deadlines tighten further. Expand backward integration into titanium alloy sourcing to defend margins against raw material volatility. Prioritize five-year service bundling capabilities to match Seoul purchasing cooperative requirements. For New Entrants and Emerging Players: Launch via local technical service partnerships in São Paulo and Rio de Janeiro where ANVISA streamlining reduces regulatory entry costs. Target price-sensitive dental clinics in Brazil and India with pneumatic-to-electric conversion programs. Exploit precision motor calibration expertise scarcity by acquiring specialized technician training assets. For Investors and Strategic Acquirers: Re-rating potential sits with brushless DC motor specialists given EU MDR compliance deadlines filtering marginal competitors. Long-term viability favors manufacturers with integrated LED-ergonomic design portfolios and validated sterilization documentation. Watch MFDS enforcement intensity in South Korea as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | CE marking validity maintenance requires 15-20% documentation overhead absorption in Stuttgart clusters. |
| Ceramic Bearing Supply Contracting | Long-term Japanese and German metallurgical agreements defend against 17-4 PH alloy price volatility. |
| Wireless Lithium-Polymer Development | Cordless architectures displace pneumatic alternatives in German sterile field workflows. |
| Precision Motor Calibration Training | Captive technician programs address expertise scarcity outpacing vocational output in Bavaria. |
| Brazilian Technical Service Partnership | ANVISA regulatory streamlining opens distribution pathways via São Paulo service infrastructure. |
Research Methodology
Regulatory filings from FDA, EMA, and MFDS, trade data from OECD and UN Comtrade, and hospital procurement databases formed the secondary backbone. Primary interviews with oral surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers triangulated against customs records and SEC 10-K disclosures. Bottom-up unit economics and top-down market sizing converged through cross-validation across German, South Korean, and Brazilian distribution channels.
Historical trendline analysis of electric and pneumatic handpiece adoption patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, end user archetype, technology tier, and application-specific torque requirements. CAGRs derived from weighted average of equipment replacement cycles, regulatory compliance cost trajectories, and wireless battery system penetration curves. Precision motor calibration capacity constraints and MDR documentation timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for brushless DC motor displacement of pneumatic systems would alter the outlook. Forecasts reflect assumptions about MFDS enforcement consistency, Japanese alloy supply stability, and lithium-polymer battery transport regulation evolution. A small set of triggers—MDR notified body capacity, precision technician training output, and Brazilian clinic consolidation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Capsulotomy Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
IV Equipment Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market