
 Endodontic Files Market | 2026-2036
Endodontic Files Market Size, Share, and Industry Trends Forecast 2026-2036
Endodontic Files Market Intelligence
The gap between premium nickel titanium rotary systems and commodity stainless steel hand files is recalibrating procurement patterns across dental supply chains. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to bundle file systems with imaging workflows, while VDW GmbH anchors its position through specialized endodontic training academies that lock in clinician loyalty. Brasseler USA differentiates by controlling Midwest US distribution density, allowing same-day replenishment for high-volume practices.
Endodontic files are precision-engineered instruments designed to mechanically debride and shape root canal systems, typically manufactured from nickel titanium or stainless steel alloys with taper designs ranging from 0.02 to 0.12 mm/mm and tip sizes standardized by ISO 15-140 color coding. Their primary purpose is to create a continuous tapered pathway from canal orifice to apex while preserving periapical tissue integrity, enabling subsequent obturation with gutta-percha and sealer. Nickel titanium rotary files now command the dominant margin pool due to superelasticity and cyclic fatigue resistance, though stainless steel retains volume in price-sensitive emerging markets and pediatric applications where canal morphology favors manual instrumentation. Synergistic hybrid systems combining reciprocation with continuous rotation represent the fastest-growing configuration, as manufacturers target complex anatomies like S-shaped and bifurcated canals that challenge conventional motion mechanics.
The FDA regulates endodontic files as Class II medical devices under 21 CFR 872.4760, requiring 510(k) premarket notification for substantial equivalence to predicate instruments, while the EU MDR mandates clinical evaluation reports and post-market surveillance under Annex IX for CE marking renewal. ISO 3630-1 standards govern dimensional tolerances and mechanical testing protocols, directly shaping R&D allocation toward fatigue-life validation and fracture resistance benchmarking. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA guidance on nickel ion release thresholds, as these will determine which alloy formulations and surface treatments secure market access across the two largest regulated jurisdictions.
Market Dynamics
Reciprocating motion mechanics are compressing the performance gap between single-file and multi-file systems, forcing manufacturers to justify premium positioning through metallurgical differentiation rather than step-count reduction alone.
Growth Catalysts
- Warm vertical compaction techniques:Endodontic practices in Germany and Switzerland are standardizing warm gutta-percha delivery systems that demand precisely tapered canal preparations, elevating specification requirements for rotary file tapers.
- EU MDR Annex IX clinical evaluation mandates:Post-market surveillance obligations for Class IIa devices are accelerating file system validation cycles and favoring manufacturers with established clinical data repositories.
- Nickel titanium superelastic alloys:Advanced thermal processing protocols are extending cyclic fatigue resistance thresholds, enabling single-file instrumentation in complex canal anatomies previously requiring multiple instruments.
Market Restraints
- Nickel price volatility:Aerospace and battery sector demand for nickel is compressing margin buffers for alloy-dependent file manufacturers without long-term supply contracts.
- Notified body capacity constraints under EU MDR:CE marking renewal backlogs are delaying product launches and freezing R&D roadmaps for mid-tier manufacturers without established European regulatory infrastructure.
- Stainless steel hand files:Commodity pricing in emerging markets and pediatric applications where canal morphology favors manual instrumentation limits nickel titanium penetration in volume segments.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating localized production hubs that can serve Southeast Asian markets with reduced import duty exposure.
- AI-powered canal mapping integration:Convergence of cone-beam computed tomography segmentation algorithms with file motor control systems is enabling real-time torque adjustment based on canal curvature prediction.
- Direct-to-clinic digital procurement platforms:Specialized dental supply marketplaces are disintermediating traditional distributor networks and capturing preference data that informs file system development priorities.
Industry Challenges
- ISO 3630-1 fatigue-life validation:Standardized mechanical testing protocols require capital-intensive equipment and specialized metrology expertise that smaller manufacturers struggle to access.
- Cross-platform motor compatibility:Proprietary file-to-motor communication protocols are fragmenting the installed base and forcing clinicians into single-vendor ecosystems that limit instrument choice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endodontic Files Market |
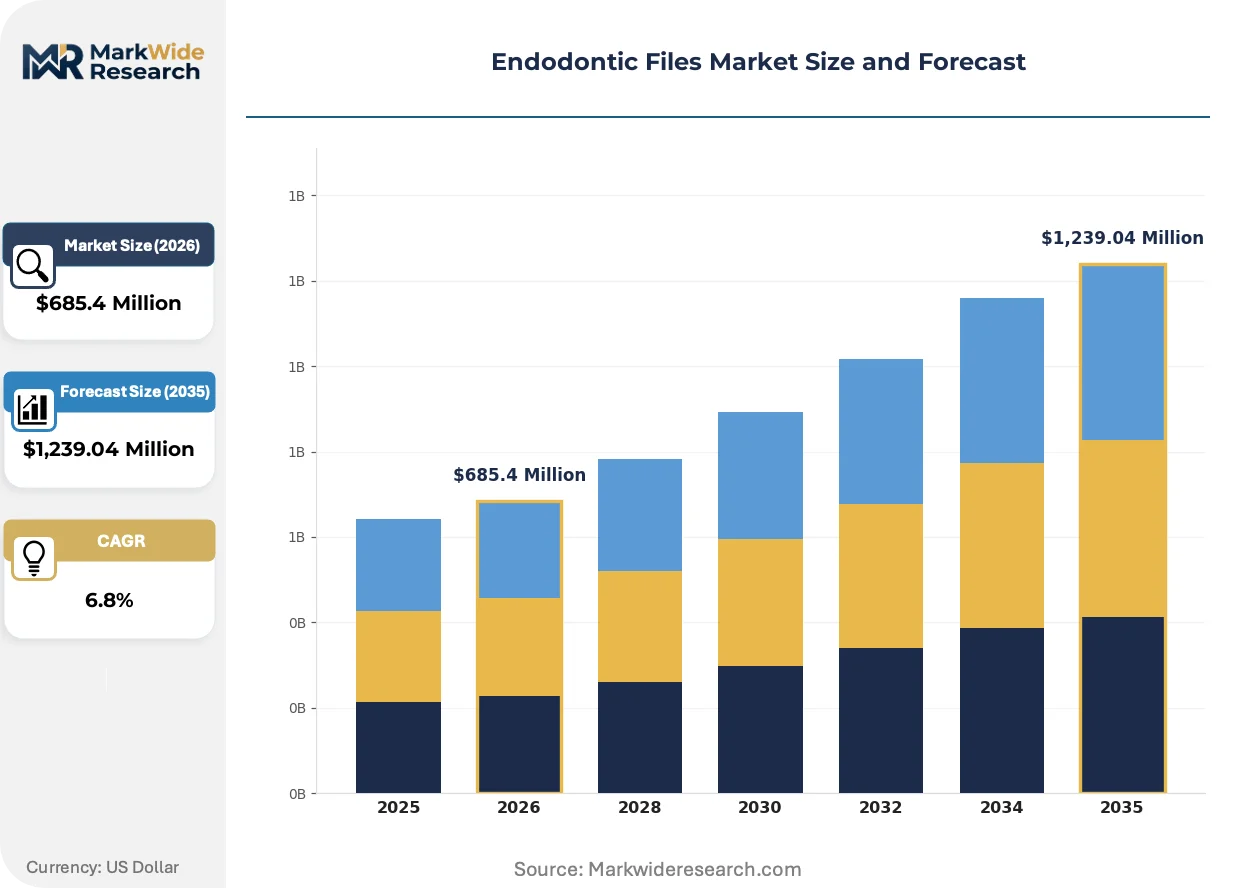
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel Titanium, Stainless Steel, Synergistic, Rotary Usage Type: Pediatric, Adult, Dental Clinics, Hospitals End User: Dentists, Oral Surgeons, Orthodontists, Endodontists Packaging Type: Box, Blister Pack, Dispenser, Bulk |
| Companies Covered | FKG Dentaire, META-BIOMED CO., LTD, Dentsply Sirona, Ultradent Products, DiaDent Group International, Envista Holdings Corporation, Brasseler USA, VDW GmbH, Coltene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endodontic Files Market Strategic Shifts & Innovations
Digital workflow integration is redefining how canal preparation data flows between diagnosis, instrumentation, and obturation stages, collapsing the historical isolation of mechanical debridement from treatment planning software.
Adaptive reciprocation technology is automating motion pattern selection based on real-time torsional load feedback. High-volume endodontic practices in South Korea and Japan are retrofitting existing motors with torque-sensing modules that switch between continuous rotation and oscillation without clinician intervention. This capability is automating the technical decision-making that previously required specialist judgment, compressing training curves for general dentists entering endodontic service lines.
EU MDR post-market clinical follow-up requirements are mandating systematic collection of file separation rates and outcomes data. Manufacturers must now maintain traceable patient-level records linking specific instrument lots to treatment results, creating compliance infrastructure that favors integrated file-motor systems with embedded usage logging. Smaller file producers without digital connectivity capabilities face exclusion from institutional procurement channels.
Subscription-based file replenishment models are displacing bulk purchasing cycles in North American dental service organizations. These entities negotiate enterprise agreements that bundle per-procedure file allocation with motor maintenance and training credits, shifting capital expenditure to operational expense structures. Procurement teams in multi-location practices favor this arrangement for its predictable cost scaling and reduced inventory carrying burden across distributed clinic networks.
Endodontic Files Market Segmentation
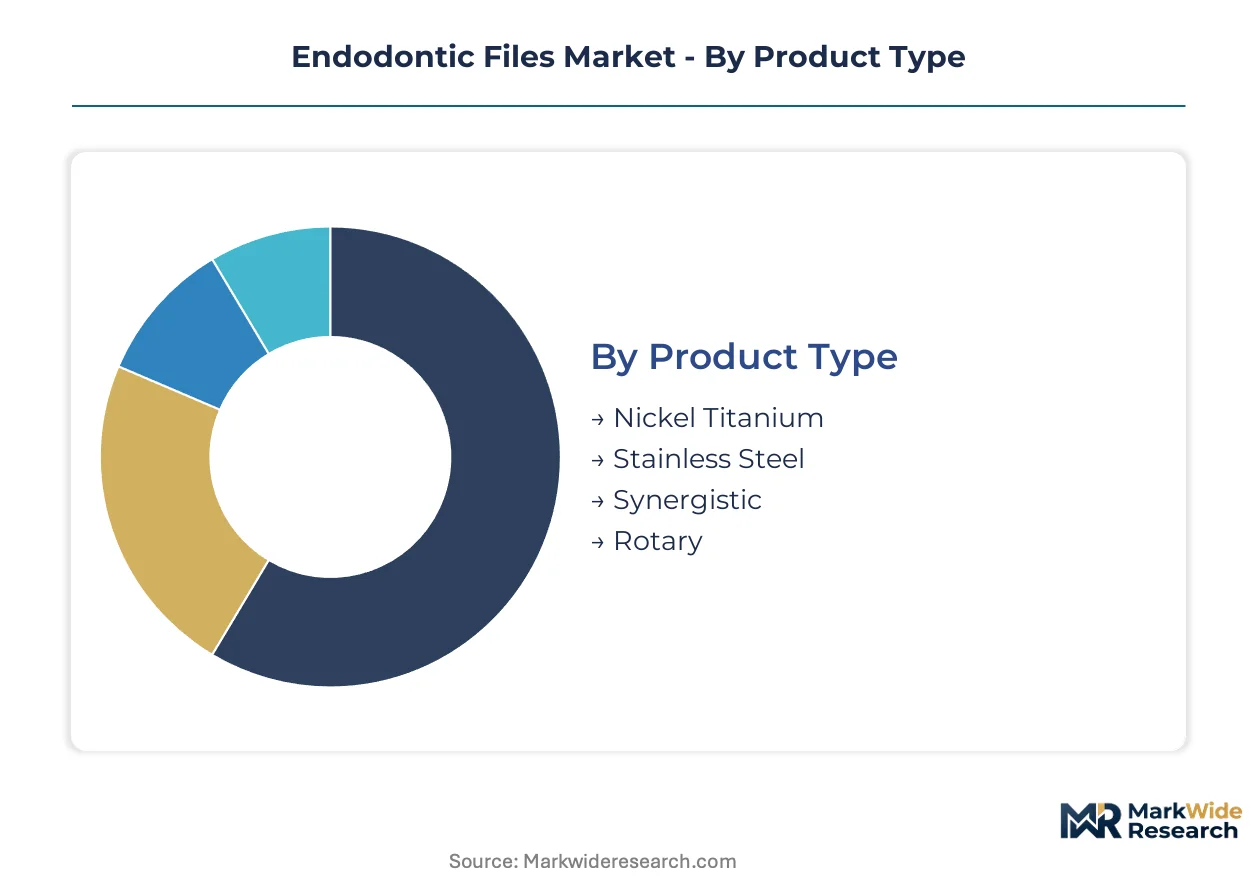
Endodontic file segmentation reveals how procurement priorities diverge across clinical settings and practitioner specializations. Alloy composition and motion mechanics separate premium workflows from cost-constrained environments, while packaging formats reflect inventory velocity and sterilization protocols.
Product Type:
Cost tier separates commodity hand instrumentation from precision-engineered rotary systems that command per-procedure pricing premiums.
- Nickel Titanium:Superelastic alloys with thermal processing deliver cyclic fatigue resistance for complex canal anatomies. Demand concentrates in German specialized endodontic practices where reimbursement clarity supports premium file adoption and warm vertical compaction techniques require precise taper preparations.
- Stainless Steel:Rigid hand files with ISO standardized tip sizes retain dominance in price-sensitive emerging markets. Pediatric applications in India and Southeast Asia favor manual instrumentation where canal morphology and cost constraints limit rotary penetration.
- Synergistic:Hybrid reciprocation-continuous rotation systems automate motion pattern selection based on real-time torsional feedback.
- Rotary:Motor-driven continuous rotation files dominate high-volume North American dental service organizations.
Volume sits with Nickel Titanium; growth tilts toward Synergistic.
Usage Type:
Application context determines whether files serve single-visit emergency protocols or multi-appointment retreatment sequences.
- Pediatric:Smaller canal diameters and incomplete root formation favor manual instrumentation with enhanced tactile feedback. Practices in Japan and South Korea report rising pediatric endodontic referrals as parental tooth preservation preferences strengthen.
- Adult:Complex secondary dentin deposition and calcified canals drive demand for adaptive reciprocation technology. German and Swiss clinics standardizing warm gutta-percha delivery systems elevate specification requirements for precisely tapered rotary preparations.
- Dental Clinics:Independent and group practices generate the majority of file consumption through high procedure volumes.
- Hospitals:Academic medical centers and trauma facilities handle complex cases requiring specialized file inventories.
Volume sits with Adult; growth tilts toward Dental Clinics.
End User:
Customer type reflects training depth and reimbursement structure differences that shape instrument selection criteria.
- Dentists:General practitioners expanding into endodontic service lines drive demand for simplified single-file systems. North American dental service organizations negotiate enterprise subscription agreements that bundle per-procedure file allocation with motor maintenance credits.
- Endodontists:Specialists require comprehensive multi-file sequences for complex retreatment and surgical cases. VDW GmbH training academies lock in clinician loyalty through certified education programs that specify proprietary file systems.
- Oral Surgeons:Surgical endodontic procedures demand robust files for apicoectomy and intentional replantation techniques.
- Orthodontists:Limited endodontic exposure in orthodontic residencies generates occasional file purchases for emergency interventions.
Volume sits with Dentists; growth tilts toward Endodontists.
Packaging Type:
Supply chain velocity and sterilization burden differentiate procurement preferences across practice scales.
- Blister Pack:Individual sterile packaging eliminates cross-contamination risk and supports single-use protocols. High-volume South Korean and Japanese practices retrofitting motors with torque-sensing modules favor blister packs for their traceability compliance with EU MDR post-market surveillance mandates.
- Dispenser:Chairside delivery systems reduce operatory clutter and accelerate instrument access during multi-canal procedures. Brasseler USA controls Midwest US distribution density to enable same-day replenishment for dispenser-dependent high-volume practices.
- Box:Traditional bulk packaging retains relevance for institutional procurement with central sterilization facilities.
- Bulk:Unpackaged files serve in-house sterilization workflows at large dental schools and hospital systems.
Volume sits with Box; growth tilts toward Blister Pack.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European endodontic file procurement through specialized endodontic practices clustered in Bavaria. German reimbursement clarity supports premium nickel titanium adoption. FDA clearance pathways and dental service organization expansion drive North American demand concentration.
United States
Dental service organizations in Texas and Florida negotiate enterprise subscription agreements bundling per-procedure file allocation with motor maintenance credits. FDA 510(k) premarket notification requirements under 21 CFR 872.4760 compress product development cycles for rotary instrument manufacturers. The Minneapolis medical device corridor hosts distribution density enabling same-day replenishment for high-volume Midwest practices.
Germany
Specialized endodontic practices in Munich and Berlin standardize warm vertical compaction techniques demanding precisely tapered canal preparations. EU MDR Annex IX clinical evaluation mandates accelerate file system validation cycles through post-market surveillance obligations. The Lake Constance medical technology cluster concentrates metallurgical R&D for nickel titanium superelastic alloys.
Japan
Pediatric endodontic referrals strengthen in Tokyo and Osaka as parental tooth preservation preferences intensify. PMDA medical device regulations align with ISO 3630-1 dimensional tolerance standards governing fatigue-life validation protocols. The Nagoya precision manufacturing corridor produces torque-sensing motor modules enabling adaptive reciprocation technology.
India
Domestic manufacturing incentives under the PLI scheme for medical devices localize production hubs serving Southeast Asian markets. CDSCO medical device regulations govern import duty exposure for nickel titanium alloy formulations. The Ahmedabad-Gandhinagar pharmaceutical and medical device cluster attracts contract manufacturers targeting price-sensitive emerging market segments.
South Korea
High-volume endodontic practices in Seoul retrofit existing motors with torque-sensing modules automating motion pattern selection. MFDS medical device approval pathways require clinical data repositories supporting post-market surveillance. The Busan-Ulsan industrial corridor supplies precision-engineered components for hybrid reciprocation-continuous rotation systems.
Endodontic Files Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the endodontic file supply base. Integrated dental equipment conglomerates with captive alloy processing capabilities face specialized instrument manufacturers sourcing thermal-treated nickel titanium from third-party metallurgical suppliers. Two strategic archetypes dominate: full-ecosystem vendors bundling file systems with imaging workflows and training-academy specialists locking clinician loyalty through certified education programs. Competitive moves concentrate on distribution density control for same-day replenishment and proprietary file-to-motor communication protocols fragmenting the installed base.
Among German-based specialists, VDW GmbH exemplifies the training-academy archetype through certified education programs that specify proprietary file systems. Dentsply Sirona anchors the integrated-ecosystem tier as a conglomerate with CAD/CAM bundling capabilities. Brasseler USA occupies a position within the distribution-density specialists, controlling Midwest US replenishment velocity for high-volume practices. These three represent the structural separation between metallurgical innovators, workflow integrators, and logistics optimizers defining competitive positioning.
| Leading Market Players |
|---|
| FKG Dentaire |
| META-BIOMED CO., LTD |
| Dentsply Sirona |
| Ultradent Products |
| DiaDent Group International |
| Envista Holdings Corporation |
| Brasseler USA |
| VDW GmbH |
| Coltene |
| Others |
Cost & Logistics Intelligence
EU MDR Annex IX clinical evaluation mandates for Class IIa medical devices gate qualified supply access and premium-tier pricing power by requiring post-market surveillance infrastructure that only capitalized manufacturers can sustain. Nickel titanium alloy formulations with validated fatigue-life data command per-procedure premiums, while commodity stainless steel hand files serve price-sensitive segments where regulatory compliance costs are minimized.
Pricing Analysis
Value-based pricing anchored to clinical throughput outcomes separates premium nickel titanium rotary systems from commodity hand instrumentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 3630-1 certification grade and bundled training credits. Cost compression in the standard tier is intensifying because nickel price volatility from aerospace and battery sector demand squeezes margin buffers. Dental service organizations demonstrate lowest price sensitivity through enterprise subscription agreements, while independent clinics in emerging markets exhibit highest sensitivity to per-unit file costs.
Supply Chain Analysis
Freight cost exposure from precision metallurgical suppliers in Germany, Japan, and South Korea shapes inventory positioning strategies for North American distributors. Nickel titanium superelastic alloys draw from thermal processing facilities concentrated around Lake Constance, the Nagoya precision corridor, and the Busan-Ulsan industrial belt. Single-source vulnerability in specialized alloy formulations creates supply chain risk when aerospace demand spikes divert nickel feedstock. Distribution runs through dental service organization procurement platforms and specialized supply marketplaces disintermediating traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR post-market surveillance obligations create a barrier-to-entry moat favoring manufacturers with established clinical data repositories and digital traceability infrastructure.
For Market Incumbents: Deepen vertical integration into nickel titanium thermal processing to secure alloy supply against aerospace and battery sector competition. Expand certified training academy networks to lock clinician loyalty and defend against asset-light designers sourcing third-party metallurgy. Prioritize embedded file-motor communication protocols that fragment the installed base and complicate multi-vendor procurement for dental service organizations. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the most penetrable route into North American dental service organizations seeking to disintermediate traditional distributors. Target India's PLI scheme for medical devices to establish localized production serving Southeast Asian price-sensitive segments with reduced import duty exposure. Pursue AI-powered canal mapping integration as a differentiated go-to-market angle that captures preference data informing file system development priorities. For Investors and Strategic Acquirers: FDA 510(k) clearance backlogs shortening from submission to market entry is the leading indicator that regulatory capacity is expanding and mid-tier manufacturers may achieve faster commercialization timelines. Frame long-term viability around manufacturers with captive alloy processing and digital connectivity capabilities that satisfy EU MDR traceability mandates. Acquisition targets should display integrated file-motor systems with embedded usage logging. Monitor nickel price volatility indices as the primary signal for margin compression risk across the supply base.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Infrastructure | Post-market surveillance capabilities satisfy Annex IX clinical evaluation mandates for CE marking renewal. |
| Nickel Titanium Alloy Vertical Integration | Captive thermal processing secures superelastic alloy supply against aerospace and battery sector demand spikes. |
| AI-Powered Canal Mapping Integration | Real-time torque adjustment based on CBCT segmentation algorithms differentiates next-generation file systems. |
| Direct-to-Clinic Digital Procurement | Specialized dental supply marketplaces capture preference data and disintermediate traditional distributor networks. |
| Certified Training Academy Expansion | VDW GmbH-style education programs lock clinician loyalty through proprietary file system specification. |
Research Approach
FDA 510(k) premarket notification databases, EU MDR notified body capacity reports, and ISO 3630-1 mechanical testing standards formed the secondary backbone, supplemented by customs and trade data tracking nickel titanium alloy flows. Primary interviews with endodontic specialists, dental service organization procurement directors, biomedical engineers at file manufacturers, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled procedure volume estimates with alloy consumption data across the analysis window.
Bottom-up modeling segmented the market by alloy composition, motion mechanics, usage type, and end user archetype, while top-down approaches validated aggregate figures against dental equipment installation bases and reimbursement code utilization. CAGRs were derived from trend extrapolation of nickel titanium adoption rates, warm vertical compaction technique diffusion, and dental service organization expansion patterns throughout the forecast period. Forecast inputs incorporated notified body capacity constraints, nickel price volatility indices, and PLI scheme incentive trajectories.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time file separation rate reporting and proprietary motor usage logs introduce uncertainty bands around adoption curve assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wireless ECG Devices Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Bionic Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Neurovascular Catheters Market
Medical Devices
Digital Stethoscope Market
Medical Devices
Sphincterotomes Market
Medical Devices
Spinal Implant Market
Medical Devices
Cranial Orthoses Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Pulmonology Devices Market