
 Global Anti-Snoring Device Market | 2026-2036
Global Anti-Snoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Snoring Device Market Foresight
Premium custom-fitted mandibular advancement devices are decoupling from over-the-counter nasal dilators and chin straps on price, clinical validation, and reimbursement access. ResMed leverages its respiratory technology heritage to dominate continuous positive airway pressure adjacencies, while SomnoMed sustains global manufacturing scale across dental sleep medicine channels. ProSomnus Sleep Technologies specializes in digitally manufactured oral appliances with prescription-grade titration, occupying the precision end of the device spectrum.
Anti-snoring devices are mechanical, electrical, or sensor-based appliances designed to maintain upper airway patency during sleep through mandibular repositioning, tongue retention, or nasal dilation, typically constructed from medical-grade thermoplastics or silicone with boil-and-bite or CAD-CAM fabrication protocols. Mandibular advancement devices capture the largest revenue pool due to physician prescribing patterns and dental lab partnerships, while smart wearable and biofeedback technologies represent the fastest-expanding segment as consumers seek data-integrated sleep hygiene solutions. Pressure sensor based systems are maturing in sleep clinic settings where polysomnography integration drives clinical acceptance.
FDA 510(k) clearance requirements and EU MDR Class IIa certification frameworks elevate barriers for new entrants while compelling established manufacturers to maintain rigorous biocompatibility and clinical evidence dossiers. The EU AI Act and evolving FDA software-as-medical-device guidance further complicate regulatory pathways for connected anti-snoring technologies with algorithmic features. Stakeholders must monitor reimbursement policy shifts in Germany's statutory health insurance system and Japan's MHLW device classification updates to anticipate channel access changes.
Market Dynamics
The global anti-snoring device market is experiencing a fundamental shift as mandibular advancement devices absorb digital manufacturing capabilities from dental CAD-CAM workflows, compressing production cycles and enabling mass customization that was previously limited to boutique dental laboratories.
Growth Catalysts
- FDA 510(k) pathway clarity:The FDA's streamlined predicate device framework for Class II oral appliances accelerates market entry for thermoplastic mandibular repositioning devices, reducing regulatory timeline uncertainty for domestic manufacturers.
- Home sleep testing proliferation:Diagnostic sleep study migration from clinical polysomnography to home-based monitoring expands the addressable patient pool by removing facility-based bottlenecks in diagnosis.
- Germany's statutory health insurance reimbursement:Germany's GKV-Spitzenverband maintains favorable reimbursement codes for prescription oral appliances, creating predictable payment pathways that stabilize dental sleep medicine practice economics.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone suppliers in Germany and Japan control high-purity biocompatible material flows, exposing device manufacturers to input cost volatility and allocation constraints during supply disruptions.
- EU MDR technical documentation burden:The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa devices extend certification timelines and elevate compliance costs for smaller manufacturers without established quality management systems.
- CPAP therapy substitution threat:Continuous positive airway pressure devices retain physician preference for moderate-to-severe obstructive sleep apnea, limiting mandibular advancement device penetration in the highest-acuity patient segments.
Strategic Opportunities
- India's underpenetrated diagnosis infrastructure:India's sleep disorder awareness campaigns and expanding private diagnostic networks create first-mover advantages for device manufacturers establishing local dental partnerships ahead of reimbursement maturation.
- Algorithmic biofeedback convergence:Integration of pressure-sensing arrays with machine learning-based sleep position coaching represents unclaimed white space between passive mechanical devices and active therapeutic interventions.
- Direct-to-consumer channel innovation:Telehealth-integrated prescription workflows bypass traditional dental sleep medicine gatekeepers, capturing patients who abandon care due to specialist access friction in the United States and United Kingdom.
Industry Challenges
- CAD-CAM technician scarcity:Digital dental manufacturing requires specialized technicians proficient in 3D oral scanning, design software, and additive production protocols, creating talent bottlenecks that constrain scaling capacity.
- EU AI Act compliance complexity:Connected anti-snoring devices with algorithmic sleep coaching features face uncertain classification under the EU Artificial Intelligence Act's risk-tier framework, delaying product roadmap commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Snoring Device Market |
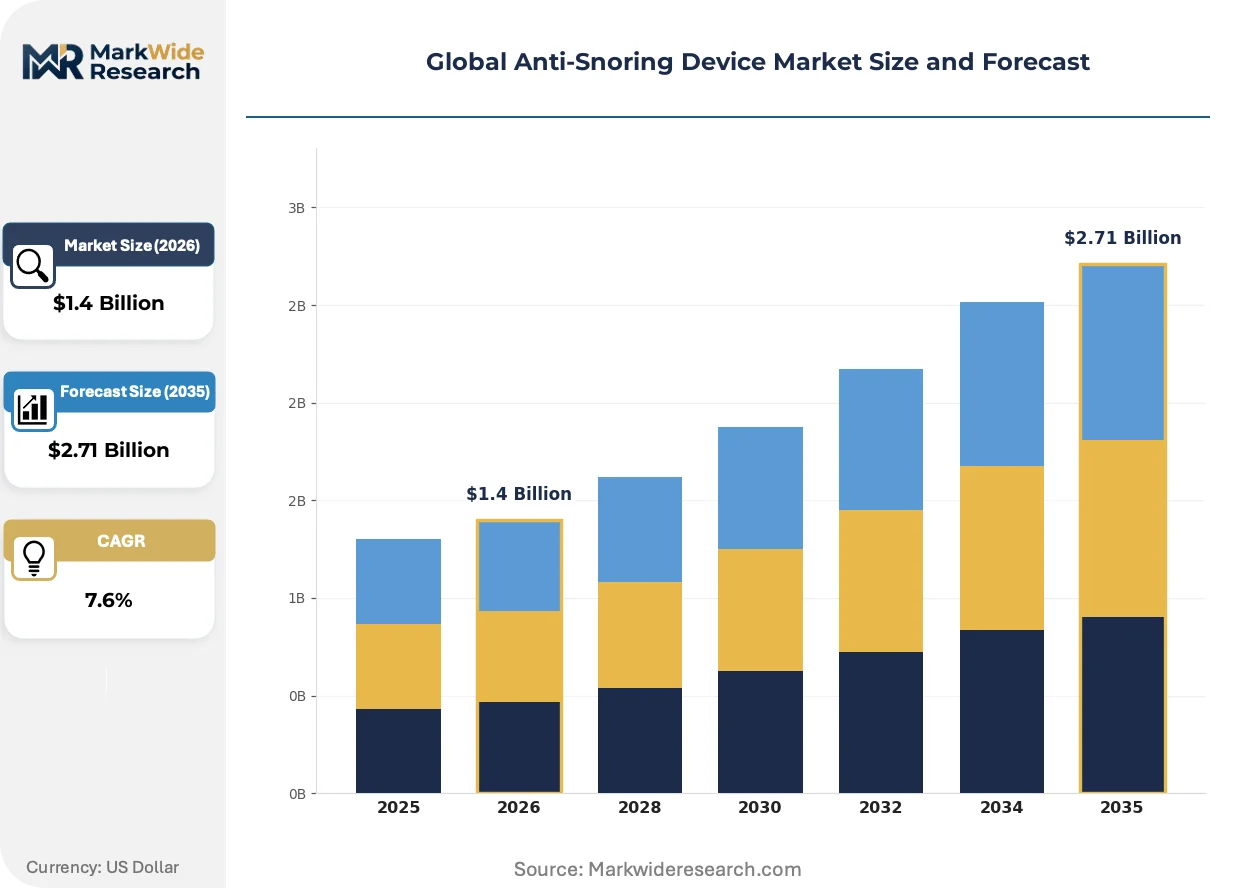
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Advancement Device, Tongue Stabilizing Device, Nasal Dilator, Chin Strap, Pillows Technology: Mechanical, Electrical, Pressure Sensor Based, Smart Wearable, Biofeedback Application: Sleep Apnea Management, Snoring Reduction, Respiratory Support, Lifestyle Improvement, Partner Disturbance Prevention End User: Home Users, Sleep Clinics, ENT Specialists, Wellness Centers, Sleep Disorder Clinics |
| Companies Covered | ResMed, SomnoMed, ProSomnus Sleep Technologies, Fisher & Paykel Healthcare, Koninklijke Philips, Apnea Sciences Corporation, Airway Management, Tomed Dr. Toussaint GmbH, Sleeping Well, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Snoring Device Market Shifts & Advancements
Digital fabrication and sensor integration are fundamentally restructuring how anti-snoring devices are designed, manufactured, and prescribed, shifting competitive advantage toward technology-enabled manufacturers and away from traditional dental laboratory networks.
Polymer-based additive manufacturing is absorbing thermoplastic mandibular advancement device production from conventional milling and injection molding. Sleep clinics and dental practices in the United States and Germany are adopting chairside 3D printing systems that compress device delivery from weeks to days. This technology is absorbing the traditional dental laboratory intermediary, compressing margin capture by third-party fabricators and enabling point-of-care production economics.
The EU AI Act's risk classification framework for machine learning-enabled medical devices is reshaping development priorities for connected anti-snoring technologies. Manufacturers must now maintain algorithmic transparency documentation and human oversight protocols that elevate software engineering costs. Smart wearable segments with biofeedback features face the steepest compliance adjustments, with German and French regulators already requesting conformity assessments for sleep position coaching algorithms.
Patients are abandoning specialist-referral pathways in favor of telehealth-integrated direct purchasing, fragmenting the traditional dental sleep medicine channel. Online platforms with remote prescription verification are displacing brick-and-clay dental partnerships in the United States and United Kingdom. This behavioral shift is most visible among millennial and Generation X demographics seeking sleep apnea solutions without multiple clinical appointments.
Global Anti-Snoring Device Market Segmentation
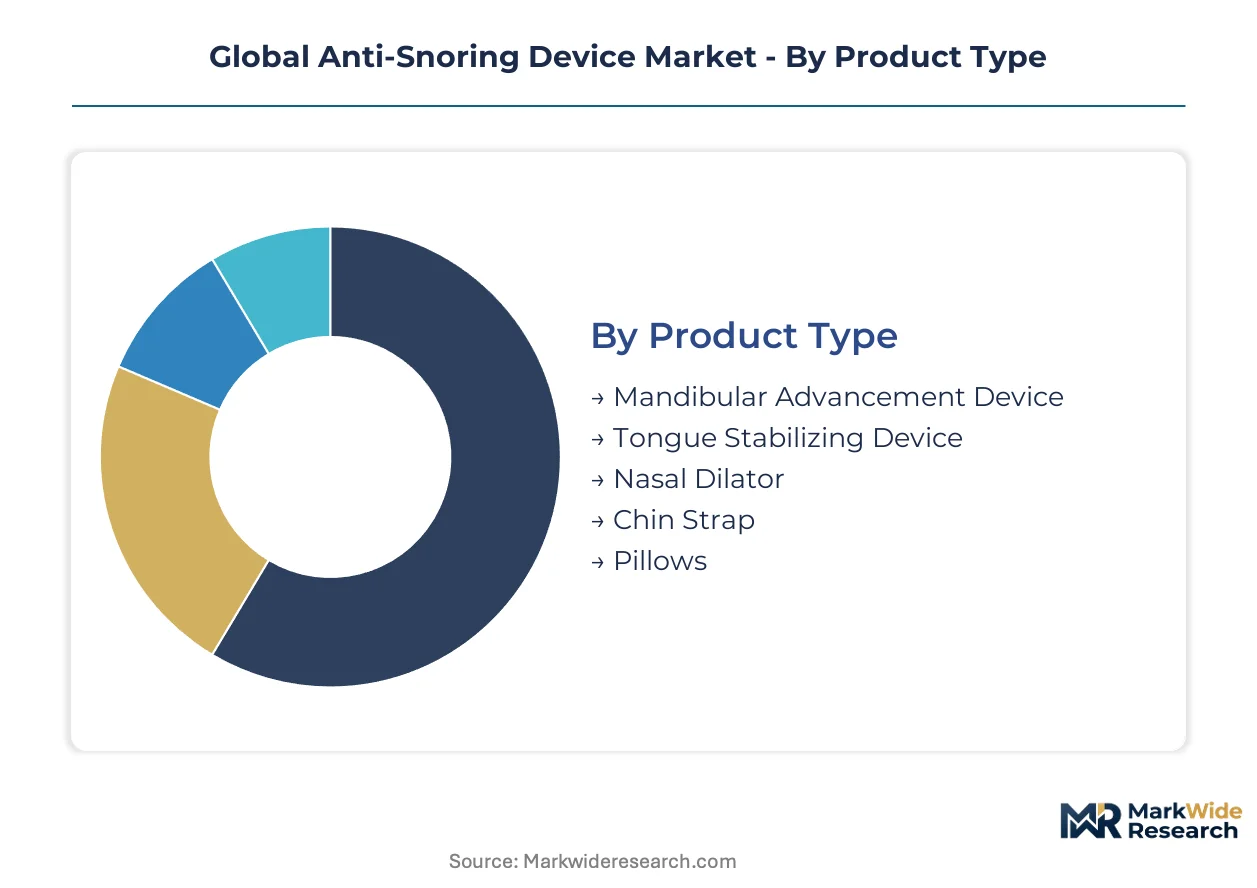
Device taxonomy in the anti-snoring market separates mechanical appliances from algorithmic systems, with fabrication protocols and reimbursement pathways diverging sharply across categories. Understanding these segment boundaries clarifies where capital flows concentrate and which technology platforms reshape competitive advantage.
Product Type:
Thermoplastic composition and dental lab integration define the manufacturing economics across oral appliance categories.
- Mandibular Advancement Device:Medical-grade thermoplastic appliances reposition the lower jaw forward to maintain upper airway patency during sleep. Demand concentrates in the United States and Germany where dental sleep medicine partnerships and favorable reimbursement codes stabilize prescription volumes. FDA 510(k) predicate pathways and EU MDR Class IIa certification requirements elevate barriers for new entrants while rewarding established manufacturers with clinical evidence dossiers.
- Tongue Stabilizing Device:Silicone suction bulbs retain the tongue in forward position without mandibular repositioning, serving patients with dental contraindications to MAD therapy. Adoption is accelerating among aging populations in Japan seeking home-based alternatives to CPAP therapy, though reimbursement gaps in statutory health insurance systems constrain volume scaling relative to prescription oral appliances.
- Nasal Dilator:External adhesive strips or internal mechanical expanders improve nasal airflow without oral cavity involvement.
- Chin Strap:Neoprene or elastic compression garments maintain mandibular closure to encourage nasal breathing.
- Pillows:Foam or inflatable positional therapy devices discourage supine sleeping.
Mandibular Advancement Devices lead on scale; Smart Wearable segments lead on momentum.
Technology:
Sensor integration and algorithmic capability separate premium prescription tiers from commodity mechanical alternatives.
- Mechanical:Passive thermoplastic or silicone appliances without electronic components dominate unit economics through boil-and-bite or CAD-CAM fabrication. Germany's statutory health insurance system maintains dedicated reimbursement codes for these devices, anchoring dental sleep medicine practice revenue.
- Smart Wearable:Bluetooth-enabled throat bands, position sensors, and vibration-detecting wearables transmit sleep architecture data to companion applications. Integration with telehealth platforms in the United States and United Kingdom is displacing traditional specialist-referral pathways among digitally native demographics.
- Electrical:Microcurrent or vibration-based stimulation devices activate airway musculature.
- Pressure Sensor Based:Polysomnography-integrated arrays capture respiratory flow dynamics in clinical settings.
- Biofeedback:Haptic or auditory conditioning systems train sleep position behavior through algorithmic coaching.
Mechanical platforms anchor current revenue; Smart Wearable and Biofeedback combinations are climbing the fastest.
Application:
Clinical indication severity determines device selection, reimbursement eligibility, and channel access.
- Sleep Apnea Management:Prescription-grade mandibular advancement devices and sensor-based diagnostics target diagnosed obstructive sleep apnea patients. Physician prescribing patterns in the United States favor CPAP for moderate-to-severe cases, limiting oral appliance penetration to mild-to-moderate severity bands.
- Snoring Reduction:Over-the-counter nasal dilators, chin straps, and mechanical oral appliances address primary snoring without apnea comorbidity. Direct-to-consumer platforms in the United Kingdom capture patients abandoning specialist pathways due to appointment friction.
- Respiratory Support:Adjunctive devices for chronic respiratory conditions.
- Lifestyle Improvement:Wellness-positioned products targeting sleep quality optimization.
- Partner Disturbance Prevention:Relationship-motivated purchasing without clinical diagnosis.
Sleep Apnea Management commands premium pricing; Snoring Reduction segments are gaining share fastest through channel innovation.
End User:
Channel configuration and prescription requirements fragment demand across clinical and consumer environments.
- Home Users:Direct-purchasing consumers through retail pharmacies, e-commerce platforms, and telehealth-integrated workflows. Telehealth prescription verification in the United States enables remote access to custom-fitted devices previously gated by dental specialist appointments.
- Sleep Clinics:Polysomnography-equipped facilities in Germany and Japan integrate pressure-sensor based systems for diagnostic and therapeutic monitoring. These sites drive adoption of data-integrated devices with algorithmic sleep coaching capabilities.
- ENT Specialists:Otolaryngology practices prescribing nasal and oral cavity interventions.
- Wellness Centers:Non-clinical sleep optimization facilities.
- Sleep Disorder Clinics:Dedicated diagnostic and treatment centers.
Home Users represent the largest addressable population; Sleep Clinics drive technology validation and reimbursement precedent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sleep medicine specialists cluster in the United States, Germany, and Japan where diagnostic infrastructure and reimbursement maturity support device prescribing. Dental sleep medicine partnerships and polysomnography networks anchor regional demand concentration.
United States
Home sleep testing expansion and telehealth-integrated prescription workflows accelerate device access beyond traditional specialist gatekeeping. FDA 510(k) predicate pathways for Class II oral appliances provide regulatory clarity for thermoplastic mandibular advancement devices. Sleep clinics in the Boston-Cambridge corridor and Stanford-San Francisco axis drive adoption of sensor-integrated systems with polysomnography compatibility.
Germany
Germany's GKV-Spitzenverband maintains dedicated reimbursement codes for prescription oral appliances, stabilizing dental sleep medicine practice revenue. EU MDR Class IIa certification requirements elevate compliance costs while rewarding established manufacturers with clinical evidence dossiers. Medical-grade silicone suppliers in the Munich-Stuttgart industrial belt control high-purity biocompatible material flows for device fabrication.
Japan
Aging demographics and home care adoption preferences accelerate demand for tongue stabilizing devices as CPAP alternatives. MHLW device classification updates and statutory health insurance reimbursement gaps shape channel access for oral appliances. Sleep disorder clinics in Tokyo-Osaka metropolitan corridors integrate pressure-sensor based diagnostics with therapeutic device prescribing.
India
Expanding private diagnostic networks and sleep disorder awareness campaigns create first-mover opportunities ahead of reimbursement maturation. CDSCO medical device registration requirements and BIS standards for biocompatible materials establish compliance frameworks for imported and locally manufactured devices. Dental partnerships in Mumbai and Bengaluru medical corridors anchor initial market development efforts.
United Kingdom
Direct-to-consumer platforms with remote prescription verification fragment traditional dental sleep medicine channel structures. NHS reimbursement constraints for oral appliances push demand toward private-pay telehealth workflows. Sleep medicine clusters in London and Manchester academic medical centers validate connected device technologies for algorithmic sleep coaching.
Global Anti-Snoring Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fabrication protocols and distribution channels. The market structures around three tiers: respiratory technology heritage players with CPAP adjacencies, dental sleep medicine specialists with global manufacturing scale, and digitally native precision manufacturers with CAD-CAM workflows. Consolidation pressures concentrate among mid-scale fabricators lacking vertical control over biocompatible material supply or algorithmic software development. Dominant competitive moves include strategic partnerships with dental laboratory networks and geographic expansion through telehealth-integrated direct channels.
Among respiratory-technology heritage players, ResMed anchors the segment with established sleep medicine infrastructure. SomnoMed GmbH exemplifies global-scale dental sleep medicine specialists with manufacturing footprint across prescription oral appliance categories. ProSomnus Sleep Technologies occupies the precision-manufacturing archetype with digitally fabricated prescription-grade devices. These three represent distinct competitive positioning vectors: therapeutic ecosystem integration, global dental channel penetration, and CAD-CAM fabrication specialization respectively.
| Leading Market Players |
|---|
| ResMed |
| SomnoMed |
| ProSomnus Sleep Technologies |
| Fisher & Paykel Healthcare |
| Koninklijke Philips |
| Apnea Sciences Corporation |
| Airway Management |
| Tomed Dr. Toussaint GmbH |
| Sleeping Well |
| Others |
Supply & Pricing Matrix
CAD-CAM manufacturing migration simultaneously compresses unit production costs and concentrates fabrication capacity among dental technology specialists with chairside 3D printing infrastructure, reshaping margin capture across prescription oral appliance tiers.
Pricing Analysis
The bundled-vs-unbundled service split separates prescription-grade mandibular advancement devices from direct-to-consumer alternatives. Three-tier pricing structure across premium custom-fitted, standard boil-and-bite, and economy nasal dilator levels reflects FDA 510(k) certification investment and dental lab partnership depth. Price differentiation hinges on clinical validation dossiers and telehealth prescription verification workflows. Cost compression in standard thermoplastic tiers intensifies as chairside fabrication displaces third-party laboratory intermediaries. Home users purchasing through e-commerce platforms exhibit highest price sensitivity; sleep clinics and dental sleep medicine practices demonstrate lowest sensitivity due to reimbursement code stability.
Supply Chain Analysis
Medical-grade silicone supply rests on specialty chemical producers in Germany and Japan with high-purity biocompatible material capabilities. Raw material flows draw from thermoplastic resin suppliers in the United States, precision sensor manufacturers in South Korea, and dental CAD-CAM hardware producers in Germany. Single-source vulnerability concentrates in medical-grade silicone allocations during supply disruptions. Distribution runs through dental laboratory networks for prescription devices, direct-to-consumer platforms for over-the-counter segments, and hospital procurement systems for sleep clinic integrated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through digital fabrication cost-down curves and premium-tier algorithmic biofeedback convergence, rewarding manufacturers with integrated CAD-CAM and sensor development capabilities.
For Market Incumbents: Lock in dental sleep medicine channel control through exclusive CAD-CAM technician training partnerships and chairside 3D printing system placements. Secure backward integration into medical-grade thermoplastic resin supply through long-term offtake agreements with German and Japanese specialty material producers. The CPAP therapy substitution threat demands defensive positioning in mild-to-moderate sleep apnea segments through polysomnography-integrated sensor validation. For New Entrants and Emerging Players: FDA 510(k) predicate pathway clarity in the United States opens a window for thermoplastic mandibular advancement device market entry with streamlined regulatory timelines. Target India's underpenetrated diagnostic infrastructure through local dental partnership development ahead of CDSCO reimbursement maturation. Algorithmic biofeedback convergence represents the most penetrable white space between passive mechanical devices and active therapeutic interventions, accessible through telehealth-integrated direct-to-consumer workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators lacking vertical control over biocompatible material supply or algorithmic software development. Long-term viability across the analysis window favors manufacturers with integrated CAD-CAM production and sensor-enabled biofeedback roadmaps. Watch Germany's GKV-Spitzenverband reimbursement code revisions and Japan's MHLW device classification updates as inflection indicators for channel access economics.| Strategic Initiative | Industry Significance |
|---|---|
| CAD-CAM Manufacturing Scale-Up | Chairside 3D printing compression from weeks to days disrupts dental laboratory intermediaries. |
| FDA 510(k) Submission Pathway | Predicate device framework accelerates Class II oral appliance market entry timelines. |
| Telehealth Platform Integration | Remote prescription verification captures patients abandoning specialist-referral pathways. |
| Biocompatible Material Supply Agreement | Long-term silicone and thermoplastic offtake secures input cost predictability. |
| Algorithmic Sleep Coaching Development | EU AI Act compliance investment differentiates premium connected device tiers. |
Research Methodology
Multiple input streams — primary interviews with dental sleep medicine practitioners, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical shipment data cross-referenced against expert panel input established baseline segmentation across product type, technology platform, application severity, and end-user channel dimensions. CAGRs were derived from modeled adoption curves incorporating home sleep testing penetration rates, reimbursement code stability indices, and digital fabrication cost-down trajectories. Polysomnography network expansion and telehealth prescription verification adoption served as industry-specific forecast inputs throughout the projection horizon.
Revisions become necessary when EU MDR certification timeline extensions, FDA software-as-medical-device guidance updates, or Germany's statutory health insurance reimbursement code modifications materialize. Forecasts reflect documented assumptions regarding diagnostic infrastructure expansion and regulatory pathway stability. A small set of named triggers — MHLW device classification updates, CDSCO registration requirement changes, and EU AI Act algorithmic risk-tier interpretations — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Needle Guides Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Artificial Spine Discs Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Organ Care Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Bone Power Tools Market