
 Japan Drug Delivery Devices Market | 2026-2036
Japan Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Drug Delivery Devices Market Foresight
Biomedical engineering talent is bifurcating between legacy mechanical device expertise and digital-therapeutics integration, constraining product development timelines for hybrid platforms. Terumo leverages its domestic manufacturing scale to dominate infusion pump supply chains. Daiichi Sankyo Co. anchors its position through deep specialization in oncology injectable formats. Becton Dickinson competes by extending its global needle-free portfolio into Japanese hospital procurement networks.
Drug delivery devices encompass engineered systems that administer pharmaceutical compounds through controlled release mechanisms, incorporating specifications such as flow rates, particle size distribution, and biocompatibility grades to ensure therapeutic efficacy and patient safety. These systems serve the primary commercial purpose of improving bioavailability, reducing dosing frequency, and enabling targeted administration across acute and chronic care settings. Injectable devices occupy the largest revenue pool given Japan's established hospital infrastructure, while wearable injectors represent the fastest-expanding technology segment as diabetes and autoimmune protocols shift toward ambulatory administration. Home healthcare channels capture growing margin pools as reimbursement frameworks expand for self-administered therapies outside institutional settings.
PMDA governs combination product approvals through its Office of Medical Devices, while METI coordinates industrial policy supporting domestic medical device manufacturing under Japan's healthcare growth strategy. JIS standards establish material and performance benchmarks that shape product design requirements and market access thresholds for both domestic producers and imported systems. Stakeholders must monitor how PMDA's evolving digital health guidance intersects with METI's semiconductor-linked device subsidies to determine platform investment priorities.
Market Dynamics
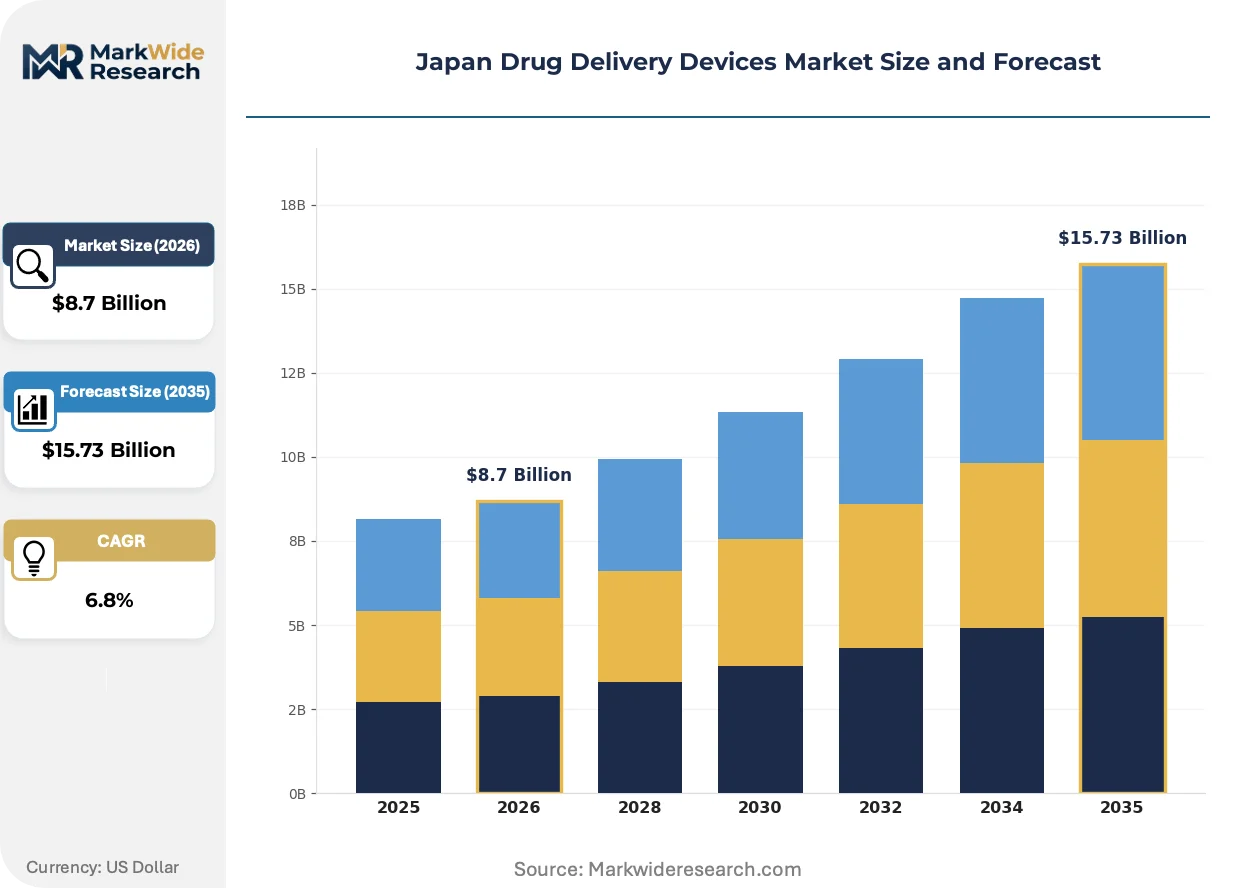
Japan's drug delivery devices market is compressing around the convergence of hospital procurement consolidation and PMDA's accelerated review pathways for combination products, forcing manufacturers to restructure development timelines and supply footprints simultaneously.
Growth Catalysts
- Home Healthcare Expansion:METI's reimbursement reforms for self-administered therapies outside institutional settings are pulling ambulatory infusion systems into chronic disease management protocols.
- PMDA Combination Product Streamlining:The Office of Medical Devices has harmonized review timelines for device-drug hybrids, reducing regulatory friction for novel injectable formats.
- Wearable Injector Technology:Diabetes and autoimmune treatment protocols are migrating from hospital-based administration to patient-controlled platforms.
Market Restraints
- Biomedical Engineering Talent Scarcity:The bifurcation between legacy mechanical device expertise and digital-therapeutics integration is constraining hybrid platform development timelines.
- Domestic Manufacturing Concentration:Infusion pump supply chains cluster heavily around Kanto-region production facilities, creating geographic vulnerability to disruption.
- JIS Certification Complexity:Material and performance benchmarks for biocompatibility grades impose extended validation cycles on imported systems seeking market access.
Strategic Opportunities
- Kansai Regional Underpenetration:Osaka-Kobe pharmaceutical R&D clusters remain underserved by specialized oncology injectable device suppliers relative to Tokyo density.
- Semiconductor-Linked Device Subsidies:METI's industrial policy incentives for connected delivery platforms create funding channels for sensor-integrated wearable systems.
- Digital Health Guidance Convergence:PMDA's evolving software-as-medical-device frameworks intersect with combination product pathways to enable app-controlled dosing platforms.
Industry Challenges
- Hybrid Platform Integration Complexity:Engineering teams must reconcile mechanical drug delivery specifications with real-time data transmission protocols and cybersecurity requirements.
- Legacy Hospital Procurement Lock-In:Established supply contracts with Tokyo's dense hospital network create switching friction for novel device entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Drug Delivery Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Devices, Infusion Pumps, Inhalation Devices, Transdermal Patches End User: Hospitals, Clinics, Home Healthcare, Pharmacies Technology: Needle-free Devices, Smart Inhalers, Microneedle Systems, Wearable Injectors Application: Chronic Disease Management, Pain Management, Vaccination, Oncology |
| Companies Covered | Otsuka Pharmaceutical Co., Daiichi Sankyo Co., Taisei Kako Co., Ltd., Johnson & Johnson, Becton Dickinson, Terumo, Mitsubishi Tanabe Pharma, Novartis, Nipro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Drug Delivery Devices Market Shifts & Advancements
Active pharmaceutical ingredient stability requirements and patient mobility demands are reshaping device architecture across Japan's delivery systems market, compressing form factors while expanding connectivity capabilities.
Microneedle array technology is miniaturizing transdermal drug administration for biologic compounds previously restricted to intravenous delivery. Dermatology and vaccine protocols in Osaka's outpatient clinics are adopting these platforms at accelerating pace. The technology is miniaturizing patient-administered delivery windows, collapsing the distinction between hospital and home administration settings.
PMDA's Office of Medical Devices has issued clarified guidance on software-as-medical-device classifications for connected delivery platforms. This regulatory precision reduces ambiguity for manufacturers integrating dose-tracking applications with mechanical injectors. Wearable insulin delivery systems are responding fastest, restructuring validation documentation to align with the new digital health framework.
Hospital procurement committees in Tokyo's metropolitan network are unbundling after-sales service contracts from device acquisition agreements. Third-party technical service providers are displacing manufacturer-captive maintenance operations. This pattern is most visible in infusion pump categories, where independent service organizations now capture calibration and preventive maintenance revenue streams previously retained by original equipment suppliers.
Japan Drug Delivery Devices Market Segmentation
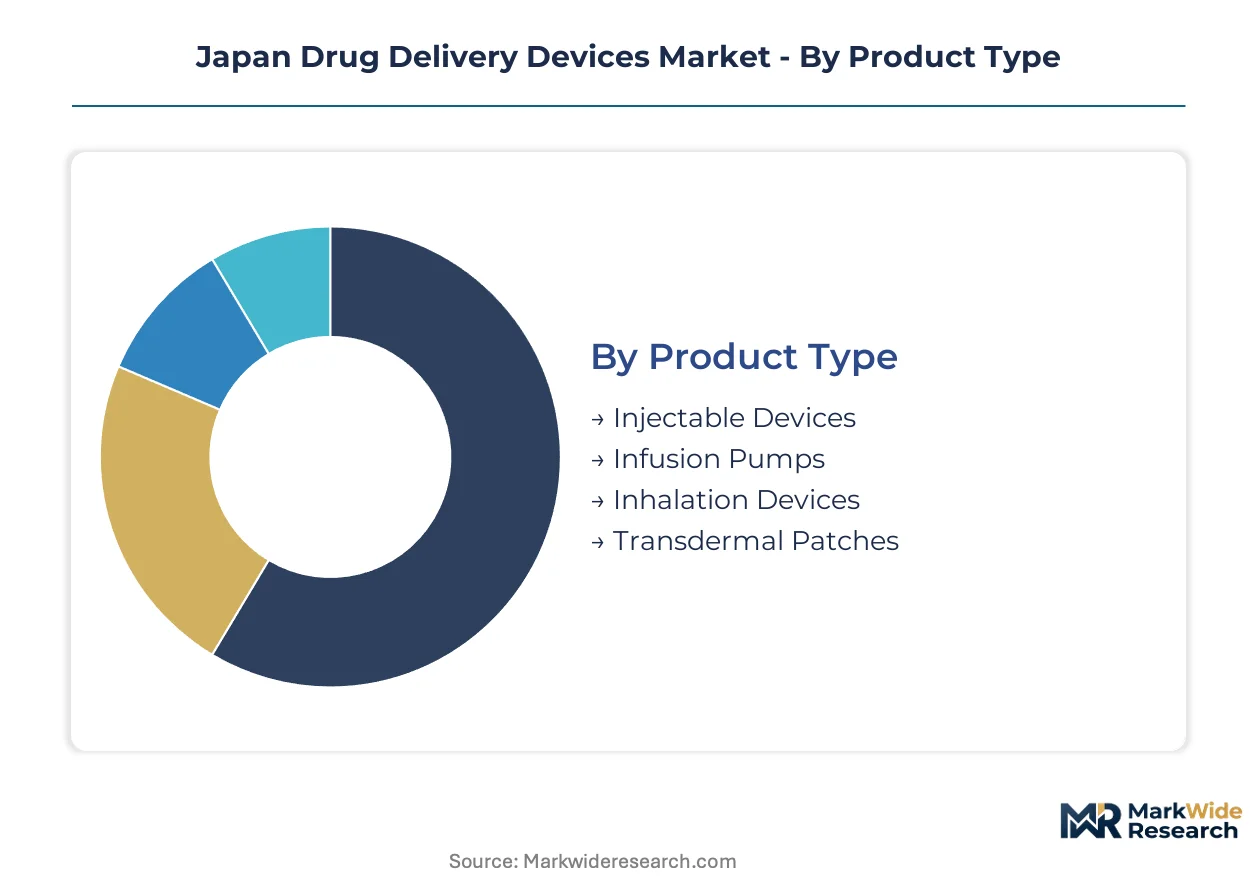
Device architecture in Japan's market fragments across administration routes, patient settings, and connectivity levels. Each segmentation axis reveals distinct procurement patterns and regulatory validation requirements.
Product Type:
Domestic production clusters around Kanto-region facilities for infusion pumps, while transdermal and inhalation platforms draw heavier import dependence.
- Injectable Devices:Prefilled syringes and autoinjectors dominate hospital procurement through established supply contracts with Tokyo's metropolitan network. Prefilled formats reduce dosing errors in high-volume oncology and diabetes protocols.
- Infusion Pumps:Terumo's domestic manufacturing scale anchors supply chains for ambulatory and large-volume infusion systems. METI's semiconductor-linked subsidies are pulling sensor-integrated pump development toward connected platforms.
- Inhalation Devices:Dry powder and metered-dose inhalers serve asthma and COPD management through outpatient clinic networks.
- Transdermal Patches:Controlled-release patches for pain and hormone therapies concentrate in home healthcare channels.
Injectable devices hold the largest share; momentum sits with infusion pumps.
End User:
Reimbursement tiering creates sharp margin differentiation between institutional procurement and self-administered channels.
- Hospitals:Tokyo's dense hospital network drives bulk purchasing of infusion pumps and complex injectable systems. PMDA's combination product streamlining accelerates adoption of novel device-drug pairings in oncology wards.
- Home Healthcare:METI's reimbursement reforms for self-administered therapies are pulling wearable injectors and transdermal systems into chronic disease management. Patient mobility demands compress device form factors while expanding connectivity capabilities.
- Clinics:Osaka-Kobe outpatient networks adopt microneedle arrays for dermatology and vaccine protocols at accelerating pace.
- Pharmacies:Retail distribution concentrates on inhalation devices and prefilled autoinjectors for established therapies.
Hospitals command the largest revenue pool; home healthcare channels are expanding most quickly.
Technology:
Engineering talent scarcity bifurcates development timelines between legacy mechanical platforms and digital-therapeutics integration.
- Wearable Injectors:Patient-controlled platforms for diabetes and autoimmune therapies are restructuring validation documentation to align with PMDA's software-as-medical-device frameworks. Real-time dose tracking and app-controlled interfaces differentiate competitive offerings.
- Smart Inhalers:Bluetooth-enabled dose monitoring and adherence tracking integrate with digital health platforms. PMDA's clarified guidance on connected device classifications reduces regulatory ambiguity for manufacturers.
- Microneedle Systems:Miniaturized transdermal arrays collapse the distinction between hospital and home administration for biologics previously restricted to intravenous delivery.
- Needle-free Devices:Jet injectors and pressure-based systems address needle phobia and sharps disposal requirements in vaccination and pediatric protocols.
Wearable injectors hold the largest installed base; smart inhalers are gaining share fastest.
Application:
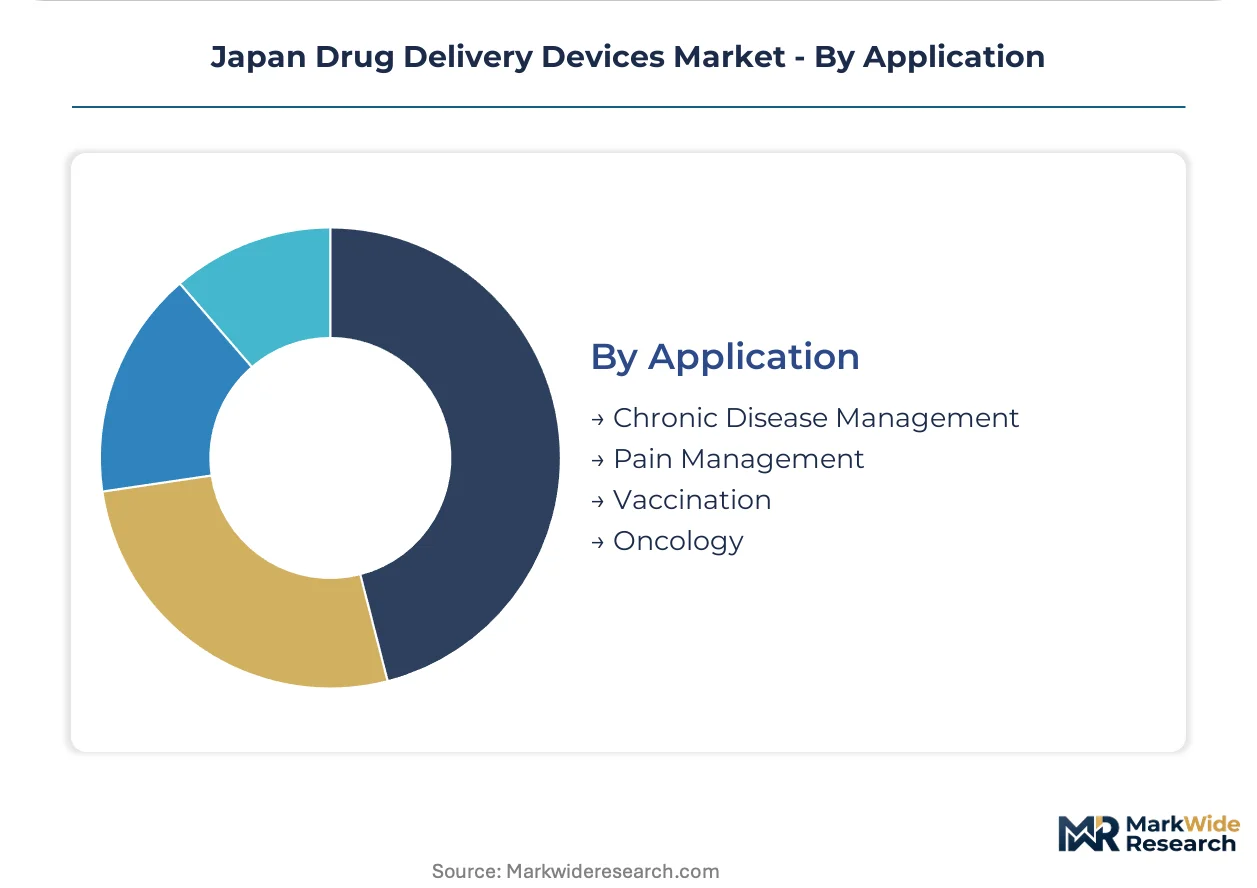
Clinical trial density and reimbursement generosity determine device technology selection across therapeutic areas.
- Chronic Disease Management:Diabetes and autoimmune protocols drive demand for ambulatory infusion and wearable injection platforms. Patient self-administration requirements prioritize ergonomic design and connectivity integration.
- Oncology:Daiichi Sankyo's specialization in injectable formats anchors demand for precision dosing and cold-chain stability in biologic delivery. Prefilled syringes and closed-system transfer devices dominate hospital procurement.
- Pain Management:Transdermal patches and patient-controlled analgesia pumps serve post-surgical and palliative care settings.
- Vaccination:Microneedle arrays and needle-free jet injectors address mass immunization and pediatric administration requirements.
Chronic disease management holds the largest share; oncology applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's regulatory framework shapes device development priorities across Japan's archipelago, with METI's industrial policy directing investment toward specific prefectural clusters. Regional concentration of pharmaceutical R&D and hospital infrastructure creates distinct demand profiles.
Kanto
Tokyo's metropolitan hospital network drives bulk procurement of infusion pumps and complex injectable systems. PMDA's Office of Medical Devices accelerates combination product approvals for oncology wards concentrated in this corridor. Yokohama-Kawasaki pharmaceutical manufacturing belts anchor domestic production capacity for prefilled syringe formats.
Kansai
Osaka-Kobe outpatient clinics adopt microneedle arrays for dermatology and vaccine protocols at accelerating pace. METI's semiconductor-linked subsidies pull sensor-integrated wearable development toward this historically underpenetrated region. Kyoto's biomedical engineering programs feed talent pipelines for digital-therapeutics integration.
Chubu
Nagoya's precision manufacturing heritage supports component fabrication for infusion pump supply chains. JIS certification requirements for biocompatibility grades extend validation cycles for imported systems seeking entry through this industrial gateway. Aichi prefecture's medical device subcontractors cluster around Terumo's domestic manufacturing scale.
Kyushu
Fukuoka's pharmaceutical R&D parks attract diabetes and autoimmune protocol developers seeking proximity to aging patient populations. PMDA's software-as-medical-device guidance enables app-controlled dosing platform trials in regional hospital networks. Kumamoto's biotech incubators specialize in transdermal patch formulation stability testing.
Hokkaido
Sapporo's remote care infrastructure prioritizes self-administered therapy reimbursement under METI's home healthcare expansion reforms. Cold-chain stability requirements for biologic delivery concentrate specialized logistics investment in this northern island. Regional procurement committees unbundle after-sales service contracts from device acquisition agreements.
Japan Drug Delivery Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturers leveraging JIS certification familiarity against multinational entrants with global portfolio breadth. The structure compresses around hospital procurement consolidation and PMDA's accelerated review pathways, forcing simultaneous restructuring of development timelines and supply footprints. Three archetypes dominate: domestic manufacturing-scale incumbents, global needle-free portfolio extenders, and oncology injectable format specialists. Competitive moves concentrate on supply chain geographic diversification and digital-therapeutics integration partnerships.
Among Japan-based pharmaceutical-device hybrids, Daiichi Sankyo Co. and Otsuka Pharmaceutical Co. exemplify the deep specialization archetype in oncology and CNS therapeutic areas respectively. Terumo occupies a position representing domestic manufacturing-scale leverage in infusion pump supply chains. Becton Dickinson sits within the global portfolio extender tier, anchoring multinational presence through hospital procurement network penetration.
| Leading Market Players |
|---|
| Otsuka Pharmaceutical Co. |
| Daiichi Sankyo Co. |
| Taisei Kako Co., Ltd. |
| Johnson & Johnson |
| Becton Dickinson |
| Terumo |
| Mitsubishi Tanabe Pharma |
| Novartis |
| Nipro |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Tokyo metropolitan hospital networks and domestic infusion pump manufacturers lock in supply access while anchoring price visibility across multi-year procurement cycles. METI's semiconductor-linked subsidies for connected devices introduce cost-offset mechanisms that compress net acquisition prices for sensor-integrated platforms without eroding manufacturer margins.
Pricing Analysis
Kanto-region procurement committees command 15-20% price discounts against Kyushu and Hokkaido equivalents due to volume concentration and unbundled service contracts. Three-tier pricing structure across premium smart-injector, standard infusion pump, and economy prefilled syringe levels differentiates offerings. Cost compression in the economy tier intensifies as third-party technical service providers displace manufacturer-captive maintenance revenue. Home healthcare channels exhibit highest price sensitivity; oncology wards demonstrate lowest sensitivity due to reimbursement generosity.
Supply Chain Analysis
Kanto-region production facility concentration around Yokohama-Kawasaki pharmaceutical belts creates single-source vulnerability for precision pump components. Domestic manufacturing draws from German precision motors, Taiwanese sensor modules, and domestic biocompatibility-grade polymers. Tariff exposure on semiconductor-linked device imports from South Korea and China elevates input cost volatility. Distribution runs through Terumo-captive logistics networks and independent medical device distributors serving regional hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's drug delivery devices market requires substitution defense against biosimilar-administration format shifts that bypass traditional injector platforms. Incumbents must navigate digital-native therapeutic delivery systems that disintermediate mechanical device interfaces.
For Market Incumbents: Consolidate Kanto-region hospital procurement relationships through bundled connectivity service offerings that raise switching costs for procurement committees. Deepen backward integration into sensor module fabrication to offset semiconductor supply volatility flagged by METI subsidy frameworks. Lock in biomedical engineering talent pipelines through Kyoto university partnerships before digital-therapeutics competitors capture hybrid platform expertise.
For New Entrants and Emerging Players: After-sales service unbundling in infusion pump categories creates white-space for independent technical service organizations to capture calibration and preventive maintenance revenue streams previously retained by original equipment suppliers. Target Kansai-region microneedle array adoption in Osaka-Kobe dermatology clinics as the most penetrable geography. Lead with PMDA software-as-medical-device pre-certification to accelerate hospital pilot programs.
For Investors and Strategic Acquirers: Digital-therapeutics integration specialists with validated PMDA combination product pathways represent priority acquisition targets for platform consolidation plays. Long-term viability hinges on 5-10 year reimbursement expansion for self-administered therapies outside institutional settings. Watch METI's semiconductor subsidy allocation shifts as inflection indicator for connected device platform investment priority.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Combination Product Pre-Certification | Accelerates hospital pilot programs for novel device-drug hybrids in oncology wards. |
| Backward Integration into Sensor Modules | Reduces tariff exposure on Taiwanese and South Korean semiconductor inputs. |
| Kyoto Biomedical Engineering Pipeline Partnership | Secures hybrid platform talent before digital-therapeutics competitors capture expertise. |
| Independent Technical Service Organization Launch | Captures calibration revenue streams from unbundled Tokyo hospital procurement contracts. |
| Kansai Microneedle Array Market Development | Exploits underpenetration in Osaka-Kobe dermatology clinic networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers at device manufacturers, PMDA regulatory affairs specialists, and METI industrial policy officers. Secondary validation drew from PMDA medical device approval databases, METI subsidy disclosure filings, hospital GPO contract registries, and JIS standards documentation. Bottom-up and top-down triangulation reconciled manufacturer shipment data with institutional procurement records.
Across the analysis window, the forecast framework modeled volume and value trajectories across product type, end user, technology, and application dimensions with regional prefectural granularity. CAGRs were derived from regression analysis of historical approval timelines, reimbursement expansion patterns, and semiconductor subsidy allocation trends. Forecast inputs incorporated PMDA digital health guidance evolution and METI home healthcare reform implementation pace.
Forecasts assume regulatory continuity in PMDA combination product pathways and METI semiconductor-linked subsidy regimes; material policy shifts would require re-modeling. Revision becomes warranted when PMDA software-as-medical-device classification thresholds or METI reimbursement tier adjustments cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pocket Otoscope Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Oxygenator Market
Medical Devices
North America and Europe Medical Technology Market