
 Electrosurgical Devices Market | 2026-2036
Electrosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electrosurgical Devices Market Analysis
China is reshaping electrosurgical device supply dynamics through expanded domestic manufacturing of radiofrequency generators and precision electrodes. Medtronic leverages its integrated surgical ecosystem to bundle energy platforms with consumable attachments across hospital networks. Johnson & Johnson (Ethicon) sustains leadership in advanced bipolar vessel sealing through proprietary feedback algorithms and surgeon training infrastructure.
Electrosurgical devices generate controlled thermal energy via high-frequency alternating current to cut, coagulate, or ablate tissue during operative procedures, typically operating at frequencies between 300 kHz and 3 MHz to avoid neuromuscular stimulation. Radiofrequency-based systems anchor the technology segment due to proven hemostasis reliability and broad instrument compatibility across specialties. Bipolar instruments are capturing expanded share in minimally invasive applications where targeted energy delivery reduces lateral thermal spread and preserves adjacent tissue integrity. General surgery occupies the largest application volume, though gynecology represents a concentrated margin pool driven by procedural specialization and disposable electrode premiumization.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures govern market access, with both frameworks intensifying scrutiny of electrical safety validation and biocompatibility testing for reusable handpiece components. The EPA regulates sterilization byproduct emissions from reprocessing facilities, influencing hospital decisions between disposable and reusable instrument strategies. Stakeholders must monitor evolving electrosurgical smoke evacuation mandates from OSHA and equivalent occupational health bodies, as workplace exposure standards increasingly dictate capital equipment specifications alongside clinical performance criteria.
Market Dynamics
The EU Medical Device Regulation is compressing market entry timelines while simultaneously elevating electrical safety validation standards for radiofrequency generators and reusable handpiece components.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedural volumes in the United States are accelerating capital equipment refresh cycles for compact electrosurgical platforms. These facilities prioritize space-efficient generators with integrated smoke evacuation.
- OSHA workplace exposure mandates:Evolving electrosurgical smoke evacuation standards in the United States are forcing hospital capital committees to specify filtration-equipped generators regardless of price premium.
- Minimally invasive surgery penetration:Laparoscopic and robotic-assisted procedures favor bipolar instruments with targeted energy delivery, expanding the addressable instrument base beyond traditional monopolar systems.
Market Restraints
- Copper and precious metal volatility:Electrode manufacturing depends on conductive alloys whose commodity price swings compress margin predictability for disposable instrument suppliers.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints extend premarket approval timelines for active surgical equipment, freezing product launch schedules.
- Reusable handpiece reprocessing economics:EPA sterilization byproduct regulations raise reprocessing facility compliance costs, narrowing the cost gap with disposables and complicating hospital procurement calculus.
Strategic Opportunities
- China domestic production acceleration:NMPA registration pathway improvements for Class II active devices enable local manufacturing of radiofrequency generators to serve price-sensitive provincial hospital networks.
- AI-integrated feedback algorithms:Real-time tissue impedance monitoring converges with machine learning to automate power modulation, differentiating premium platforms from commodity generators.
- India surgical infrastructure buildout:Ayushman Bharat health mission expansion creates procurement demand for mid-tier electrosurgical systems in tier-2 and tier-3 cities previously dependent on manual surgical techniques.
Industry Challenges
- Biomedical engineering talent scarcity:Electrosurgical device development requires specialized expertise in high-frequency circuit design and thermal modeling that outpaces university program output.
- Legacy generator fleet interoperability:Hospital systems with decade-old capital equipment face integration friction when attaching new proprietary consumables, complicating vendor switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrosurgical Devices Market |
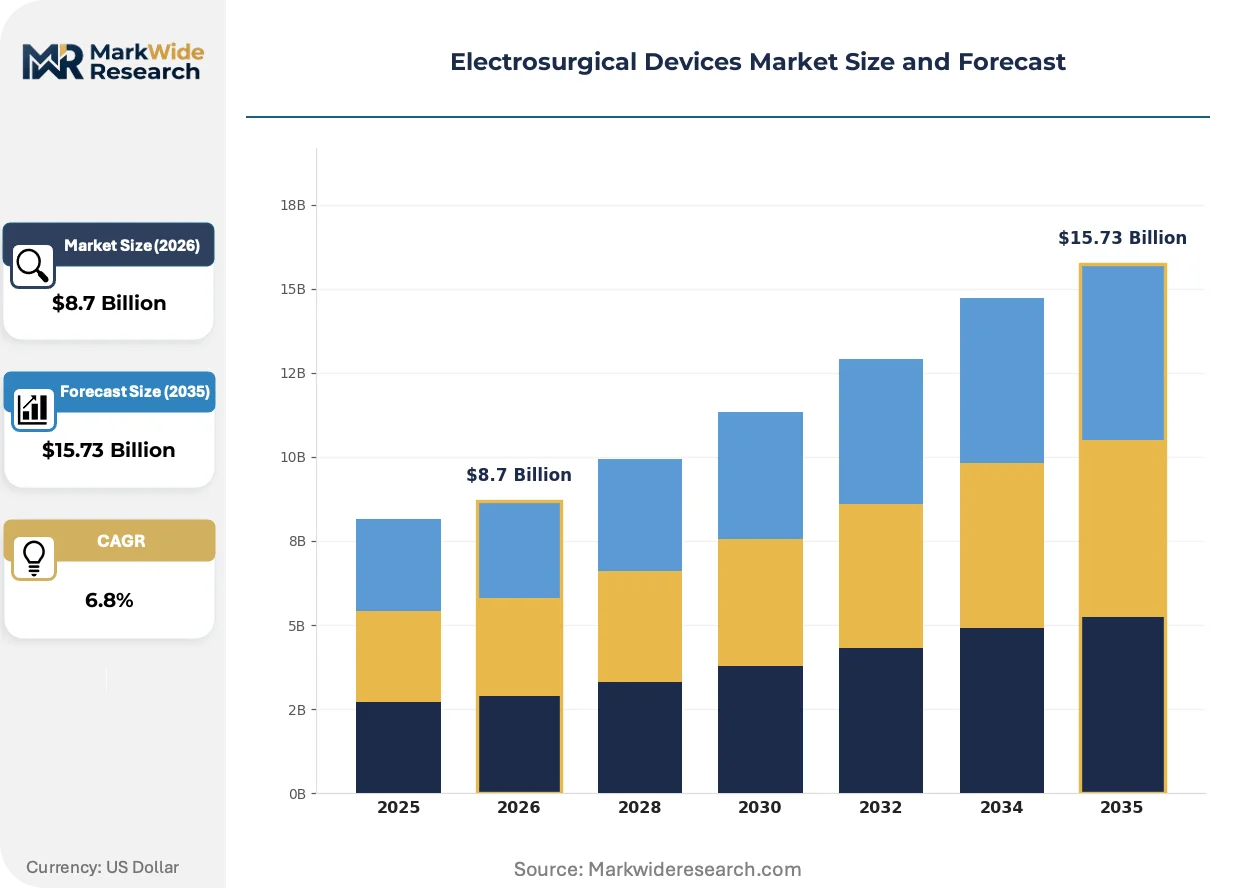
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopolar, Bipolar, Hybrid, Accessories End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Application: General Surgery, Gynecology, Orthopedics, Cardiology Technology: Plasma, Laser, Radiofrequency, Microwave |
| Companies Covered | Medtronic, Johnson & Johnson (Ethicon), B. Braun Melsungen AG, Olympus Corporation, Boston Scientific Corporation, CONMED Corporation, Applied Medical Resources Corporation, Erbe Elektromedizin GmbH, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrosurgical Devices Market Emerging Trajectories
Digital connectivity and intelligent energy delivery are redefining competitive differentiation in electrosurgical platforms, shifting value capture from hardware specifications to procedural data integration.
Advanced impedance-sensing generators with closed-loop power modulation are virtualizing the traditional surgeon-controlled energy application process. Academic medical centers in Germany and the United States are piloting these systems for complex hepatobiliary procedures where thermal injury precision determines outcomes. This virtualization compresses the learning curve for advanced vessel sealing while reducing variance in tissue effect quality across operator experience levels.
EU MDR recertification deadlines for legacy active surgical equipment are forcing manufacturers to regenerate clinical evidence packages for products with decades of safe use history. The industrial consequence is a concentration of regulatory affairs resources toward portfolio maintenance rather than novel platform development. Small and mid-sized device firms without captive notified body relationships face existential timeline pressure, accelerating strategic exits to larger conglomerates with established EU conformity infrastructure.
Integrated health networks in the United States are consolidating electrosurgical procurement decisions at the system level rather than individual hospital autonomy. Supply chain directors now mandate cross-facility standardization on single energy platforms to simplify instrument inventory and negotiate volume-based consumable pricing. This concentration is most visible in the Southeast and Midwest where Catholic health systems and for-profit chains have completed multi-hospital acquisitions, compressing the vendor shortlist to suppliers with national service footprints and GPO contract alignment.
Electrosurgical Devices Market Segmentation
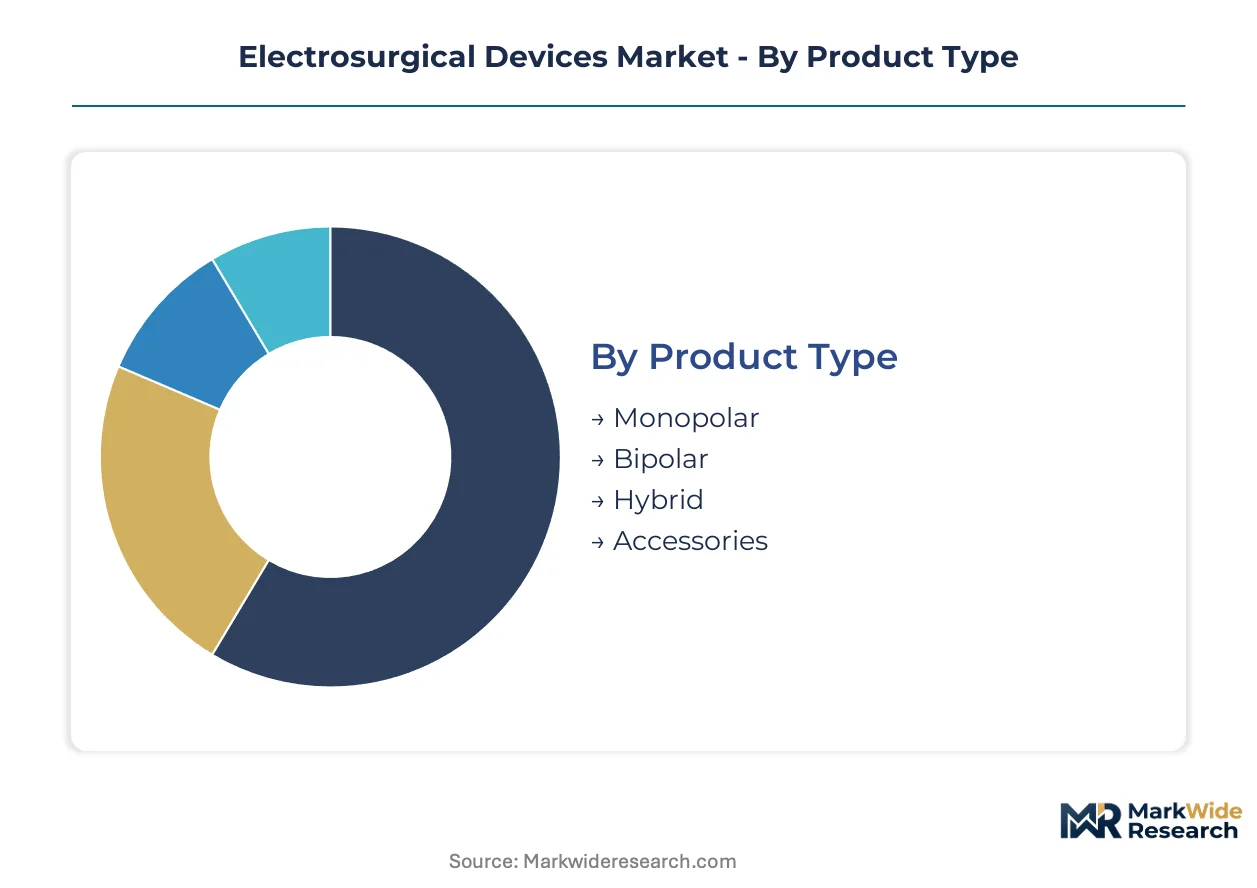
Electrosurgical device segmentation reflects divergent service intensity requirements across product architectures and clinical settings. Technical complexity of generator platforms versus disposable instrument volumes creates distinct margin profiles and customer retention mechanics.
Product Type:
After-sales service intensity varies sharply across product architectures, with capital equipment demanding field engineering support while consumables rely on logistics reliability.
- Monopolar:High-frequency current flows from generator through active electrode to patient return electrode, enabling rapid tissue cutting with broad thermal spread. General surgery departments in United States academic medical centers drive replacement demand as legacy generator fleets age beyond decade-long depreciation cycles. Service contracts for these systems generate recurring revenue streams that anchor vendor relationships.
- Bipolar:Current passes between two closely spaced electrodes at the instrument tip, confining thermal effect to targeted tissue with minimal lateral damage. Minimally invasive surgery suites in Germany and Japan specify these instruments for robotic-assisted procedures where tissue preservation determines outcomes. Premium pricing reflects proprietary feedback algorithms that automate power modulation.
- Hybrid:Combines monopolar cutting capability with bipolar coagulation in single instrument platforms. United States integrated health networks favor hybrid configurations to reduce capital footprint in space-constrained ambulatory facilities.
- Accessories:Encompasses patient return electrodes, footswitches, and connection cables with standardized electrical interfaces. Procurement concentrates through group purchasing organizations seeking volume leverage on high-turnover consumables.
Monopolar holds the largest share; momentum sits with bipolar as minimally invasive penetration deepens.
End User:
Capital allocation authority and procurement sophistication diverge across facility types, shaping pricing architecture and contract terms.
- Hospitals:Comprehensive surgical departments with centralized biomedical engineering support and established vendor relationships. United States health systems negotiate enterprise-wide agreements bundling generator platforms with multi-year consumable commitments.
- Clinics:Outpatient facilities performing limited procedural volumes with constrained equipment budgets. These sites prioritize compact radiofrequency generators with simplified user interfaces over advanced feature sets.
- Ambulatory Surgical Centers:Specialized facilities optimized for same-day discharge procedures with space-efficient layouts. OSHA smoke evacuation mandates in United States drive capital refresh cycles for integrated generator-evacuation platforms. These centers represent the steepest expansion trajectory as outpatient migration accelerates.
- Research Laboratories:Academic and commercial R&D facilities utilizing electrosurgical platforms for preclinical studies and device validation. Procurement emphasizes precision instrumentation with data logging capabilities for protocol documentation.
Hospitals dominate installed base; ambulatory surgical centers are gaining share fastest through outpatient volume migration.
Application:
Procedural volume concentration and reimbursement economics create tiered market attractiveness across surgical specialties.
- General Surgery:Broadest procedural footprint encompassing cholecystectomy, appendectomy, and hernia repair with standardized technique protocols. United States community hospitals and European district hospitals generate baseline demand for reliable mid-tier generator systems.
- Gynecology:Hysteroscopic and laparoscopic procedures with specialized instrument geometries requiring dedicated electrode configurations. Premium disposable pricing in this segment reflects procedural specialization and surgeon training infrastructure investment.
- Orthopedics:Soft tissue dissection and hemostasis in joint reconstruction and spine procedures. Demand concentrates in United States specialty orthopedic hospitals and German musculoskeletal centers with high arthroscopy volumes.
- Cardiology:Electrosurgical applications in cardiac rhythm device implantation and electrophysiology ablation. Regulatory scrutiny from FDA and notified bodies elevates electrical safety validation requirements for these critical applications.
General surgery commands the largest volume; gynecology offers the most concentrated margin pool through premium consumable attachment.
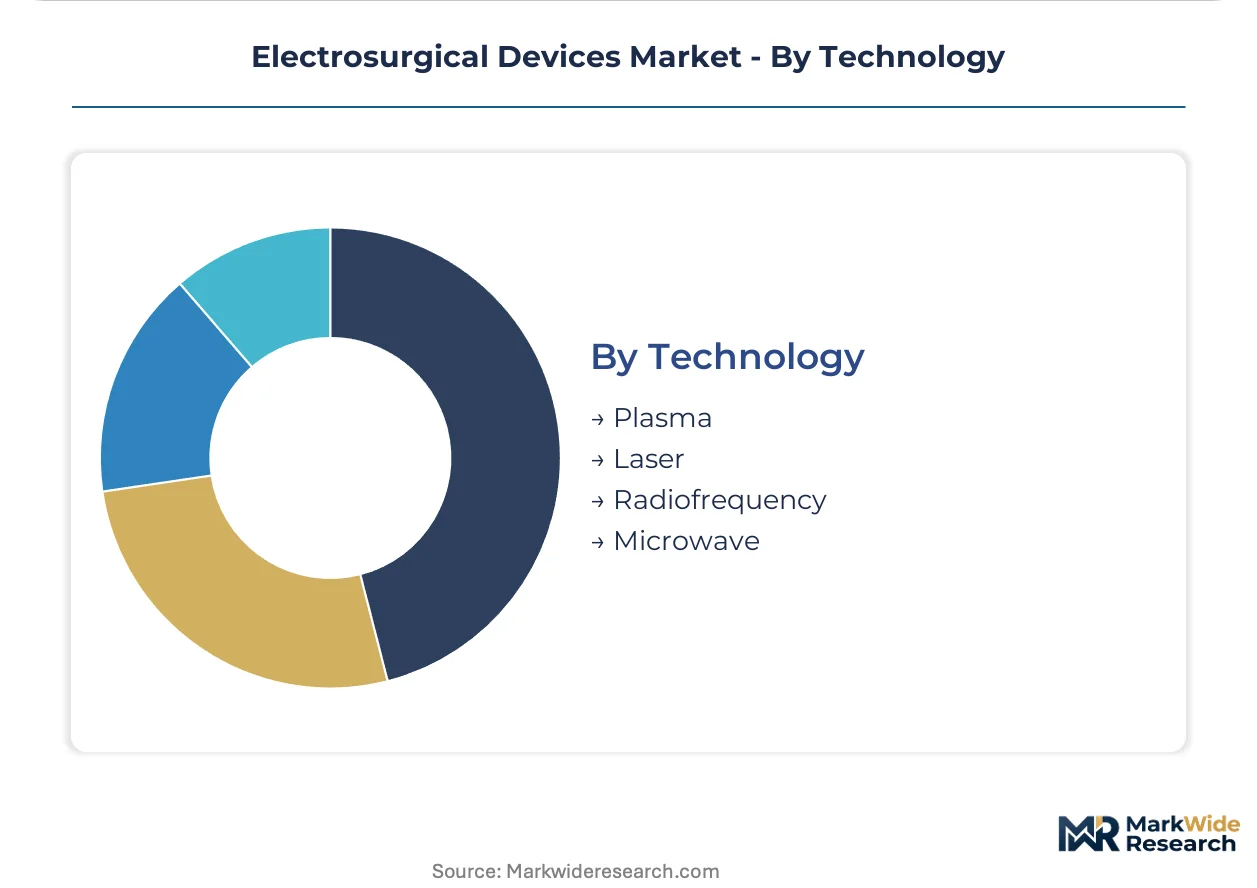
Technology:
Energy delivery modality determines thermal effect precision, tissue interaction physics, and competitive differentiation potential.
- Radiofrequency:Alternating current between 300 kHz and 3 MHz generates resistive heating for cutting and coagulation with proven hemostasis reliability. This technology anchors the installed base across United States, Germany, and Japan due to broad instrument compatibility and established surgeon familiarity.
- Plasma:Ionized gas stream enables non-contact tissue ablation with minimal thermal penetration. Applications concentrate in otolaryngology and dermatology where surface effect precision outweighs cutting speed requirements.
- Laser:Coherent light energy for tissue vaporization with wavelength-selective absorption characteristics. Premium positioning in aesthetic and ophthalmic procedures where thermal collateral damage must be eliminated.
- Microwave:Electromagnetic radiation at 915 MHz or 2.45 GHz for volumetric tissue heating. Emerging applications in hepatic tumor ablation where deep coagulation zones reduce local recurrence versus radiofrequency approaches.
Radiofrequency maintains dominant installed position; microwave is expanding most quickly in interventional oncology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of electrosurgical generators and precision electrodes clusters in Germany, the United States, and China, with each hub serving distinct regulatory environments and procurement channels. Hospital consolidation and ambulatory expansion are redrawing demand geography across mature and emerging markets.
United States
Integrated health networks in the Southeast and Midwest are standardizing electrosurgical procurement across multi-hospital systems, compressing vendor shortlists to suppliers with national service footprints. OSHA workplace exposure mandates for electrosurgical smoke evacuation are forcing capital committees to specify filtration-equipped generators regardless of price premium. The Minneapolis-Saint Paul corridor hosts major device manufacturers serving these consolidated health systems.
Germany
Academic medical centers in Baden-Württemberg and Bavaria are piloting impedance-sensing generators with closed-loop power modulation for complex hepatobiliary procedures. EU MDR recertification deadlines for legacy active surgical equipment are forcing manufacturers to regenerate clinical evidence packages, concentrating regulatory affairs resources toward portfolio maintenance. The Tübingen-Stuttgart medical technology cluster anchors precision electrode development for robotic-assisted surgery.
China
Provincial hospital networks are expanding procurement of domestically manufactured radiofrequency generators as NMPA registration pathways improve for Class II active devices. Dual carbon goals from MEE are influencing sterilization byproduct management decisions in reprocessing facilities. The Suzhou-Wuxi corridor in Jiangsu Province is expanding cleanroom manufacturing capacity for precision electrosurgical instruments serving price-sensitive domestic markets.
Japan
Minimally invasive surgery suites in Tokyo and Osaka are specifying bipolar instruments for robotic-assisted procedures where tissue preservation determines outcomes. PMDA electrical safety validation requirements for active surgical equipment maintain elevated barriers for foreign device entrants. The Chubu region around Nagoya hosts precision component suppliers feeding domestic generator assembly operations.
India
Ayushman Bharat health mission expansion is creating procurement demand for mid-tier electrosurgical systems in tier-2 and tier-3 cities previously dependent on manual surgical techniques. CDSCO regulatory harmonization with IMDRF standards is streamlining market entry for radiofrequency generators. The Mumbai-Pune corridor in Maharashtra is emerging as a distribution hub serving western and central Indian hospital networks.
Electrosurgical Devices Market Vendor Landscape
Diversified surgical conglomerates and specialized energy platform developers split the market along integrated-versus-focused capability lines. The vendor base organizes into three strategic archetypes: full-line surgical suppliers bundling energy with stapling and visualization, pure-play electrosurgical specialists defending instrument attachment economics, and regional champions serving price-sensitive procurement channels. Competitive moves concentrate on M&A to capture EU MDR conformity infrastructure and strategic partnerships to secure GPO contract alignment.
Among diversified surgical conglomerates, Medtronic and Johnson & Johnson (Ethicon) exemplify the integrated-platform archetype, leveraging enterprise-wide agreements to bundle generator placements with multi-year consumable commitments. Erbe Elektromedizin GmbH occupies a position within the specialized energy platform tier, representing German precision engineering in radiofrequency generator development. These three anchors illustrate how competitive positioning diverges between scale-driven system bundling and technical specialization in feedback algorithm development.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson (Ethicon) |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Boston Scientific Corporation |
| CONMED Corporation |
| Applied Medical Resources Corporation |
| Erbe Elektromedizin GmbH |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
The Suzhou-Wuxi corridor in Jiangsu Province anchors precision electrode manufacturing capacity, with cleanroom expansion dynamics directly translating to downstream pricing power for domestic Chinese suppliers serving provincial hospital networks. Generator assembly in Germany and the United States maintains premium positioning through proprietary feedback algorithm integration, while copper and precious metal commodity swings compress margin predictability for disposable instrument suppliers regardless of geographic origin.
Pricing Analysis
EU MDR conformity assessment requirements dictate the pricing tier structure across active surgical equipment, with electrical safety validation investment separating premium generator platforms from mid-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling intensity. Cost compression in the economy tier is intensifying because NMPA pathway improvements enable Chinese domestic manufacturers to undercut legacy suppliers on radiofrequency generator placements. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while academic medical centers in Germany and the United States prioritize performance specifications over procurement cost.
Supply Chain Analysis
Extended payment terms from integrated health networks in the United States are forcing component suppliers to utilize supply-chain finance facilities, altering working capital dynamics across the electrosurgical device ecosystem. Manufacturing concentrates in Germany, the United States, and China, with precision electrode fabrication drawing from copper alloys, precious metal coatings, and ceramic insulator substrates. Single-source vulnerability in high-frequency circuit board supply from Japanese component houses creates chokepoint exposure for generator assembly operations. Distribution runs through group purchasing organizations in the United States and direct hospital contracts in Germany, with regional distributors serving tier-2 and tier-3 cities in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in high-frequency circuit design and thermal modeling is outpacing university program output, creating a persistent capability gap that shapes competitive durability across the electrosurgical device value chain. This scarcity concentrates development capacity within incumbent conglomerates and German precision engineering specialists, elevating the strategic value of captive R&D infrastructure.
For Market Incumbents: Insulate proprietary feedback algorithm portfolios through accelerated patent filing in AI-integrated power modulation, while expanding captive notified body relationships to preempt EU MDR conformity assessment bottlenecks. Vertical integration into precision electrode manufacturing in the Suzhou-Wuxi corridor reduces copper alloy cost exposure and secures supply continuity for disposable instrument attachments. For New Entrants and Emerging Players: Pursue mid-tier electrosurgical system procurement opportunities in tier-2 and tier-3 Indian cities under Ayushman Bharat expansion, where incumbent service footprints remain underdeveloped. Gynecology applications offer the most penetrable segment due to procedural specialization requirements that reward focused instrument development over full-platform competition. Partner with regional distributors in Maharashtra to secure CDSCO registration pathway navigation and hospital procurement committee access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant electrosurgical divisions lacking EU MDR recertification resources. Long-term viability hinges on regulatory affairs infrastructure ownership rather than product differentiation alone. Watch NMPA Class II active device registration timeline compression as the signal indicating when Chinese domestic production acceleration will trigger price-based displacement in Southeast Asian export markets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Infrastructure Acquisition | Captive notified body relationships compress recertification timelines for legacy generator portfolios. |
| AI-Integrated Feedback Algorithm Development | Real-time tissue impedance monitoring with machine learning automation differentiates premium platforms from commodity generators. |
| China Domestic Manufacturing Footprint | NMPA registration pathway improvements enable local radiofrequency generator production for price-sensitive provincial networks. |
| Hospital System Partnership Consolidation | Enterprise-wide agreements with integrated health networks in the United States secure multi-year consumable attachment commitments. |
| Smoke Evacuation Integration Platform | OSHA workplace exposure mandate compliance positions filtration-equipped generators as mandatory capital specifications. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at active surgical equipment manufacturers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement records. Bottom-up triangulation across generator placement volumes and consumable attachment rates converged with top-down market sizing through health system capital expenditure tracking.
Forecast inputs span product type segmentation across monopolar, bipolar, hybrid configurations, and accessories; end user categories including hospitals, ambulatory surgical centers, and clinics; and technology differentiation across radiofrequency, plasma, laser, and microwave energy delivery modalities. CAGRs were derived through installed base depreciation cycle modeling and outpatient procedural volume migration patterns. Electrosurgical smoke evacuation mandate compliance timelines and copper alloy commodity price trajectory assumptions anchor scenario sensitivity testing.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, copper and precious metal commodity volatility, or notified body capacity expansion would shift the trajectory. Forecasts reflect documented assumptions regarding EU MDR recertification deadline adherence and NMPA Class II active device pathway efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endodontic Devices Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Europe Arthroscopy Devices Market