
 Ultrasonic Diathermy Market | 2026-2036
Ultrasonic Diathermy Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Diathermy Market Analytics
Germany is rewriting competitive dynamics in therapeutic device manufacturing through precision engineering clusters in Baden-Württemberg and Bavaria. Zimmer MedizinSysteme GmbH leverages its Stuttgart-area production base to sustain European distribution dominance in electrotherapy and ultrasound systems. Mettler Electronics Corp. anchors North American supply through its therapeutic modality specialization. ELMA Schmidbauer GmbH differentiates via German-engineered transducer reliability and extended service networks.
Ultrasonic diathermy employs high-frequency acoustic waves, typically operating at 1 MHz or 3 MHz frequencies, to generate deep tissue thermal and non-thermal effects for musculoskeletal treatment. The technology converts electrical energy into mechanical vibrations through piezoelectric crystals, producing cavitation and microstreaming that enhance cellular permeability and blood flow in targeted tissue layers. Portable devices command expanding share among mobile physiotherapy services and home-care programs, while combination devices integrating ultrasound with electrical stimulation capture premium positioning in hospital rehabilitation departments. Continuous wave technology dominates pain management protocols, though pulsed wave configurations gain traction in acute injury protocols where thermal dosing requires tighter control.
The FDA's 510(k) premarket notification framework governs US device clearance, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for therapeutic ultrasound systems entering European markets. Germany's national reimbursement catalog under the statutory health insurance system directly shapes clinic purchasing cycles and equipment refresh rates. Stakeholders must monitor evolving MDR conformity assessment timelines and US FDA guidance updates on therapeutic ultrasound indications to align R&D pipelines with regulatory access pathways.
Market Dynamics
Collegiate athletic departments are expanding sports medicine procurement, creating concentrated demand pull for therapeutic modalities that manufacturers must configure around institutional purchasing cycles and facility integration requirements.
Growth Catalysts
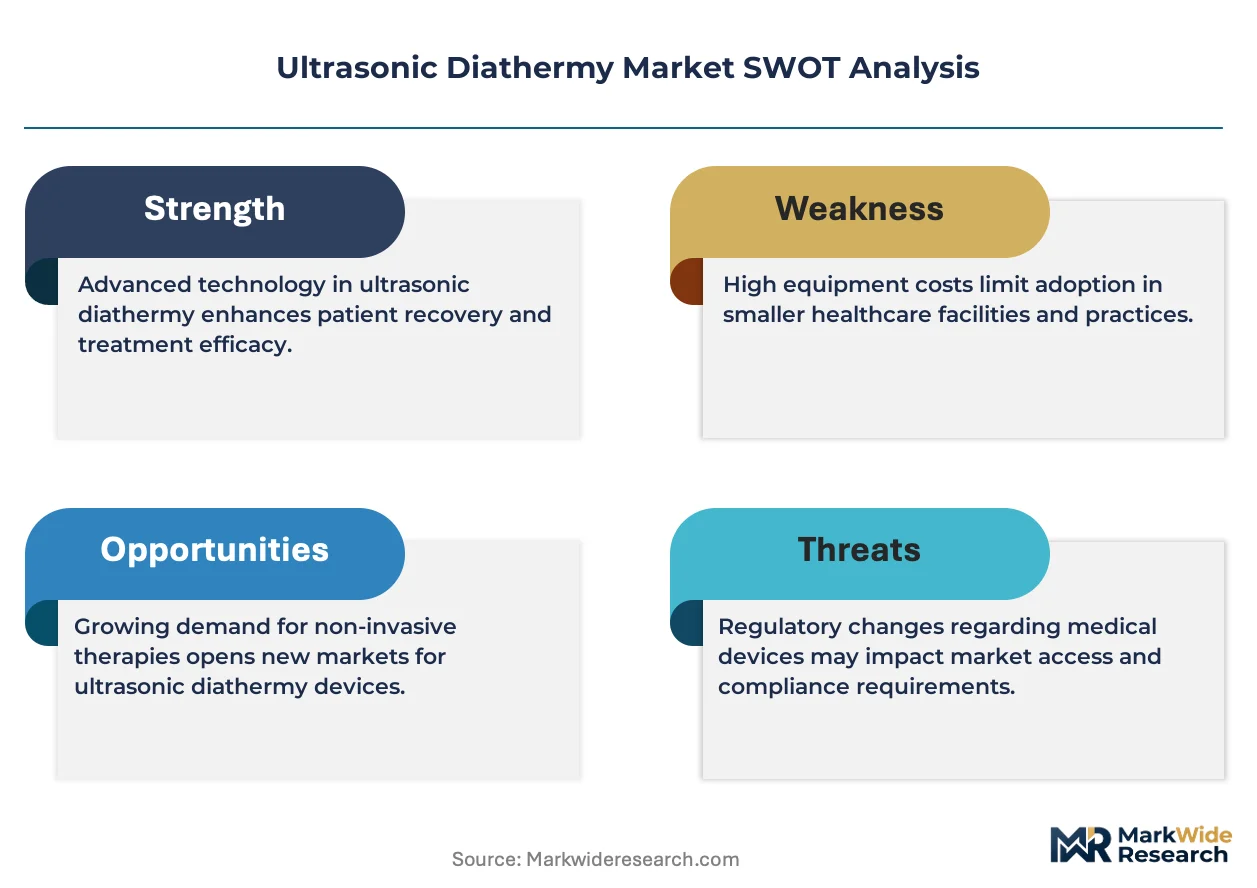
- MDR Conformity Pressure:The EU Medical Device Regulation's stricter clinical evidence requirements for therapeutic ultrasound systems is filtering out marginal competitors and consolidating procurement around established suppliers with robust technical documentation.
- Piezoelectric Crystal Advances:Improved transducer materials are extending device lifecycles and reducing maintenance intervals, lowering total cost of ownership for physiotherapy clinics operating under Germany's statutory health insurance reimbursement framework.
- Home-Care Program Expansion:Mobile physiotherapy services are driving portable device adoption, with battery-operated units capturing share from fixed-installation systems in post-acute care settings.
Market Restraints
- Input Concentration:High-purity piezoelectric ceramics production concentrates in East Asian suppliers, exposing device manufacturers to supply disruption and input cost volatility.
- Technical Ceiling:Thermal dosing precision in continuous wave configurations remains limited for acute injury protocols, constraining penetration in emergency medicine departments.
- FDA 510(k) Friction:The premarket notification pathway for Class II therapeutic devices creates extended clearance timelines that compress effective patent windows and delay revenue recognition.
Strategic Opportunities
- Combination Device Convergence:Integrated systems pairing ultrasound with electrical stimulation capture premium positioning in hospital rehabilitation departments seeking consolidated modality footprints.
- Pulsed Wave Protocol Expansion:Acute injury treatment protocols favoring tighter thermal control are opening substitution opportunities against traditional continuous wave installations in sports medicine clinics.
- Service Network Unbundling:Extended warranty and calibration service contracts represent underdeveloped revenue streams for manufacturers with established transducer reliability credentials.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Therapeutic ultrasound R&D requires specialized expertise in acoustic physics and clinical validation that concentrates in Stuttgart-area and Bavarian engineering clusters.
- Legacy System Integration:Hospital IT infrastructure compatibility requirements complicate connectivity features for new device generations, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Diathermy Market |
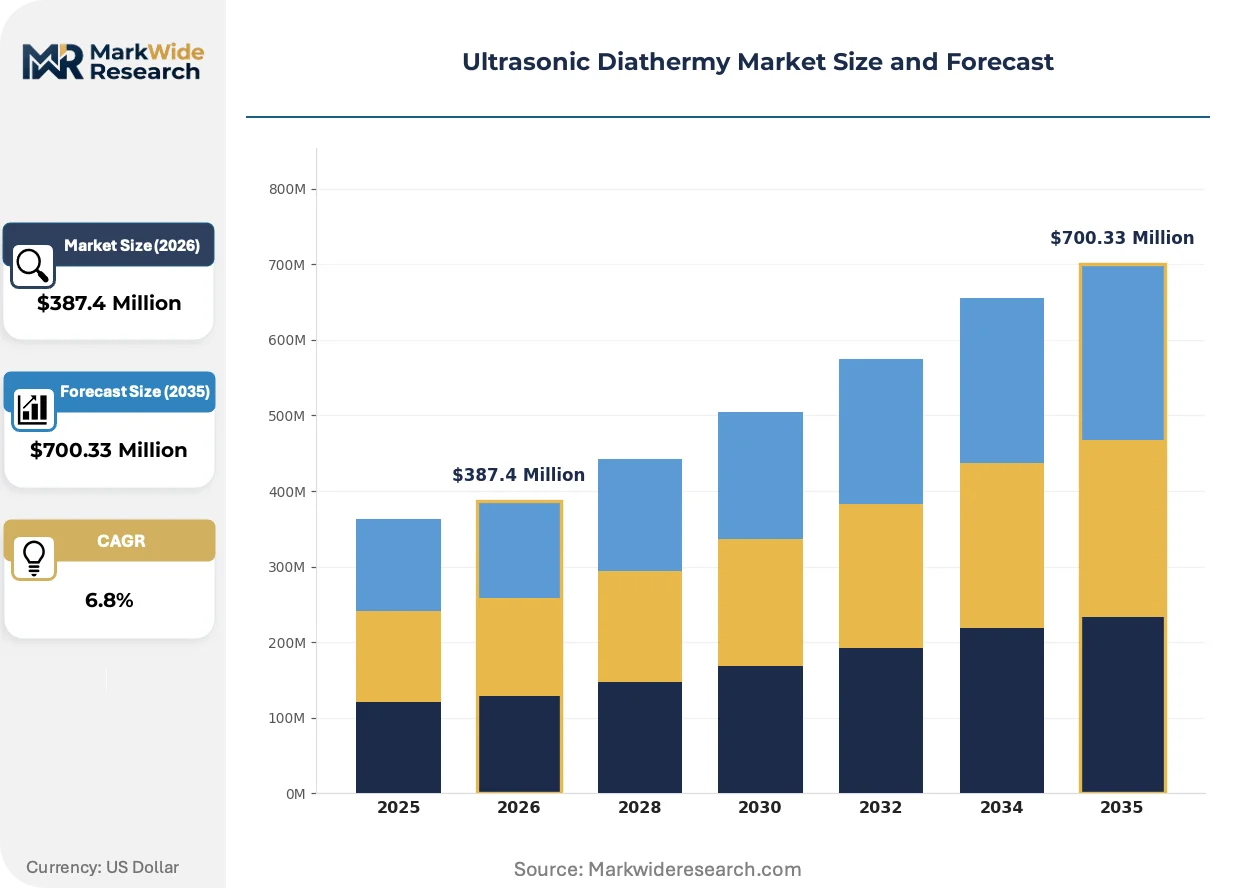
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Desktop Units, Combination Devices, Accessories Application: Pain Management, Tissue Recovery, Muscle Relaxation, Rehabilitation End User: Hospitals, Clinics, Physiotherapy Centers, Sports Facilities Technology: Continuous Wave, Pulsed Wave, High-Intensity Focused, Low-Intensity |
| Companies Covered | EMS Physio Ltd, Physio International, Mettler Electronics Corp., BTL Industries, Zimmer MedizinSysteme GmbH, ACP, Life Care Systems, ELMA Schmidbauer GmbH, Biothech India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Diathermy Market Evolving Landscape
Device architecture is pivoting toward software-defined functionality and modular hardware platforms that enable post-sale capability expansion without physical replacement.
Digital therapeutic interfaces are virtualizing treatment parameter control through tablet-based applications and cloud-connected dosage logging. Sports medicine departments at major universities are piloting these systems for remote protocol adjustment and outcome tracking. This virtualization is compressing the traditional equipment refresh cycle by decoupling hardware from feature upgrades.
The EU Medical Device Regulation's enhanced post-market surveillance requirements are forcing manufacturers to deploy real-world performance monitoring infrastructure. German notified bodies are prioritizing technical documentation audits for therapeutic ultrasound systems, extending conformity assessment timelines. High-volume physiotherapy clinic chains are responding by consolidating procurement around suppliers with established MDR compliance track records.
Equipment leasing structures are displacing outright purchase in hospital capital budgeting, with rehabilitation departments favoring operational expenditure treatment over depreciation schedules. Distributors are repositioning as managed service providers, bundling maintenance and calibration into per-treatment fee arrangements. This shift is most pronounced in Germany's dense physiotherapy clinic networks where equipment utilization rates support usage-based contracting models.
Ultrasonic Diathermy Market Segmentation
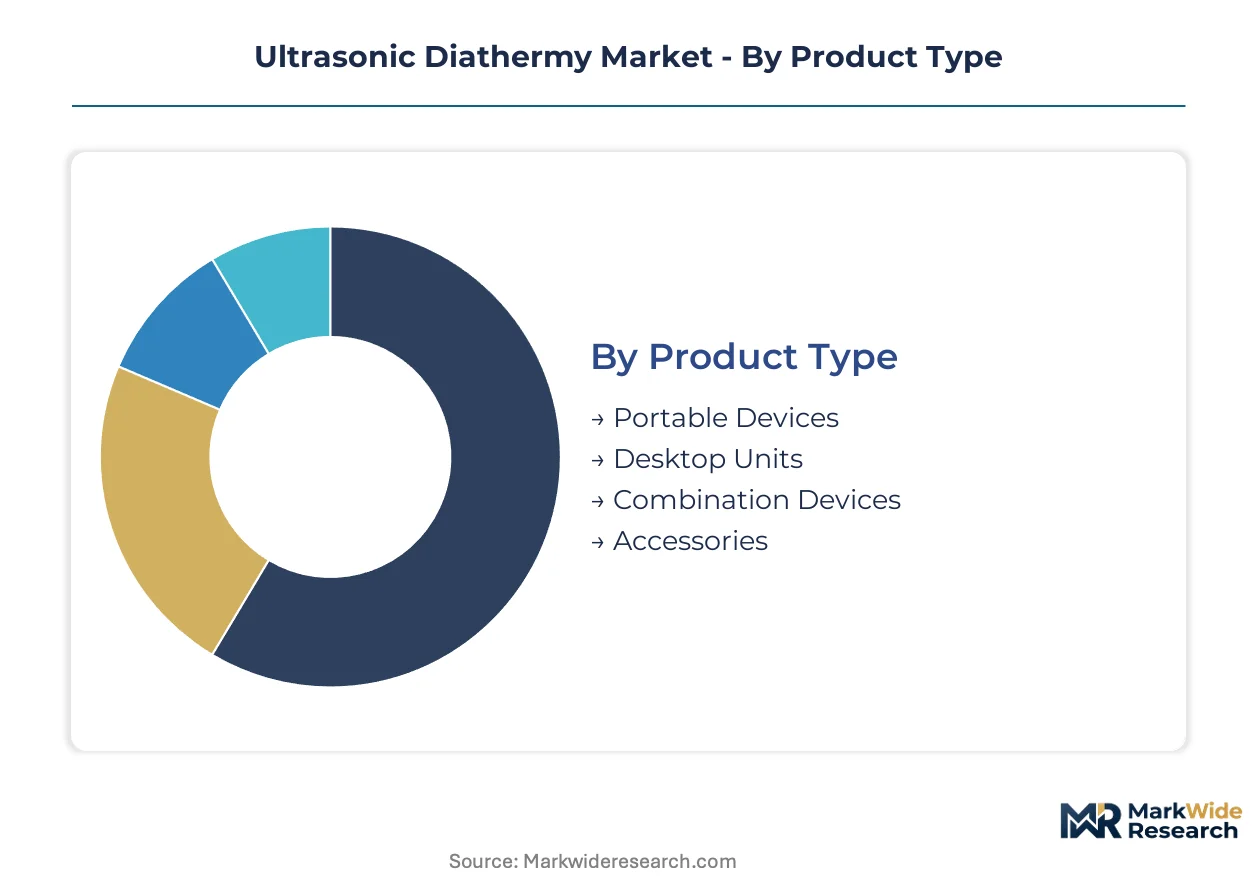
Segmentation in ultrasonic diathermy reveals how clinical settings, patient mobility requirements, and treatment protocols fragment procurement patterns across healthcare infrastructure. Manufacturers configure product portfolios around these divides to capture institutional budgets and reimbursement pathways.
Product Type:
Mature fixed-installation systems coexist with emerging portable formats as physiotherapy delivery models diverge across care settings.
- Portable Devices:Battery-operated units with compact transducer heads enable mobile physiotherapy services and home-care programs. Demand concentrates in Germany's dense clinic networks where statutory health insurance reimbursement supports domiciliary treatment models and equipment leasing structures.
- Desktop Units:Fixed-installation systems with calibrated output stability serve high-throughput physiotherapy centers requiring consistent thermal dosing precision. These systems dominate hospital rehabilitation departments in the United States where FDA 510(k) clearance timelines favor established device architectures.
- Combination Devices:Integrated platforms pairing ultrasound with electrical stimulation capture premium positioning in sports medicine facilities seeking consolidated modality footprints.
- Accessories:Replacement transducers, coupling gels, and calibration tools generate recurring revenue streams tied to device lifecycle management.
Desktop units handle the majority of throughput; portable devices are climbing the fastest on share.
Application:
Clinical protocols stratify around acute versus chronic presentation timelines and thermal dosing requirements.
- Pain Management:Continuous wave configurations deliver deep tissue heating for chronic musculoskeletal conditions. Demand concentrates in United States pain clinics where CPT coding supports therapeutic ultrasound reimbursement.
- Tissue Recovery:Pulsed wave protocols enhance cellular permeability and microcirculation in post-surgical rehabilitation. German orthopedic departments favor these applications under statutory health insurance treatment catalogs.
- Muscle Relaxation:Low-intensity applications target superficial tissue layers for spasm reduction in outpatient settings.
- Rehabilitation:Comprehensive protocols integrating multiple acoustic parameters serve stroke and trauma recovery programs in hospital-based departments.
Pain management absorbs the largest procedure volume; tissue recovery shows the steepest expansion trajectory.
End User:
Purchasing authority concentrates in reimbursement-linked institutions while direct-pay segments experiment with alternative acquisition models.
- Hospitals:Capital budgeting cycles and IT integration requirements shape procurement of connected devices with electronic health record compatibility. United States hospital systems prioritize FDA-cleared platforms with established clinical evidence packages.
- Clinics:Independent physiotherapy practices in Germany operate within statutory health insurance frameworks that dictate equipment refresh rates and technical specifications.
- Physiotherapy Centers:High-volume chains favor operational expenditure treatment through leasing arrangements and per-treatment service contracts.
- Sports Facilities:Collegiate athletic departments drive concentrated demand pull for therapeutic modalities configured around institutional purchasing cycles.
Hospitals command the highest average transaction values; physiotherapy centers are gaining share fastest through consolidation.
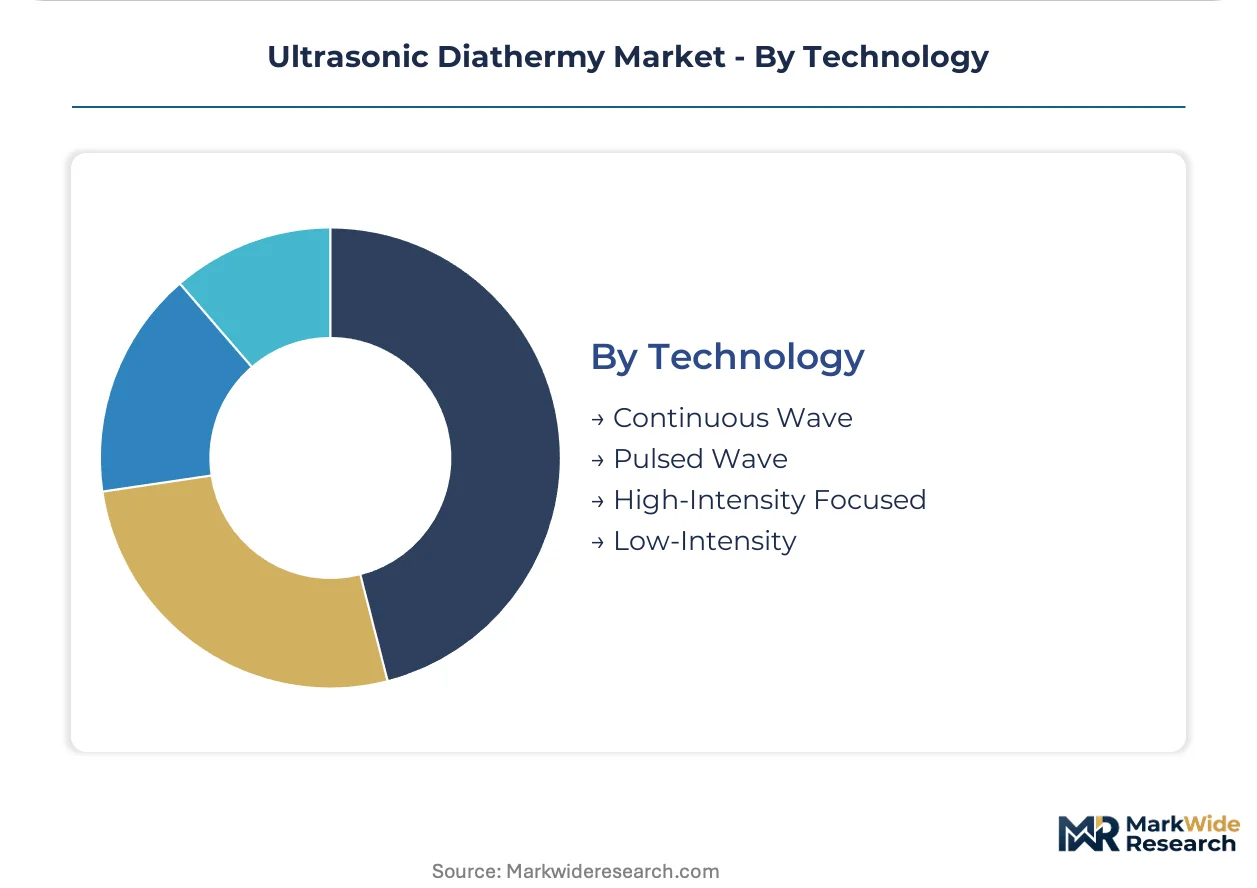
Technology:
Waveform engineering divides between established thermal delivery and emerging non-thermal protocols.
- Continuous Wave:Sustained acoustic output generates predictable thermal gradients for chronic pain protocols. United States sports medicine programs rely on these systems for established treatment algorithms.
- Pulsed Wave:Intermittent energy delivery enables acute injury treatment with tighter thermal control. German clinics adopt these configurations for post-operative protocols under MDR conformity requirements.
- High-Intensity Focused:Concentrated beam geometry targets discrete tissue volumes in specialized therapeutic applications.
- Low-Intensity:Sub-thermal dosing supports cellular stimulation without measurable temperature elevation in sensitive patient populations.
Continuous wave technology maintains installed base dominance; pulsed wave configurations are expanding most quickly in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's 510(k) framework for Class II medical devices anchors procurement patterns in the United States, while Germany's statutory health insurance reimbursement catalog drives equipment refresh cycles across Europe's densest physiotherapy networks.
United States
Collegiate athletic departments and hospital rehabilitation centers generate concentrated demand for therapeutic modalities. The FDA's 510(k) premarket notification pathway governs device clearance timelines and shapes product entry strategies. Boston-area and California medical device clusters host development activity for connected therapeutic systems.
Germany
Statutory health insurance reimbursement frameworks directly dictate clinic purchasing cycles and premium equipment turnover rates. The EU Medical Device Regulation imposes stricter clinical evidence requirements that filter procurement toward established suppliers. Baden-Württemberg and Bavarian precision engineering clusters sustain domestic manufacturing dominance in electrotherapy and ultrasound systems.
United Kingdom
NHS procurement frameworks and private physiotherapy chains drive demand for portable and fixed-installation therapeutic devices. The Medicines and Healthcare products Regulatory Agency oversees device conformity assessment post-Brexit. London and Southeast England concentrate distribution infrastructure for European therapeutic equipment imports.
China
Expanding hospital rehabilitation departments and sports medicine facilities generate procurement growth for therapeutic ultrasound systems. The National Medical Products Administration regulates Class II medical device registration and clinical trial requirements. Yangtze River Delta manufacturing bases produce piezoelectric components for domestic and export device assembly.
Japan
Aging demographics and post-acute care expansion drive adoption of portable therapeutic devices in home-care settings. The Pharmaceuticals and Medical Devices Agency enforces stringent quality management system requirements for therapeutic equipment. Kanto region medical device clusters specialize in miniaturized transducer technology for precision therapeutic applications.
Ultrasonic Diathermy Market Competitive Landscape
German-engineered specialists and diversified therapeutic device manufacturers split the market between premium reliability positioning and portfolio breadth strategies. The vendor base concentrates around established European suppliers with MDR compliance track records and North American specialists with FDA clearance expertise. Three archetypes dominate: precision engineering houses with regional cluster advantages, diversified electrotherapy platforms with multi-modality portfolios, and portable device specialists serving mobile care delivery models. Competitive moves center on MDR technical documentation investments and combination device R&D to capture hospital rehabilitation procurement.
Among Stuttgart-area fabricators, Zimmer MedizinSysteme GmbH anchors the precision engineering tier with regional production base advantages. ELMA Schmidbauer GmbH exemplifies the German-engineered reliability archetype through extended service network positioning. Mettler Electronics Corp. represents North American therapeutic modality specialization with established distribution infrastructure.
| Leading Market Players |
|---|
| EMS Physio Ltd |
| Physio International |
| Mettler Electronics Corp. |
| BTL Industries |
| Zimmer MedizinSysteme GmbH |
| ACP |
| Life Care Systems |
| ELMA Schmidbauer GmbH |
| Biothech India |
| Others |
Value Network & Pricing Analysis
East Asian piezoelectric ceramic production concentrates upstream sourcing for transducer assemblies, anchoring margin capture in device manufacturing downstream where FDA and MDR certification tiers separate premium positioning from commodity competition. German physiotherapy clinic networks and US hospital rehabilitation departments absorb divergent pricing structures shaped by reimbursement frameworks and procurement consolidation.
Pricing Analysis
German statutory health insurance reimbursement catalogs support 15-25% price premiums over US hospital procurement for equivalent device specifications, reflecting divergent buyer archetypes and contract structures. Pricing stratifies across premium, standard, and economy tiers based on MDR conformity assessment depth and transducer calibration certification. Cost compression in portable device segments is intensifying as battery technology commoditizes and Asian assemblers enter European distribution channels. Independent physiotherapy clinics in Germany exhibit highest price sensitivity due to fixed reimbursement rates, while US academic medical centers prioritize clinical evidence packages over unit economics.
Supply Chain Analysis
Export controls on high-purity piezoelectric materials and precision acoustic engineering equipment limit technology transfer from German and Japanese specialty suppliers to emerging manufacturing bases. Device assembly draws from ceramic substrate production in China, transducer fabrication in Japan, and final system integration in Germany and the United States. Single-source vulnerability concentrates in synthetic quartz crystal growth capacity, where two Japanese suppliers control medical-grade material flows. Distribution runs through authorized service networks requiring factory-trained calibration technicians, extending lead times for replacement transducers and favoring regional inventory positioning by established manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic diathermy market rewards regulatory entrenchment as a defensive moat, where MDR technical documentation investments and FDA 510(k) clearance track records create switching costs that marginal competitors cannot replicate.
For Market Incumbents: Build regulatory dossier depth as the primary moat by accelerating MDR Annex II technical documentation investments ahead of notified body audit queues. Anchor capacity addition in Baden-Württemberg precision engineering clusters to sustain transducer reliability credentials against emerging Asian assemblers. Prioritize backward integration into piezoelectric ceramic sourcing through long-term offtake agreements with Japanese material suppliers to mitigate single-source exposure. For New Entrants and Emerging Players: US collegiate athletic departments represent the most penetrable white-space target, as institutional purchasing cycles favor configurable therapeutic modalities with remote protocol management capabilities. Portable device segments for mobile physiotherapy services offer lower regulatory friction than hospital-grade fixed installations. Pursue software-defined functionality as the go-to-market angle, decoupling hardware refresh cycles from feature upgrades through cloud-connected dosage logging platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrotherapy platform companies seeking bolt-on ultrasound capabilities to fill modality portfolio gaps. Five-to-ten year viability hinges on MDR compliance infrastructure amortization and service network density rather than device manufacturing scale. Monitor FDA guidance updates on therapeutic ultrasound indications as the inflection signal for R&D pipeline reallocation and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates notified body audit readiness and filters procurement toward compliant suppliers in German clinic networks. |
| Combination Device R&D | Captures premium positioning in US hospital rehabilitation departments seeking consolidated modality footprints. |
| Service Network Expansion | Generates recurring revenue through calibration contracts tied to transducer lifecycle management in high-volume chains. |
| Pulsed Wave Protocol Development | Opens substitution opportunities in acute injury segments where thermal dosing precision constrains continuous wave penetration. |
| Software Companion Development | Enables remote protocol adjustment and outcome tracking for collegiate athletic department pilot programs. |
Research Methodology
Operator-level perspectives from biomedical engineers, physiotherapy clinic directors, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation audit records, and German statutory health insurance reimbursement catalogs. Bottom-up demand modeling across product type, application, end user, and technology segments triangulated with top-down market sizing from device shipment data and installed base estimates.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting divergent MDR conformity assessment timeline assumptions and US hospital capital expenditure cycle positions. Segmentation dimensions modeled include device format, clinical protocol, purchaser type, and waveform technology, with regional regulatory cluster effects layered across country-level forecasts. CAGRs derived from weighted average of historical equipment refresh rates and projected reimbursement framework evolution, incorporating piezoelectric material cost trajectory assumptions and portable device adoption curve parameters.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian device assemblers or sudden export restrictions on Japanese ceramic substrates would shift outcomes beyond modeled ranges. Material shifts in FDA guidance on therapeutic ultrasound indications or EU MDR post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Connectivity Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Urology Guidewires Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Neuromuscular Transmission Monitor Market