
 Global Endoscopic Clips Market | 2026-2036
Global Endoscopic Clips Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopic Clips Market Foresight
Ambulatory surgery centers are redrawing procurement patterns in endoscopic clips, pulling volume away from hospital-centric supply chains. Olympus Corporation dominates gastrointestinal device distribution across Asia-Pacific markets. Boston Scientific Corporation differentiates through hemostasis application specialization. Cook Medical anchors its position via deep relationships with ambulatory surgery center networks.
Endoscopic clips are metallic or polymeric implantable devices delivered through flexible endoscopes to mechanically approximate tissue or achieve hemostasis, typically constructed from nitinol or stainless steel with silicone or rubber overmolding for atraumatic grip. These devices serve primarily to arrest gastrointestinal bleeding and close mucosal defects without open surgery. Over-the-scope clips command premium positioning due to their superior closure force in refractory fistulas, while through-the-scope variants sustain higher procedural volume in routine polypectomy settings. Deployment methodology segments sharply between manual torque-controlled systems favored in cost-sensitive clinics and automated deployment platforms gaining traction in academic medical centers.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and material selection for nitinol-based clip architectures. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 govern supplier qualification across manufacturing tiers. Stakeholders must monitor how FDA guidance on reusable device reprocessing and EU F-Gas Regulation implications for sterilization equipment reshape total cost-of-ownership calculations for clip deployment systems.
Market Dynamics
EU MDR biocompatibility testing requirements are compressing product development timelines for nitinol-based clip architectures while simultaneously elevating qualification barriers for new entrants.
Growth Catalysts
- MDR conformity assessments:Stricter EU biocompatibility mandates under ISO 10993 are accelerating R&D investment in advanced nitinol surface treatments and silicone overmolding techniques.
- Ambulatory surgery centers:These facilities in Germany, Japan, and the United States are driving faster clip adoption than traditional hospitals by prioritizing same-day discharge protocols.
- Over-the-scope technology:Superior closure force in refractory fistula applications is expanding addressable procedural volumes beyond routine polypectomy settings.
Market Restraints
- Nitinol supply concentration:Specialty shape-memory alloy production concentrates among a limited supplier base, exposing manufacturers to raw material volatility and qualification delays.
- FDA 510(k) pathway friction:Reusable device reprocessing guidance creates extended review cycles for automated deployment platforms, stretching time-to-market for academic medical center-focused systems.
- Mechanical substitute competition:Endoscopic suturing devices and thermal ablation systems compete for hemostasis procedures in select gastrointestinal bleeding presentations.
Strategic Opportunities
- Underpenetrated Japanese outpatient networks:METI-supported same-day surgery expansion creates whitespace for through-the-scope clip volumes outside Tokyo-Osaka hospital corridors.
- EU F-Gas Regulation tailwind:Sterilization equipment requalification requirements are forcing equipment replacement cycles that favor integrated clip deployment system vendors.
- Automated-manual convergence:Hybrid torque-feedback platforms combining manual control with precision deployment are opening mid-tier clinic segments previously cost-excluded from advanced systems.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization study bottlenecks at qualified laboratories are extending product validation timelines.
- Legacy sterilization infrastructure:Existing hospital ethylene oxide and hydrogen peroxide plasma systems require revalidation for new clip delivery device materials, complicating facility-level adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopic Clips Market |
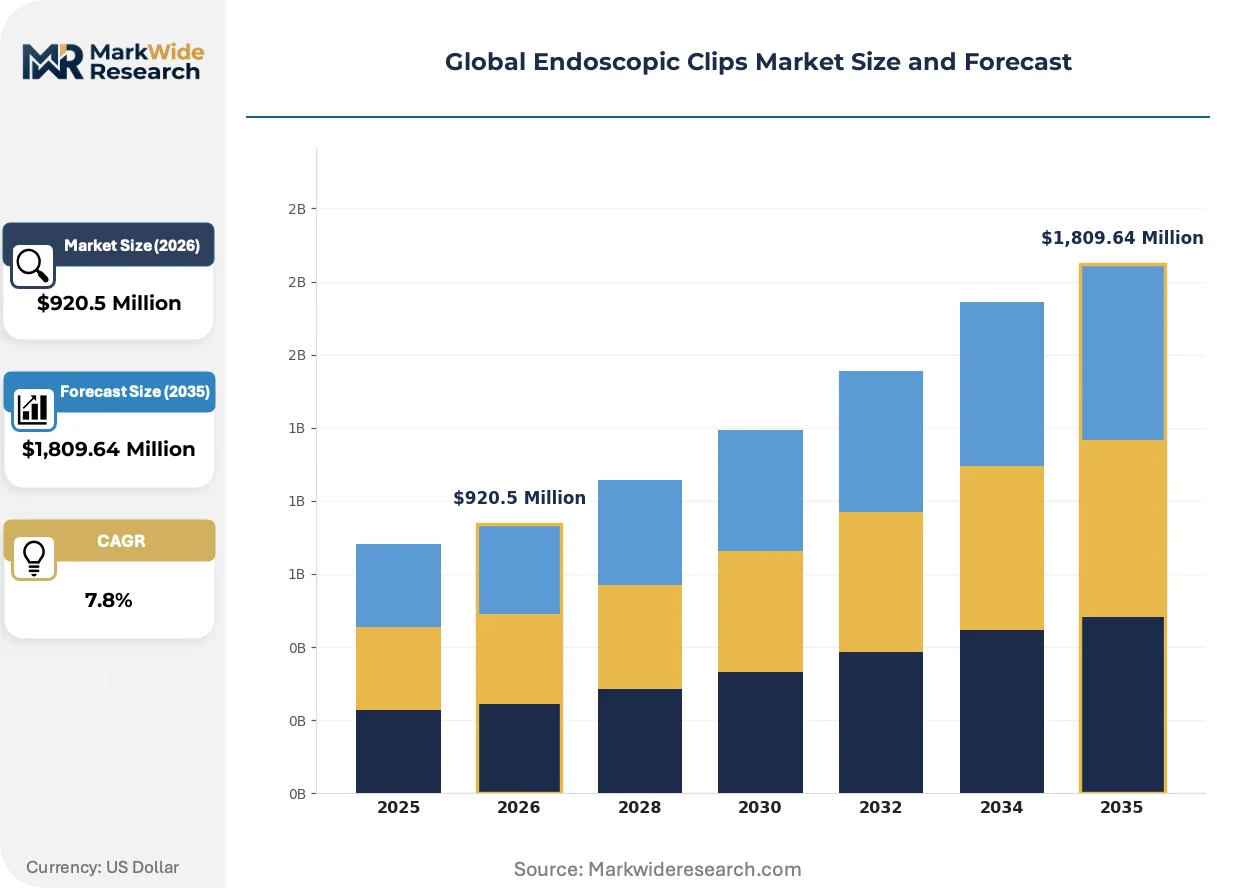
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,809.64 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Through-the-Scope Clips, Over-the-Scope Clips, Resolution Clips, Triangular Clips, Detachable Clips Application: Hemostasis, Tissue Approximation, Gastrointestinal Bleeding, Polypectomy, Anastomotic Leak Closure End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions, Diagnostic Centers Deployment: Single-Use, Reusable, Manual Deployment, Automated Deployment, Torque-Controlled |
| Companies Covered | CONMED Corporation, Johnson & Johnson, Boston Scientific Corporation, Fujifilm Holdings Corporation, Ovesco Endoscopy, Olympus Corporation, Cook Medical, Teleflex Incorporated, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopic Clips Market Shifts & Advancements
Device miniaturization and materials science advances are fragmenting competitive positioning across deployment methodology tiers while regulatory harmonization efforts create divergent compliance pathways.
Robotic-assisted endoscopic platforms are fragmenting the traditional manual clip deployment segment. Academic medical centers in the United States and South Korea are piloting autonomous positioning systems that reduce operator variability in complex fistula closures. This capability compression is forcing manual torque-controlled vendors to defend position through price repositioning in cost-sensitive ambulatory settings.
EU MDR Article 10 technical documentation requirements are reshaping supplier qualification protocols. Manufacturers must now demonstrate nitinol traceability from melt source through final sterilization, elevating documentation burdens for second-tier component vendors. German notified bodies are processing these submissions with extended review cycles, delaying CE marking for novel clip architectures.
Hospital purchasing consortiums are consolidating procurement authority for endoscopic accessories across multi-facility networks. United States-based integrated delivery networks are unbundling clip pricing from endoscope service contracts, forcing manufacturers to compete on standalone value metrics. This concentration is most visible in the southeastern United States, where regional purchasing cooperatives now control access to ambulatory surgery center networks.
Global Endoscopic Clips Market Segmentation
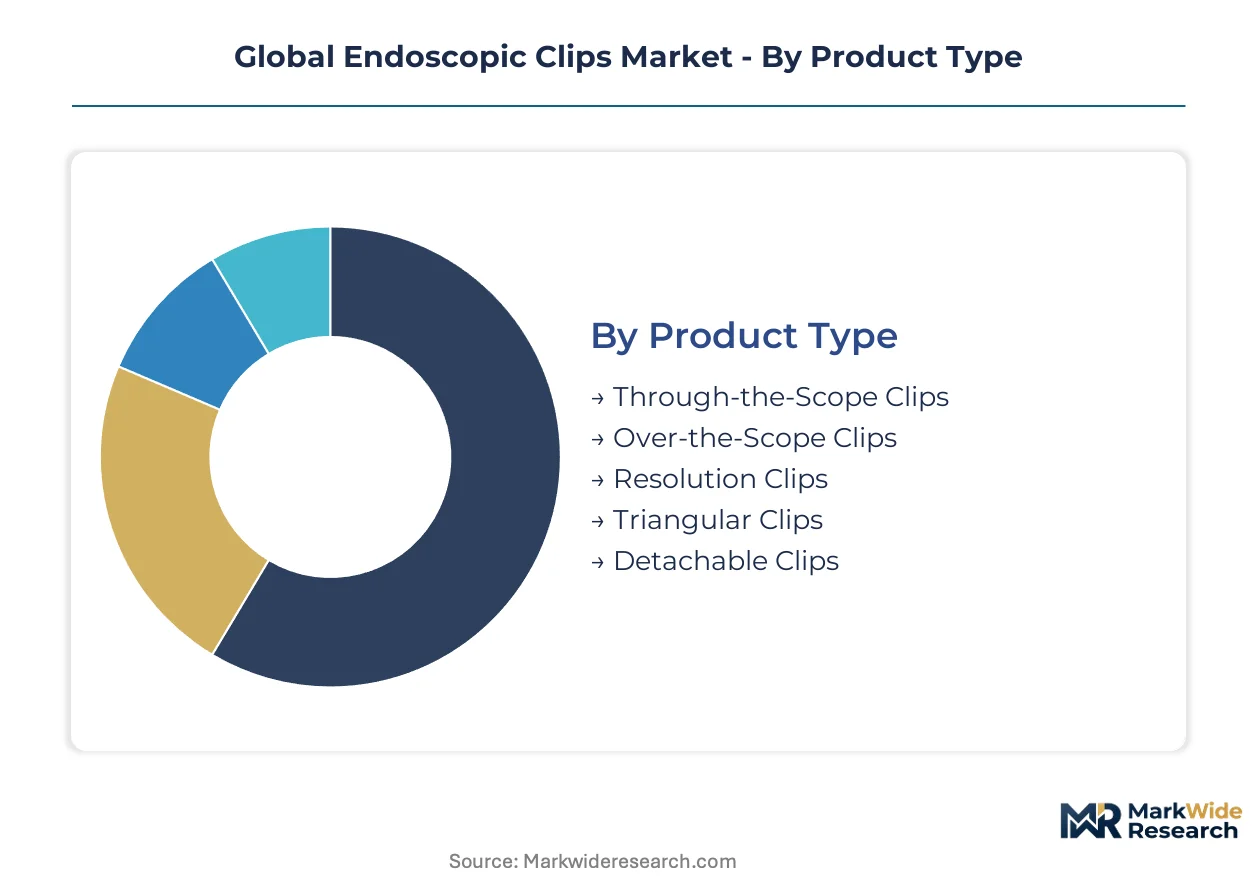
Endoscopic clip segmentation reveals divergent channel economics across deployment methodologies. Product architecture and application setting determine whether clips flow through hospital supply chains or ambulatory surgery center procurement networks.
Product Type:
Channel access varies sharply by clip architecture, with over-the-scope systems commanding premium placement in academic medical centers while through-the-scope variants penetrate cost-sensitive clinic networks.
- Through-the-Scope Clips:These nitinol or stainless steel devices deploy via standard endoscope working channels for routine polypectomy and hemostasis. Demand concentrates in German and United States ambulatory surgery centers where same-day discharge protocols prioritize procedural speed over closure force. Reimbursement compression in outpatient settings sustains volume leadership despite lower per-unit pricing.
- Over-the-Scope Clips:Larger-capacity systems mounted on cap-based delivery platforms generate superior mechanical force for refractory fistula closure. Academic medical centers in Japan and South Korea absorb premium pricing for complex anastomotic leak applications where surgical alternatives carry higher morbidity. METI-supported same-day surgery expansion in Japanese prefectures outside Tokyo-Osaka corridors is expanding addressable volume.
- Resolution Clips:Rotatable designs with dual-action jaws target precise mucosal defect closure in polypectomy settings.
- Triangular Clips:Three-pronged configurations distribute closing force across broader tissue surface areas in large defect applications.
- Detachable Clips:Release mechanisms enable repositioning prior to final deployment, reducing misplacement risk in difficult anatomical locations.
By volume, Through-the-Scope Clips leads. By growth pace, Over-the-Scope Clips is ahead.
Application:
Clinical indication determines reimbursement tier and facility qualification requirements, with hemostasis applications penetrating broader provider networks than complex fistula closure.
- Hemostasis:Arrest of gastrointestinal bleeding represents the foundational indication across all clip architectures. United States ambulatory surgery centers and Japanese outpatient networks drive procedural volume for non-variceal upper GI bleeding where thermal ablation alternatives compete on speed. FDA 510(k) clearance pathways for hemostasis claims require less extensive clinical evidence than novel tissue approximation indications.
- Tissue Approximation:Mechanical closure of mucosal defects without suture placement demands superior mechanical properties and operator training. German hospital networks and South Korean academic centers concentrate demand for complex fistula and perforation closure where over-the-scope systems justify premium positioning. EU MDR biocompatibility documentation requirements extend validation timelines for expanded tissue approximation claims.
- Gastrointestinal Bleeding:Emergency settings prioritize rapid deployment capability over precision features.
- Polypectomy:Routine resection sites in screening colonoscopy generate high-volume, price-sensitive demand.
- Anastomotic Leak Closure:Post-surgical complications require specialized clip configurations and advanced endoscopic expertise.
Hemostasis captures the largest procedure count. Tissue Approximation is climbing the fastest as complex endoscopic interventions displace surgical alternatives.
End User:
Procurement authority consolidation across integrated delivery networks is fragmenting vendor access patterns by facility type.
- Hospitals:Traditional inpatient and outpatient departments maintain preference for automated deployment platforms and comprehensive service contracts. Southeastern United States purchasing cooperatives now unbundle clip pricing from endoscope service agreements, forcing standalone value demonstration. Legacy ethylene oxide sterilization infrastructure complicates adoption of novel clip delivery materials.
- Ambulatory Surgery Centers:Same-day discharge protocols in Germany, Japan, and the United States prioritize manual torque-controlled systems with lower capital requirements. Cook Medical has anchored position through deep relationships with these networks. FDA guidance on reusable device reprocessing creates compliance burdens for automated platform adoption.
- Specialty Clinics:Gastroenterology-focused practices concentrate screening and surveillance procedures.
- Research Institutions:Academic medical centers pilot robotic-assisted and autonomous positioning systems.
- Diagnostic Centers:Screening-focused facilities generate high-volume, price-sensitive demand for routine applications.
Hospitals retain the highest absolute spend. Ambulatory Surgery Centers is gaining share fastest as procedure migration accelerates.
Deployment:
Capital intensity and regulatory qualification burden separate automated platform adoption from manual system penetration.
- Single-Use:Disposable clip cartridges eliminate reprocessing validation and cross-contamination risk. United States ambulatory surgery centers and Japanese outpatient networks absorb per-procedure cost premiums to avoid sterilization infrastructure investment. EU F-Gas Regulation implications for sterilization equipment reinforce single-use preference in European facilities facing equipment replacement cycles.
- Manual Deployment:Torque-controlled hand systems dominate cost-sensitive clinic segments with lower capital barriers. Hybrid torque-feedback platforms combining manual control with precision guidance are opening mid-tier segments previously excluded from advanced systems. German and United States manufacturers defend position through price repositioning against robotic-assisted alternatives.
- Reusable:Capital equipment with disposable components targets high-volume hospital settings.
- Automated Deployment:Precision positioning systems concentrate in academic medical centers with research funding.
- Torque-Controlled:Direct mechanical feedback remains preferred in cost-constrained environments.
Manual Deployment leads by installed base. Single-Use is expanding most quickly as regulatory reprocessing requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export nitinol-based clip systems to Japanese academic medical centers, establishing the primary trade corridor in this specialized device category.
United States
Ambulatory surgery centers in the southeastern states drive procedural volume through same-day discharge protocols. FDA guidance on reusable device reprocessing extends review cycles for automated deployment platforms. Integrated delivery networks in Texas and Florida consolidate procurement authority across multi-facility systems.
Germany
Notified bodies process EU MDR conformity assessments with extended review timelines for novel clip architectures. ISO 13485 quality management systems govern supplier qualification across manufacturing tiers. The Baden-Württemberg medical technology cluster anchors nitinol surface treatment R&D for silicone overmolding applications.
Japan
METI-supported same-day surgery expansion creates procedural whitespace outside Tokyo-Osaka hospital corridors. PMDA regulatory frameworks shape biocompatibility documentation requirements for implantable devices. Academic medical centers in Nagoya and Fukuoka pilot over-the-scope systems for complex anastomotic leak closure.
South Korea
Academic medical centers in Seoul deploy robotic-assisted positioning systems for complex fistula interventions. MFDS regulatory pathways align with ISO 10993 biocompatibility testing standards for nitinol-based architectures. The Bundang-Seongnam medical corridor concentrates demand for precision deployment platforms.
Global Endoscopic Clips Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification capabilities and ambulatory surgery center network access. The vendor base fragments across three tiers: diversified medical device conglomerates with full endoscopy portfolios, gastrointestinal-focused specialists with hemostasis application expertise, and regional fabricators serving cost-sensitive clinic segments. Dominant competitive moves include strategic partnerships with sterilization equipment vendors and portfolio diversification into single-use deployment systems.
Among diversified device manufacturers, Olympus Corporation and Fujifilm Holdings Corporation occupy positions spanning endoscope systems and accessory devices. Boston Scientific Corporation exemplifies the hemostasis-specialist archetype with concentrated expertise in tissue approximation applications. CONMED Corporation represents the mid-tier surgical device fabricator segment with broader gastrointestinal portfolio coverage.
| Leading Market Players |
|---|
| CONMED Corporation |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Ovesco Endoscopy |
| Olympus Corporation |
| Cook Medical |
| Teleflex Incorporated |
| Medtronic |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with nitinol melt suppliers lock in raw material access and price visibility for German and Japanese clip manufacturers facing EU MDR qualification delays. These long-term offtake structures insulate tier-one vendors from spot market volatility while compressing margins for second-tier fabricators excluded from preferred supplier networks.
Pricing Analysis
Next-generation over-the-scope systems command 40-60% premiums over through-the-scope variants due to superior mechanical force and complex fistula applications. Pricing stratifies across premium automated platforms, standard manual torque-controlled systems, and economy-grade single-use cartridges driven by sterilization infrastructure gaps. Cost compression in the manual deployment tier is intensifying because Japanese outpatient networks and United States ambulatory surgery centers prioritize same-day discharge economics. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers in South Korea and Japan absorb premium positioning for robotic-assisted platforms.
Supply Chain Analysis
Nitinol shape-memory alloy production concentrates in the United States, Germany, and Japan, creating single-source vulnerability for clip architectures requiring specialized surface treatments. Manufacturing draws from nitinol wire feedstock, silicone overmolding compounds, and precision laser-cutting equipment. Tariff exposure on Chinese-sourced surgical-grade stainless steel is forcing supply chain reconfiguration toward domestic European and North American metal suppliers. Distribution runs through hospital purchasing cooperatives in the southeastern United States and GPO-mediated channels in German hospital networks, with direct-to-ambulatory-center relationships gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endoscopic clips market functions as a service-attach opportunity where sterilization equipment requalification and reprocessing validation services expand faster than hardware unit growth. Recurring revenue from single-use cartridge supply contracts and automated platform maintenance agreements now outpaces capital equipment sales in ambulatory settings.
For Market Incumbents: Shield market position by deepening backward integration into nitinol surface treatment capabilities and securing ISO 10993-5 cytotoxicity testing capacity at qualified laboratories. The threat of robotic-assisted positioning systems from South Korean academic centers demands defensive patent filings in torque-feedback hybrid architectures. Channel control through exclusive ambulatory surgery center service contracts remains the critical lever against price erosion. For New Entrants and Emerging Players: Differentiate on automated-manual convergence platforms targeting mid-tier German and United States clinics previously cost-excluded from precision deployment systems. The most penetrable whitespace sits in Japanese prefectures outside Tokyo-Osaka corridors where METI-supported same-day surgery expansion outpaces local supply infrastructure. A reimbursement-first go-to-market angle emphasizing reduced readmission costs for complex fistula closure accelerates hospital adoption. For Investors and Strategic Acquirers: Nitinol traceability specialists with documented melt-to-sterilization chain-of-custody capabilities represent the highest-conviction acquisition archetype for EU MDR compliance exposure. Long-term viability hinges on regulatory qualification moats widening through extended German notified body review cycles. Watch FDA guidance evolution on reusable device reprocessing as the inflection signal for single-use platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 technical documentation requirements compress timelines for nitinol-based architectures. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida consolidate procurement authority across multi-facility systems. |
| Software Companion Development | Torque-feedback hybrid platforms reduce operator variability in complex fistula closure procedures. |
| Reimbursement Strategy | Same-day discharge protocols in German and Japanese outpatient networks prioritize procedural speed economics. |
| Backward Integration | In-house nitinol surface treatment capabilities insulate against raw material volatility and qualification delays. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, GPO contracts managers, and biomedical engineers and secondary validation against FDA 510(k) filings, EU MDR notified body submission databases, and hospital procurement records anchors the qualitative findings. The analysis combines bottom-up procedure volume estimates from ambulatory surgery center networks with top-down market sizing derived from nitinol raw material consumption patterns across German and Japanese manufacturing clusters.
Sensitivity analysis across deployment methodology, clip architecture, and end-user facility type informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, clinical application, end-user category, and regional regulatory cluster. CAGRs derive from procedure migration trends toward outpatient settings and premium technology adoption curves in academic medical centers. Nitinol supplier qualification timelines and sterilization equipment replacement cycles under EU F-Gas Regulation serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained ambulatory surgery center volume expansion and stable nitinol supply access would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory harmonization progress. Practitioners should keep alternative scenarios live as FDA reusable device reprocessing guidance and German notified body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Gastroscopes Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Endoscopy Equipment Market