
 Ultra-High Molecular Weight Polyethylene Fibers Market | 2026-2036
Ultra-High Molecular Weight Polyethylene Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-High Molecular Weight Polyethylene Fibers Market Intelligence
Aramid is repositioning product economics in high-performance fiber systems as weight-sensitive applications migrate toward hybrid reinforcement architectures. DSM-Firmenich leverages gel-spinning expertise to sustain premium positioning in ballistic-grade filament supply. Honeywell International Inc. anchors North American defense contracts through captive polymerization and downstream fiber drawing. Teijin Limited competes across Asian industrial rope markets with differentiated high-tenacity yarn formulations.
Ultra-high molecular weight polyethylene fibers are linear polyethylene chains with molecular masses exceeding three million g/mol, produced primarily through gel spinning to achieve specific strengths surpassing steel at one-eighth the density, serving ballistic protection, marine mooring, and orthopedic implant applications. Filament and yarn categories dominate current value capture in protective clothing and ropes, where defense procurement cycles and offshore wind installation schedules concentrate volume. Medical devices and composites represent faster-growing application pockets as orthopedic suture standards tighten and automotive lightweighting programs expand thermoplastic composite adoption.
FDA biocompatibility requirements and EU REACH chemical registration constrain raw material sourcing and finished fiber export access for non-compliant producers. The EU Green Deal carbon-border adjustments and emerging EPA per- and polyfluoroalkyl substance restrictions will reshape polymer feedstock selection and energy intensity benchmarks across the supply base. Stakeholders must monitor evolving defense localization mandates and medical device reclassification proceedings to align capacity investments with certifiable demand corridors.
Market Dynamics
Defense procurement localization mandates and REACH chemical compliance are restructuring fiber supply chains, forcing producers to decertify non-compliant feedstocks and relocate polymerization assets closer to end-use armor fabrication sites.
Growth Catalysts
- NATO ballistic protection programs:Member states are expanding personal armor and vehicle hardening contracts, creating sustained filament offtake through multi-year procurement cycles.
- EU Green Deal carbon-border adjustments:These mechanisms favor low-carbon gel-spinning facilities, advantaging producers with renewable energy access in fiber-grade polyethylene production.
- Offshore wind mooring deployment:Floating turbine installations in the North Sea and US Atlantic coast are consuming high-tenacity rope constructions at accelerating volumes.
Market Restraints
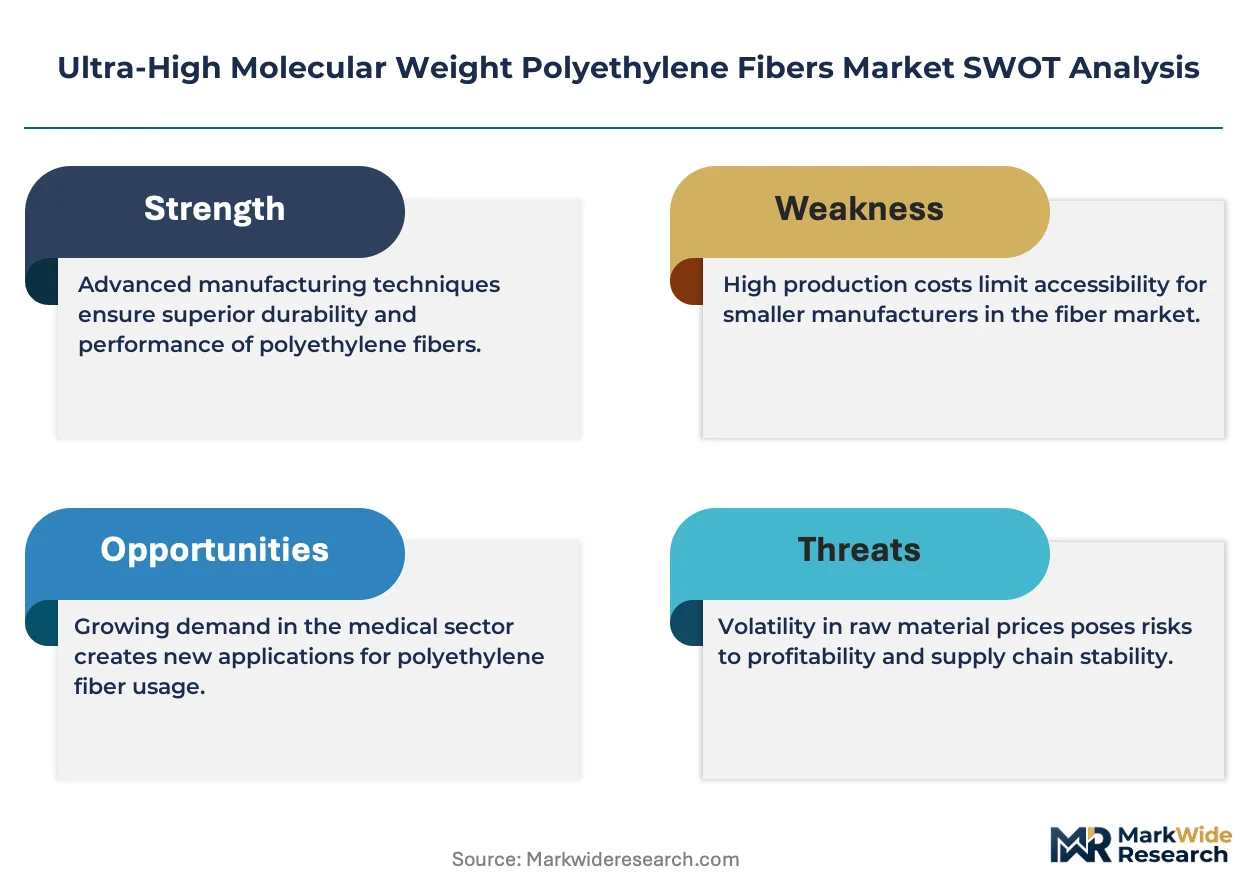
- Feedstock cost volatility:Ethylene and hexene prices fluctuate with crude oil benchmarks, compressing margins for non-integrated fiber producers without captive polymerization.
- Gel-spinning capacity concentration:Premium filament supply clusters in the Netherlands, Japan, and the United States, creating geographic single-source risk for defense contractors.
- Aramid hybrid substitution:Weight-critical aerospace applications are migrating toward para-aramid and carbon fiber blends in select ballistic panels.
Strategic Opportunities
- Orthopedic suture standardization:FDA biocompatibility pathways for UHMWPE surgical yarns remain underdeveloped, offering first-mover advantage to compliant filament producers.
- Automotive thermoplastic composites:Lightweighting mandates in Germany and California are opening specifications for chopped fiber reinforcement in bumper beams and underbody shields.
- India defense indigenization:The PLI scheme for critical materials is creating localized demand for domestic ballistic fiber production capacity.
Industry Challenges
- Gel-spinning technician scarcity:The specialized solvent-handling and extrusion expertise required for high-modulus fiber production is concentrated among retiring cohorts in Japan and Europe.
- REACH registration timelines:ECHA chemical substance dossiers for modified polyethylene grades extend certification cycles, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-High Molecular Weight Polyethylene Fibers Market |
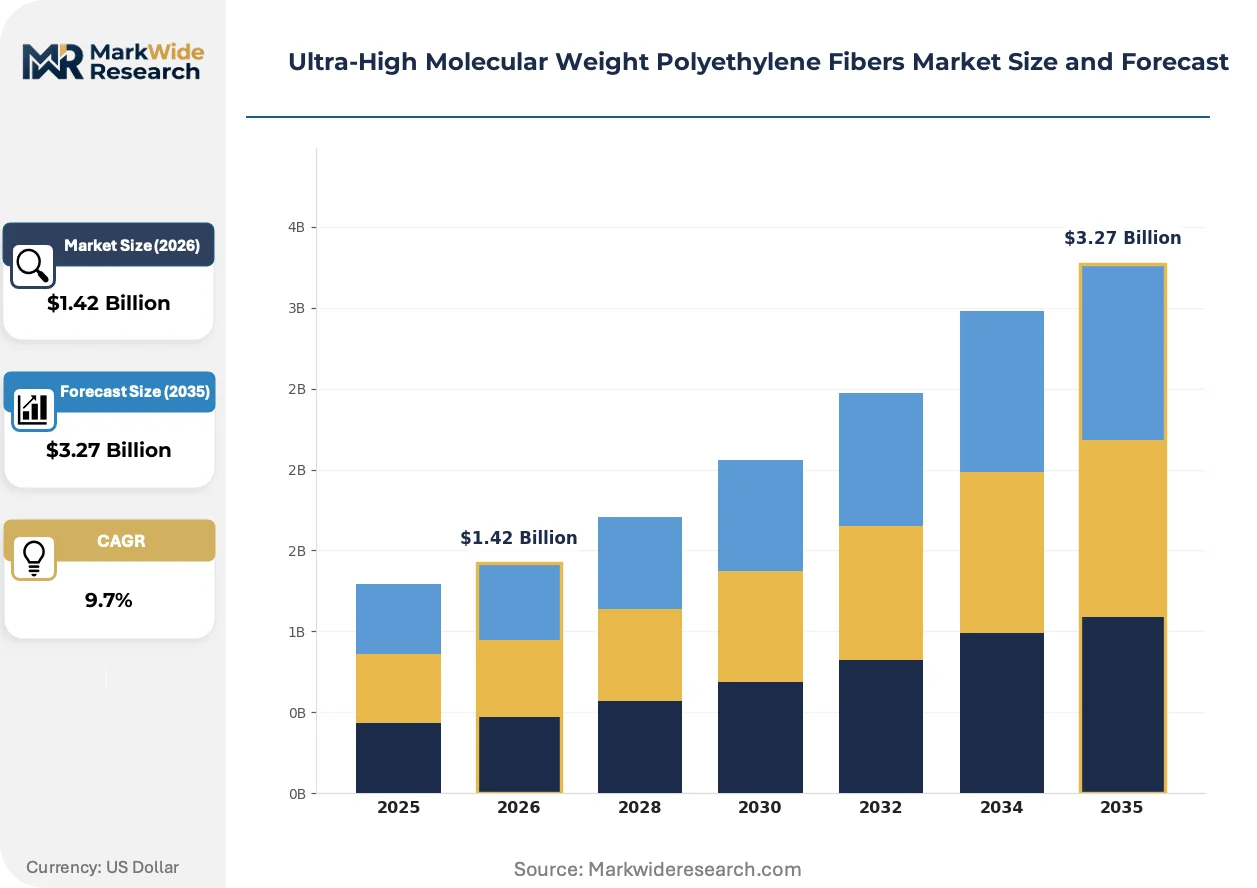
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filaments, Yarns, Sheets, Ropes End Use: Aerospace, Medical, Industrial, Defense Manufacturing Process: Gel Spinning, Melt Spinning, Solution Spinning, Fiber Drawing Application: Protective Clothing, Ropes & Slings, Medical Devices, Composites |
| Companies Covered | DSM-Firmenich, Toyobo Co., Ltd., Honeywell International Inc., Braskem S.A., Beijing Tongyizhong Specialty Technology & Development Co., Ltd., Avient Corporation, Teijin Limited, LyondellBasell Industries, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-High Molecular Weight Polyethylene Fibers Market Strategic Shifts & Innovations
Gel-spinning process intensification and regulatory chemistry disclosure are compressing competitive differentiation, while end-use buyers consolidate specifications around certified performance tiers rather than proprietary formulations.
Multi-stage solvent extraction with supercritical CO2 is consolidating as the dominant purification architecture for medical-grade filament. Orthopedic device manufacturers in Germany and Switzerland are specifying this processing route for suture and tape applications. The technology is consolidating supplier tiers by disqualifying producers lacking supercritical infrastructure from premium medical certifications.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of spin finishes and surface treatments used in ballistic yarn coatings. Fiber processors must resubmit chemical safety dossiers to ECHA, adding compliance overhead. Marine rope producers serving North Sea offshore wind are most affected, substituting silicone-based alternatives that alter friction coefficients in mooring terminations.
Defense procurement offices are consolidating specifications around NATO-standardized performance envelopes rather than national proprietary grades. Armor system integrators in the United States, United Kingdom, and Poland are accepting cross-certified filament lots, reducing qualification overhead. This consolidation is compressing pricing premiums previously captured by incumbent suppliers with sole-source national contracts.
Ultra-High Molecular Weight Polyethylene Fibers Market Segmentation
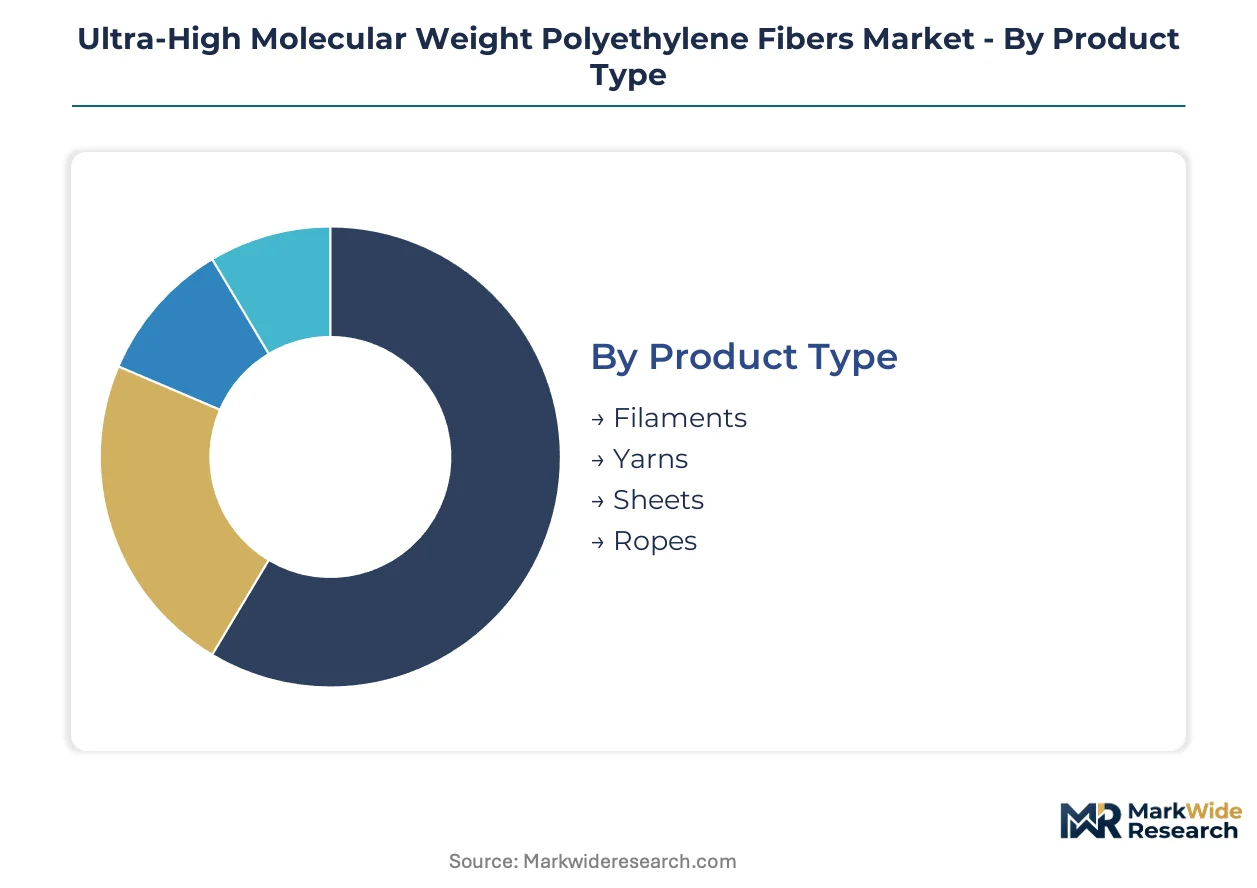
UHMWPE fiber markets stratify sharply between commodity rope volumes and premium medical filament pricing. Segment boundaries increasingly blur as defense contractors demand certified performance tiers rather than proprietary grades.
Product Type:
Volume concentrates in industrial rope constructions, while premium capture clusters in medical-grade filaments requiring supercritical CO2 purification.
- Filaments:Individual fiber strands with molecular alignment exceeding 95% crystallinity serve ballistic panels and surgical sutures. DSM-Firmenich and Honeywell dominate filament supply to NATO armor programs and FDA-cleared orthopedic device manufacturers.
- Yarns:Twisted multifilament constructions deliver tenacity above 35 cN/dtex for marine mooring and cut-resistant gloves. North Sea offshore wind installations consume accelerating yarn volumes for floating turbine tethering systems.
- Sheets:Unidirectional prepregs and cross-ply laminates armor vehicle hulls and helicopter seats. EU REACH chemical registration constrains sheet producers serving European defense integrators.
- Ropes:Braided and parallel-strand constructions moor floating offshore platforms and rig deep-sea lifting slings. Industrial rope specifications standardize around breaking strength tiers rather than proprietary formulations.
Today's leader: Filaments. Tomorrow's challenger: Ropes.
End Use:
Defense procurement anchors volume offtake, while medical applications command pricing multiples through biocompatibility certification barriers.
- Aerospace:Cabin panel reinforcement and cargo netting utilize chopped fiber in thermoplastic matrices. Boeing and Airbus specifications increasingly accept cross-certified filament lots, compressing supplier premiums.
- Medical:Orthopedic sutures, hernia repair meshes, and artificial ligaments require ISO 10993 biocompatibility validation. Supercritical CO2 processing infrastructure disqualifies most Asian producers from premium medical certifications.
- Industrial:Cut-resistant gloves, fishing lines, and conveyor belting consume commodity-grade yarns. Industrial buyers consolidate specifications around tenacity-per-dollar metrics rather than brand loyalty.
- Defense:Personal body armor, vehicle hardening, and helmet shells drive filament demand through multi-year NATO procurement cycles. Poland and United Kingdom armor integrators now accept cross-certified lots, reducing sole-source premiums.
Defense commands volume leadership. Medical segments expand most quickly through aging demographics and surgical procedure standardization.
Manufacturing Process:
Gel spinning retains premium positioning for high-modulus applications, while melt spinning penetrates cost-sensitive industrial segments.
- Gel Spinning:Solvent-based extraction of ultra-high molecular weight polyethylene achieves specific strengths surpassing steel at one-eighth density. DSM-Firmenich's Netherlands facilities and Teijin's Japanese plants concentrate global premium filament capacity.
- Melt Spinning:Thermoplastic extrusion without solvent handling produces lower-tenacity fibers for industrial ropes and geotextiles. Melt-spun output serves price-sensitive Asian industrial markets lacking ballistic certification requirements.
- Solution Spinning:Dilute polymer solutions enable intermediate modulus fibers for specialty fishing lines and sailcloth. Solution routes occupy narrowing niches between gel-spun premium and melt-spun commodity tiers.
- Fiber Drawing:Post-extrusion orientation stretching tunes mechanical properties for specific end-use specifications. Drawing stages integrate with gel and melt lines to customize modulus-elongation tradeoffs.
Gel spinning dominates performance tiers. Melt spinning gains share in industrial applications where certification overhead is absent.
Application:
Protective clothing and ropes concentrate current revenue, while composites and medical devices represent emerging specification battlegrounds.
- Protective Clothing:Ballistic vests, helmets, and stab-resistant garments consume certified filament through defense procurement channels. NATO standardization of performance envelopes reduces qualification overhead for cross-certified suppliers.
- Ropes & Slings:Deep-sea mooring, crane lifting, and offshore wind tethering demand high-tenacity constructions with predictable creep behavior. North Sea floating turbine deployments accelerate rope consumption ahead of US Atlantic coast installations.
- Medical Devices:Sutures, tapes, and orthopedic implants require supercritical CO2 purification and FDA biocompatibility pathways. German and Swiss device manufacturers specify this processing route, consolidating supplier tiers.
- Composites:Chopped fiber reinforcement penetrates automotive bumper beams and underbody shields under Germany and California lightweighting mandates. Thermoplastic composite adoption in passenger vehicles remains specification-limited.
Ropes and protective clothing anchor present revenue. Medical devices and composites gain share fastest through regulatory certification barriers and automotive lightweighting programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands concentrates premium gel-spinning capacity through DSM-Firmenich's Heerlen facilities, anchoring European ballistic fiber supply chains. Defense procurement localization mandates and REACH chemical compliance are restructuring fiber supply chains across NATO member states.
United States
Domestic armor programs and offshore mooring projects anchor fiber offtake through Honeywell's captive polymerization assets in Virginia. EPA per- and polyfluoroalkyl substance restrictions reshape polymer feedstock selection for defense contractors. The Virginia Beach-Norfolk corridor houses concentrated filament drawing capacity serving Pentagon procurement cycles.
Germany
Automotive lightweighting mandates in Baden-Württemberg and Bavaria open specifications for chopped fiber reinforcement in bumper beams. EU Green Deal carbon-border adjustments favor low-carbon gel-spinning facilities with renewable energy access. The Stuttgart industrial cluster drives thermoplastic composite adoption for underbody shields.
Japan
Teijin's Matsuyama facilities compete across Asian industrial rope markets with differentiated high-tenacity yarn formulations. METI standards govern medical device fiber certifications for orthopedic applications. The Shikoku region retains concentrated gel-spinning technician expertise amid retiring cohorts.
United Kingdom
Armor system integrators in the Midlands now accept cross-certified filament lots, reducing sole-source premiums previously captured by incumbents. NATO-standardized performance envelopes consolidate procurement specifications. The Sheffield-Rotherham corridor hosts vehicle hardening fabrication sites demanding localized polymerization assets.
India
The PLI scheme for critical materials creates localized demand for domestic ballistic fiber production capacity. DGFT import substitution policies accelerate defense indigenization timelines. The Pune-Ahmednagar belt emerges as a prospective cluster for rope manufacturing serving offshore energy projects.
Ultra-High Molecular Weight Polyethylene Fibers Market Key Industry Players
Capacity expansion dominates the current landscape as producers decertify non-compliant feedstocks and relocate polymerization assets closer to end-use armor fabrication sites. The vendor base stratifies sharply between integrated petrochemical conglomerates with captive ethylene supply and specialized fiber spinners dependent on merchant polymer. Three archetypes occupy distinct competitive positions: diversified chemical majors leveraging backward integration, pure-play fiber specialists commanding premium medical certifications, and regional rope fabricators serving price-sensitive industrial markets. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with producers seeking renewable energy access for carbon-border compliance and defense contractors demanding localized supply.
Among diversified chemical majors, DSM-Firmenich and Honeywell International Inc. exemplify the integrated archetype with captive control over polymerization and downstream fiber drawing. Teijin Limited occupies a position within the Asian specialist tier, representing pure-play fiber expertise concentrated in high-tenacity yarn formulations for marine and industrial applications. These three anchors demonstrate how competitive positioning derives from feedstock integration depth and certification breadth rather than scale alone.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Toyobo Co., Ltd. |
| Honeywell International Inc. |
| Braskem S.A. |
| Beijing Tongyizhong Specialty Technology & Development Co., Ltd. |
| Avient Corporation |
| Teijin Limited |
| LyondellBasell Industries |
| Celanese Corporation |
| Others |
Cost & Logistics Intelligence
Captive polymerization assets in Virginia and the Netherlands anchor pricing power for integrated producers serving NATO defense contracts. This backward integration shields margin structures from ethylene and hexene volatility while locking in long-term offtake agreements with armor system integrators. Non-integrated fiber spinners face compressed margins without control over feedstock costs.
Pricing Analysis
Ethylene and hexene cost pass-through mechanisms dominate contract negotiations for non-integrated producers lacking captive polymerization. Pricing stratifies across medical-grade filaments, defense-certified yarns, and industrial rope tiers based on certification depth and supercritical CO2 processing infrastructure. Cost compression in industrial segments intensifies as Asian melt-spun capacity expands without REACH compliance overhead. Defense procurement offices demonstrate lowest price sensitivity due to multi-year NATO standardization mandates, while industrial rope buyers prioritize tenacity-per-dollar metrics.
Supply Chain Analysis
Single-source vulnerability sits with premium gel-spinning capacity concentrated in the Netherlands, Japan, and the United States. Raw material dependencies draw from ethylene feedstocks, solvent systems for gel extraction, and spin finish chemistries facing EU REACH Annex XVII restrictions. Tariff exposure on polymer-grade polyethylene imports threatens non-integrated European producers. Distribution runs through defense contractor qualification channels for ballistic filaments and marine rope fabricator networks for industrial yarns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH chemical registration and FDA biocompatibility pathways create certifiable demand corridors that justify capacity investments. The EU Green Deal carbon-border adjustment mechanism accelerates localization mandates across NATO member states.
For Market Incumbents: Anticipate aramid hybrid substitution in weight-critical aerospace panels by deepening medical certification moats through supercritical CO2 infrastructure investments. Consolidate polymerization assets closer to Sheffield-Rotherham vehicle hardening fabrication sites to satisfy UK defense localization mandates. Lock in long-term ethylene supply agreements before EPA per- and polyfluoroalkyl substance restrictions reshape feedstock specifications.
For New Entrants and Emerging Players: Begin with automotive thermoplastic composite specifications in Baden-Württemberg, where chopped fiber reinforcement for bumper beams lacks entrenched incumbent relationships. Target India's PLI scheme for critical materials as the most penetrable defense indigenization window. Pursue joint development agreements with German orthopedic device manufacturers seeking second-source suture filament supply.
For Investors and Strategic Acquirers: Roll-up economics work for regional rope fabricators with marine mooring expertise because North Sea offshore wind deployment schedules concentrate predictable volume offtake. Platform consolidation across European industrial yarn producers offers five-to-ten year viability as carbon-border adjustments favor low-carbon gel-spinning facilities. Monitor ECHA chemical substance dossier approval timelines as the inflection signal for modified polyethylene grade commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Captive ethylene supply secures margin stability against crude-linked feedstock volatility for Virginia-based defense contractors. |
| Supercritical CO2 Purification Infrastructure | Medical-grade filament certifications from German device manufacturers require this processing route, disqualifying conventional competitors. |
| Defense Localization Partnership | Co-location with Sheffield-Rotherham armor fabrication satisfies UK procurement mandates and reduces logistics exposure. |
| REACH-Compliant Spin Finish Reformulation | Silicone-based alternatives for marine rope coatings ensure continued North Sea offshore wind mooring contract eligibility. |
| Automotive Composite Specification Development | Baden-Württemberg lightweighting mandates for underbody shields create first-mover positioning in thermoplastic reinforcement. |
Research Approach
Bottom-up defense procurement and medical device modeling reconciled against top-down gel-spinning capacity tracking forms the analytical core of this study. Primary interviews with armor system integrators, orthopedic device procurement managers, marine rope fabricators, and gel-spinning technical directors combined with secondary validation from ECHA chemical registration databases, NATO standardization documents, FDA 510(k) filings, and EU Green Deal implementation reports. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map ethylene feedstock availability through polymerization assets to finished filament and yarn output across product type, end use, manufacturing process, and application dimensions. CAGRs derive from defense procurement cycle analysis, offshore wind installation schedules, and orthopedic procedure volume projections throughout the forecast period. Medical device reclassification proceedings and EPA per- and polyfluoroalkyl substance regulatory timelines inform scenario-weighted outputs.
Several conditions sit outside the modeled scope, including sudden NATO defense budget reallocations, breakthrough aramid-carbon fiber hybrid technologies displacing UHMWPE in ballistic panels, and unanticipated ECHA substance bans affecting spin finish chemistries. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Basalt Fiber Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Carbon Fiber Wrap Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Global Nylon Monofilament Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Fiberglass Sunscreen Market
Fibers
Fiberglass Cloth Market
Fibers
Global Bicomponent Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Vinylon Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
High Temperature Superconducting Fibers Market