
 Global Electronic Grade Glass Fibers Market | 2026-2036
Global Electronic Grade Glass Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Grade Glass Fibers Market Foresight
Semiconductor packaging houses are rotating procurement priority from commodity laminates toward ultra-low-CTE glass fiber prepregs as advanced packaging architectures multiply die interconnect density. Owens Corning leverages its North American boron-free E-glass platform to supply substrate makers qualifying for next-generation interposers. Nippon Electric Glass Co., Ltd. anchors Japan's domestic supply chain through proprietary alkali-free formulations with sub-3.5 ppm alkali content. China Jushi Co., Ltd. competes on furnace scale, operating the world's largest individual glass melting tanks dedicated to electronic yarn production.
Electronic grade glass fibers are continuous filaments drawn from molten borosilicate or alkali-free glass compositions, engineered to achieve dielectric constants below 6.0 and dissipation factors under 0.001 for high-frequency signal integrity in printed circuit boards and semiconductor substrates. E-glass variants dominate laminate volume due to cost-positioning and established supply chain compatibility with epoxy resin systems. S-glass commands premium positioning in aerospace and defense systems where tensile modulus above 86 GPa justifies the higher raw material cost of magnesium-alumina-silicate formulations. Woven fabric forms capture the largest share of PCB-facing demand, though chopped strands are accelerating in semiconductor molding compound applications as transfer molding processes adapt to thinner package profiles.
The EPA enforces Maximum Achievable Control Technology standards for glass fiber furnace emissions in the United States, while REACH compliance in Europe mandates full substance registration for boron and fluorine compounds used in specialty glass batches. China's MEE has tightened particulate matter limits for industrial glass melting, pushing producers toward oxygen-fuel combustion retrofits or electric furnace conversions. Stakeholders must monitor evolving halogen-free flame retardant mandates across multiple jurisdictions, as brominated epoxy compatibility with glass fiber sizing chemistry becomes a qualifying constraint for telecommunications infrastructure contracts.
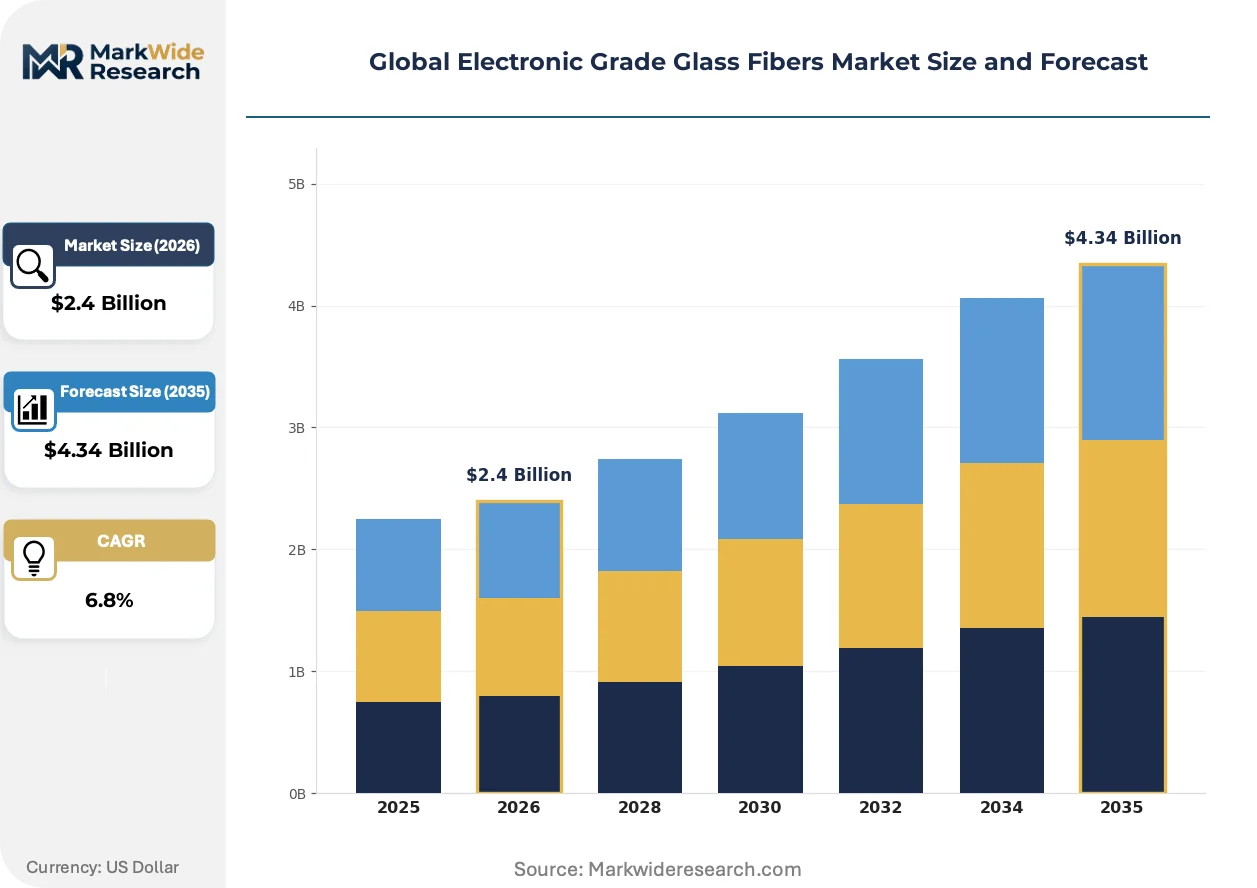
Market Dynamics
Semiconductor node migration below five nanometers is compressing dielectric tolerance windows, forcing substrate manufacturers to qualify entirely new glass fiber compositions while furnace emissions regulations simultaneously mandate capital-intensive combustion retrofits across major production bases.
Growth Catalysts
- Advanced Packaging Architectures:Chiplet-based designs multiply interconnect density, pulling ultra-low-CTE glass fiber prepregs into high-volume qualification cycles at leading semiconductor packaging houses.
- REACH Compliance Mandates:Full substance registration requirements for boron compounds in Europe are accelerating substitution toward alkali-free formulations with superior dielectric stability.
- East China Cluster Density:Zhejiang and Jiangsu provinces concentrate the world's densest PCB laminate manufacturing footprint, creating localized demand pull for integrated glass fiber drawing operations.
Market Restraints
- High-Purity Silica Cost Volatility:Ultra-low iron sand and synthetic silica feedstock prices fluctuate with energy-intensive refining capacity constraints in key mining jurisdictions.
- Furnace Technology Concentration:Oxygen-fuel combustion system suppliers cluster in Germany and Japan, creating single-source vulnerability for producers facing MEE particulate mandates.
- Dielectric Constant Floor:Borosilicate E-glass formulations face a theoretical limit near 5.8-6.0, constraining signal integrity at millimeter-wave frequencies above seventy-seven gigahertz.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and PCB fabrication are attracting glass fiber substrate qualification programs at new greenfield facilities.
- Halogen-Free Flame Retardant Convergence:Brominated epoxy phase-out mandates in telecommunications infrastructure create first-mover advantage for sizing chemistry compatible with phosphorus-nitrogen systems.
- Electric Furnace Conversion:Grid-decarbonization policies in the EU and China's dual carbon goals subsidize capital transitions away from fossil-fuel melting, locking in long-term cost positions.
Industry Challenges
- Specialized Melting Engineer Scarcity:Oxygen-fuel combustion optimization and electric furnace thermal profiling require expertise concentrated among retiring cohorts at legacy borosilicate operations.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA MACT, REACH SVHC, and GB standard compliance creates eighteen-to-twenty-four-month qualification cycles for new glass compositions.
- Legacy Sizing Chemistry Integration:Established silane coupling agent protocols conflict with emerging halogen-free resin systems, forcing reformulation of entire surface treatment sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Grade Glass Fibers Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Glass, S-Glass, C-Glass, AR-Glass, R-Glass, Other Specialty Glasses Application: Printed Circuit Boards, Semiconductor Packaging, Display Panels, Solar Cells, Sensors, Insulation Materials End User Industry: Consumer Electronics, Telecommunications, Aerospace Equipment, Defense Systems, Renewable Energy, Industrial Automation Form: Chopped Strands, Rovings, Woven Fabrics, Mats, Braided Tows, Multiaxial Fabrics |
| Companies Covered | Owens Corning, China Jushi Co., Ltd., Taishan Fiberglass, Chongqing Polycomp International Corp., Nippon Electric Glass Co., Ltd., Nittobo, Taiwan Glass Industry Corporation, Shandong Fiberglass Group Corp., Linzhou Guangyuan New Material Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Grade Glass Fibers Market Shifts & Advancements
Glass fiber substrate technology is fragmenting along performance-versus-cost axes as heterogeneous integration demands collide with sustainability mandates and regional supply chain reconfiguration pressures.
Low-dielectric-constant glass formulations is bifurcating the laminate market into high-frequency signal integrity tiers. Substrate manufacturers for five-nanometer-and-below nodes are qualifying magnesium-alumina-silicate derivatives with dielectric constants below 4.5, while commodity PCB producers retain boron-free E-glass for cost-sensitive layers. This split is compressing mid-range product positioning and forcing furnace operators to dedicate tank capacity to single composition families.
China's MEE has tightened industrial glass melting particulate limits, pushing producers toward oxygen-fuel retrofits or full electric conversions. Owens Corning and China Jushi are reallocating capital toward electric furnace pilots in Zhejiang to preempt enforcement waves. Japanese producers face parallel pressure from METI carbon-neutrality roadmaps, accelerating domestic alkali-free capacity expansion.
Direct mill relationships are displacing distributor intermediaries in electronic yarn procurement. Large laminate manufacturers in Jiangsu and Taiwan are negotiating multi-year offtake agreements with glass fiber draw towers, securing furnace-dedicated output while compressing working capital cycles. This consolidation is most visible in semiconductor substrate supply chains where lot traceability requirements exceed distributor capabilities.
Global Electronic Grade Glass Fibers Market Segmentation
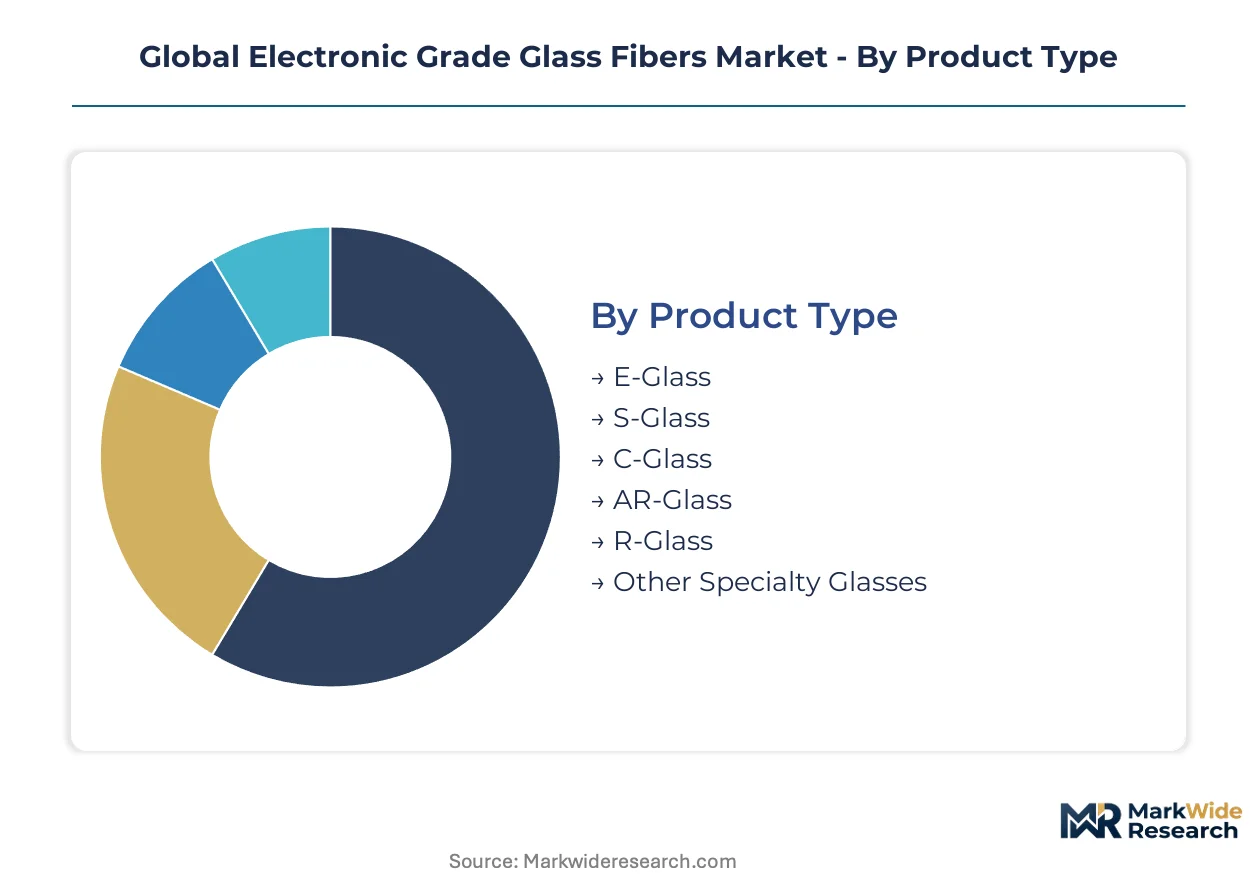
Glass fiber composition, form factor, and end-use specifications fragment procurement requirements across semiconductor packaging, PCB laminate, and telecommunications infrastructure verticals. Margin capture varies sharply by purity tier and furnace scale economics.
Product Type:
Premium pricing concentrates in alkali-free and high-modulus formulations where dielectric tolerances compress below five-nanometer node requirements.
- E-Glass:Borosilicate formulations with dielectric constants near 5.8-6.0 dominate laminate volume through cost-positioning and epoxy compatibility. PCB manufacturers in Jiangsu and Taiwan qualify this grade for standard multilayer boards where signal integrity demands stay below ten gigahertz.
- S-Glass:Magnesium-alumina-silicate chemistry delivers tensile modulus above 86 GPa for aerospace and defense systems where structural performance justifies raw material premiums. Suppliers position this grade through proprietary batch formulations with sub-3.5 ppm alkali content.
- C-Glass:Calcium-borosilicate compositions serve chemical resistance applications in industrial sensor housings and battery separator substrates.
- AR-Glass:Zirconia-doped formulations resist alkaline attack in cement-based composites and geopolymer insulation systems.
- R-Glass:High-silica low-alkali variants target aerospace radomes and missile nose cones requiring dielectric stability across thermal cycling.
- Other Specialty Glasses:Custom boron-free and fluorine-modified compositions address REACH SVHC compliance and halogen-free flame retardant mandates.
The dominant share belongs to E-Glass, while S-Glass is closing the gap fastest through defense procurement acceleration.
Application:
Customer qualification timelines stretch longest for semiconductor substrate integration where lot traceability and CTE matching requirements exceed PCB standards.
- Printed Circuit Boards:Woven fabric prepregs laminate into multilayer boards for servers, networking equipment, and automotive ECUs. East China cluster density in Zhejiang drives furnace-dedicated output agreements with integrated draw towers.
- Semiconductor Packaging:Ultra-low-CTE glass fiber substrates enable chiplet-based architectures with interconnect densities multiplying at advanced packaging houses. Transfer molding processes for thin package profiles pull chopped strands into high-volume qualification cycles.
- Display Panels:Fine-diameter yarns reinforce polarizer substrates and backlight diffuser sheets for LCD and OLED manufacturing.
- Solar Cells:Alkali-free glass backsheets and encapsulant layers support photovoltaic module durability in desert installations.
- Sensors:Hermetic fiber-to-metal seals protect MEMS devices in automotive pressure and inertial measurement units.
- Insulation Materials:Chopped strand mats thermoform into battery pack barriers and electric motor slot liners.
Semiconductor Packaging commands the steepest expansion trajectory as node migration compresses dielectric tolerance windows.
End User Industry:
Procurement concentration tracks electronics manufacturing cluster density and defense procurement cycles across major economies.
- Consumer Electronics:Smartphone and laptop PCB laminates specify boron-free E-glass for cost-sensitive high-volume production. India's PLI scheme incentives are attracting substrate qualification programs at new greenfield facilities.
- Telecommunications:Base station and optical transceiver boards demand halogen-free compatibility as brominated epoxy phase-out mandates tighten across infrastructure contracts.
- Aerospace Equipment:S-glass and R-glass structural composites reduce weight in satellite buses and unmanned aerial vehicle airframes.
- Defense Systems:Domestic supply chain requirements in Japan and the United States restrict qualification to approved melt facilities with ITAR or equivalent certification.
- Renewable Energy:Wind turbine blade spar caps and nacelle electrical systems specify corrosion-resistant glass fiber reinforcements.
- Industrial Automation:Motor drives and power inverters require thermal cycling resistance in high-voltage insulation systems.
Consumer Electronics retains volume leadership, though Telecommunications is gaining share fastest through 5G infrastructure deployment.
Form:
Process compatibility with resin transfer, prepreg lamination, and injection molding dictates form factor selection and sizing chemistry formulation.
- Woven Fabrics:Plain and satin weaves dominate PCB-facing demand through established epoxy resin system compatibility and dimensional stability during lamination presses.
- Chopped Strands:Length-controlled segments accelerate in semiconductor molding compound applications as transfer molding adapts to thinner package profiles.
- Rovings:Direct-drawn continuous bundles serve filament winding and pultrusion processes for structural composite manufacturing.
- Mats:Chopped strand and continuous filament configurations thermoform into complex insulation shapes for electrical equipment.
- Braided Tows:Triaxial and biaxial architectures reinforce pressure vessels and drive shafts with torsional load distribution.
- Multiaxial Fabrics:Non-crimp stitched layers optimize fiber orientation for wind blade shells and marine hull structures.
Woven Fabrics hold the largest position, while Chopped Strands are expanding most quickly through semiconductor packaging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber melting capacity clusters where electronics manufacturing density intersects with regulatory pressure on furnace emissions. The United States, China, Japan, Germany, and Taiwan concentrate the most qualified substrate supply chains.
United States
Semiconductor packaging houses in Arizona and Texas are qualifying ultra-low-CTE substrates for advanced node production. EPA MACT standards enforce Maximum Achievable Control Technology for glass furnace emissions, pushing producers toward oxygen-fuel combustion retrofits. Owens Corning operates boron-free E-glass capacity in the Southeast to serve domestic interposer substrate makers.
China
PCB laminate factories in Zhejiang and Jiangsu provinces drive the world's densest demand cluster for electronic yarn. MEE particulate limits for industrial glass melting are accelerating electric furnace conversions and oxygen-fuel retrofits across East China. China Jushi runs the largest individual glass melting tanks dedicated to electronic grade production in Jiaxing.
Japan
Domestic supply chain requirements restrict qualification to approved melt facilities serving semiconductor substrate manufacturers. METI carbon-neutrality roadmaps are accelerating alkali-free capacity expansion to meet dielectric stability demands. Nippon Electric Glass anchors production in Shiga Prefecture with proprietary sub-3.5 ppm alkali formulations.
Germany
REACH SVHC compliance mandates full substance registration for boron compounds used in specialty glass batches. Oxygen-fuel combustion system suppliers cluster in Bavaria and Baden-Württemberg, creating equipment concentration for furnace retrofits. Producers in the Rhine-Ruhr region serve telecommunications infrastructure contracts requiring halogen-free flame retardant compatibility.
Taiwan
Advanced packaging foundries in Hsinchu Science Park are pulling ultra-low-CTE prepregs into high-volume qualification cycles. Direct mill relationships are displacing distributor intermediaries as laminate manufacturers negotiate multi-year offtake agreements. Taiwan Glass Industry Corporation maintains furnace-dedicated output agreements with substrate producers requiring lot traceability.
Global Electronic Grade Glass Fibers Market Competitive Landscape
Concentration sits with integrated glass fiber drawing operations that control furnace scale and composition purity tiers. North American and Japanese players anchor premium substrate supply chains through proprietary alkali-free formulations, while Chinese producers compete on tank capacity and cost positioning. Two strategic archetypes dominate: vertically integrated laminate manufacturers with captive glass fiber supply, and specialized draw tower operators serving merchant markets. Competitive moves center on electric furnace conversion capital deployment and multi-year offtake agreements with semiconductor packaging houses.
Within the integrated multinational tier, Owens Corning and Nippon Electric Glass Co., Ltd. represent premium substrate supply chain anchoring. Among scale-driven Chinese producers, China Jushi Co., Ltd. exemplifies furnace capacity concentration. These three occupy positions across the boron-free E-glass and alkali-free formulation spectrum, with geographic specialization reflecting regional regulatory and demand configurations.
| Leading Market Players |
|---|
| Owens Corning |
| China Jushi Co., Ltd. |
| Taishan Fiberglass |
| Chongqing Polycomp International Corp. |
| Nippon Electric Glass Co., Ltd. |
| Nittobo |
| Taiwan Glass Industry Corporation |
| Shandong Fiberglass Group Corp. |
| Linzhou Guangyuan New Material Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Oxygen-fuel combustion retrofits replacing legacy fossil-fuel melting simultaneously relocate furnace capacity toward East China clusters and compress margin structures across mid-tier producers. This substitution dynamic concentrates pricing power with integrated draw tower operators while forcing merchant suppliers into volume-discount negotiations with laminate manufacturers in Zhejiang and Jiangsu.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with alkali-free formulations commanding certification premiums against boron-free E-glass commodities. Price differentiation centers on dielectric grade certification and furnace-dedicated output agreements, with semiconductor substrate makers showing least sensitivity and commodity PCB producers driving hardest bargain. Cost compression in standard-tier E-glass is intensifying because China Jushi and Taishan Fiberglass are expanding tank capacity into oversupply conditions.
Supply Chain Analysis
Strait of Malacca transit underwrites silica sand feedstock flows from Australia and Southeast Asian mining jurisdictions to East China melting clusters. Supply concentrates in China, Japan, and Germany, with ultra-low-iron sand and synthetic silica feedstock drawing from energy-intensive refining operations in Western Australia and Vietnam. Single-source vulnerability sits with German and Japanese oxygen-fuel combustion system suppliers facing MEE enforcement timelines. Distribution runs through direct mill relationships displacing distributor intermediaries for semiconductor substrate qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor node migration below five nanometers constitutes a high-growth disruption as dielectric tolerance compression forces substrate requalification cycles across advanced packaging houses. EPA MACT and REACH SVHC compliance timelines are simultaneously accelerating capital deployment into electric furnace conversions.
For Market Incumbents: Secure furnace-dedicated output agreements with Taiwan and Jiangsu laminate manufacturers before electric conversion capital locks in capacity allocation. Defend margin position by accelerating alkali-free formulation R&D ahead of REACH boron compound registration deadlines. Threat substitution from magnesium-alumina-silicate derivatives demands proprietary batch chemistry investment. For New Entrants and Emerging Players: Lead with halogen-free sizing chemistry compatibility as telecommunications infrastructure contracts phase out brominated epoxy systems. Target India's PLI scheme greenfield facilities for substrate qualification programs where incumbent presence remains thin. Go-to-market angle centers on phosphorus-nitrogen flame retardant integration support. For Investors and Strategic Acquirers: The market sits at a capital-intensity escalation phase that favors integrated draw tower operators with captive furnace technology. Long-term viability over the next decade hinges on electric conversion completion and alkali-free capacity positioning. Acquisition archetype: mid-scale Chinese producers with MEE-compliant pilot furnaces in Zhejiang. Watch oxygen-fuel equipment order backlogs as inflection indicator for retrofit completion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Conversion | MEE particulate enforcement in East China is accelerating capital redeployment away from fossil-fuel melting. |
| Alkali-Free Formulation Expansion | REACH SVHC registration mandates for boron compounds are pulling substrate makers toward dielectric-stable alternatives. |
| Direct Mill Relationship Consolidation | Lot traceability requirements in semiconductor packaging are compressing distributor roles in Taiwan and Jiangsu procurement. |
| Halogen-Free Sizing Chemistry Development | Telecommunications infrastructure contracts are mandating phosphorus-nitrogen flame retardant compatibility in epoxy systems. |
| India Greenfield Facility Qualification | PLI scheme incentives for semiconductor packaging are attracting substrate maker investment in new manufacturing clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with glass fiber plant managers, PCB laminate procurement leads at East China clusters, semiconductor packaging substrate engineers, and furnace technology suppliers in Germany and Japan. Secondary validation drew from MEE enforcement bulletins, REACH SVHC registration databases, EPA MACT compliance filings, and customs trade data for silica sand and synthetic silica feedstock. Bottom-up capacity modeling triangulated against top-down electronics manufacturing cluster demand aggregation.
Across the analysis window, volume and value outputs segmented by glass composition grade, form factor, end-use application, and regional production hub. CAGRs derived from furnace capacity expansion pipelines cross-referenced with PCB laminate and semiconductor substrate demand forecasts. Industry-specific inputs included oxygen-fuel retrofit completion timelines and electric furnace conversion subsidy qualification under EU and China's dual carbon frameworks.
Forecasts assume regulatory continuity in EPA MACT, REACH SVHC, and GB standard enforcement regimes; material policy shifts would require re-modeling particulate limit stringency or boron compound registration timelines. Specific risks include specialized melting engineer scarcity compressing retrofit execution rates and multi-jurisdiction certification delays extending new composition qualification cycles. Revision becomes warranted when oxygen-fuel equipment order backlogs exceed eighteen-month delivery windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Pitch-Based Carbon Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Carbon Fiber Tapes Market
Fibers
Carbon Fiber Wrap Market
Fibers
Global Electronic Fiberglass Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Global Bicomponent Fiber Market
Fibers
Europe Carbon Fiber Market
Fibers
Global Concrete Fiber Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Global Nylon Monofilament Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Artificial Muscle Fibers Market