
 Vinylon Market | 2026-2036
Vinylon Market Size, Share, and Industry Trends Forecast 2026-2036
Vinylon Market Analytics
Aftermarket technical-service revenue for Vinylon fiber processing is fragmenting across regional equipment specialists and resin compounders. Kuraray leverages its captive polyvinyl alcohol supply chain to sustain margin capture in high-tenacity fiber grades. Wanwei Group anchors Chinese domestic demand through backward integration into carbide-based acetylene chemistry. Unitika competes in Japanese industrial textiles by specializing in heat-resistant Vinylon variants for specialty paper reinforcement.
Vinylon is a synthetic fiber produced through the formalization of polyvinyl alcohol (PVA) fibers, yielding a material with tensile strength of 4-7 grams per denier and superior alkali resistance compared to standard polyesters. Its primary industrial purpose centers on cement bags, tarpaulins, and geotextiles where moisture-cure bonding and dimensional stability under wet load prove critical. Vinylon Fiber occupies the dominant volume position given its entrenched role in bulk packaging across Asian construction markets. Composite Fiber represents the fastest-expanding category as automakers adopt Vinylon-polypropylene hybrids for interior trim requiring low-flammability profiles.
China's SAMR enforces GB/T standards for synthetic fiber tensile consistency in public infrastructure contracts, directly shaping qualification thresholds for domestic suppliers. Japan's METI administers JIS L 1013 testing protocols that govern Vinylon fiber acceptance in geotextile applications, creating a technical barrier for non-compliant imports. REACH registration requirements in Europe constrain PVA precursor chemistry access for exporters lacking full substance dossiers. Stakeholders must monitor regulatory divergence between Asian performance standards and European chemical-compliance frameworks when allocating capacity investments.
Market Dynamics
China's tightening GB/T standards for synthetic fiber purity are compressing supplier margins while simultaneously elevating qualification barriers for public-works procurement across East Asian infrastructure markets.
Growth Catalysts
- Geotextile specification upgrades:Infrastructure durability mandates in China's 14th Five-Year Plan are accelerating specification-grade Vinylon adoption for soil stabilization and drainage systems.
- REACH compliance maturation:European ECHA registration pathways for PVA precursor chemistry are stabilizing, reducing entry friction for qualified Asian exporters serving continental geotextile tenders.
- Acetylene-carbide process optimization:Wanwei Group's backward integration into calcium carbide feedstock is lowering unit production costs for high-alkali-resistant fiber grades.
Market Restraints
- Feedstock concentration risk:Polyvinyl alcohol supply concentrates among three Japanese and Chinese chemical conglomerates, creating vulnerability to coordinated output restrictions.
- Formaldehyde chemistry scrutiny:ECHA's SVHC candidate list reviews of formaldehyde-releasing substances are elevating compliance costs for European-bound Vinylon shipments.
- Polypropylene substitution:PP-based woven geotextiles are capturing tender share in cost-sensitive Southeast Asian infrastructure bids where alkali resistance specifications remain unenforced.
Strategic Opportunities
- Automotive interior hybridization:Vinylon-polypropylene composite fibers are penetrating EU and Japanese automaker supply chains for low-flammability cabin trim applications.
- Indian coastal infrastructure:BIS certification alignment with JIS L 1013 protocols would unlock geotextile demand from Mumbai-Chennai industrial corridor port modernization.
- SAMR green procurement incentives:China's State Administration for Market Rewards is prioritizing recycled-content fibers in state-owned enterprise packaging tenders.
Industry Challenges
- Formalization process engineering talent:Wet-spinning and heat-treatment expertise for high-tenacity fiber production is concentrating among retiring Japanese technical specialists.
- Multi-standard certification timelines:Concurrent GB/T, JIS L 1013, and ISO 2076 compliance testing extends product qualification cycles by 8-14 months for cross-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinylon Market |
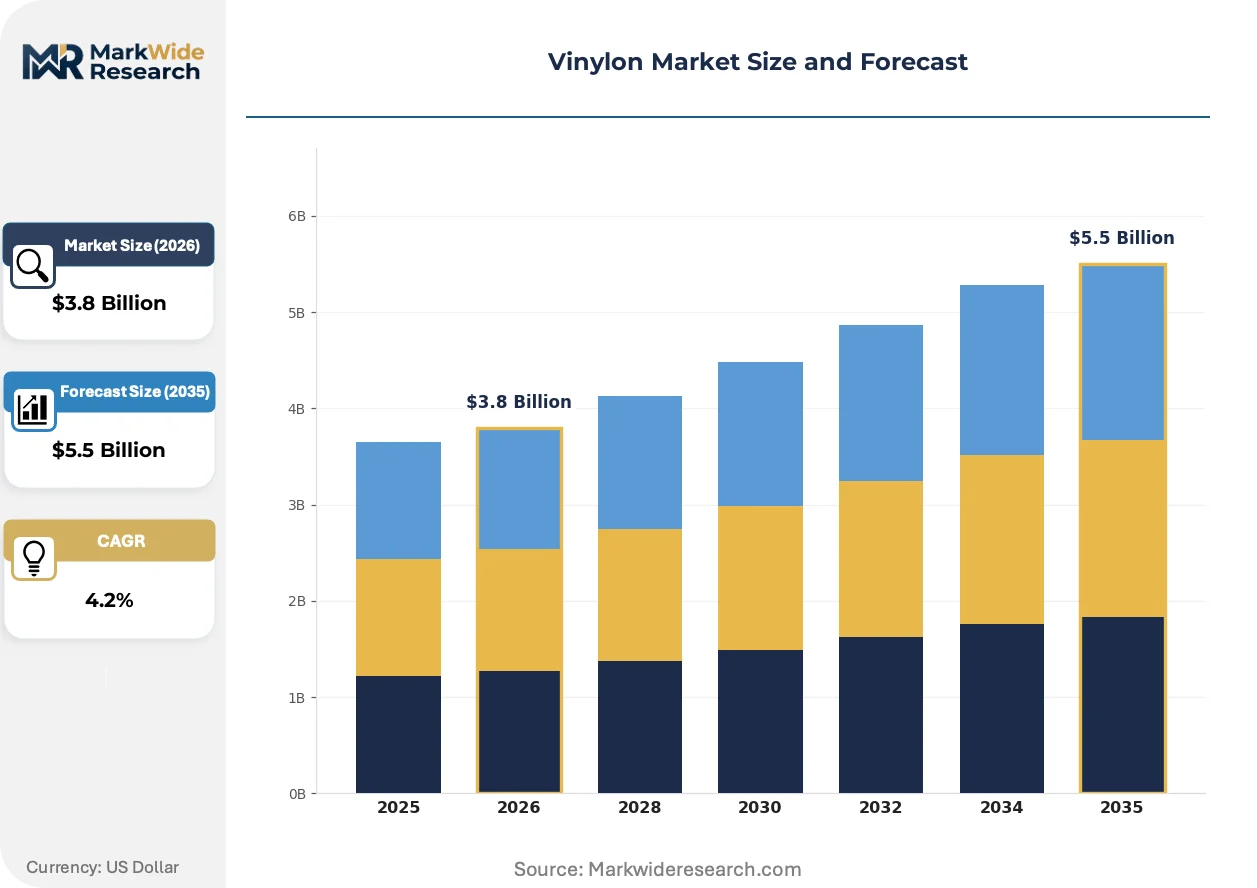
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinylon Fiber, Composite Fiber, Coated Fabric, Blended Material Application: Textiles, Automotive, Industrial, Construction End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Kuraray, Wanwei Group, Sinopec Group, Unitika, Xiangwei, Fujian Fuwei, Shuangxin PVA, MiniFIBERS, Ningxia Dadi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinylon Market Evolving Landscape
Material convergence between synthetic fiber categories and regulatory chemistry disclosure requirements are restructuring how Vinylon producers qualify for premium specification tiers across construction and automotive end-uses.
Hybrid Vinylon-polypropylene composite fiber is hybridizing conventional geotextile and automotive trim supply chains. Tier-1 seating suppliers in Germany and Japan are qualifying these materials for flame-retardant interior panels. This convergence is compressing pure-play polypropylene fiber margins in specification-grade segments while opening Vinylon volume to non-traditional automotive channels.
REACH Article 33 disclosure obligations for formaldehyde-containing articles are tightening downstream documentation requirements. European geotextile importers now demand batch-level substance dossiers from Asian fiber suppliers. Construction-grade Vinylon shipments to Rotterdam and Hamburg are experiencing extended customs clearance protocols as ECHA enforcement intensifies.
Specification-driven procurement is fragmenting tender participation across certification tiers. Japanese general contractors now require JIS L 1013 test reports for all geotextile submittals on METI-supervised infrastructure projects. Chinese state-owned developers are mirroring this selectivity through SAMR-registered supplier databases, compressing spot-market sales for uncertified producers.
Vinylon Market Segmentation
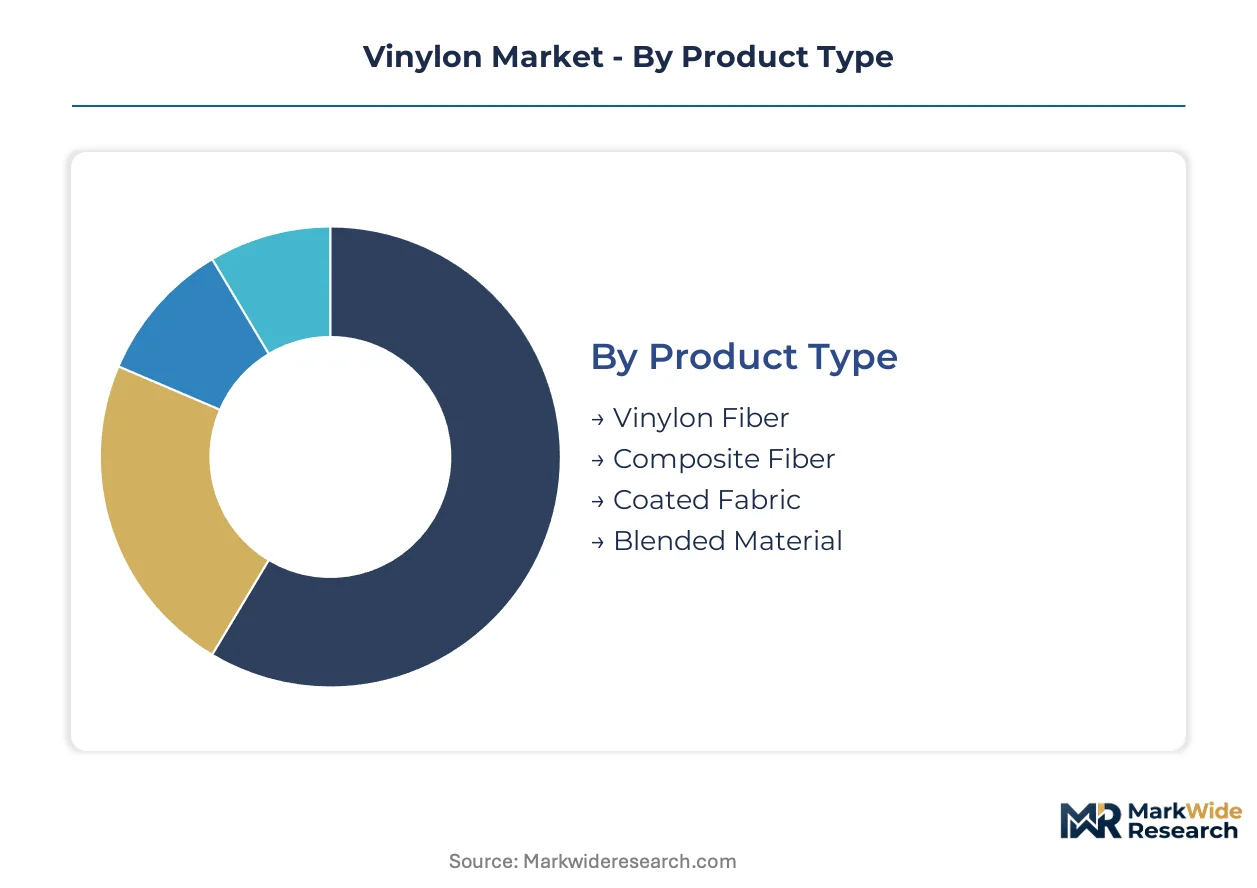
Vinylon market segmentation reveals divergent replacement cycles across product categories, with infrastructure-grade materials commanding multi-year procurement timelines while automotive specifications turn over with model-year refresh rates. Understanding these velocity differentials shapes inventory positioning and qualification investment priorities for suppliers.
Product Type:
Cycle times stretch from months for commodity fiber to years for certified construction materials, compressing working capital efficiency for specification-grade producers.
- Vinylon Fiber:Standard-grade PVA-formalized fiber delivers 4-7 grams per denier tensile strength with inherent alkali resistance. Cement bag and tarpaulin manufacturers across East Asian construction clusters anchor volume demand, though GB/T purity tightening is elevating batch rejection rates for uncertified suppliers.
- Composite Fiber:Vinylon-polypropylene hybrid structures combine low-flammability profiles with processability advantages. German and Japanese automakers are qualifying these materials for cabin trim applications, representing the segment where expansion concentrates most steeply.
- Coated Fabric:Laminated constructions for geomembrane and protective cover applications.
- Blended Material:Cotton-Vinylon and polyester-Vinylon mixes for textile applications requiring moisture management.
Vinylon Fiber dominates installed base across Asian packaging markets. Composite Fiber is where expansion concentrates as automotive qualification cycles accelerate.
Application:
Margin structures invert across application tiers, with specification-grade construction materials commanding premium pricing over commoditized textile feedstock.
- Construction:Geotextile and cement bag applications demand GB/T or JIS L 1013 certified fiber with documented alkali resistance. Chinese state-owned infrastructure tenders under the 14th Five-Year Plan are compressing spot-market participation to pre-qualified supplier databases.
- Automotive:Interior trim panels and seating substrates require REACH Article 33 disclosure compliance for formaldehyde content. EU and Japanese OEMs are adopting Vinylon-PP hybrids for flame-retardant specifications, with ECHA enforcement intensifying documentation burdens.
- Textiles:Industrial sewing thread and specialty paper reinforcement applications.
- Industrial:Filtration media and rope/cordage for chemical-exposed environments.
Construction commands the dominant revenue share. Automotive is climbing the fastest as material hybridization penetrates cabin interior specifications.
End User:
Procurement sophistication fragments across buyer categories, with state-linked manufacturers enforcing certification regimes that exclude spot-market suppliers.
- Manufacturers:Cement producers, textile mills, and automotive Tier-1s purchase fiber on annual contracts with technical service attachments. Chinese SOE packaging tenders now require SAMR-registered supplier status, disqualifying uncertified traders.
- Distributors:Regional stocking intermediaries serving smaller textile processors and repair markets.
- Retailers:Specialty fabric and industrial supply chains for end-consumer sales.
- Consumers:Direct purchases for craft, repair, and small-scale construction applications.
Manufacturers dominate procurement volume. Distributors represent the channel where consolidation is accelerating as certification burdens concentrate supplier relationships.
Distribution Channel:
Channel economics diverge sharply between specification-grade contract sales and spot-market wholesale, with compliance documentation costs favoring direct manufacturer relationships.
- Direct Sales:Long-term supply agreements linking fiber producers to cement manufacturers and automotive seating suppliers. Kuraray and Wanwei Group anchor this channel through captive technical service capabilities.
- Wholesale:Regional distributors aggregating demand from mid-scale textile processors.
- Offline:Industrial supply stores and trade-counter sales for immediate-need procurement.
- Online:E-procurement platforms for standard-grade fiber and small-lot orders.
Direct Sales captures the dominant contract value. Online is expanding most quickly for standardized grades as procurement digitization penetrates mid-tier manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Chinese state-owned cement producers absorb specification-grade premiums for GB/T-certified fiber, while Southeast Asian contractors default to polypropylene substitutes where alkali-resistance mandates remain unenforced.
China
Cement bag manufacturers in the Yangtze River Delta anchor regional volume demand. SAMR's tightening GB/T standards for synthetic fiber purity are compressing spot-market participation to pre-qualified supplier databases. Chongqing-based acetylene-carbide clusters are optimizing unit costs for high-alkali-resistant grades serving public-works procurement.
Japan
Geotextile specification for soil stabilization drives industrial fiber demand. METI-administered JIS L 1013 testing protocols create technical barriers for non-compliant imports. Osaka-Kobe industrial corridors concentrate specialty paper reinforcement applications requiring heat-resistant Vinylon variants.
Germany
Automotive seating suppliers qualify Vinylon-polypropylene hybrids for flame-retardant cabin trim. ECHA's REACH Article 33 disclosure obligations intensify batch-level documentation requirements for formaldehyde-containing articles. Hamburg-Rotterdam port corridors experience extended customs clearance protocols as enforcement tightens.
India
Mumbai-Chennai industrial corridor port modernization projects represent latent geotextile demand. BIS certification alignment with JIS L 1013 protocols would unlock specification-grade tender participation. Gujarat-based textile clusters currently absorb standard-grade fiber for tarpaulin and industrial sewing thread applications.
South Korea
Construction-grade geotextile adoption lags Chinese specification intensity. The country's national standards body maintains synthetic fiber testing protocols that reference ISO 2076 with regional modifications. Busan-Ulsan industrial zones concentrate mid-scale fiber processing for export-oriented packaging manufacturers.
Vinylon Market Competitive Landscape
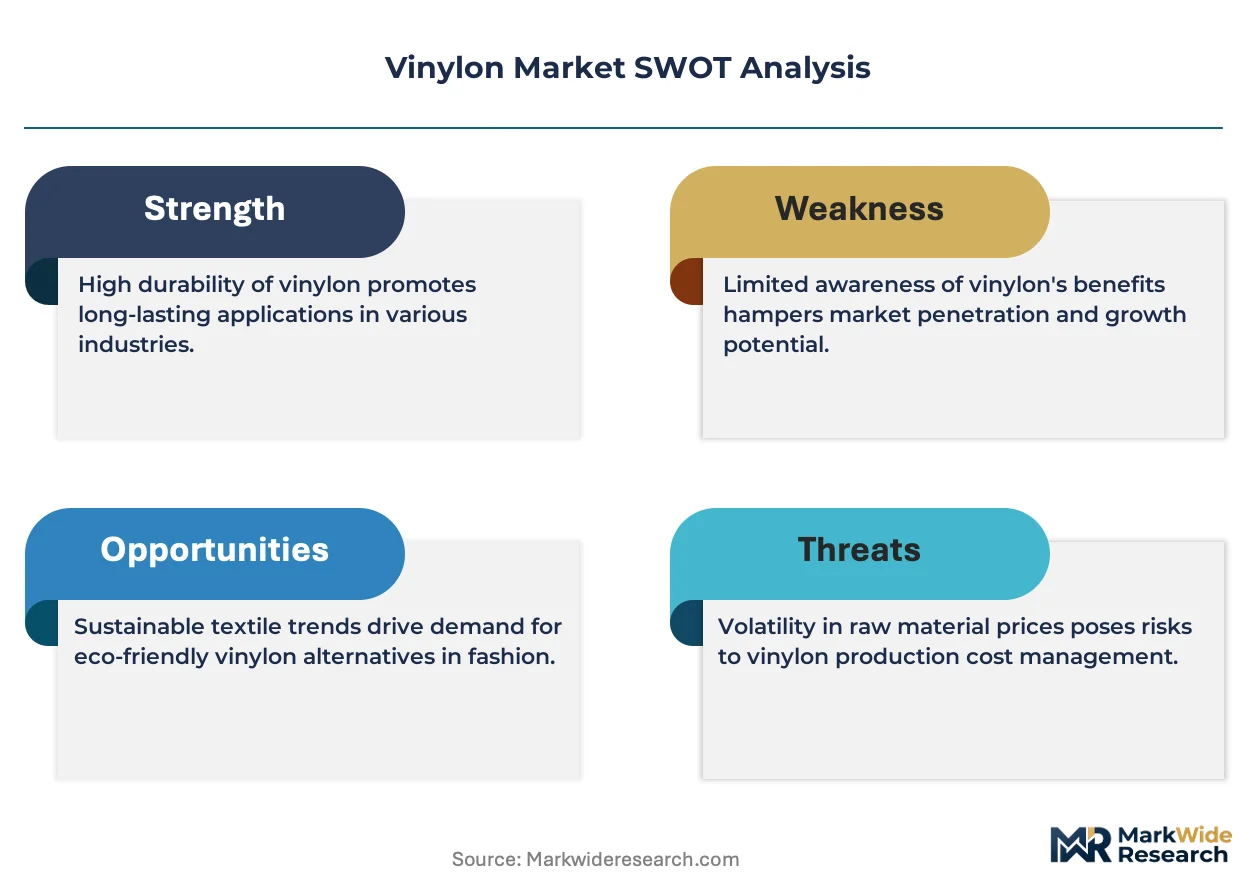
Captive feedstock specialists and specification-grade fabricators split the market into margin-protected and price-exposed tiers. Japanese and Chinese chemical conglomerates concentrate polyvinyl alcohol supply among three dominant sources, creating coordinated output vulnerability. Strategic archetypes include backward-integrated acetylene producers, PVA-captive fiber specialists, and regional equipment-integrated compounders. Capacity expansion and certification-tier positioning dominate competitive moves as qualification timelines extend.
Within the captive-supply tier, Kuraray and Wanwei Group exemplify divergent feedstock strategies. Kuraray represents Japanese PVA-captive specialization. Wanwei Group anchors Chinese acetylene-carbide backward integration. Unitika occupies a position within specification-grade diversification for heat-resistant variants.
| Leading Market Players |
|---|
| Kuraray |
| Wanwei Group |
| Sinopec Group |
| Unitika |
| Xiangwei |
| Fujian Fuwei |
| Shuangxin PVA |
| MiniFIBERS |
| Ningxia Dadi |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese and Chinese polyvinyl alcohol suppliers determines both pricing tier spreads and supply chain shape, compressing margins for non-captive fiber producers while elevating premiums for backward-integrated suppliers serving specification-grade procurement.
Pricing Analysis
Aftermarket technical-service revenue for fiber processing equipment drives lifetime value across installation and maintenance contracts. Contract-based long-term offtake dominates cement bag and geotextile procurement, with price differentiation anchored in GB/T certification tier and volume scale. Pricing pressure stems from polypropylene substitution in Southeast Asian infrastructure bids where alkali-resistance mandates remain unenforced. State-owned cement manufacturers in China exhibit lowest price sensitivity, absorbing specification-grade premiums for certified fiber, while spot-market traders face margin compression from batch rejection rates under tightening purity standards.
Supply Chain Analysis
Contract-manufacturing concentration rests with Kuraray, Wanwei Group, and Sinopec Group holding captive PVA capacity across Japan and China. Raw material dependencies center on acetylene-carbide chemistry, formaldehyde reagents, and heat-treatment equipment. Supply chain risk manifests as single-source vulnerability: three conglomerates control polyvinyl alcohol feedstock, creating coordinated output restriction exposure. Distribution runs through direct sales agreements linking fiber producers to cement manufacturers and automotive Tier-1 seating suppliers, with regional distributors aggregating mid-scale textile processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vinylon market sits in cyclical recovery as China's 14th Five-Year Plan infrastructure spending accelerates specification-grade geotextile procurement from state-owned developers.
For Market Incumbents: Pre-empt polypropylene substitution by locking multi-year offtake agreements with Yangtze River Delta cement producers before Southeast Asian cost-sensitive tenders shift entirely to synthetic alternatives. Secure backward integration into acetylene-carbide feedstock or captive PVA supply to defend margin position against feedstock concentration risk from Japanese and Chinese chemical conglomerates. For New Entrants and Emerging Players: Indian coastal infrastructure underpenetration offers white-space entry through BIS certification alignment with JIS L 1013 protocols for Mumbai-Chennai port modernization geotextile demand. Target automotive interior hybridization as the most penetrable segment, qualifying Vinylon-polypropylene composites for EU and Japanese OEM flame-retardant specifications through REACH Article 33 disclosure compliance. For Investors and Strategic Acquirers: ECHA's SVHC candidate list review of formaldehyde-releasing substances reshapes the acquisition landscape, elevating compliance infrastructure as a value driver for European-bound exposure. Long-term viability favors acetylene-carbide backward-integrated specialists with SAMR-registered supplier status. Watch ECHA enforcement intensity at Rotterdam and Hamburg customs as the signal for compliance-cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene-Carbide Feedstock | Wanwei Group's captive calcium carbide supply lowers unit costs for high-alkali-resistant grades. |
| GB/T Certification Investment | SAMR-registered supplier status unlocks Chinese state-owned enterprise packaging tender participation. |
| Automotive Hybrid Qualification | Vinylon-polypropylene composites penetrate German and Japanese OEM flame-retardant cabin trim specifications. |
| REACH Article 33 Compliance Infrastructure | Batch-level substance dossiers satisfy ECHA enforcement at Rotterdam and Hamburg port corridors. |
| JIS L 1013 Testing Protocol Alignment | METI-supervised infrastructure projects require certified geotextile submittals from Japanese general contractors. |
Research Methodology
A standing panel of fiber plant managers, cement procurement leads, automotive Tier-1 seating engineers, and ECHA regulatory affairs specialists provided ongoing calibration across primary interviews. Secondary validation drew from customs and trade data, SEC filings of listed chemical conglomerates, GB/T standard revision notices, and JIS L 1013 testing protocol documentation. Bottom-up fiber demand modeling triangulated against top-down construction and automotive production forecasts.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include product type, application tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating acetylene-carbide process cost curves and specification-grade certification penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by backward-integrated acetylene producers or coordinated PVA output restrictions by Japanese-Chinese conglomerates would shift outcomes. Quarterly review of SAMR certification database additions, ECHA SVHC list revisions, and Indian BIS-JIS alignment progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Dry-Molded Fibre Market
Fibers
Citrus Pulp Fiber Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
E-Glass Fiber Market
Fibers
Fiberglass Sunscreen Market
Fibers
Metal Fiber Felt Market
Fibers
Bleached Linter Cellulose Market
Fibers
Renewable Carbon Fibers Market
Fibers
Fiberglass Mat Market
Fibers
Global Bicomponent Fiber Market
Fibers
Carbon Fiber Tapes Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Carbon Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market