
 Global R-Glass Fiber Market | 2026-2036
Global R-Glass Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global R-Glass Fiber Market Foresight
The EU Green Deal is shifting procurement criteria across European aerospace supply chains toward low-carbon, high-durability reinforcement materials. Owens Corning leverages its North American manufacturing scale to supply certified R-glass rovings to tier-one aerostructures builders. Jushi Group Co., Ltd. anchors Asian supply through integrated fiber-to-fabric capabilities at its Zhejiang complex. Nippon Electric Glass Co., Ltd. differentiates via boron-free formulations that meet Japan's METI energy-efficiency guidelines for transport applications.
R-glass fiber denotes a high-modulus, alumina-lime-borosilicate glass reinforcement engineered for tensile strength above 4,400 MPa and elastic modulus near 86 GPa, produced through platinum-rhodium bushing drawing at melt temperatures exceeding 1,300°C to serve load-bearing composite structures. Chopped strands command the largest volume share across molding operations for complex aerostructures, while woven roving captures premium margin pools in prepreg fabrication for primary aircraft components. Filament products represent the fastest-expanding category as automated fiber placement systems gain adoption in next-generation wing and fuselage programs.
FAA certification standards for composite primary structures, EASA's continued airworthiness directives on bonded repairs, and China's GB standards for high-performance fiber reinforcement collectively shape product qualification pathways and market access timelines. The EU's CSRD disclosure requirements are extending material traceability obligations upstream to raw fiber producers. Stakeholders must monitor evolving qualification protocols for recycled-content R-glass as circularity mandates penetrate aerospace procurement specifications.
Market Dynamics
Automated fiber placement systems are compressing production timelines for primary aerostructures while EU Green Deal emissions benchmarks force material substitution toward high-modulus reinforcement grades. Platinum-rhodium bushing drawing capacity concentrates among integrated fiber-to-fabric producers with captive melt operations.
Growth Catalysts
- EU Green Deal industrial benchmarks:Aerospace tier-one suppliers face binding emissions disclosure thresholds under CSRD, redirecting procurement toward boron-free R-glass formulations with certified lifecycle data.
- Automated fiber placement adoption:Next-generation wing programs at Boeing and Airbus specify filament-wound R-glass for automated layup, displacing manual prepreg operations in Munich and Hamburg production lines.
- Japan's METI transport efficiency guidelines:Domestic rail and automotive OEMs source high-modulus reinforcement meeting energy-intensity targets, opening specification windows for alumina-lime-borosilicate grades above 4,400 MPa tensile strength.
Market Restraints
- Platinum-rhodium bushing supply concentration:South African PGM refining disruptions transmit directly to fiber drawing capacity, constraining output elasticity when aerospace order books expand.
- EASA continued airworthiness directives:Bonded repair qualification protocols for composite primary structures extend certification timelines, freezing material substitution decisions until full airframe testing completes.
- Carbon fiber modulus competition:PAN-based alternatives above 230 GPa elastic modulus capture wing spar applications where weight minimization dominates stiffness-to-density ratios.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic aerospace manufacturing incentives under the Production Linked Incentive framework attract R-glass roving investments for helicopter airframe programs.
- Recycled-content certification protocols:Circular economy mandates in France and Germany position reclaimed fiber qualification as a procurement differentiator for CSRD-compliant supply chains.
- Filament winding + resin transfer molding convergence:Pressure vessel manufacturers integrate continuous fiber placement with closed-mold infusion, reducing layup labor for hydrogen storage tanks.
Industry Challenges
- Platinum-rhodium metallurgy skill scarcity:Bushing maintenance and orifice plate engineering expertise concentrates among aging workforces in Belgium and Japan, constraining capacity expansion.
- FAA-EASA harmonization gaps:Divergent composite damage tolerance certification paths force dual qualification runs for global airframe programs, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global R-Glass Fiber Market |
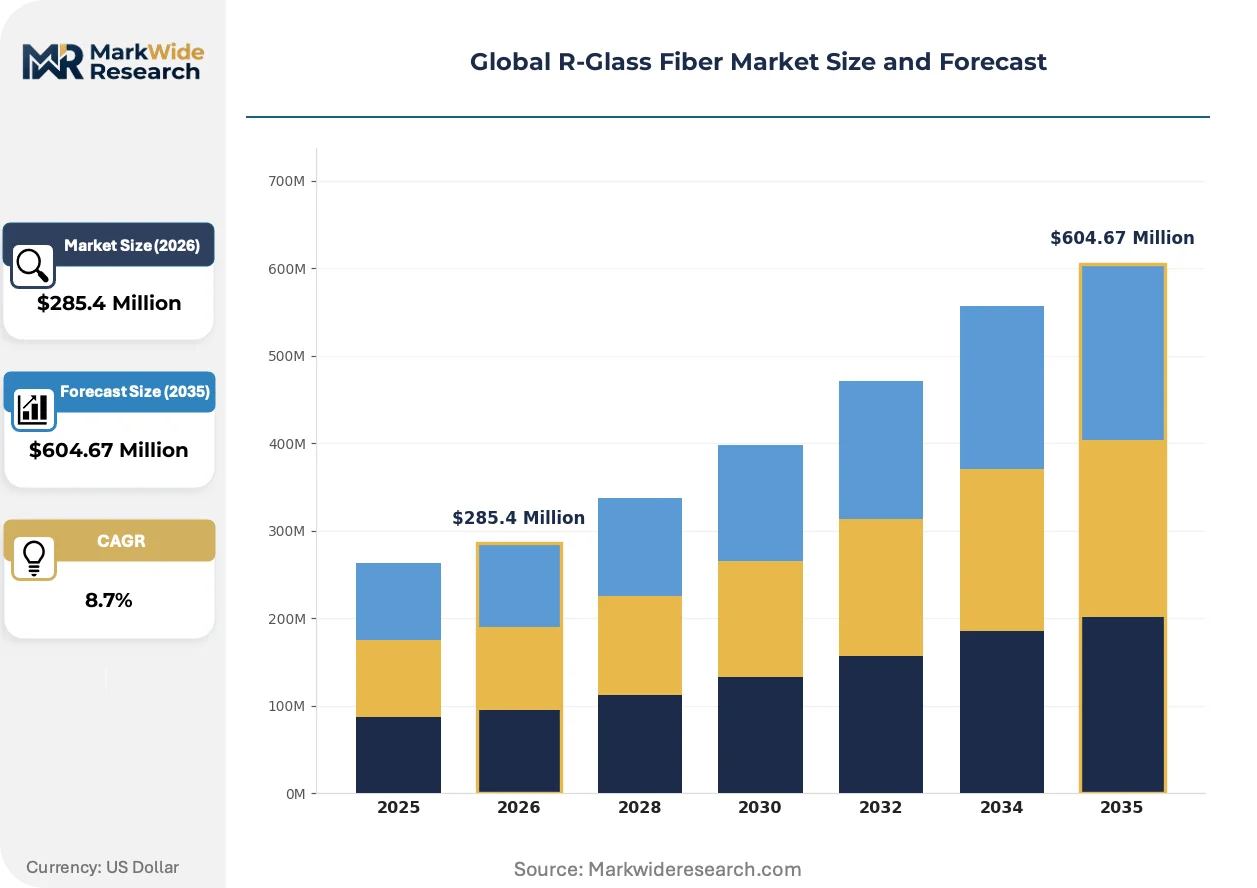
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Strands, Rovings, Woven Roving, Mat, Yarn, Filament Application: Composites, Aerospace Components, Marine Equipment, Sports Goods, Construction Materials, Electronics End User: Aerospace Manufacturers, Marine Fabricators, Sporting Goods Producers, Construction Contractors, Electronic Device Makers, Defense Firms Manufacturing Stage: Fiber Production, Prepreg Fabrication, Molding, Lamination, Assembly, Quality Testing |
| Companies Covered | Jushi Group Co., Ltd., Owens Corning, Nippon Electric Glass Co., Ltd., Taishan Fiberglass Inc., Chongqing Polycomp International Corporation, Johns Manville Corporation, Saint-Gobain Vetrotex, Shandong Fiberglass Group Co., Ltd., 3B - The Fiberglass Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global R-Glass Fiber Market Shifts & Advancements
Digital thread integration across fiber production and composite fabrication is collapsing quality assurance cycles. Material traceability requirements now extend from bushing output through cured laminate.
Automated fiber placement with in-situ consolidation is automating wing skin production at Boeing's Charleston facility and Airbus's Hamburg composite center. Tier-one aerostructures builders specify R-glass filament tows for these systems, compressing layup schedules from weeks to days while maintaining ±3% fiber volume fraction tolerance. The technology is automating manual prepreg operations that previously dominated primary structure fabrication.
REACH SVHC candidate list expansion is compelling reformulation of boron-containing glass chemistries. ECHA's 2024 boric acid restriction proposal forces fiber producers to validate alumina-rich alternative melts without modulus degradation. German aerospace suppliers accelerate qualification of boron-free R-glass grades to preempt supply chain interruption.
Buyers now mandate mill-level carbon intensity disclosure before contract award. CSRD scope 3 reporting obligations push procurement teams toward fiber producers with verified renewable electricity shares. This specification shift concentrates contract awards among integrated smelter-draw-fabric operations in Norway and France with hydroelectric power sourcing.
Global R-Glass Fiber Market Segmentation
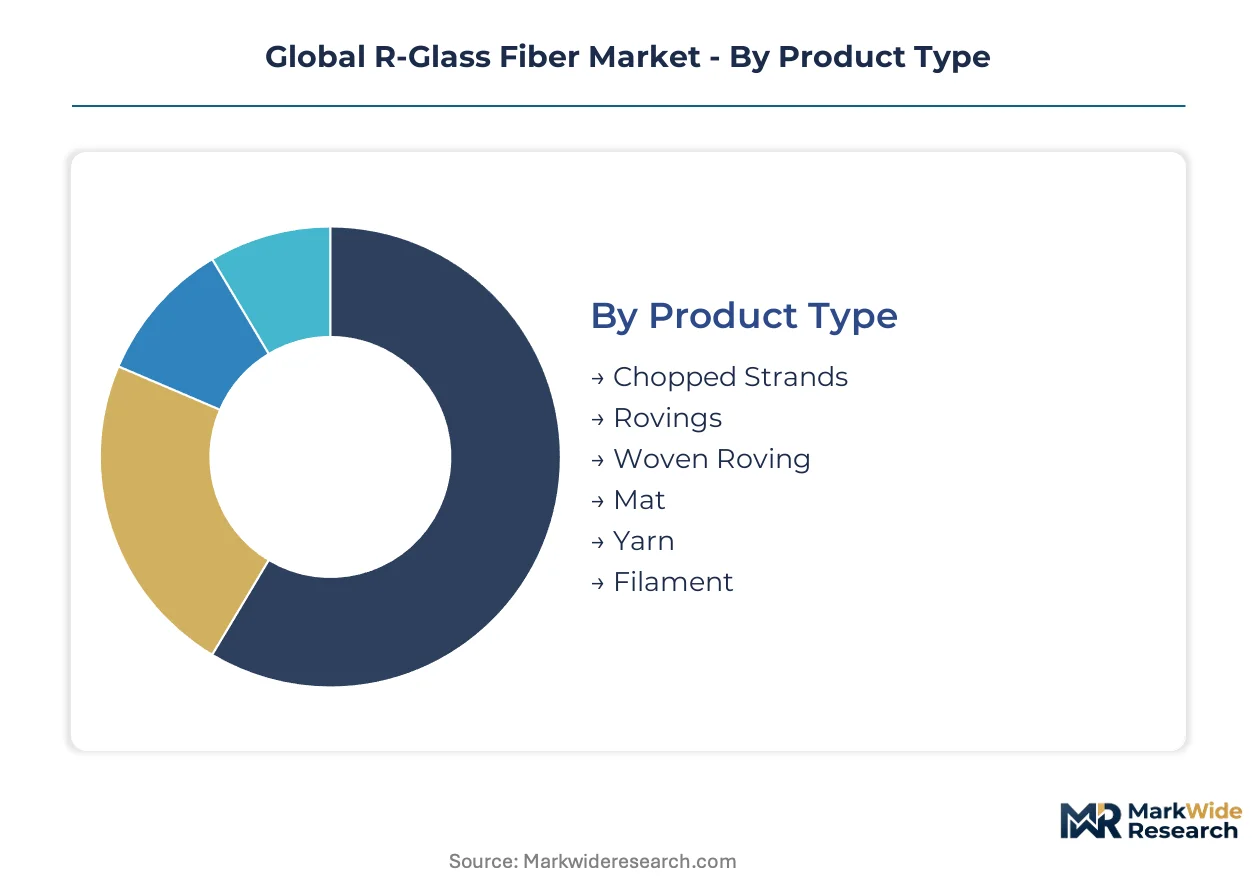
Segmentation in the R-glass fiber market reveals how platinum-rhodium bushing capacity and automated placement technologies concentrate value capture among specific product forms. Understanding these divisions exposes where procurement power shifts and where qualification barriers protect incumbent positions.
Product Type:
Platinum-rhodium bushing drawing capacity concentrates among integrated producers, favoring formats that maximize throughput per melt hour.
- Chopped Strands:Short-cut fibers engineered for bulk molding compound integration, typically 3-24mm in length. Demand concentrates in Germany's aerospace cluster around Munich, where tier-one suppliers specify these grades for complex aerostructure geometries under EU Green Deal emissions benchmarks.
- Filament:Continuous tows optimized for automated fiber placement systems with tensile strength above 4,400 MPa. Boeing's Charleston facility and Airbus's Hamburg composite center specify these products for next-generation wing programs, displacing manual prepreg operations.
- Rovings:Assembled strands for pultrusion and filament winding operations.
- Woven Roving:Bidirectional fabrics capturing premium margin pools in prepreg fabrication for primary aircraft components.
- Mat:Chopped strand mats for hand lay-up and closed-mold processes.
- Yarn:Twisted bundles for specialized textile reinforcements in high-tension applications.
Today's leader: Chopped Strands. Tomorrow's challenger: Filament.
Application:
Cost tier stratification separates qualification-intensive aerospace applications from volume-driven construction segments.
- Composites:Matrix-integrated reinforcements serving structural load-bearing functions. Japan's METI transport efficiency guidelines drive specification of alumina-lime-borosilicate grades above 4,400 MPa tensile strength for rail and automotive OEMs.
- Aerospace Components:Primary and secondary structures requiring FAA and EASA certification. EASA continued airworthiness directives on bonded repairs extend material qualification timelines, freezing substitution decisions until full airframe testing completes.
- Marine Equipment:Hull and superstructure applications in commercial and recreational vessels.
- Sports Goods:High-performance equipment leveraging stiffness-to-weight ratios.
- Construction Materials:Infrastructure reinforcement with lower qualification barriers.
- Electronics:Printed circuit board substrates and insulation components.
Aerospace Components command the steepest expansion trajectory as automated placement penetrates primary structures. Composites defend volume leadership across transport sectors.
End User:
Customer type determines contract structure, with defense and aerospace buyers demanding mill-level carbon intensity disclosure before award.
- Aerospace Manufacturers:Tier-one aerostructures builders with CSRD scope 3 reporting obligations. These buyers concentrate procurement among integrated smelter-draw-fabric operations in Norway and France with verified renewable electricity shares.
- Defense Firms:National security contractors with sovereign supply chain requirements. India's PLI scheme for advanced materials attracts R-glass roving investments for helicopter airframe programs under domestic aerospace manufacturing incentives.
- Marine Fabricators:Shipyard and boat builders with corrosion-resistant specifications.
- Sporting Goods Producers:Equipment brands prioritizing stiffness-to-weight optimization.
- Construction Contractors:Infrastructure developers with price-sensitive procurement.
- Electronic Device Makers:PCB and insulation material purchasers.
Aerospace Manufacturers anchor current procurement value. Defense Firms are gaining share fastest through sovereign capability mandates.
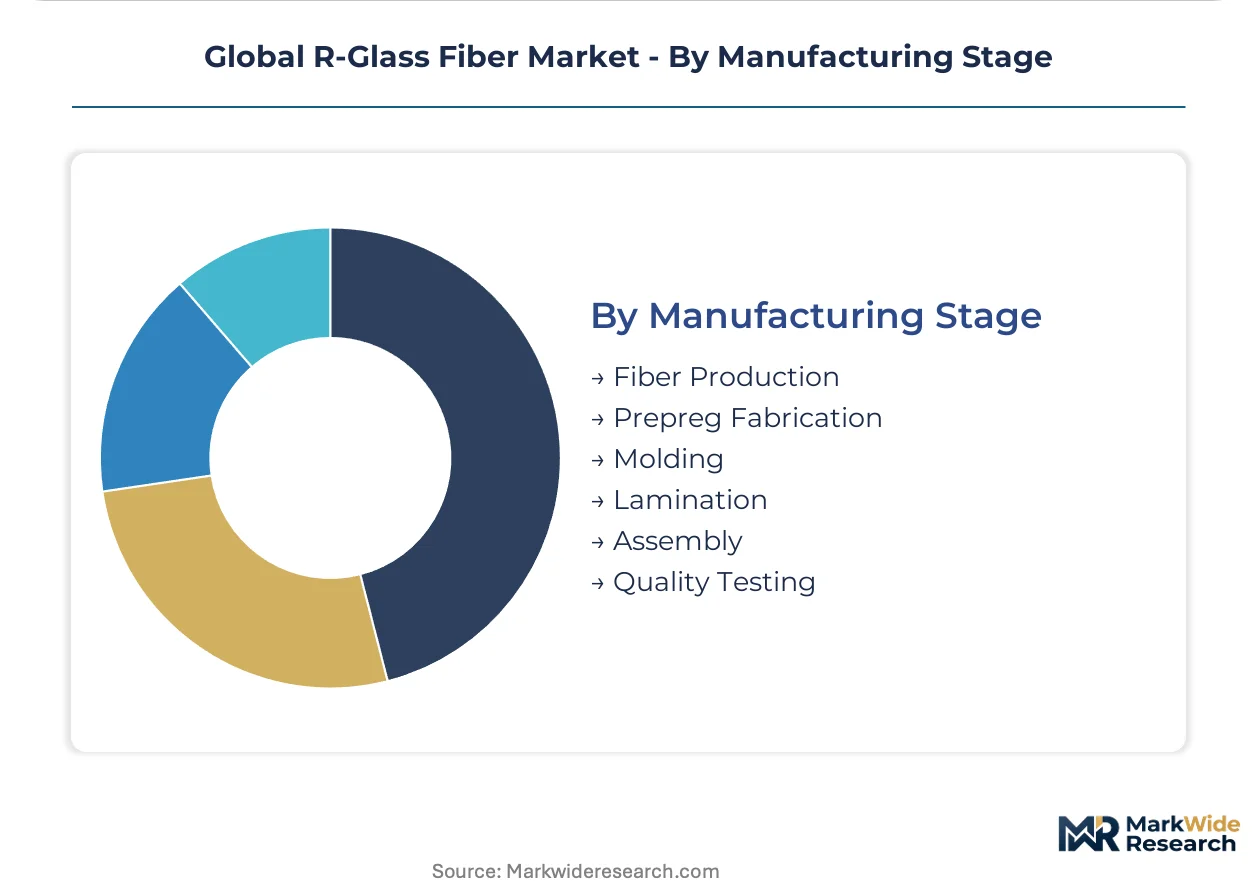
Manufacturing Stage:
Maturity gradients separate capital-intensive fiber production from labor-dependent downstream fabrication.
- Fiber Production:Platinum-rhodium bushing drawing at melt temperatures exceeding 1,300°C. South African PGM refining disruptions transmit directly to capacity constraints, limiting output elasticity when aerospace order books expand.
- Prepreg Fabrication:Resin-impregnated sheet goods for autoclave curing. REACH SVHC candidate list expansion compels reformulation of boron-containing chemistries, forcing validation of alumina-rich alternative melts without modulus degradation.
- Molding:Compression and injection processes for complex geometries.
- Lamination:Layered construction of reinforced polymer stacks.
- Assembly:Component integration into finished structures.
- Quality Testing:Non-destructive evaluation and certification documentation.
Fiber Production commands margin concentration through metallurgical scarcity. Prepreg Fabrication faces the steepest regulatory reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
R-glass fiber manufacturing originated in European glassmaking traditions, with Belgium and Germany developing the first high-modulus formulations for aerospace applications during the mid-20th century. This technical heritage continues to shape geographic concentration, though production capacity has dispersed across integrated smelter-draw operations in multiple continents.
United States
FAA certification protocols for composite primary structures drive specification of high-tensile filament tows above 4,400 MPa at Boeing's Charleston facility and Lockheed Martin's Fort Worth operations. The EPA's industrial emissions tracking under the Clean Air Act intersects with aerospace procurement teams demanding mill-level carbon intensity disclosure. Automated fiber placement adoption concentrates in South Carolina and Washington state production lines.
Germany
EASA continued airworthiness directives on bonded repairs extend material qualification timelines for Munich and Hamburg aerospace clusters. The EU Green Deal's CSRD disclosure requirements redirect procurement toward boron-free R-glass formulations with certified lifecycle data. Tier-one aerostructures builders at Airbus's Hamburg composite center specify filament-wound products for next-generation wing programs.
China
GB standards for high-performance fiber reinforcement shape domestic qualification pathways for rail and automotive OEMs seeking alumina-lime-borosilicate grades. The country's dual carbon goals under MEE regulations push composite makers toward renewable electricity sourcing at Zhejiang and Shandong production bases. Integrated fiber-to-fabric capabilities concentrate in the Yangtze River Delta manufacturing corridor.
Japan
METI transport efficiency guidelines open specification windows for high-modulus reinforcement meeting energy-intensity targets in domestic rail applications. JIS standards govern product qualification for pressure vessel manufacturers integrating continuous fiber placement with closed-mold infusion. Technical expertise in platinum-rhodium bushing maintenance concentrates among aging workforces in Osaka and Nagoya industrial zones.
India
The PLI scheme for advanced materials attracts R-glass roving investments for helicopter airframe programs under domestic aerospace manufacturing incentives. BIS certification requirements intersect with defense procurement specifications for sovereign supply chain security. Production gravity shifts toward Gujarat and Karnataka as tier-one suppliers establish qualification protocols for composite primary structures.
Global R-Glass Fiber Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and metallurgical capability dimensions. The vendor base stratifies into three tiers: integrated fiber-to-fabric operators with captive melt capacity, specialized prepreg fabricators serving aerospace qualification pathways, and regional converters supplying construction and industrial segments. Two dominant competitive moves define current positioning: backward integration into platinum-rhodium bushing maintenance expertise, and geographic expansion toward CSRD-compliant renewable electricity sourcing.
Among Asia-Pacific integrated producers, Jushi Group Co., Ltd. and Taishan Fiberglass Inc. occupy positions exemplifying scale-driven fiber-to-fabric capabilities. Owens Corning represents North American manufacturing breadth serving certified aerospace supply chains. These three entities anchor distinct competitive archetypes: Chinese integrated smelter-draw operations, and North American qualification-intensive supply positioning.
| Leading Market Players |
|---|
| Jushi Group Co., Ltd. |
| Owens Corning |
| Nippon Electric Glass Co., Ltd. |
| Taishan Fiberglass Inc. |
| Chongqing Polycomp International Corporation |
| Johns Manville Corporation |
| Saint-Gobain Vetrotex |
| Shandong Fiberglass Group Co., Ltd. |
| 3B - The Fiberglass Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between aerospace-qualified filament and construction-grade chopped strands splits both pricing power and supply chain configuration across the R-glass fiber market. Premium tiers command contract-based offtake structures tied to CSRD-compliant renewable electricity sourcing, while commodity grades trade on spot markets tethered to platinum-rhodium bushing capacity constraints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contract negotiations, with aerospace filament capturing value through FAA-EASA dual qualification requirements and construction-grade mat products competing on volume scale. Price differentiation hinges on certification tier and captive melt capacity, with integrated producers in Norway and France extracting margin premiums through verified hydroelectric sourcing. Cost compression in standard-grade rovings is intensifying because South African PGM refining disruptions constrain drawing capacity elasticity. Construction contractors exhibit highest price sensitivity, while tier-one aerostructures builders prioritize carbon intensity disclosure over unit cost.
Supply Chain Analysis
Qualification gating through FAA and EASA certification pathways concentrates aerospace-grade supply among integrated fiber-to-fabric operators in Belgium, Germany, and Japan with captive platinum-rhodium bushing maintenance expertise. Raw material dependencies draw from South African PGM refining, alumina-rich mineral feeds, and boron-free chemical formulations compelled by REACH SVHC restrictions. Single-source vulnerability runs through South African platinum-rhodium refining disruptions that transmit directly to fiber drawing capacity. Distribution feeds from integrated smelter-draw operations through qualified prepreg fabricators to tier-one aerostructures builders with CSRD scope 3 reporting obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's CSRD disclosure requirements compound procurement specifications with binding carbon intensity thresholds, transforming material traceability from competitive advantage into market access prerequisite.
For Market Incumbents: Extend captive bushing maintenance capabilities through apprenticeship programs in Belgium and Nagoya industrial zones to counteract aging workforce attrition. Deepen backward integration into alumina-rich mineral sourcing to preempt REACH-driven boron-free formulation disruptions. Carbon fiber modulus competition above 230 GPa threatens wing spar applications where weight minimization dominates stiffness-to-density ratios.
For New Entrants and Emerging Players: Enter via India's PLI scheme for advanced materials, where domestic aerospace manufacturing incentives attract R-glass roving investments for helicopter airframe programs with sovereign supply chain security specifications. Recycled-content certification protocols in France and Germany offer penetrable white-space as circular economy mandates position reclaimed fiber qualification as procurement differentiator. Go-to-market leverage rests on mill-level carbon intensity disclosure capabilities aligned with CSRD scope 3 reporting obligations.
For Investors and Strategic Acquirers: Consolidation pressure builds where platinum-rhodium metallurgy skill scarcity constrains capacity expansion among aging workforces. Long-term viability favors integrated smelter-draw-fabric operations with verified renewable electricity shares and established aerospace qualification pathways. Acquisition target archetype: mid-cap European producers with captive melt capacity and EASA certification history. Signal to watch: FAA-EASA harmonization progress on composite damage tolerance certification paths that would collapse dual qualification overhead.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Refining Partnerships | Secures platinum-rhodium bushing supply against South African disruption risk. |
| Boron-Free Formulation Validation | Preempts REACH SVHC restrictions compelling alumina-rich melt reformulation. |
| Automated Fiber Placement System Qualification | Captures Boeing and Airbus next-generation wing program specifications. |
| CSRD-Compliant Renewable Electricity Sourcing | Enables mill-level carbon intensity disclosure for tier-one aerostructures procurement. |
| Recycled-Content Certification Protocol Development | Positions reclaimed fiber for circular economy mandates in France and Germany. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with aerospace procurement directors, composite plant managers, platinum-rhodium metallurgy specialists, and EASA regulatory affairs leads with secondary validation. Secondary sources include FAA certification databases, EASA continued airworthiness directives, EU CSRD disclosure filings, customs trade data on PGM imports, and SEC filings from integrated fiber producers. Bottom-up and top-down triangulation cross-validates filament tow demand against automated fiber placement system deployment data.
Granularity-level framing models product type, application, end user, and manufacturing stage dimensions across the projection horizon, with specific attention to aerospace component qualification timelines and construction material price elasticity. CAGRs derive from segment-level volume build-ups reconciled against macroeconomic drivers. Industry-specific forecast inputs include platinum-rhodium price indices and EU Green Deal industrial emissions benchmark implementation schedules.
Inputs from EASA regulatory filings and PGM refining capacity reports were available through the study window; gaps in real-time aerospace order book visibility introduce uncertainty bands around filament demand projections. Forecasts reflect assumptions regarding FAA-EASA harmonization progress and REACH SVHC enforcement timing. A model refresh is warranted upon material change in South African PGM refining output or EU boric acid restriction finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Keratin Market
Fibers
Dry-Molded Fibre Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Precision Fiber Molding Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Vinylon Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Carbon Fiber Tapes Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market