
 Global Nylon Monofilament Market | 2026-2036
Global Nylon Monofilament Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nylon Monofilament Market Outlook
Maintenance contracts for extrusion die calibration and tension-control software is broadening what equipment suppliers sell alongside raw filament. Toray Industries leverages captive polymerization in Japan to sustain margin on high-tenacity industrial grades. BASF SE anchors European medical suture supply through certified PA66 resin streams. DuPont competes in North American sporting goods channels with differentiated fluoropolymer-coated offerings.
Nylon monofilament denotes a single-strand extrusion of polyamide polymer, typically 0.05 mm to 3.0 mm in diameter, produced through melt-spinning of nylon-6 or nylon-6,6 chips followed by controlled drawing and annealing to achieve target tensile strength and dimensional stability. The material serves as a load-bearing or binding element where uniform cross-section, abrasion resistance, and controlled elongation are critical. Medical sutures command premium positioning due to USP Class VI and ISO 10993 certification burdens that limit qualified suppliers. Industrial filaments in construction and agriculture represent volume anchors with thinner margin profiles. Treated and coated forms are gaining share as end users specify UV stabilization and lubricious surface finishes for demanding outdoor and surgical applications.
US FDA 21 CFR Part 177.1500 governs nylon resin contact with food and indirect medical applications, while EU MDR and REACH constrain monomer residuals and additive migration in implantable and consumer-touch products. China's GB standards and NMPA registration requirements for surgical sutures create parallel compliance tracks that shape export qualification investments. Stakeholders must monitor how bio-based caprolactam feedstock certifications and extended producer responsibility frameworks for fishing gear alter material specifications and supplier qualification timelines.
Market Dynamics
Medical suture manufacturers in Germany and Japan are consolidating procurement around REACH-certified and MDR-compliant resin streams, compressing supplier qualification timelines and favoring integrated polymerization-to-filament operations.
Growth Catalysts
- EU MDR biocompatibility mandates:Implantable polymer certification requirements are narrowing qualified supplier pools and locking in premium resin contracts for compliant manufacturers.
- Fishing line cluster expansion:Zhejiang province's integrated nylon-6 chip-to-yarn operations are capturing volume demand from Southeast Asian aquaculture fleet modernization.
- UV stabilization chemistry advances:Additive packages extending outdoor service life are opening specification wins in agricultural trellis and construction geogrid applications.
Market Restraints
- Caprolactam price volatility:Benzene derivative feedstock swings compress margin on commodity-grade industrial filament.
- PA66 resin supply concentration:European adipic acid production bottlenecks constrain high-tenacity industrial grade availability.
- Polyester monofilament substitution:Lower-cost PET alternatives are displacing nylon in non-load-bearing consumer applications.
Strategic Opportunities
- Brazilian surgical suture market:ANVISA registration pathways for USP Class VI materials remain underpenetrated by qualified Asian suppliers.
- Bio-based caprolactam certification:Mass balance accounting standards are creating premium positioning for renewable feedstock claims.
- Extended producer responsibility frameworks:EU fishing gear collection mandates are driving specification for recyclable monofilament grades.
Industry Challenges
- Extrusion die calibration expertise:Tolerance control for medical-grade diameters below 0.1 mm requires specialized technician training programs.
- ISO 10993 certification timelines:Cytotoxicity and sensitization testing protocols extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nylon Monofilament Market |
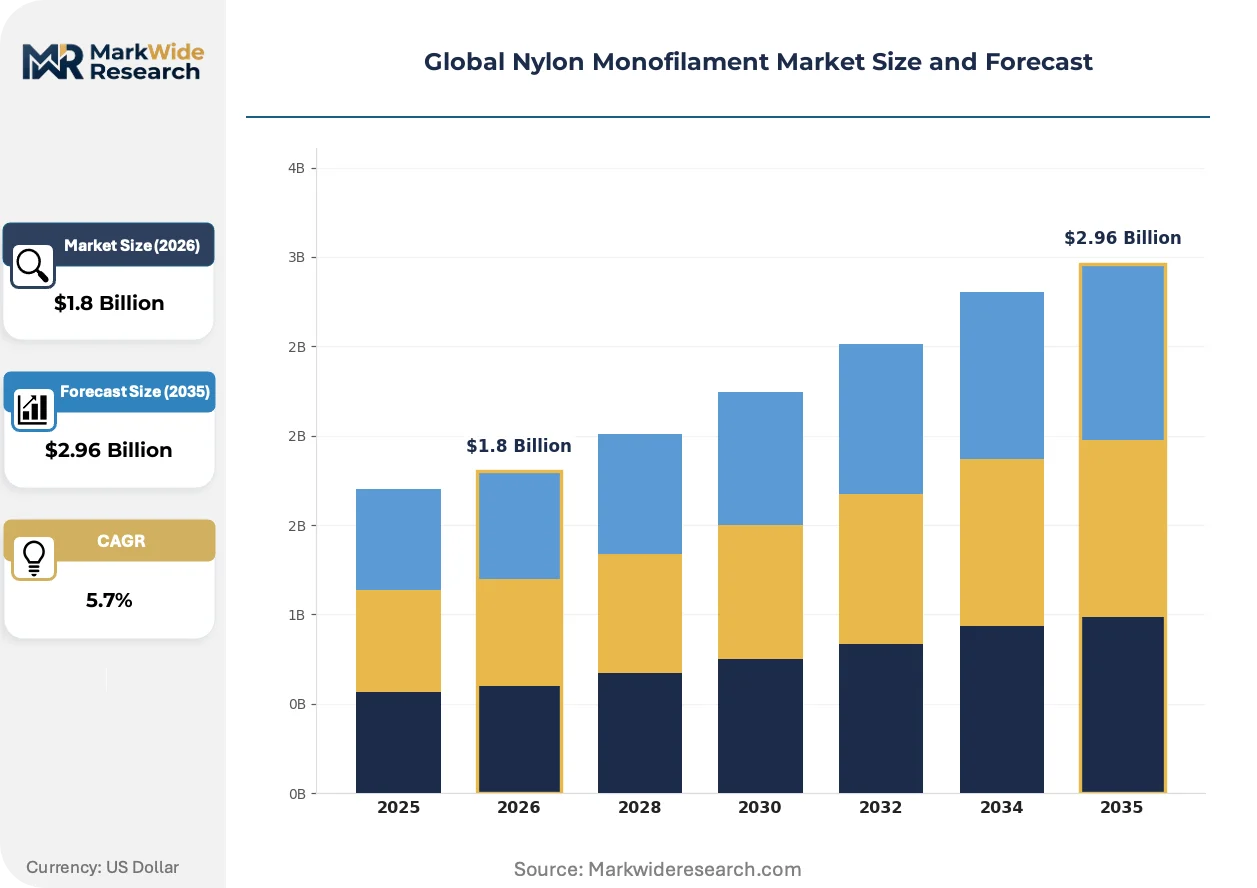
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fishing Lines, Medical Sutures, Industrial Filaments, Garden Lines End User: Textile Industry, Fishing Industry, Healthcare Sector, Agriculture Form: Non-Treated, Treated, Coated, Reinforced Application: Sporting Goods, Medical Devices, Agricultural Tools, Construction |
| Companies Covered | Toray Industries, Inc., BASF SE, DuPont, Royal DSM, Solvay, Evonik Industries AG, Asahi Kasei Corporation, Ascend Performance Materials, Perlon Monofil GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nylon Monofilament Market Strategic Shifts
Coating and surface treatment technologies are compressing the performance gap between commodity and specialty grades, while regulatory fragmentation across FDA, EMA, and NMPA jurisdictions is forcing parallel qualification investments.
Multi-layer co-extrusion is unifying barrier and mechanical properties in single-pass operations. Medical device manufacturers in Japan are adopting these systems to consolidate USP-compliant suture production. The technology is unifying what previously required separate extrusion and coating steps, reducing qualified supplier counts.
REACH Annex XVII restrictions on monomer residuals are tightening specification windows for implantable applications. ECHA enforcement is pushing compounders toward closed-loop polymerization controls. German suture manufacturers are responding with captive resin purification investments.
Hospital procurement consolidation is compressing vendor counts and demanding bundled suture-and-needle contracts. Integrated device suppliers are displacing standalone filament distributors in North American surgical channels. The shift is most visible in ambulatory surgery center networks seeking single-source accountability.
Global Nylon Monofilament Market Segmentation
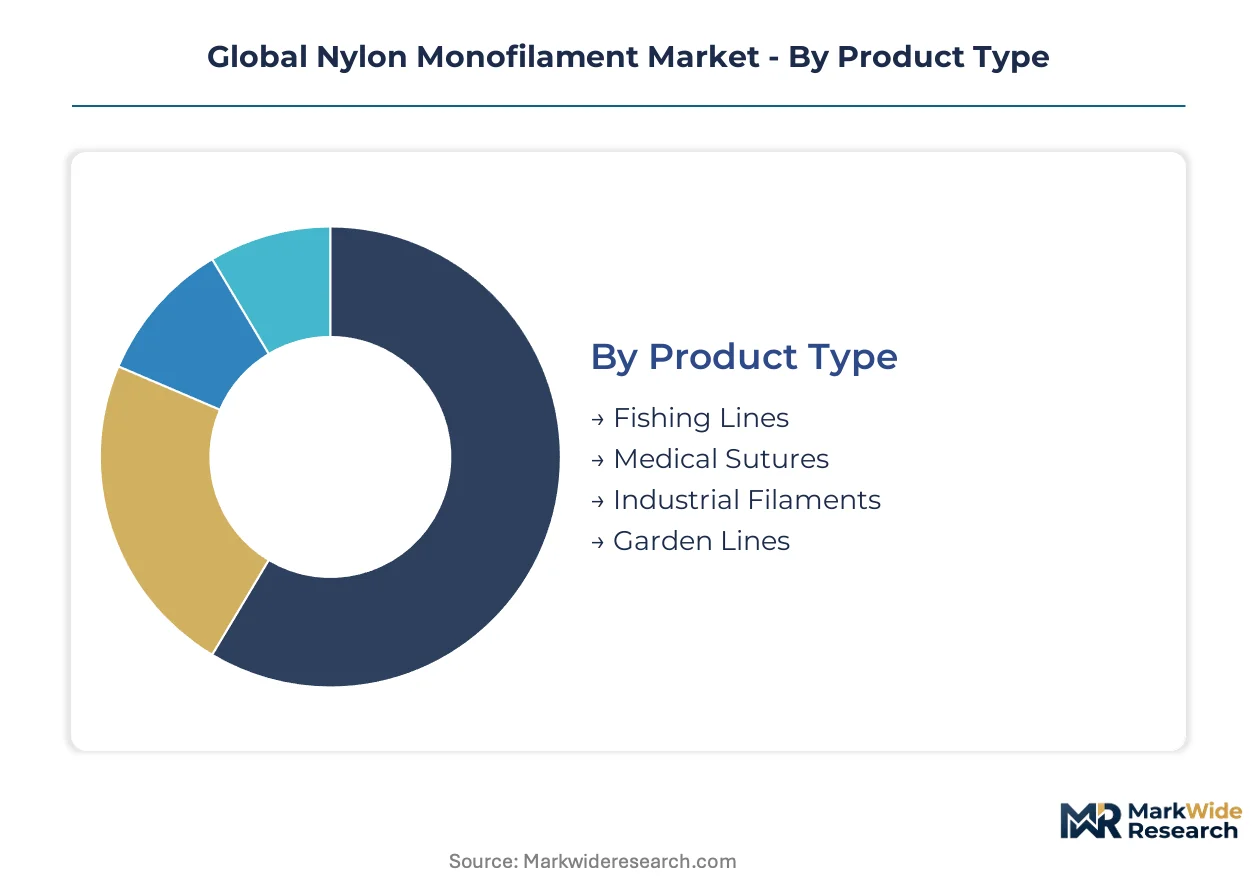
Nylon monofilament purchasing decisions hinge on performance certification tiers rather than commodity pricing. Buyers in surgical and industrial channels evaluate diameter tolerance, tensile consistency, and regulatory compliance as primary selection filters.
Product Type:
Buyers prioritize certification burden and margin sustainability when selecting product categories.
- Medical Sutures:USP Class VI and ISO 10993 compliance requirements restrict qualified suppliers to polymerization-integrated manufacturers. German and Japanese device makers consolidate procurement around REACH-certified resin streams, locking in premium contract structures.
- Fishing Lines:China's Zhejiang province dominates volume output through chip-to-yarn integrated operations serving Southeast Asian aquaculture fleet modernization. UV stabilization additive packages differentiate specification wins.
- Industrial Filaments:Construction geogrid and agricultural trellis applications anchor volume with thinner margin profiles.
- Garden Lines:Consumer trimming applications face displacement pressure from lower-cost PET alternatives.
Volume sits with Fishing Lines; growth tilts toward Medical Sutures.
End User:
Customer procurement scale and technical specification stringency segment demand concentration.
- Healthcare Sector:Hospital consolidation compresses vendor counts and demands bundled suture-and-needle contracts. Ambulatory surgery center networks in North America seek single-source accountability from integrated device suppliers.
- Fishing Industry:Fleet operators specify recyclable monofilament grades under EU extended producer responsibility frameworks for gear collection mandates.
- Agriculture:Trellis and greenhouse applications drive treated filament demand for outdoor service life extension.
- Textile Industry:Industrial sewing and binding operations consume commodity grades with price-sensitive procurement.
Procurement scale concentrates in Healthcare Sector; specification complexity climbs fastest in Fishing Industry.
Form:
Surface engineering investment separates premium positioning from commodity supply.
- Coated:Fluoropolymer and lubricious surface finishes command specification in surgical and high-performance sporting goods channels. Multi-layer co-extrusion systems consolidate previously separate extrusion and coating steps.
- Treated:UV stabilization chemistry advances open wins in agricultural trellis and construction geogrid applications exposed to prolonged outdoor degradation.
- Reinforced:High-tenacity industrial grades require captive polymerization controls to sustain margin.
- Non-Treated:Base filament serves cost-sensitive textile and consumer applications with minimal additive burden.
Technology investment concentrates in Coated; adoption velocity runs highest in Treated.
Application:
Regulatory jurisdiction fragmentation shapes parallel qualification investment requirements.
- Medical Devices:FDA 21 CFR Part 177.1500, EU MDR, and NMPA registration create three-track compliance architecture. Cytotoxicity and sensitization testing protocols extend product launch cycles by 18-24 months.
- Construction:Geogrid and concrete reinforcement applications specify high-tenacity PA66 grades constrained by European adipic acid production bottlenecks.
- Agricultural Tools:Trellis, greenhouse, and binding applications specify UV-stabilized treated forms for extended field service.
- Sporting Goods:North American recreational fishing and racket stringing channels differentiate on fluoropolymer-coated offerings.
Certification burden concentrates in Medical Devices; specification expansion runs steepest in Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of commodity-grade industrial filament while Germany and Japan dominate medical suture certification. Consumption clusters diverge between Southeast Asian aquaculture fleet modernization and North American surgical device procurement.
China
Zhejiang province's integrated nylon-6 chip-to-yarn operations supply fishing line demand from Vietnamese and Indonesian fleet operators. GB standards and NMPA registration requirements for surgical sutures create parallel compliance tracks for export-bound manufacturers. Shaoxing and Jiaxing industrial zones concentrate extrusion capacity serving both domestic textile binding and international sporting goods channels.
Germany
REACH Annex XVII enforcement on monomer residuals tightens specification windows for implantable polymer applications. EU MDR biocompatibility mandates compress supplier qualification timelines around certified PA66 resin streams. Baden-Württemberg medical device manufacturers consolidate procurement through captive polymerization investments near Ludwigshafen chemical complexes.
United States
Hospital procurement consolidation drives bundled suture-and-needle contract demand across ambulatory surgery center networks. FDA 21 CFR Part 177.1500 governs nylon resin contact specifications for food and indirect medical applications. North Carolina and Virginia textile corridors host fluoropolymer-coated filament operations serving recreational fishing and racket stringing channels.
Japan
METI industrial standards and PMDA medical device regulations shape dual-track qualification requirements for domestic and export markets. Kansai region polymerization-integrated producers sustain margin on high-tenacity industrial grades through captive caprolactam supply. Osaka-based device manufacturers adopt multi-layer co-extrusion systems to consolidate USP-compliant suture production.
Brazil
ANVISA registration pathways for USP Class VI materials remain underpenetrated by qualified Asian suppliers, creating procurement gaps for domestic surgical device manufacturers. São Paulo state medical distributors seek alternative resin sources as European adipic acid bottlenecks constrain PA66 availability. Local fishing fleet operators import treated monofilament directly from Zhejiang exporters, bypassing regional conversion facilities.
Global Nylon Monofilament Market Competitive Environment
Capital-heavy producers compete with asset-light designers across certification-tiered market segments. Integrated polymerization-to-filament operations command premium positioning in medical channels where REACH and MDR compliance narrow qualified supplier pools. Three archetypes dominate: resin-integrated multinationals anchoring medical certification, regional extrusion specialists serving industrial volume, and coating-technology differentiators in sporting goods. Competitive moves concentrate on backward integration into caprolactam supply and multi-layer co-extrusion system adoption.
Among resin-integrated multinationals, Toray Industries, Inc., BASF SE, and DuPont exemplify divergent geographic anchoring strategies. Toray represents Japanese captive polymerization approaches sustaining margin on high-tenacity grades. BASF SE occupies a position anchoring European medical suture supply through certified PA66 streams. DuPont sits within North American sporting goods differentiation, with fluoropolymer-coated offerings compressing the performance gap between commodity and specialty tiers. Each archetype responds to distinct regulatory jurisdictions—METI and PMDA in Japan, ECHA and EU MDR in Europe, FDA in the United States—forcing parallel qualification investments rather than global product standardization.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| BASF SE |
| DuPont |
| Royal DSM |
| Solvay |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| Ascend Performance Materials |
| Perlon Monofil GmbH |
| Others |
Value Chain & Pricing Dynamics
EU MDR biocompatibility mandates and REACH Annex XVII enforcement on monomer residuals are compressing supplier qualification timelines and forcing buyers toward polymerization-integrated manufacturers, which in turn concentrates pricing power among certified resin stream holders and widens spreads between compliant and non-compliant grades.
Pricing Analysis
Margin tightening in commodity-grade industrial filament reflects benzene derivative feedstock swings and polyester substitution pressure, while premium medical suture contracts sustain structural premiums through USP Class VI and ISO 10993 certification scarcity. Pricing stratifies across certification tiers, with REACH-certified PA66 resin streams commanding substantial premia over standard industrial grades. Hospital procurement consolidation intensifies cost-down pressure on bundled suture-and-needle contracts, rendering ambulatory surgery centers the most price-sensitive buyers and polymerization-integrated multinationals the least.
Supply Chain Analysis
Freight cost differentials between Zhejiang province export hubs and European medical device clusters favor regional captive polymerization investments over long-haul resin shipments. Supply concentrates in China for commodity nylon-6 chip-to-yarn operations, Germany for REACH-certified PA66 medical grades, and Japan for high-tenacity industrial filament. Raw material flows hinge on caprolactam from benzene derivatives, adipic acid for PA66 polymerization, and UV stabilizer additive packages. Single-source vulnerability sits with European adipic acid production bottlenecks. Distribution runs through integrated device suppliers displacing standalone filament distributors in North American surgical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-integrated players as regulatory fragmentation across FDA, EMA, and NMPA jurisdictions forces parallel qualification investments that weaker capitalized extrusion specialists cannot sustain.
For Market Incumbents: Cement polymerization-to-filament integration through captive caprolactam supply investments near Ludwigshafen or Kansai chemical complexes. Deepen backward integration into bio-based feedstock certification to capture mass balance accounting premiums before mass-market commoditization. Lock in long-term resin contracts with Baden-Württemberg device manufacturers facing EU MDR compliance deadlines. For New Entrants and Emerging Players: Ambulatory surgery center networks seeking single-source accountability represent the most penetrable channel for qualified Asian suppliers lacking European medical certification history. Target Brazilian ANVISA registration pathways for USP Class VI materials where qualified supply remains scarce. Pursue co-development partnerships with Zhejiang fishing line exporters seeking UV stabilization chemistry upgrades for EU extended producer responsibility compliance. For Investors and Strategic Acquirers: The window for entry favors mid-cap coating-technology specialists with fluoropolymer surface treatment capabilities applicable across surgical and sporting goods channels. Long-term viability rests on acquiring assets with existing ISO 10993 certification infrastructure rather than greenfield qualification timelines. Watch for ANVISA registration approvals by Asian suppliers as the inflection signal for Brazilian market penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam Supply | Toray Industries sustains margin on high-tenacity grades through captive polymerization in Kansai. |
| Multi-layer Co-extrusion System Adoption | Osaka device manufacturers consolidate USP-compliant suture production into single-pass operations. |
| Bio-based Feedstock Certification Investment | Mass balance accounting standards create premium positioning for renewable caprolactam claims. |
| ANVISA Registration Pathway Development | Qualified Asian suppliers can capture procurement gaps in São Paulo state surgical device distribution. |
| Extended Producer Responsibility Compliance | EU fishing gear collection mandates drive specification for recyclable monofilament grades. |
Study Parameters
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone, supplemented by primary interviews with extrusion plant managers, medical device procurement leads, polymerization R&D directors, and distribution channel partners across China, Germany, Japan, and the United States. Bottom-up and top-down triangulation validated volume estimates against customs data and downstream consumption patterns.
Bottom-up modeling built from filament diameter specifications, polymerization capacity utilization, and end-use application intensity across medical suture, fishing line, industrial geogrid, and agricultural trellis segments. Top-down cross-checks applied macroeconomic indicators and polymer consumption ratios. CAGRs derived from regression analysis of historical price-volume relationships and regulatory-driven substitution elasticity. Forecast inputs incorporated REACH Annex XVII enforcement timelines and EU MDR transition deadlines.
Several conditions sit outside the modeled scope, including abrupt caprolactam feedstock disruptions, unilateral tariff adjustments on Chinese filament exports, and accelerated polyester substitution in non-load-bearing applications. Forecasts reflect documented assumptions about certification timeline continuity and resin supply chain stability. Stakeholders should weight assumptions against their own operating context and monitor ECHA enforcement patterns for signals of specification window tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Ceramic Fiber Market
Fibers
Carbon Fiber Tapes Market
Fibers
Carbon Fiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Fiberglass Mat Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
High Performance Fibers for Defense Market
Fibers
Thermoformed Fiber Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Renewable Carbon Fibers Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Global Electronic Grade Glass Fibers Market