
 Global Perfluorinated Type Plastic Optical Fiber Market | 2026-2036
Global Perfluorinated Type Plastic Optical Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfluorinated Type Plastic Optical Fiber Market Outlook
The performance gap between silica fiber and perfluorinated plastic optical fiber is narrowing as graded-index engineering and perfluorinated polymer chemistry advance. Fujikura Ltd. leverages its polymer science heritage to sustain leadership in high-purity fluorinated resin formulations. Chromis Fiberoptics Inc. anchors its position through specialized multi-mode fiber architectures for industrial sensing networks. Daikin Industries Ltd. competes by controlling captive fluoropolymer feedstock supply for captive fiber extrusion.
Perfluorinated type plastic optical fiber consists of a perfluorinated polymer core—typically amorphous fluoroplastic with a refractive index near 1.35—clad with lower-index fluorinated polymers, manufactured via melt extrusion or preform drawing to achieve bandwidth-distance products exceeding 1 Gbps over 100 meters. Its primary purpose is short-reach, high-flexibility data transmission where silica fragility, bending loss, or cost prohibit deployment. Multi-mode fiber occupies the largest installed base due to legacy compatibility with LED and VCSEL sources in building automation and automotive networks. Specialty fiber represents the fastest-expanding margin pool as medical device OEMs specify biocompatible, sterilization-resistant jackets for surgical robotics and endoscopic systems. Ribbon fiber configurations sustain demand in dense telecom backhaul where multiple channels must deploy through constrained duct infrastructure.
FDA device regulations in the United States, EU MDR and REACH in Europe, and China's NMPA medical device classification rules collectively shape product certification pathways and material disclosure requirements for perfluorinated fiber entering healthcare applications. Japan's METI energy efficiency directives and JIS standards for building communications infrastructure reinforce domestic quality benchmarks that export-oriented manufacturers must satisfy. Stakeholders must monitor how fluoropolymer environmental scrutiny under OECD chemical hazard assessments and evolving EU F-Gas restrictions recalibrate raw material availability and reformulation timelines.
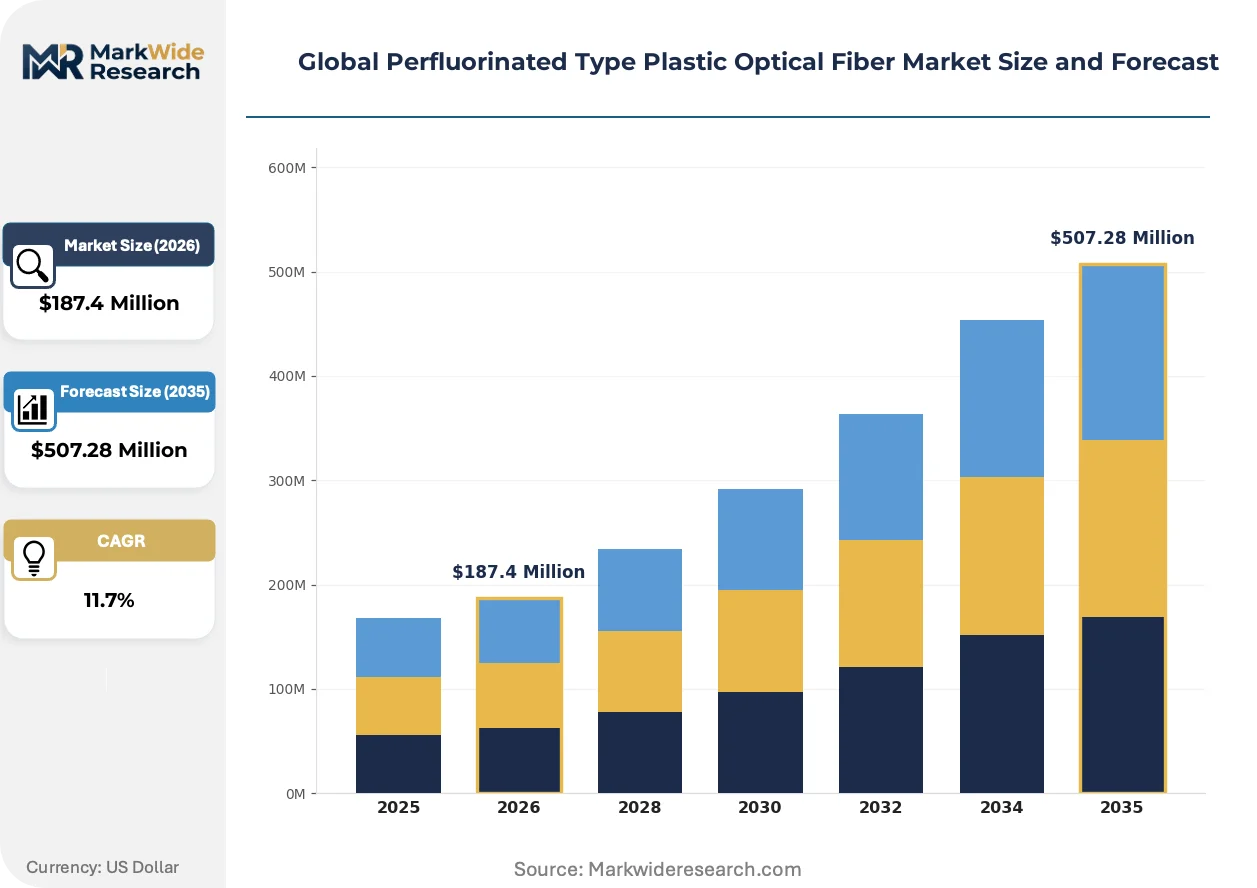
Market Dynamics
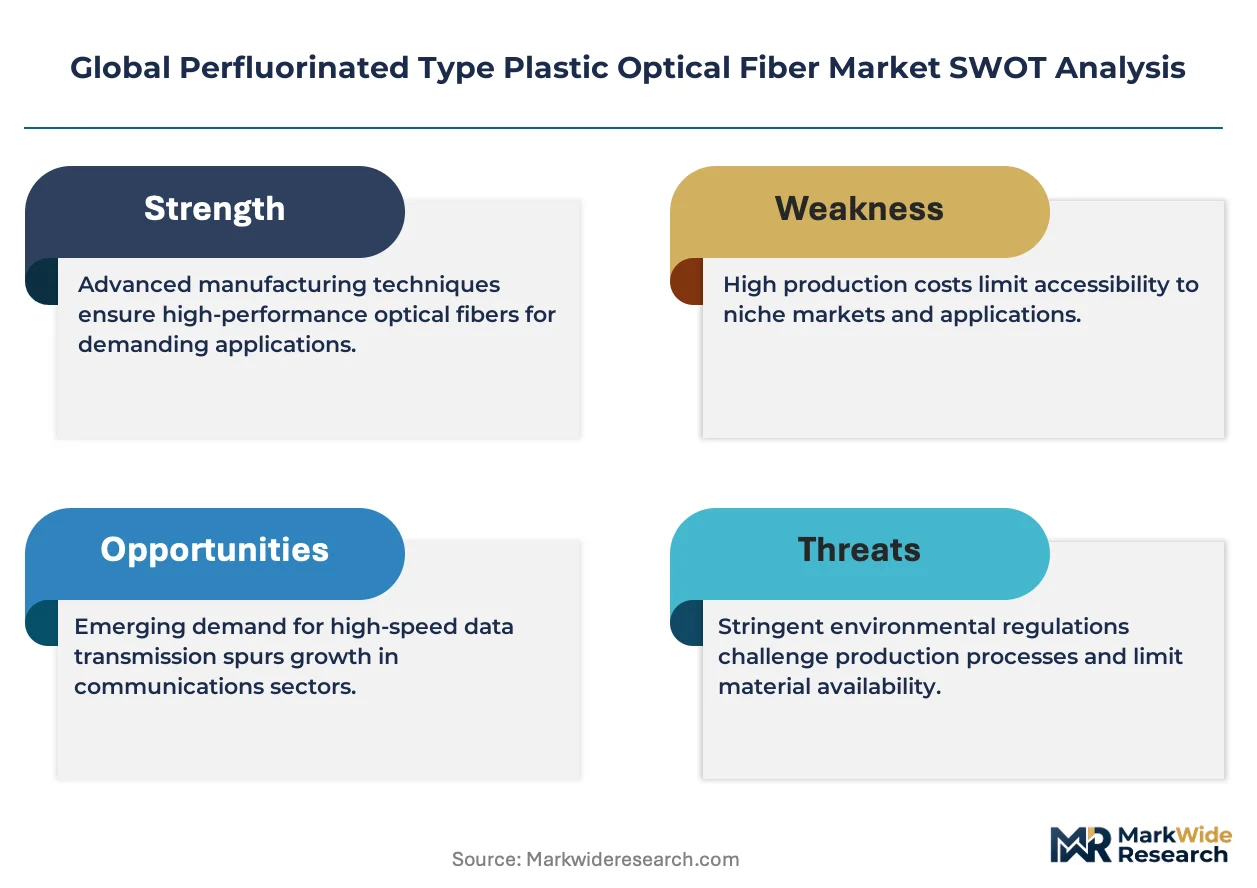
REACH compliance deadlines and China's dual carbon goals are forcing fluoropolymer reformulation cycles that compress supplier margins while opening first-mover advantages for resin innovators with certified low-GWP chemistries.
Growth Catalysts
- EU MDR medical device certification:Biocompatibility mandates for surgical robotics are pulling perfluorinated fiber into endoscopic instrumentation at premium pricing tiers.
- Guangdong province cluster concentration:Fiber optic component ecosystems in this region serve simultaneous demand from domestic telecom buildouts and export-oriented medical device assembly.
- Graded-index polymer engineering:Bandwidth-distance improvements are digitizing legacy building automation networks previously served by silica fiber alternatives.
Market Restraints
- Fluoropolymer feedstock concentration:Captive resin production by Japanese and German chemical conglomerates limits second-tier fiber extruders to spot-market purchasing with volatile term structures.
- EU F-Gas Regulation phase-down schedules:Restricted availability of high-performance fluorinated monomers is extending raw material qualification timelines by 18-24 months for non-integrated manufacturers.
- Silica fiber cost compression:Mass-produced bend-insensitive single-mode fiber from Chinese state-owned enterprises is narrowing the cost-performance window for short-reach plastic optical fiber deployment.
Strategic Opportunities
- Saudi Arabia healthcare infrastructure:SFDA medical device registration pathways and MOHAP procurement standardization are creating anchor demand for sterilization-resistant fiber in surgical suites.
- Industrial sensing network convergence:Integration of perfluorinated fiber with distributed acoustic sensing systems is opening condition-monitoring applications in chemical processing plants.
- Japan METI energy efficiency directives:Building communications infrastructure mandates are mandating low-loss optical cabling in commercial retrofits, favoring flexible polymer solutions over rigid glass.
Industry Challenges
- Fluoropolymer synthesis talent scarcity:Specialized polymer chemists capable of amorphous fluoroplastic molecular weight control command compensation premiums that strain R&D budgets at mid-scale extruders.
- Multi-jurisdiction certification stacking:Simultaneous FDA 510(k), EU MDR, and NMPA Class II device pathways require redundant biocompatibility testing protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfluorinated Type Plastic Optical Fiber Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Specialty Fiber, Ribbon Fiber Application: Telecommunications, Medical Devices, Industrial Applications, Military End User: Telecom Providers, Healthcare Institutions, Manufacturing Units, Defense Contractors Installation: Indoor, Outdoor, Undersea, Aerial |
| Companies Covered | Asahi Kasei Corporation, Fujikura Ltd., Chromis Fiberoptics Inc., Sumitomo Electric Industries Ltd., Furukawa Electric Co. Ltd., 3M Company, Daikin Industries Ltd., Mitsubishi Chemical Group, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfluorinated Type Plastic Optical Fiber Market Strategic Shifts
Active reformulation of perfluorinated polymer cores around lower-global-warming-potential chemistries is intersecting with graded-index manufacturing advances to expand addressable bandwidth in legacy multi-mode installations.
Perfluorinated amorphous fluoroplastic core materials with refractive indices near 1.35 are digitizing building automation networks previously constrained by LED-VCSEL compatibility limitations. Facility managers in German commercial real estate are specifying these fibers for retrofit deployments where conduit space prohibits silica fiber bending radii. The structural consequence is compression of legacy copper and glass hybrid infrastructure in sub-100-meter data runs.
EU F-Gas Regulation phase-down schedules are forcing fluoropolymer manufacturers toward hydrofluoroether and fluoroketone process chemistries with reduced greenhouse gas footprints. Industrial consequence includes 12-18 month reformulation timelines for fiber extruders dependent on external resin supply. Medical device OEMs in the Netherlands and Switzerland are responding by pre-qualifying alternative jacket materials ahead of mandatory disclosure deadlines.
Japanese automotive Tier-1 suppliers are consolidating fiber procurement through designated component distributors rather than direct mill relationships. The traditional spot-buying model for optical cabling is yielding to multi-year framework agreements with volume-commitment pricing. This shift is most visible in Kanagawa and Aichi prefectures where vehicle network architecture standardization around 10 Gbps+ in-vehicle backbones is concentrating buyer power at three major harness manufacturers.
Global Perfluorinated Type Plastic Optical Fiber Market Segmentation
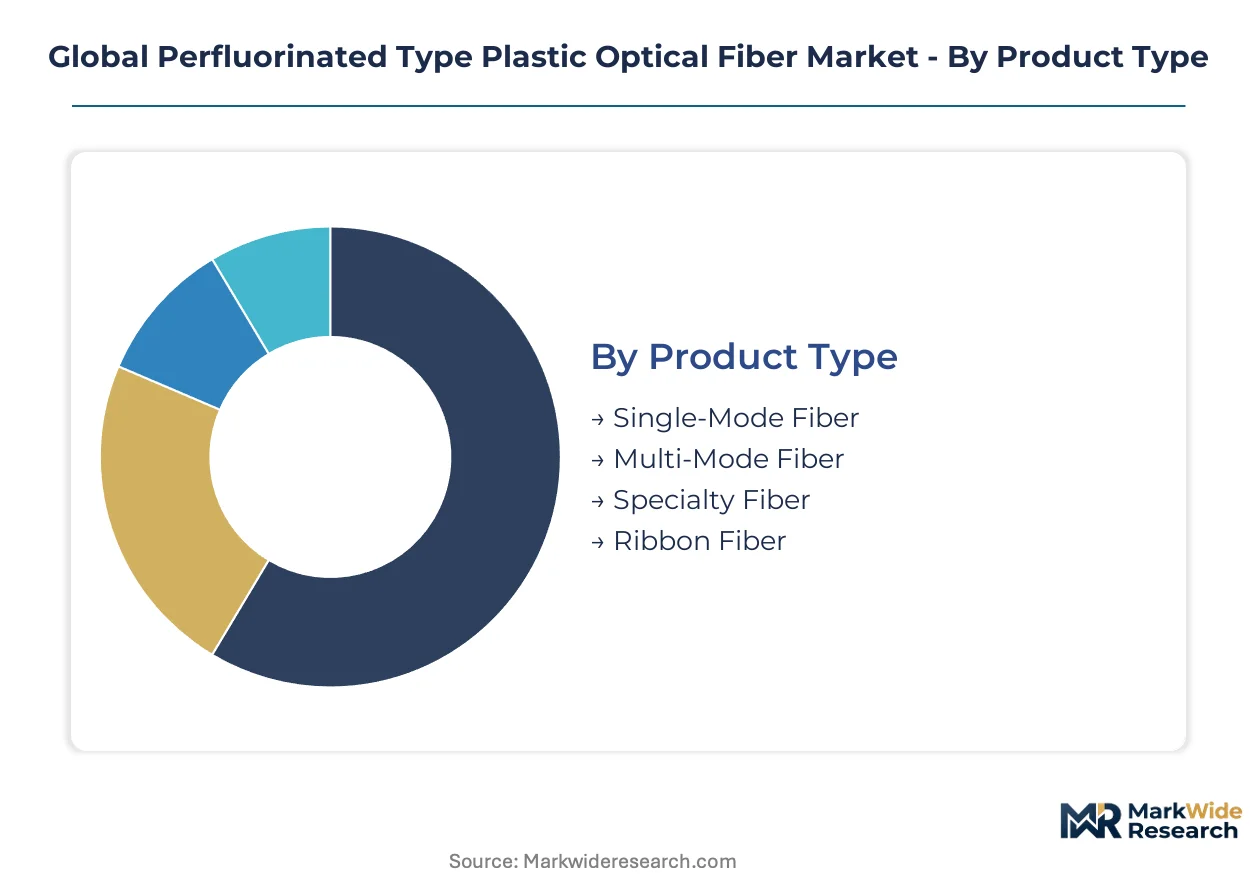
Perfluorinated plastic optical fiber serves heterogeneous deployment environments where polymer flexibility, chemical resistance, and bandwidth-distance trade-offs vary sharply. Segmentation reveals how fiber architecture, application severity, and installation constraints reshape procurement specifications and margin structures across buyer categories.
Product Type:
Mature multi-mode installations dominate legacy building automation, while emerging specialty formulations capture premium medical certification pathways.
- Multi-Mode Fiber:Graded-index polymer engineering achieves bandwidth-distance products exceeding 1 Gbps over 100 meters using LED and VCSEL sources. German commercial real estate retrofit projects specify this architecture where conduit bending radii prohibit silica fiber deployment.
- Specialty Fiber:Biocompatible fluorinated polymer jackets withstand autoclave sterilization cycles and gamma irradiation for surgical robotics. Netherlands and Switzerland medical device OEMs are pre-qualifying alternative jacket materials ahead of EU F-Gas disclosure deadlines.
- Single-Mode Fiber:Limited deployment in short-reach sensing networks where modal dispersion control exceeds cost constraints.
- Ribbon Fiber:Dense fiber arrays serve telecom backhaul through constrained duct infrastructure in Guangdong province clusters.
Multi-mode fiber handles the majority of throughput; specialty fiber is expanding most quickly on share.
Application:
Cost tier stratification separates commodity telecom volumes from medical device premium pricing.
- Medical Devices:Minimally invasive surgical instrumentation demands sterilization-resistant jackets and sub-millimeter bend diameters. FDA 510(k), EU MDR, and NMPA Class II certification stacking extends product launch timelines for fiber suppliers.
- Telecommunications:Short-reach data center interconnects and building automation digitization drive volume procurement. Chinese state-owned silica fiber producers are compressing the cost-performance window for polymer alternatives.
- Industrial Applications:Distributed acoustic sensing integration enables condition monitoring in chemical processing plants.
- Military:Ruggedized cable assemblies prioritize electromagnetic immunity and rapid field termination.
Telecommunications commands absolute volume; medical devices deliver the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication from framework agreements to spot-market purchasing.
- Telecom Providers:Japanese automotive Tier-1 suppliers are consolidating fiber procurement through designated distributors with multi-year volume commitments replacing spot-buying.
- Healthcare Institutions:Saudi SFDA registration pathways and UAE MOHAP procurement standardization are creating anchor demand for sterilization-resistant fiber in surgical suites.
- Manufacturing Units:Factory automation networks specify polymer fiber for robotic cable carrier applications.
- Defense Contractors:Mil-spec qualification requirements limit supplier pools to pre-certified extruders.
Telecom providers generate the bulk of purchase orders; healthcare institutions are climbing the fastest on procurement value.
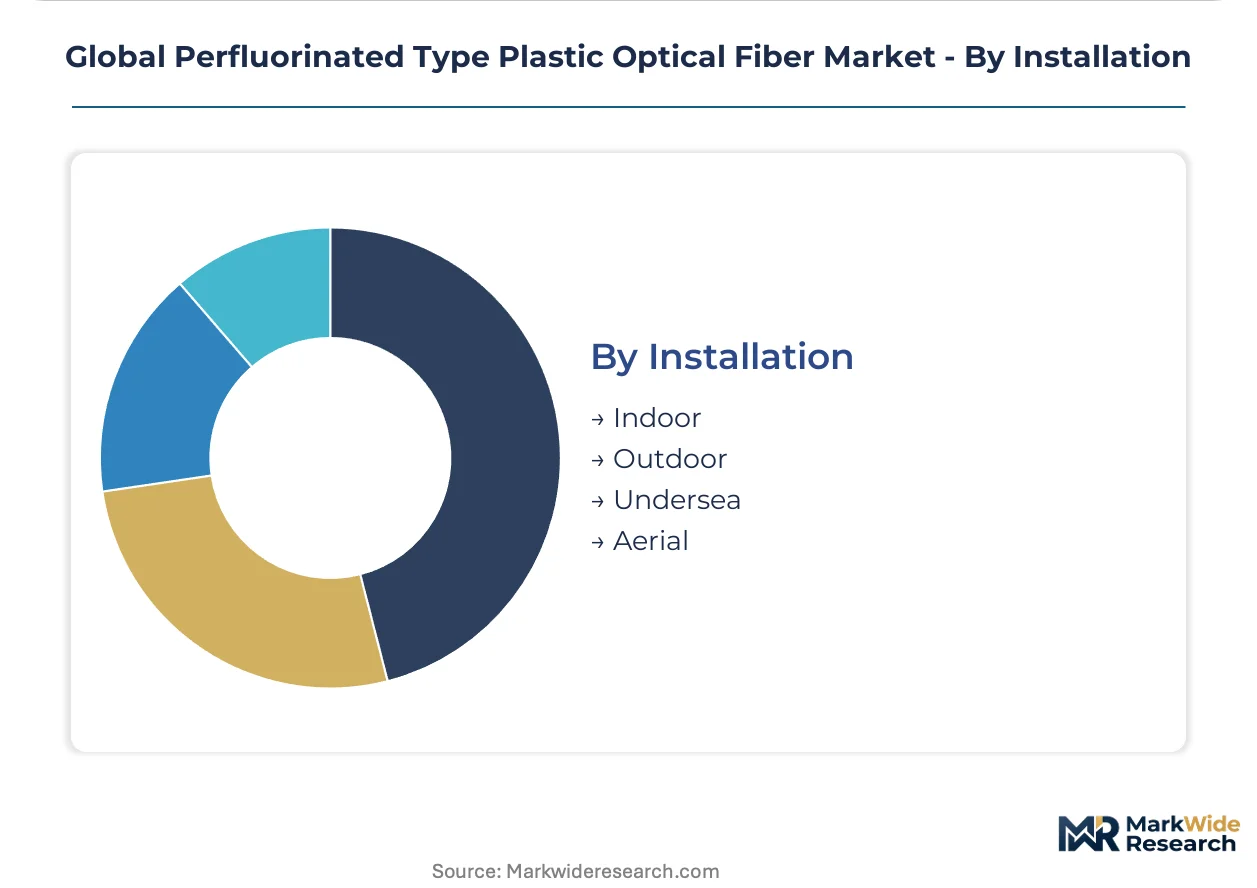
Installation:
Geography and environmental exposure dictate jacket compound selection and mechanical reinforcement specifications.
- Indoor:Plenum-rated fluoropolymer jackets satisfy building code fire resistance requirements. Japan METI energy efficiency directives mandate low-loss optical cabling in commercial retrofits.
- Outdoor:UV-stabilized and moisture-barrier constructions endure temperature cycling in aerial and buried deployments.
- Undersea:Pressure-resistant encapsulation and hydrogen-blocking layers protect against deep-ocean permeation.
- Aerial:Tensile strength members and ice-loading specifications dominate utility pole attachment designs.
Indoor installations account for the dominant deployment base; outdoor applications are gaining share fastest as industrial sensing networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese fluoropolymer producers export high-purity resin formulations to fiber extruders in Germany and China, sustaining a tripolar trade corridor that concentrates advanced material flows across three manufacturing geographies.
China
Guangdong province fiber optic component clusters serve domestic telecom buildouts and export-oriented medical device assembly simultaneously. NMPA medical device classification rules and MIIT telecommunications standards create dual compliance pathways for fiber suppliers. Shenzhen and Dongguan manufacturing zones concentrate extrusion capacity for ribbon fiber configurations destined for dense telecom backhaul.
Germany
Commercial real estate retrofit projects specify graded-index polymer fiber where conduit bending radii prohibit silica deployment. REACH compliance deadlines and EU MDR biocompatibility mandates force reformulation cycles for surgical robotics applications. Baden-Württemberg medical device OEMs pre-qualify alternative jacket materials ahead of mandatory disclosure timelines.
Japan
METI energy efficiency directives mandate low-loss optical cabling in commercial building retrofits favoring flexible polymer solutions. Kanagawa and Aichi prefecture automotive Tier-1 suppliers consolidate fiber procurement through multi-year framework agreements replacing spot-buying. Domestic chemical conglomerates maintain captive fluoropolymer feedstock production for integrated fiber extrusion operations.
United States
FDA 510(k) device certification pathways extend product launch timelines for sterilization-resistant fiber entering surgical robotics. Distributed acoustic sensing integration enables condition-monitoring deployments in Gulf Coast chemical processing plants. Massachusetts and California medical device clusters drive premium-tier demand for autoclave-resistant jacket formulations.
Saudi Arabia
SFDA medical device registration pathways and MOHAP procurement standardization create anchor demand for sterilization-resistant fiber in surgical suites. Healthcare infrastructure expansion under Vision 2030 concentrates procurement authority at centralized health authorities. Riyadh and Jeddah hospital construction projects specify fluorinated polymer cabling for operating theater digitization.
Global Perfluorinated Type Plastic Optical Fiber Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where integrated chemical conglomerates hold supply advantages over independent extruders. The vendor base separates into three strategic archetypes: captive-resin producers with backward integration into fluoropolymer synthesis, specialized fiber architects focused on multi-mode and graded-index engineering, and diversified materials conglomerates leveraging polymer science heritage across adjacent optical markets. Dominant competitive moves include multi-year procurement framework agreements with automotive and telecom anchor buyers, and pre-qualification of alternative jacket chemistries ahead of EU F-Gas phase-down deadlines.
Among Japanese integrated producers, Fujikura Ltd., Sumitomo Electric Industries Ltd., and Furukawa Electric Co. Ltd. exemplify the captive-resin archetype through in-house fluoropolymer production and fiber extrusion capabilities. These Tokyo and Osaka-based manufacturers occupy positions where upstream control over amorphous fluoroplastic formulations insulates against raw material volatility. Their scale-driven operations anchor premium-tier supply for medical device and telecommunications applications requiring certified low-GWP chemistries.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Fujikura Ltd. |
| Chromis Fiberoptics Inc. |
| Sumitomo Electric Industries Ltd. |
| Furukawa Electric Co. Ltd. |
| 3M Company |
| Daikin Industries Ltd. |
| Mitsubishi Chemical Group |
| AGC Inc. |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phase-down schedules constitute the dominant risk vector compressing both pricing tier spreads and supply chain configuration, as restricted fluorinated monomer availability forces medical device OEMs toward pre-qualified alternative jacket materials while stranding non-integrated extruders on volatile spot-market term structures.
Pricing Analysis
Prior-generation step-index polymer fiber trades at commodity-equivalent levels, current-generation graded-index formulations command certification-linked premiums from surgical robotics OEMs, and next-generation low-GWP chemistry variants are pricing at prototype-stage multiples before REACH-aligned scale economics materialize. Three-tier pricing structure across premium, standard, and economy levels separates autoclave-resistant medical grades from building automation volumes and industrial sensing commodity tiers. Cost compression in the standard tier is intensifying because Chinese state-owned silica fiber producers are narrowing the cost-performance window for short-reach polymer alternatives. Healthcare institutions demonstrate the lowest price sensitivity due to regulatory compliance requirements, while telecom providers in Guangdong province exhibit the highest sensitivity as procurement consolidates through multi-year framework agreements.
Supply Chain Analysis
Tariff exposure between Japan and Germany on high-purity fluorinated resin formulations dominates supply chain risk assessment for independent fiber extruders lacking captive polymer synthesis. Manufacturing concentration centers on Japan, Germany, and China's Guangdong province, where integrated chemical conglomerates control amorphous fluoroplastic feedstock production. Raw material sourcing draws from fluorinated monomer specialists, specialty polymer compounders, and medical-grade jacket material providers. Single-source vulnerability concentrates in Japanese fluoropolymer producers exporting resin formulations to German and Chinese extrusion facilities. Distribution runs through designated component distributors serving Japanese automotive Tier-1 suppliers and direct mill relationships for medical device OEMs requiring biocompatibility certification stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer chemists capable of amorphous fluoroplastic molecular weight control represent the critical skill scarcity constraining R&D throughput at mid-scale extruders, creating asymmetric capability advantages for integrated chemical conglomerates with in-house talent pipelines.
For Market Incumbents: Entrench supply security through backward integration into fluoropolymer synthesis or locked long-term offtake agreements with Japanese resin producers before EU F-Gas phase-down deadlines accelerate feedstock competition. Prioritize pre-qualification of alternative low-GWP jacket chemistries ahead of mandatory disclosure timelines to defend premium-tier positioning against reformulation-lagged competitors. Capacity addition in Baden-Württemberg medical device clusters offers geographic anchoring for EU MDR-certified production.
For New Entrants and Emerging Players: Pursue white-space opportunity in Saudi Arabian healthcare infrastructure under Vision 2030, where SFDA registration pathways and centralized MOHAP procurement create anchor demand without incumbent saturation. Target industrial sensing network convergence applications in Gulf Coast chemical processing plants, where distributed acoustic sensing integration remains underpenetrated by established fiber architects. A specialized multi-mode fiber engineering competency provides the most viable go-to-market angle against integrated conglomerates.
For Investors and Strategic Acquirers: The market sits at a reformulation-cycle phase that favors captive-resin producers with certified low-GWP chemistry pipelines over non-integrated extruders facing 18-24 month raw material qualification timelines. Long-term viability across the analysis window hinges on upstream control over fluoropolymer feedstock or exclusive distributor relationships with automotive anchor buyers. Acquisition target archetype: mid-scale extruders with medical device certification stacking capabilities but resin supply vulnerability. The signal to watch is Japanese automotive Tier-1 supplier procurement consolidation velocity, as framework agreement penetration indicates pricing power compression for spot-market-dependent players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Synthesis | Captive resin production insulates Japanese and German conglomerates from EU F-Gas supply restrictions. |
| Pre-Qualification of Low-GWP Jacket Chemistries | Netherlands and Switzerland medical device OEMs are advancing alternative materials ahead of REACH deadlines. |
| Multi-Year Procurement Framework Agreements | Kanagawa and Aichi prefecture automotive suppliers are consolidating fiber purchasing through designated distributors. |
| Medical Device Certification Stacking Investment | Simultaneous FDA 510(k), EU MDR, and NMPA Class II pathways extend launch timelines but lock in premium pricing tiers. |
| Industrial Sensing Network Partnership Development | Distributed acoustic sensing integration in chemical processing plants opens condition-monitoring applications beyond traditional telecom. |
Study Parameters
Desk research of fluoropolymer trade flow databases, SEC 10-K filings from integrated chemical conglomerates, and EU ECHA regulatory disclosure records preceded structured interviews with polymer R&D directors, medical device procurement managers at German OEMs, fiber extrusion plant managers, and Japanese automotive Tier-1 supplier sourcing leads. Primary fieldwork combined with secondary validation from MIIT telecommunications standards documentation and NMPA medical device classification rules enabled bottom-up and top-down triangulation across the value chain.
Forecast assumptions held EU F-Gas phase-down schedules and REACH compliance deadlines as fixed boundary conditions while varying fluoropolymer innovation cycle velocity and medical device OEM pre-qualification adoption rates across the projection horizon. Segmentation dimensions modeled include product architecture (multi-mode, specialty, ribbon), application severity (medical device, telecommunications, industrial), and regional regulatory cluster (FDA-dominated, EMA-aligned, NMPA-governed). CAGRs were derived from installed base replacement dynamics and greenfield deployment pipelines, with specific inputs from Guangdong province fiber optic component cluster output data and German commercial real estate retrofit specification trends.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale extruders or accelerated low-GWP chemistry breakthroughs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Global Fiberglass Market
Fibers
Renewable Carbon Fibers Market
Fibers
Thermoformed Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Dry-Molded Fibre Market
Fibers
Viscose Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Carbon Fiber Tapes Market
Fibers
Global Bicomponent Fiber Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Fiber Intermediates Market