
 Aramid Paper Market | 2026-2036
Aramid Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Paper Market Analysis
Glass-mat thermoplastics in electrical insulation is consolidating share as OEMs seek thinner, thermally stable barrier layers for high-voltage systems. Teijin leverages its para-aramid polymerization expertise to sustain premium positioning in aerospace-grade rolls. DuPont anchors North American supply through backward integration into meta-aramid fiber spinning. Yantai Tayho Advanced Materials competes on cost-adjusted sheet formats for domestic electronics laminators.
Aramid paper consists of fibrillated aromatic polyamide fibers bonded into nonwoven sheets with dielectric strengths exceeding 15 kV/mm and continuous operating temperatures above 220°C, serving primarily as thermal-electrical barriers in compact energy systems. Electrical insulation leads volume absorption as transformer OEMs and battery pack assemblers specify thinner, higher-temperature-rated barriers. Aerospace Components commands margin concentration due to lot-traceability requirements and AS9100 certification overhead, while Composites in structural laminates extends fastest from wind blade root inserts and pressure vessel wraps.
China's SAMR enforces GB standards for flame propagation in rail and electrical enclosures, filtering import access to certified suppliers. The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants redirect formulation demand toward inherently non-flammable aramid substrates. Japan's METI circularity guidelines for industrial materials add recovery-protocol requirements to supplier qualification. Stakeholders must monitor divergence between Asian performance-test protocols and European chemical-registration thresholds when qualifying new paper grades for cross-border programs.
Market Dynamics
Aramid paper demand is bifurcating between high-performance aerospace specifications and cost-optimized formats for mass-market electrical insulation, with GB standard compliance in China acting as the primary gatekeeper for supplier qualification.
Growth Catalysts
- Electric vehicle battery thermal barriers:Cell-to-pack architectures require thinner dielectric separators rated above 220°C continuous operation. Battery assemblers in Shenzhen and Yantai corridors specify certified aramid substrates for module isolation.
- EU F-Gas Regulation:Halogenated flame retardant phase-outs redirect transformer OEMs toward inherently non-flammable aromatic polyamide barriers. REACH restrictions accelerate substitution timelines for incumbent insulation materials.
- Wind blade root inserts:Pressure vessel wraps and structural laminate applications extend para-aramid consumption beyond traditional electrical markets. Turbine manufacturers specify lot-traceable rolls for load-bearing composite nodes.
Market Restraints
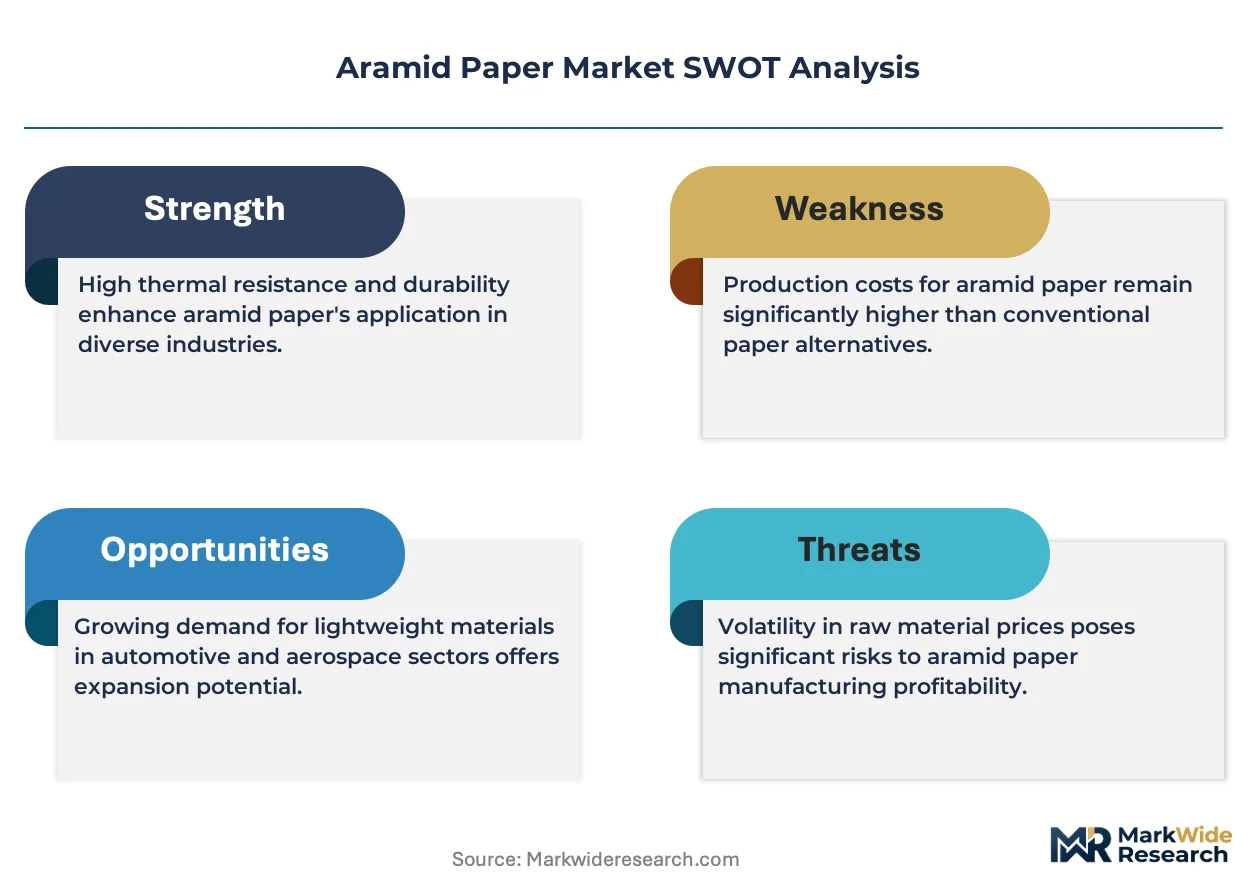
- Meta-aramid fiber feedstock concentration:Polymerization capacity clusters in East Asian industrial corridors, exposing non-integrated converters to supply interruption risks during raw material allocation cycles.
- Para-aramid fibrillation energy intensity:High-pressure refining and wet-laid sheet formation require substantial thermal input, compressing margins when energy tariffs spike in manufacturing zones.
- Glass-mat thermoplastic substitution:Thinner GMT barriers with comparable dielectric performance capture share in cost-sensitive transformer segments, particularly in domestic Chinese supply chains.
Strategic Opportunities
- Solid-state battery commercialization:Next-generation cell architectures demand higher thermal runaway resistance. Solid-state electrolyte interfaces require aramid separators with modified surface chemistry for ionic conductivity.
- India electrical infrastructure buildout:Grid modernization and renewable integration projects create demand for high-temperature transformer insulation. BIS certification pathways for flame-retardant materials remain underpenetrated by qualified suppliers.
- Japan METI circularity protocols:Industrial material recovery mandates incentivize closed-loop fibrillated fiber collection. Suppliers establishing take-back infrastructure gain preferred-provider status with Japanese electrical equipment OEMs.
Industry Challenges
- AS9100 aerospace certification timelines:Lot traceability and statistical process control documentation extend qualification cycles to 18-24 months for new paper grades, delaying revenue recognition from defense and satellite programs.
- Cross-border protocol divergence:GB flame propagation test methods differ from IEC thermal endurance standards, forcing dual qualification investments for suppliers serving both Chinese and European transformer markets.
- Specialized wet-lay equipment scarcity:Nonwoven sheet formation lines capable of sub-50 gsm caliper control require capital commitments exceeding mid-tier converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Paper Market |
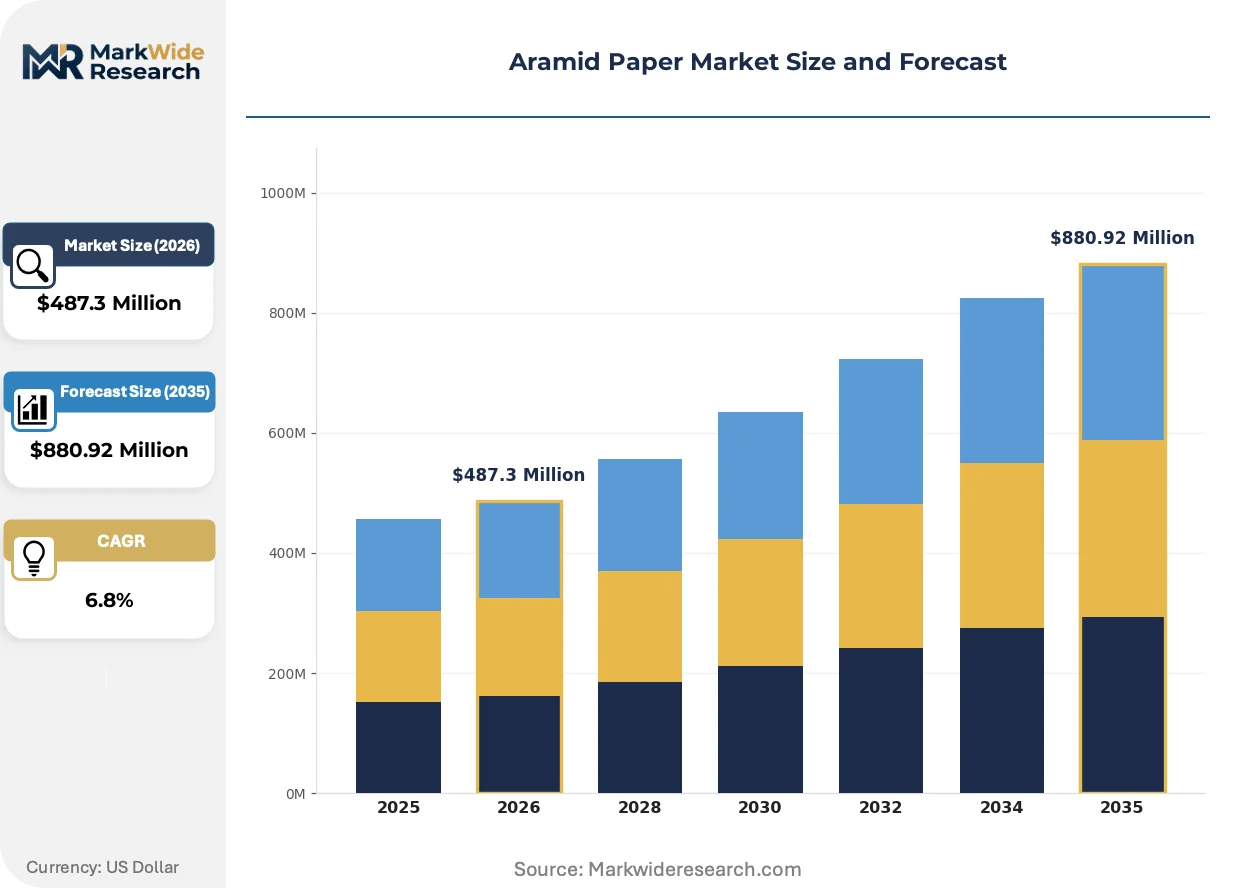
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Insulation, High-Temperature Apparel, Composites, Aerospace Components End User: Aerospace, Automotive, Electronics, Telecommunications Form: Rolls, Sheets, Laminates, Coatings Application: Flame Resistance, Insulation, Reinforcement, Filtration |
| Companies Covered | Shenzhen LongPont, SRO, Teijin, E.I. Du Pont de Nemours, Teijin Aramid, DuPont, X-FIPER, Yantai Tayho Advanced Materials, Yantai Tayho Advanced, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Paper Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are compressing traditional insulation supply chains while opening specification windows for engineered aromatic polyamide formats.
Calendered ultra-thin aramid sheets are modularizing barrier layer architectures in high-voltage battery packs. Cell manufacturers specify 25-40 gsm substrates that integrate thermal protection with dielectric isolation in single-ply configurations. This format consolidation eliminates separate mica-polymer laminate stacks, reducing pack mass and assembly labor content.
REACH restrictions on halogenated flame retardants are eliminating incumbent insulation chemistries from European electrical equipment. Transformer OEMs and rail enclosure fabricators now mandate inherently non-flammable substrates to avoid substance registration costs and supply discontinuity risks. German and French rail procurement specifications explicitly favor aromatic polyamide papers for traction motor insulation and cable wrapping applications.
Direct mill relationships are displacing distributor intermediaries in large-format roll procurement. Tier-one battery pack assemblers and wind turbine manufacturers negotiate annual volume contracts with fibrillated fiber producers for certified substrate supply. This channel compression is most pronounced in the Yantai industrial corridor, where domestic laminators source meta-aramid sheets through captive tolling arrangements rather than merchant distribution networks.
Aramid Paper Market Segmentation
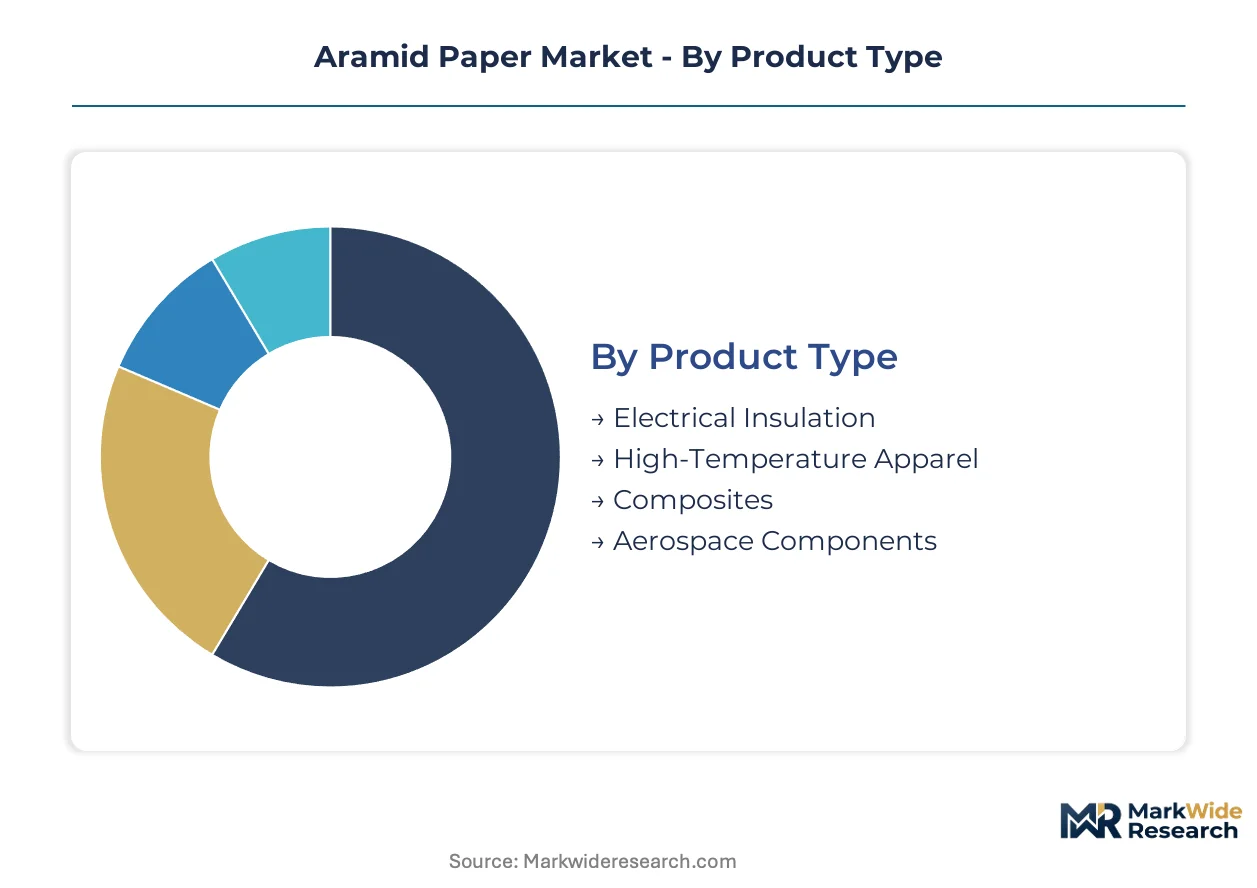
Aramid paper specifications diverge sharply across end-use environments, from aerospace lot-traceability mandates to cost-optimized electrical barrier formats. Understanding these segment boundaries clarifies where fibrillated fiber producers must qualify distinct substrate grades versus standardize production runs.
Product Type:
Replacement cycles for legacy insulation materials are shortening as thermal runaway risks in compact energy systems force specification upgrades toward aromatic polyamide barriers.
- Electrical Insulation:Fibrillated meta-aramid sheets with dielectric strengths exceeding 15 kV/mm serve as thermal-electrical barriers in transformer windings and battery pack separators. Demand concentrates in Shenzhen and Yantai manufacturing corridors where EV battery assemblers specify certified substrates for module isolation.
- Composites:Para-aramid paper reinforces structural laminates for wind blade root inserts and pressure vessel wraps through controlled caliper wet-laid formation. Turbine manufacturers in Northern Europe and China specify lot-traceable rolls for load-bearing composite nodes.
- High-Temperature Apparel:Heat-resistant nonwoven layers protect industrial workers in foundries and emergency response scenarios.
- Aerospace Components:AS9100-certified rolls with statistical process control documentation serve satellite and defense programs.
Electrical Insulation sits at the top of the volume ranking, with Composites climbing the fastest.
End User:
Customer procurement scale determines whether aramid paper moves through direct mill relationships or distributor intermediaries.
- Electronics:Laminators and battery pack assemblers source ultra-thin 25-40 gsm sheets for high-voltage barrier integration. Japanese electrical equipment OEMs now require METI-aligned circularity protocols from suppliers.
- Automotive:Cell-to-pack architectures demand thinner dielectric separators rated above 220°C continuous operation. OEMs in Germany and South Korea negotiate annual volume contracts for certified substrate supply.
- Aerospace:Defense and satellite programs impose 18-24 month qualification cycles for new paper grades.
- Telecommunications:Cable wrapping and enclosure insulation applications favor inherently non-flammable substrates under EU F-Gas Regulation.
Electronics commands the steepest expansion trajectory as battery thermal barriers multiply specification requirements.
Form:
Physical format dictates manufacturing equipment requirements and downstream processing compatibility.
- Rolls:Large-format continuous substrates enable automated winding operations in transformer and cable manufacturing. Direct mill relationships are displacing distributor channels for certified roll supply.
- Sheets:Cut-to-size formats serve laminators and small-batch composite fabricators with tighter inventory management.
- Laminates:Pre-bonded multi-layer structures reduce assembly labor in electrical equipment production.
- Coatings:Surface-modified substrates for solid-state battery separators with tailored ionic conductivity.
Rolls dominate current procurement volumes, with Coatings gaining share fastest from next-generation cell architecture demands.
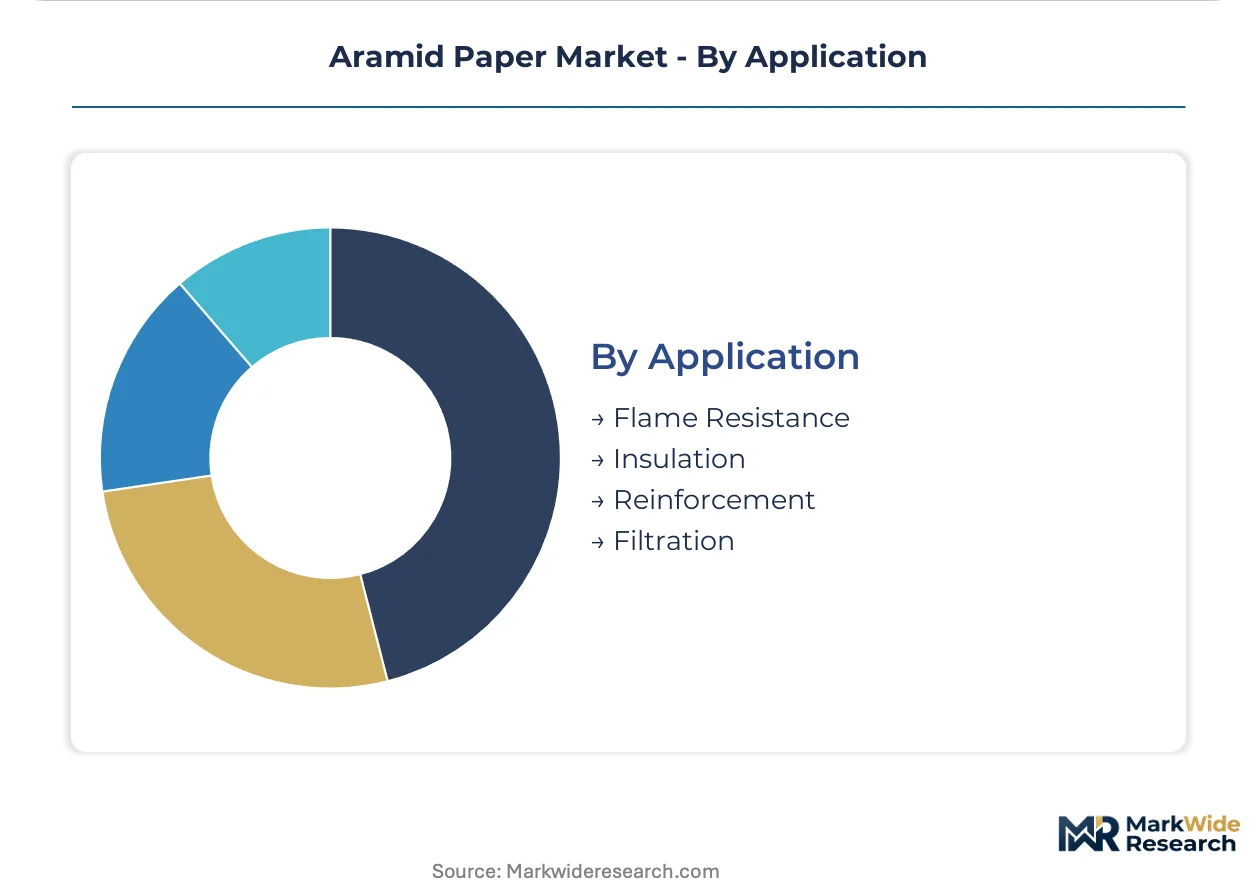
Application:
Functional performance requirements segment the market between inherent material properties and engineered surface characteristics.
- Insulation:Dielectric and thermal barrier functions in electrical equipment and energy storage systems. GB standards in China and IEC thermal endurance standards in Europe create dual qualification requirements for cross-border suppliers.
- Flame Resistance:Inherently non-flammable aromatic polyamide chemistry eliminates halogenated flame retardant dependencies under REACH restrictions.
- Reinforcement:Structural fiber distribution in composite matrices for load-bearing applications.
- Filtration:High-temperature particulate capture in industrial process streams.
Insulation leads by volume, with Flame Resistance expanding most quickly from regulatory chemistry phase-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yantai-Shenzhen industrial corridor concentrates the world's densest fibrillated aramid fiber production, with Chinese converters supplying certified substrates to battery pack assemblers and transformer OEMs across three continents.
China
GB standards enforced by SAMR filter import access for flame-retardant electrical enclosures, compelling foreign suppliers to achieve dual certification for rail and EV battery applications. The Yantai industrial corridor hosts integrated meta-aramid polymerization and sheet formation capacity serving domestic laminators through captive tolling arrangements. Shenzhen battery assemblers specify 25-40 gsm caliper substrates for cell-to-pack thermal barriers.
United States
Transformer OEMs and aerospace programs drive consumption of AS9100-certified rolls with statistical process control documentation. EPA and OSHA regulations on industrial chemical exposure reinforce procurement of inherently non-flammable barriers over halogenated alternatives. The Southeast manufacturing belt, particularly around North Carolina and Tennessee, concentrates electrical equipment fabrication requiring high-temperature insulation.
Germany
The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants redirect rail and traction motor insulation demand toward aromatic polyamide substrates. German turbine manufacturers specify lot-traceable para-aramid rolls for wind blade root inserts. The Ruhr industrial region and Bavarian manufacturing zones host composite fabricators integrating fibrillated sheets into pressure vessel wraps.
Japan
METI circularity guidelines for industrial materials add recovery-protocol requirements to supplier qualification, favoring producers with closed-loop fiber collection infrastructure. Electrical equipment OEMs in the Kanto and Kansai regions mandate METI-aligned sustainability documentation for aramid paper procurement. Nagoya-based automotive suppliers source ultra-thin separators for solid-state battery development programs.
India
Grid modernization and renewable integration projects create demand for high-temperature transformer insulation as BIS certification pathways for flame-retardant materials remain underpenetrated. Maharashtra and Gujarat industrial corridors concentrate electrical infrastructure manufacturing. Domestic laminators currently rely on imported meta-aramid sheets pending localized fibrillation capacity commissioning.
Aramid Paper Market Vendor Landscape
Global majors compete with regional champions across certification tiers and supply chain integration levels. The vendor base stratifies between aerospace-grade specialists with AS9100 documentation and cost-optimized sheet converters serving mass-market electrical insulation. Three archetypes dominate: backward-integrated polymer producers controlling fiber spinning through sheet formation, tolling specialists leveraging regional wet-lay equipment access, and composite integrators specifying lot-traceable rolls for structural applications. Capacity expansion and strategic tolling partnerships represent the dominant competitive moves.
Among East Asian integrated producers, Teijin and Yantai Tayho Advanced Materials occupy distinct positions on the premium-versus-cost spectrum. Teijin exemplifies the aerospace-certified archetype with para-aramid polymerization expertise sustaining premium positioning in satellite and defense programs. Yantai Tayho Advanced Materials represents the cost-adjusted regional champion competing on sheet format flexibility for domestic electronics laminators. DuPont anchors North American supply through in-house meta-aramid fiber spinning capacity, serving transformer OEMs with backward-integrated substrate production.
| Leading Market Players |
|---|
| Shenzhen LongPont |
| SRO |
| Teijin |
| E.I. Du Pont de Nemours |
| Teijin Aramid |
| DuPont |
| X-FIPER |
| Yantai Tayho Advanced Materials |
| Yantai Tayho Advanced |
| Others |
Supply Flow & Price Mechanics
Meta-aramid fiber feedstock costs cascade through three pricing tiers as polymerization capacity in Yantai and Shenzhen corridors concentrates supply control among integrated producers. Energy-intensive fibrillation and wet-laid sheet formation compress margins for non-integrated converters when regional electricity tariffs spike, forcing tiered pricing separation between AS9100-certified aerospace grades and cost-optimized electrical insulation formats.
Pricing Analysis
Input-cost pass-through from para-aramid polymerization feeds a three-tier pricing structure across premium aerospace-certified, standard industrial-grade, and economy electrical barrier levels. Price differentiation rests on AS9100 certification overhead and lot-traceability documentation versus volume-scale sheet formats. Cost compression in economy tiers is intensifying because glass-mat thermoplastic substitutes capture transformer OEM share. Battery pack assemblers in East Asian manufacturing clusters show least price sensitivity due to thermal runaway liability exposure, while domestic Chinese laminators exhibit highest sensitivity to per-kilogram sheet pricing.
Supply Chain Analysis
Single-source vulnerability sits with meta-aramid polymerization capacity concentrated in China, Japan, and the United States. Raw material dependencies draw from aromatic polyamide fiber spinning, high-pressure refining equipment, and specialized wet-lay formation lines. Tariff exposure on fibrillated fiber imports into the European Union under REACH compliance timelines presents structural risk. Distribution runs through direct mill relationships for tier-one battery and wind turbine OEMs, with distributor intermediaries serving smaller composite fabricators and electrical equipment laminators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in solid-state battery separator coatings and India electrical infrastructure penetration, where premium-tier thermal barrier specifications outpace commodity sheet pricing erosion.
For Market Incumbents: Extend aerospace certification documentation into solid-state battery separator coatings before qualification cycles lengthen. Add captive fibrillation capacity in the Yantai corridor to offset raw material allocation risk from polymerization suppliers. Defend against glass-mat thermoplastic substitution by emphasizing 220°C continuous operation ratings in transformer OEM specifications. For New Entrants and Emerging Players: Enter via India BIS certification pathways for flame-retardant transformer insulation, where qualified supplier penetration remains underdeveloped. Target Maharashtra and Gujarat industrial corridors with tolling partnerships for meta-aramid sheet conversion. Pursue joint qualification programs with European rail OEMs seeking REACH-compliant halogen-free barrier substrates. For Investors and Strategic Acquirers: Consolidation pressure builds where wet-lay equipment scarcity constrains mid-tier converter expansion. Five-to-ten-year viability favors backward-integrated producers controlling polymerization through sheet formation. Target acquisition archetype: regional champions with GB-standard certification and captive tolling relationships in Shenzhen-Yantai corridors. Signal to monitor: solid-state battery separator coating qualification announcements from Japanese automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Spinning | Captive meta-aramid supply insulates converters from Yantai corridor allocation cycles. |
| AS9100 Certification Investment | Aerospace documentation opens defense and satellite program revenue streams with 18-24 month qualification. |
| GB Standard Dual Qualification | SAMR compliance enables access to Shenzhen battery assembler and domestic rail procurement channels. |
| Closed-Loop Fiber Collection Infrastructure | METI-aligned recovery protocols secure preferred-provider status with Japanese electrical equipment OEMs. |
| Solid-State Separator Coating Development | Surface-modified substrates address next-generation cell architecture thermal runaway resistance requirements. |
Methodological Framework
Direct dialogue with fibrillated fiber plant managers, transformer OEM procurement leads, battery pack assembler technical directors, and composite fabricator R&D heads grounded qualitative assessment. Secondary validation drew from customs trade data, SEC 10-K filings of listed materials producers, SAMR GB standard enforcement notices, and ECHA REACH restriction updates. Bottom-up volume estimates from end-use application specifications triangulated against top-down polymerization capacity assessments across the analysis window.
Segment-level projections across product type, end user, physical form, and application incorporated dielectric strength requirements, thermal endurance test protocols, and regional regulatory compliance tiers. CAGRs derived from fitted growth curves applied to qualified substrate demand in EV battery thermal barriers and wind blade root inserts. Industry-specific inputs included cell-to-pack architecture adoption rates and solid-state battery commercialization timelines.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time polymerization capacity utilization data introduce uncertainty bands around supply-side constraints. Forecasts reflect assumptions on GB standard enforcement consistency and EU F-Gas Regulation phase-out adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Metallized Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Hardwood Pulp Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Global Copier Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Pulp Market
Paper Products
North America Coated Paper Market
Paper Products
North America Specialty Paper Market
Paper Products
Pulp and Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Global Pulp and Paper Machinery Market