
 Micro-Fibrillated Cellulose Market | 2026-2036
Micro-Fibrillated Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Fibrillated Cellulose Market Outlook
Pharmaceutical-grade purity specifications is collapsing the gap between commodity cellulose and high-value functional additives. Stora Enso leverages its Nordic pulp infrastructure to secure consistent feedstock quality for MFC extraction. Borregaard differentiates through specialized lignin-cellulose coprocessing capabilities that enhance fibril dispersion. Daicel FineChem dominates Asian pharmaceutical-grade supply chains with precision-controlled fibrillation technology.
Micro-fibrillated cellulose consists of cellulose fibers mechanically or chemically disintegrated to diameters below 100 nanometers, yielding high aspect-ratio structures with tensile strengths exceeding 1 GPa and surface areas surpassing 100 m²/g; manufacturers deploy high-pressure homogenization or grinding to liberate entangled fibrils from wood pulp, cotton linters, or bacterial cellulose pellicles for use as rheology modifiers, film formers, and reinforcement phases in composite matrices. Wood-based MFC anchors volume production due to established forestry supply chains and lower raw material costs, while bacteria-based variants command premium positioning in biomedical and high-performance coating segments where ultrafine fibril networks and exceptional crystallinity justify specialized cultivation protocols. Powder delivery modes sustain the largest share of commercial transactions, though gel suspensions are gaining traction in food and personal care formulations where ready-to-disperse functionality reduces processing steps.
EPA industrial chemical oversight and FDA food additive regulations in the United States, alongside REACH substance registration and EFSA food contact material assessments in Europe, collectively elevate barrier-to-entry standards for new MFC suppliers while channeling R&D investment toward toxicological clearance and compositional consistency. The EU Green Deal's biobased material procurement directives and emerging CSRD sustainability disclosure requirements are redirecting packaging sector purchasing criteria toward traceable, low-carbon cellulose feedstocks. Stakeholders must monitor evolving regulatory convergence between pharmaceutical excipient monographs and food-grade cellulose specifications, as overlapping purity demands could reshape competitive positioning across application boundaries.
Market Dynamics
Pharmaceutical-grade purity specifications are collapsing the boundary between commodity cellulose and high-value functional additives, forcing producers to reconfigure extraction protocols and quality assurance systems across wood pulp, cotton linter, and bacterial cellulose feedstocks.
Growth Catalysts
- REACH substance registration:European chemical safety protocols are channeling R&D investment toward toxicological clearance and compositional consistency, elevating barrier-to-entry standards that favor established MFC suppliers with documented fibril characterization.
- Food Industry clean-label adoption:North American and European food manufacturers are deploying MFC as a stabilizer and thickener in sauces, dressings, and dairy alternatives, displacing synthetic hydrocolloids with plant-derived rheology modifiers.
- German papermaking clusters:Concentrated biorefinery infrastructure around Hamburg and the Ruhr region supports scaled MFC production for barrier coatings and specialty packaging applications.
Market Restraints
- High-pressure homogenization energy intensity:Mechanical fibrillation consumes substantial electricity per kilogram of MFC output, compressing margins when energy prices spike in Nordic pulp-producing regions.
- Feedstock quality variability:Wood pulp lignin content fluctuations disrupt fibril dispersion consistency, requiring pretreatment investments that commodity cellulose producers avoid.
- Bacterial cellulose cultivation costs:Specialized fermentation protocols for biomedical-grade MFC demand sterile facilities and extended growth cycles that synthetic polymer alternatives bypass.
Strategic Opportunities
- EU Green Deal biobased procurement:Packaging sector purchasing criteria are redirecting toward traceable, low-carbon cellulose feedstocks with verified lifecycle emissions documentation.
- Personal care gel suspensions:Ready-to-disperse MFC formats are penetrating cosmetic and skincare formulations, eliminating powder hydration steps for contract manufacturers.
- Pharmaceutical excipient monograph convergence:Overlapping purity demands between food-grade and pharmaceutical-grade cellulose specifications could unlock cross-application supply efficiencies for qualified producers.
Industry Challenges
- Nanoscale characterization expertise scarcity:Quality control laboratories lack standardized protocols for measuring fibril diameter distributions below 100 nanometers, creating batch release bottlenecks.
- Legacy paper mill retrofit complexity:Conventional pulp facilities require substantial capital redeployment to install grinding and homogenization equipment capable of MFC-grade fibril liberation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Fibrillated Cellulose Market |
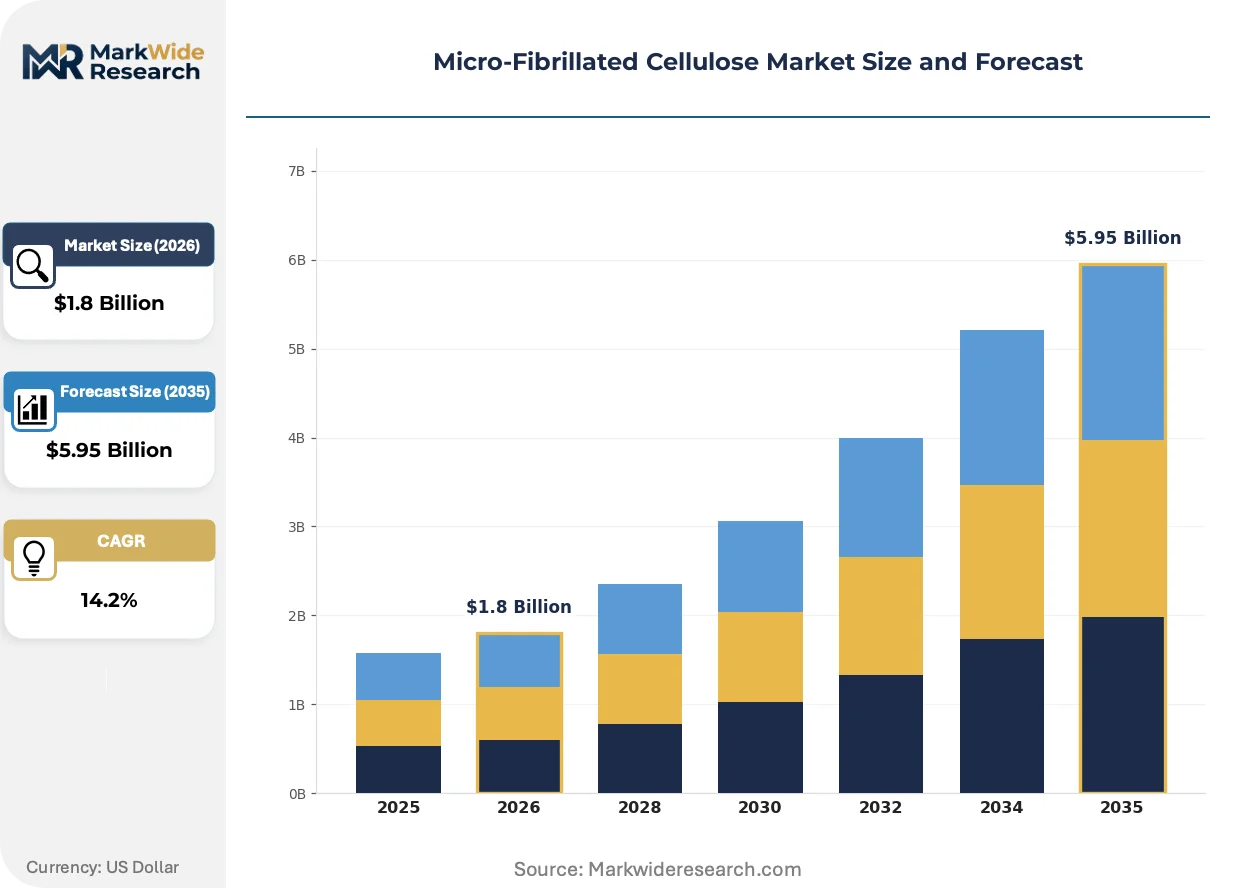
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood-Based, Cotton-Based, Bacteria-Based, Others Application: Food Additives, Pharmaceuticals, Coatings, Personal Care End User: Food Industry, Cosmetic Industry, Pharmaceutical Industry, Packaging Sector Delivery Mode: Powder, Suspension, Gel, Emulsion |
| Companies Covered | Norske Skog, FiberLean Technologies, Stora Enso, Weidmann Fiber Technology, Daicel FineChem, Borregaard, SAPPI, Zelfo Technology, Nippon Paper Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Fibrillated Cellulose Market Strategic Shifts
Enzymatic pretreatment protocols are accelerating fibril liberation while reducing mechanical energy inputs, reshaping process economics for producers seeking to decouple MFC quality from homogenization intensity.
Surface-modified MFC variants with tailored hydrophobicity profiles are displacing petroleum-derived barrier coatings in molded fiber packaging, with food service and fresh produce segments adopting these cellulose-based oil and moisture resistant layers at accelerating trial-to-commercial conversion rates.
EFSA food contact material assessments are tightening migration limits for cellulose-derived additives, compelling European suppliers to invest in contaminant screening and supply chain traceability systems that document wood sourcing, pulping chemistry, and fibrillation conditions from forest to finished additive.
Direct mill integration contracts are compressing distribution layers, with packaging converters in Germany, Finland, and Sweden securing dedicated MFC supply lines from adjacent pulp facilities, bypassing merchant distributors and capturing logistics cost advantages while locking in volume commitments.
Micro-Fibrillated Cellulose Market Segmentation
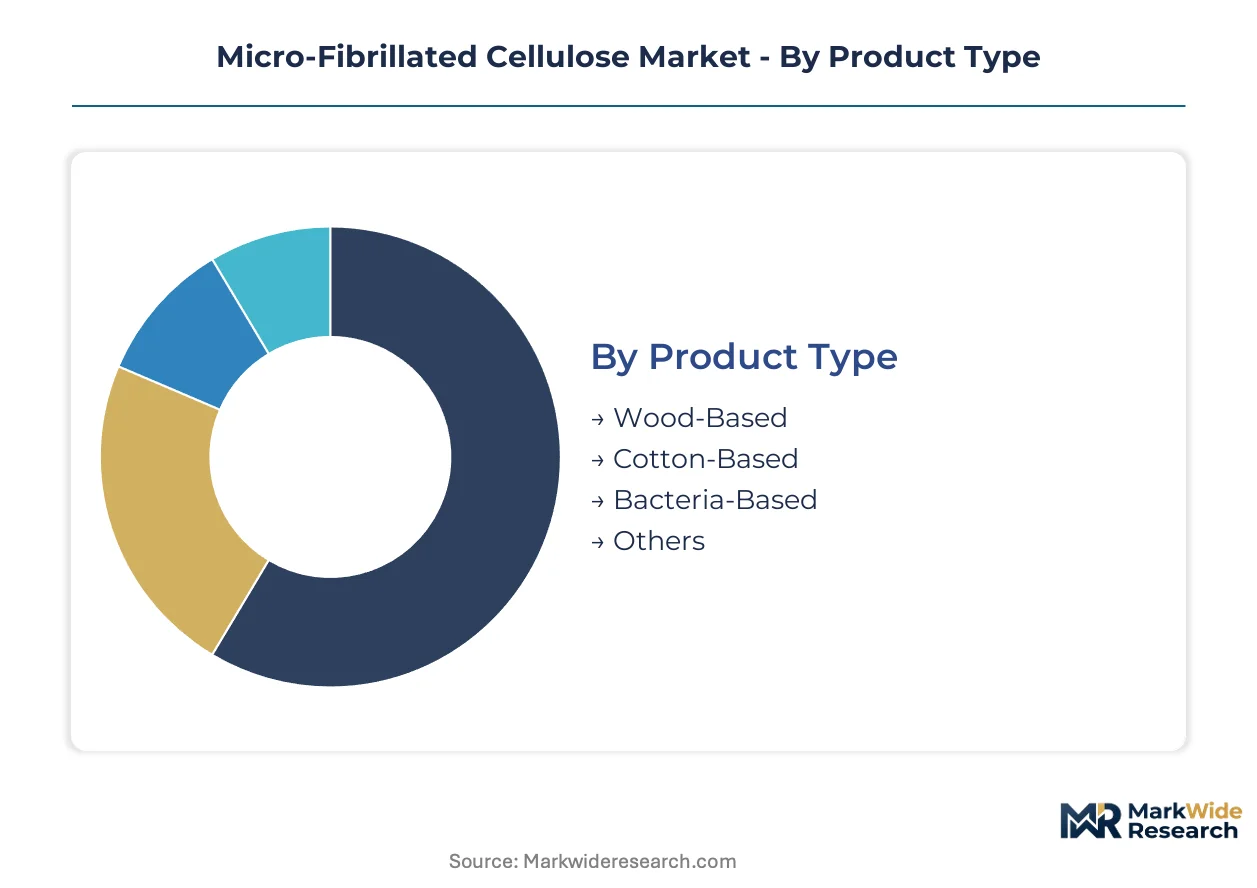
Segmentation in the Micro-Fibrillated Cellulose Market reveals how feedstock chemistry and delivery format determine substitution vulnerability against synthetic hydrocolloids and petroleum-derived rheology modifiers. Each dimension carries distinct margin profiles and regulatory clearance requirements that reshape supplier positioning.
Product Type:
Substitution pressure from modified starches and synthetic polymers varies sharply across feedstock origins, with wood-derived grades facing the steepest price competition while bacteria-based variants defend premium positioning through purity differentiation.
- Wood-Based:Mechanical fibrillation of bleached kraft pulp yields fibril diameters of 20-100 nanometers with lignin contents below 2 percent. Demand concentrates in German packaging clusters where biorefinery infrastructure supports barrier coating formulations for molded fiber food service items. Stora Enso's Nordic pulp operations anchor consistent feedstock supply for this segment.
- Bacteria-Based:Gluconacetobacter xylinus fermentation produces ultrafine fibril networks with crystallinity exceeding 80 percent and purity profiles meeting pharmaceutical excipient monographs. Biomedical coating applications in Japan and South Korea absorb output from Daicel FineChem's precision-controlled cultivation facilities despite synthetic polymer price undercutting.
- Cotton-Based:Linters from textile processing deliver high alpha-cellulose content above 95 percent for premium personal care suspensions.
- Others:Agricultural residue streams including wheat straw and sugarcane bagasse emerge as experimental feedstocks for circular economy positioning.
Wood-Based anchors the volume base while Bacteria-Based gains share at the steepest rate.
Application:
Cost tier stratification separates commodity rheology modification from high-value functional performance, with coating and pharmaceutical applications commanding 3-5x premiums over food additive volumes.
- Food Additives:Clean-label stabilizer deployment in sauces, dressings, and dairy alternatives displaces xanthan gum and modified starches in North American and European formulations. FDA food-contact guidance and EFSA migration limit compliance dominate procurement criteria.
- Pharmaceuticals:Tablet binder and controlled-release matrix applications demand endotoxin levels below 20 EU/g and documented fibril aspect ratio consistency. REACH substance registration and pharmaceutical excipient monograph convergence elevate barrier-to-entry for new suppliers.
- Coatings:Surface-modified variants with tailored hydrophobicity profiles replace petroleum-derived barrier layers in molded fiber packaging.
- Personal Care:Gel suspensions penetrate cosmetic formulations through ready-to-disperse functionality that eliminates powder hydration steps.
Food Additives generates the largest transaction volumes while Pharmaceuticals delivers the highest margin realization per kilogram.
End User:
Customer type concentration shapes contract structure, with packaging sector direct mill integration compressing distribution layers while pharmaceutical buyers demand multi-year supply agreements with documented batch traceability.
- Food Industry:Clean-label adoption across sauce, dressing, and dairy alternative manufacturers in Germany, France, and the United States drives specification tightening around fibril diameter distribution consistency.
- Pharmaceutical Industry:Excipient qualification protocols require toxicological clearance documentation and compositional consistency validation that commodity cellulose producers avoid.
- Cosmetic Industry:Skincare formulation houses in Japan and South Korea prioritize gel suspension delivery modes for manufacturing efficiency.
- Packaging Sector:German converters secure dedicated MFC supply lines from adjacent pulp facilities, bypassing merchant distributors.
Packaging Sector concentrates procurement scale while Pharmaceutical Industry deepens quality assurance requirements fastest.
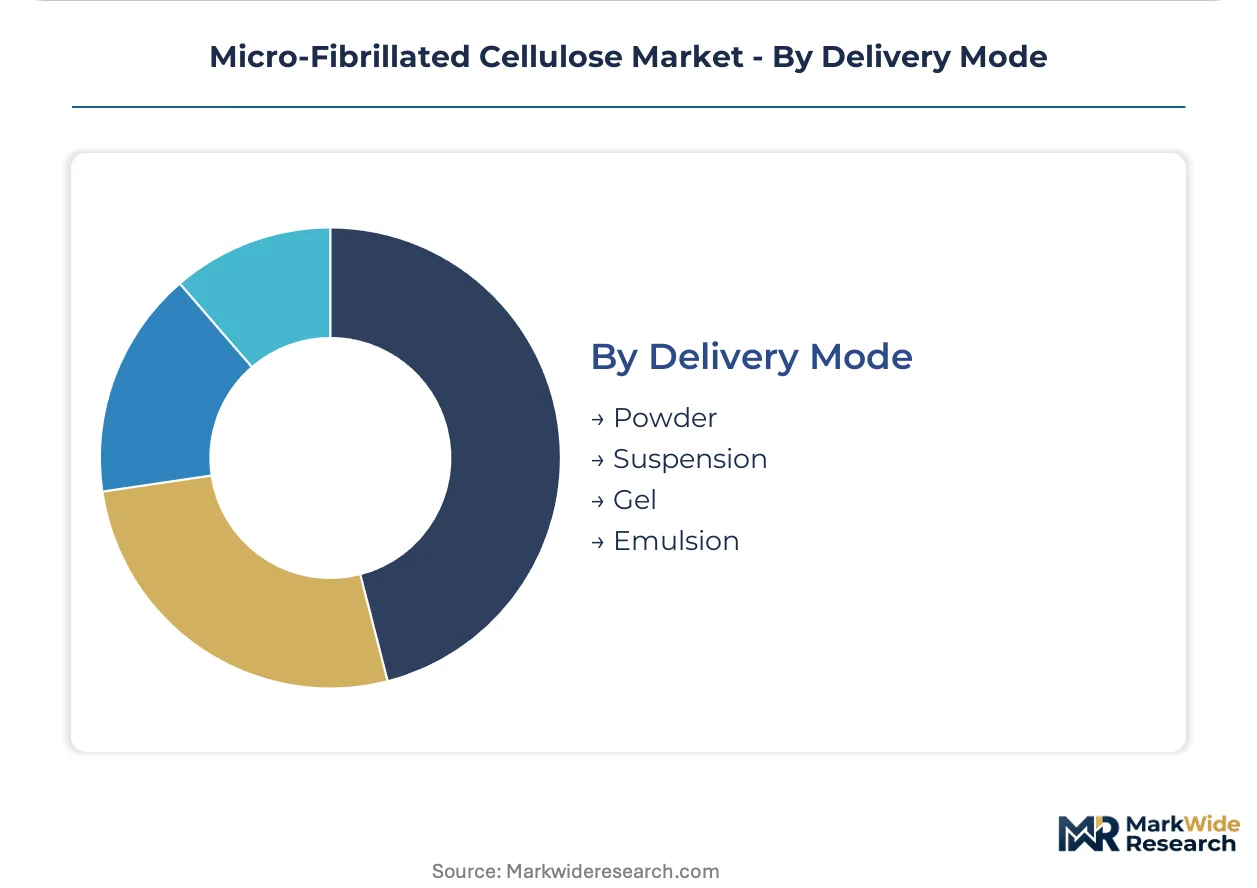
Delivery Mode:
Supply concentration in powder formats reflects legacy infrastructure, while gel and suspension investments target personal care and food processing customer segments seeking processing step elimination.
- Powder:Spray-dried formats with moisture content below 5 percent dominate commercial transactions through established logistics infrastructure and extended shelf stability. Nordic pulp producers leverage existing drying capacity.
- Gel:Ready-to-disperse suspensions at 2-10 percent solids content eliminate hydration steps for cosmetic contract manufacturers and food processing facilities.
- Suspension:Liquid concentrates at intermediate solids levels serve coating applicators with dedicated mixing equipment.
- Emulsion:Oil-phase dispersed formats address specialized barrier coating applications requiring uniform film formation.
Powder sustains the largest commercial share while Gel expands most quickly in personal care and food processing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German MFC exports supply Nordic packaging converters and Dutch barrier-coating specialists, establishing a westward trade corridor anchored by Ruhr-region biorefinery capacity.
Germany
Hamburg and Ruhr-region papermaking clusters drive MFC demand for molded fiber food-service packaging and specialty barrier coatings. REACH substance registration protocols enforce toxicological documentation standards that favor established suppliers with validated fibril characterization. Direct mill integration contracts between Ruhr biorefineries and adjacent packaging converters compress distribution layers and lock in volume commitments.
United States
Food Industry clean-label adoption accelerates MFC deployment as a stabilizer in sauces, dressings, and dairy alternatives across Midwest and Northeast processing facilities. FDA food-contact guidance and EPA industrial chemical oversight elevate purity benchmarks for cellulose-derived additives. Wisconsin and Maine pulp-producing regions host retrofit investments targeting MFC-grade fibril liberation from legacy paper mill infrastructure.
Japan
Pharmaceutical-grade MFC demand concentrates in tablet binder and controlled-release matrix applications serving domestic formulation houses. PMDA excipient qualification protocols and METI industrial standards enforce endotoxin thresholds below 20 EU/g. Daicel FineChem's precision-controlled cultivation facilities in Osaka and Tokyo metropolitan areas anchor biomedical-grade bacterial cellulose supply chains.
Sweden
Nordic pulp infrastructure supports consistent feedstock quality for MFC extraction targeting European packaging sector procurement. EU Green Deal biobased material directives redirect purchasing criteria toward traceable, low-carbon cellulose feedstocks with verified lifecycle emissions. Stora Enso's integrated forestry and fibrillation operations in Värmland and Norrland regions exemplify upstream control over wood-to-additive value chains.
South Korea
Cosmetic Industry gel suspension demand penetrates skincare formulation houses seeking ready-to-disperse MFC functionality. MFDS cosmetic ingredient regulations and national biopolymer R&D programs channel investment toward personal care delivery mode innovation. Busan-Ulsan chemical processing clusters host toll manufacturing partnerships connecting Japanese bacterial cellulose suppliers to domestic cosmetic contract manufacturers.
Micro-Fibrillated Cellulose Market Competitive Environment
Listed leaders compete with private specialists across feedstock control and fibrillation technology tiers, producing a bifurcated structure where pulp-integrated conglomerates face off against application-focused technology licensors. Tier-one positions concentrate among Nordic and Japanese entities with captive forestry or fermentation assets, while mid-scale European and North American players occupy technology-licensing niches. Two strategic archetypes dominate: upstream-integrated pulp producers leveraging feedstock quality consistency, and downstream-focused specialists monetizing surface-modification IP. Capacity expansion and direct mill integration contracts represent the dominant competitive moves reshaping supply relationships.
Within the upstream-integrated tier, Stora Enso and Nippon Paper Group exemplify archetypes combining Nordic or Japanese forestry assets with mechanical fibrillation capabilities. Borregaard occupies a distinct position among lignin-cellulose coprocessing specialists, representing the intersection of biorefinery diversification and high-value additive production. Daicel FineChem anchors the pharmaceutical-grade bacterial cellulose segment, exemplifying precision-controlled cultivation protocols that synthetic polymer alternatives cannot replicate.
| Leading Market Players |
|---|
| Norske Skog |
| FiberLean Technologies |
| Stora Enso |
| Weidmann Fiber Technology |
| Daicel FineChem |
| Borregaard |
| SAPPI |
| Zelfo Technology |
| Nippon Paper Group |
| Others |
Value Chain & Pricing Dynamics
Ruhr-region biorefinery scale economies compress unit fibrillation costs below Nordic pulp facility breakevens, concentrating supply-side pricing power among German integrated producers while forcing merchant suppliers toward gel-format differentiation to defend margin floors.
Pricing Analysis
Mechanical fibrillation technology gaps separate incumbent high-pressure homogenization pricing from emerging enzymatic-pretreatment cost structures, with next-generation bio-catalytic protocols promising 30-40 percent energy reduction. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade specifications anchors the dominant model, with endotoxin certification and REACH documentation driving 3-5x spreads between tiers. Cost compression in wood-based grades intensifies as modified starches undercut rheology-modifier positioning in sauce and dressing applications. Food Industry procurement teams exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize batch traceability over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade MFC procurement, with Japanese and German buyers maintaining 90-180 day safety inventories against bacterial cellulose cultivation cycle variability. Supply concentrates in Germany, Sweden, and Japan, with Nordic pulp infrastructure and Osaka-Tokyo fermentation clusters anchoring upstream capacity. Feedstock flows draw from bleached kraft pulp, cotton linters, and Gluconacetobacter xylinus cultivation media. Single-source vulnerability permeates pharmaceutical-grade bacterial cellulose, where Daicel FineChem's precision-controlled facilities command irreplaceable excipient qualification status. Distribution runs through direct mill integration contracts in German packaging corridors, bypassing merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-fibrillated cellulose sits in early-cycle expansion, with EU Green Deal biobased procurement directives accelerating packaging sector penetration ahead of synthetic barrier coating displacement.
For Market Incumbents: Fortify feedstock quality consistency through backward integration into Nordic forestry assets or lignin-cellulose coprocessing capabilities, defending against enzymatic-pretreatment entrants eroding mechanical fibrillation cost advantages. Prioritize pharmaceutical excipient monograph pre-qualification to capture cross-application supply efficiencies as food-grade and pharmaceutical-grade specifications converge. For New Entrants and Emerging Players: Anchor in personal care gel suspension formats where ready-to-disperse functionality eliminates powder hydration steps for cosmetic contract manufacturers, the most penetrable white-space segment. Target South Korean skincare formulation houses through Busan-Ulsan toll manufacturing partnerships, leveraging lower regulatory clearance barriers versus pharmaceutical qualification pathways. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bacterial cellulose cultivation specialists with validated endotoxin control and pharmaceutical excipient monograph status. Five-to-ten year viability hinges on substitution defense against synthetic polymer price undercutting in biomedical coatings. Watch enzymatic-pretreatment pilot scale-up announcements as inflection indicator for mechanical fibrillation margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Stora Enso's Nordic pulp operations secure consistent feedstock quality for MFC extraction. |
| Pharmaceutical Excipient Monograph Qualification | Daicel FineChem anchors biomedical-grade bacterial cellulose supply chains through PMDA validation. |
| Enzymatic Pretreatment Scale-Up | Borregaard's lignin-cellulose coprocessing capabilities reduce mechanical energy inputs per kilogram output. |
| Direct Mill Integration Contracts | German packaging converters bypass merchant distributors through Ruhr-region biorefinery supply lines. |
| Gel Suspension Format Expansion | Personal care delivery mode innovation eliminates powder hydration steps for cosmetic manufacturers. |
Study Parameters
A spread of perspectives from plant managers at Nordic pulp facilities, procurement leads at German packaging converters, pharmaceutical excipient qualification specialists, and cosmetic formulation R&D directors converged on the working assumptions. Primary interview insights combined with customs trade data, ECHA REACH registration databases, SEC 10-K filings from listed pulp producers, and EFSA food contact material assessment records. Bottom-up fibrillation capacity estimates and top-down end-use demand aggregation triangulated market sizing.
Segmentation dimensions modeled include feedstock origin, application tier, delivery mode format, and end-user industry vertical across the projection horizon. CAGRs derived from capacity expansion announcements, direct mill integration contract volumes, and substitution elasticity against synthetic hydrocolloids. Forecast inputs incorporated EU Green Deal biobased procurement directive implementation timelines and pharmaceutical excipient monograph convergence scenarios.
Material uncertainties — energy price volatility in mechanical fibrillation, bacterial cellulose cultivation contamination events, and EFSA migration limit revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about enzymatic pretreatment adoption curves and clean-label food additive penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Thermoformed Fiber Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Metal Fiber Felt Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Carbon Fiber Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
North America Nanofiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Viscose Filament Yarn Market
Fibers
PAN-Based Carbon Fibers Market