
 Carbon Fiber Wrap Market | 2026-2036
Carbon Fiber Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Wrap Market Analysis
China is rewriting capacity dynamics in carbon fiber wrap manufacturing as domestic precursor and weaving investments scale across Jiangsu and Shandong provinces. Toray Industries anchors premium aerospace-grade output through its proprietary polyacrylonitrile-to-fabric pipeline. SGL Carbon specializes in automotive structural reinforcement, leveraging its European carbon fiber heritage to serve BMW and Volkswagen programs. Hexcel Corporation dominates North American defense and aviation applications with qualified materials on multiple military platforms.
Carbon fiber wrap denotes a flexible composite sheet comprising unidirectional or woven carbon fiber filaments pre-impregnated with epoxy or thermoplastic resin matrices, typically ranging from 0.2 to 1.5 millimeters in thickness and engineered for tensile strengths exceeding 3,000 megapascals. The material functions primarily as a structural reinforcement layer bonded to concrete, steel, or polymer substrates to enhance load-bearing capacity without adding significant mass. Protective wraps command the deepest margin pools due to infrastructure lifecycle extension contracts and stringent performance warranties. Decorative segments face commoditization pressure as Chinese entrants flood automotive aftermarket channels with unbranded alternatives. OEM customer relationships sustain the longest contract visibility, though DIY enthusiasts represent the fastest-growing channel through marketplace expansion.
FAA airworthiness directives and EASA certification standards govern aerospace-grade wrap qualification, while OSHA workplace exposure limits and EPA volatile organic compound regulations constrain resin formulation chemistry in US manufacturing. Japan's METI industrial standards and China's GB composite material specifications further fragment compliance requirements for cross-border suppliers. Stakeholders must monitor evolving EU Green Deal embodied carbon thresholds, which threaten to recategorize conventional epoxy systems ahead of bio-based resin scale-up timelines.
Market Dynamics
Epoxy resin chemistry constraints under tightening EU Green Deal embodied carbon thresholds are forcing accelerated bio-based formulation development across the supply base, compressing conventional product lifecycles before next-generation alternatives achieve scale.
Growth Catalysts
- EU F-Gas Regulation compliance mandates:Aerospace maintenance programs across Germany and France require composite reinforcement solutions that eliminate high-global-warming-potential processing agents, pulling demand toward qualified carbon fiber wrap systems.
- Infrastructure lifecycle extension contracts:Bridge and tunnel rehabilitation authorities in Japan's metropolitan prefectures specify carbon fiber wrap for seismic retrofit applications, creating durable demand visibility through multi-year performance warranties.
- Automotive lightweighting imperatives:BMW and Volkswagen structural reinforcement programs in Bavaria and Lower Saxony integrate carbon fiber wrap into electric vehicle platform architectures to offset battery mass penalties.
Market Restraints
- Acrylonitrile precursor cost volatility:Polyacrylonitrile feedstock prices track propylene and ammonia commodity swings, compressing margin predictability for manufacturers without captive precursor supply.
- Japanese aerospace-grade supply concentration:Toray Industries and Mitsubishi Chemical Carbon Fiber dominate qualified defense and aviation material pools, creating single-source vulnerability for North American and European airframe integrators.
- Steel plate substitution in cost-sensitive infrastructure:Conventional bonded steel reinforcement retains preference in emerging-market civil engineering specifications where lifecycle cost analysis lacks enforcement.
Strategic Opportunities
- Underpenetrated US municipal water infrastructure:Aging concrete pressure pipe networks across California and Texas present structural strengthening applications where carbon fiber wrap outperforms dig-and-replace alternatives on disruption metrics.
- Wind turbine blade leading-edge protection:Offshore wind installations in the North Sea and Baltic Sea require erosion-resistant composite overlays that extend blade service intervals beyond current gelcoat limitations.
- Japan METI industrial standard alignment:Harmonized certification pathways for construction-grade composites reduce cross-border qualification friction for European and North American suppliers entering Japanese infrastructure markets.
Industry Challenges
- Specialized composite technician scarcity:Surface preparation, resin mixing, and vacuum-bag curing operations require skilled trades certification that outpaces vocational training program output in Germany and the United States.
- FAA and EASA concurrent qualification timelines:Aerospace-grade wrap approval demands parallel certification tracks that extend product development cycles to 18-36 months before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Wrap Market |
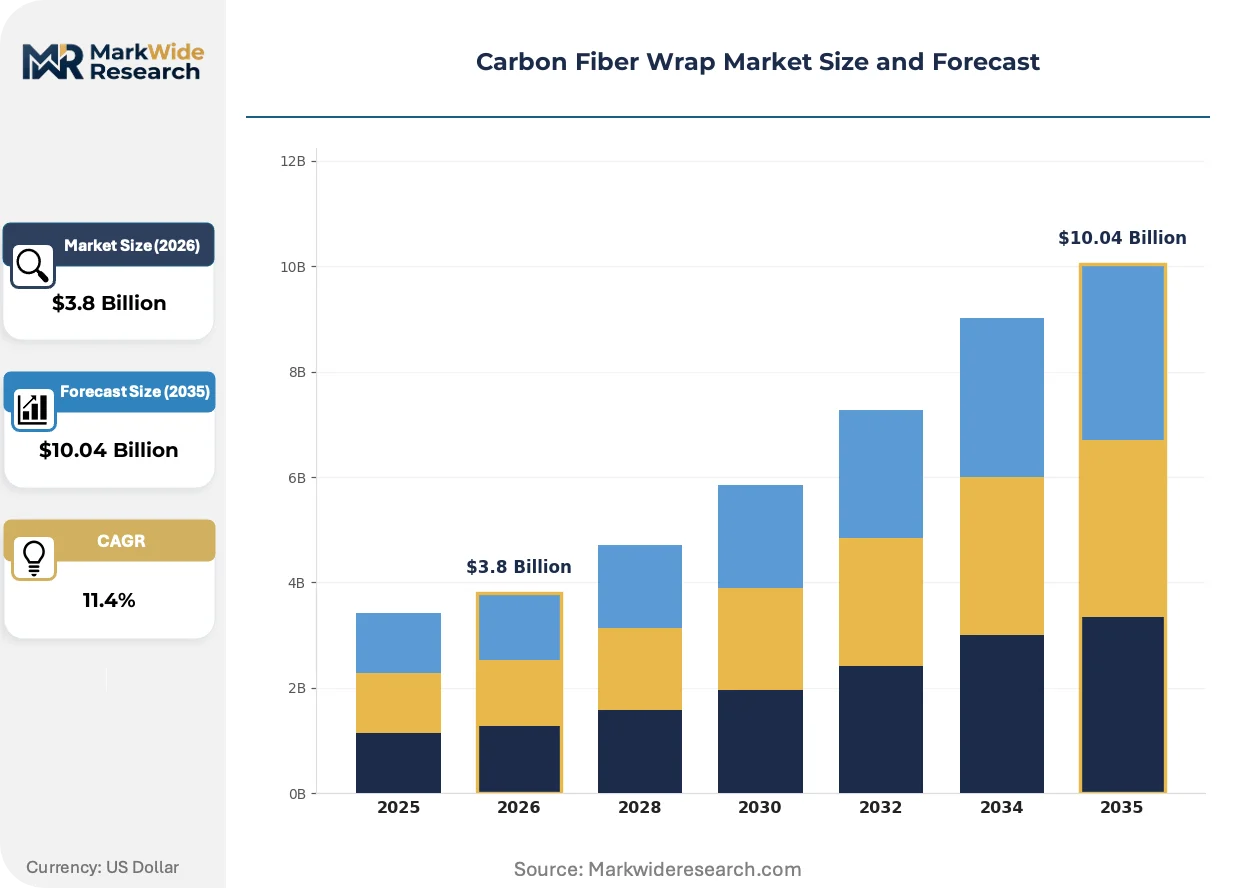
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Decorative, Protective, Automotive Application: Interior, Exterior, Sports Equipment, Industrial Components Customer Type: OEMs, Retail Consumers, Custom Builders, DIY Enthusiasts Distribution Channel: Online Retail, Specialty Shops, Distributors, Wholesale |
| Companies Covered | Hexcel Corporation, 3M, Toray Industries, DowAksa Advanced Composites, Zoltek, SGL Carbon, Teijin Limited, Formosa Plastics Corporation, Mitsubishi Chemical Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Wrap Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to compress conventional product architectures while opening substitution pathways for bio-based and thermoplastic alternatives.
Thermoplastic resin matrices are collapsing the processing cost differential between carbon fiber wrap and conventional thermoset systems. Automotive Tier-1 suppliers in Stuttgart and Wolfsburg are piloting polyamide and PEEK-based prepregs that enable sub-10-minute cycle times for structural reinforcement components. The compression of cure-cycle economics is displacing epoxy-dominated workflows in high-volume manufacturing environments.
REACH authorization requirements for bisphenol-A and epichlorohydrin derivatives are tightening formulation flexibility for European manufacturers. The ECHA sunset date mechanics are forcing accelerated substitution investments toward bio-epoxy feedstocks derived from lignin and plant-based phenolics. German automotive engineering corridors are responding with captive R&D programs to secure qualified material pipelines ahead of substance restriction enforcement.
Direct-to-installer digital distribution is fragmenting traditional distributor control over technical specification and pricing. Marketplace platforms serving DIY automotive enthusiasts and small-scale contractors in the United States are compressing information asymmetries that previously sustained regional distributor margin pools. The channel shift is most visible in California and Florida aftermarket automotive segments where application tutorial content drives self-selection behavior.
Carbon Fiber Wrap Market Segmentation
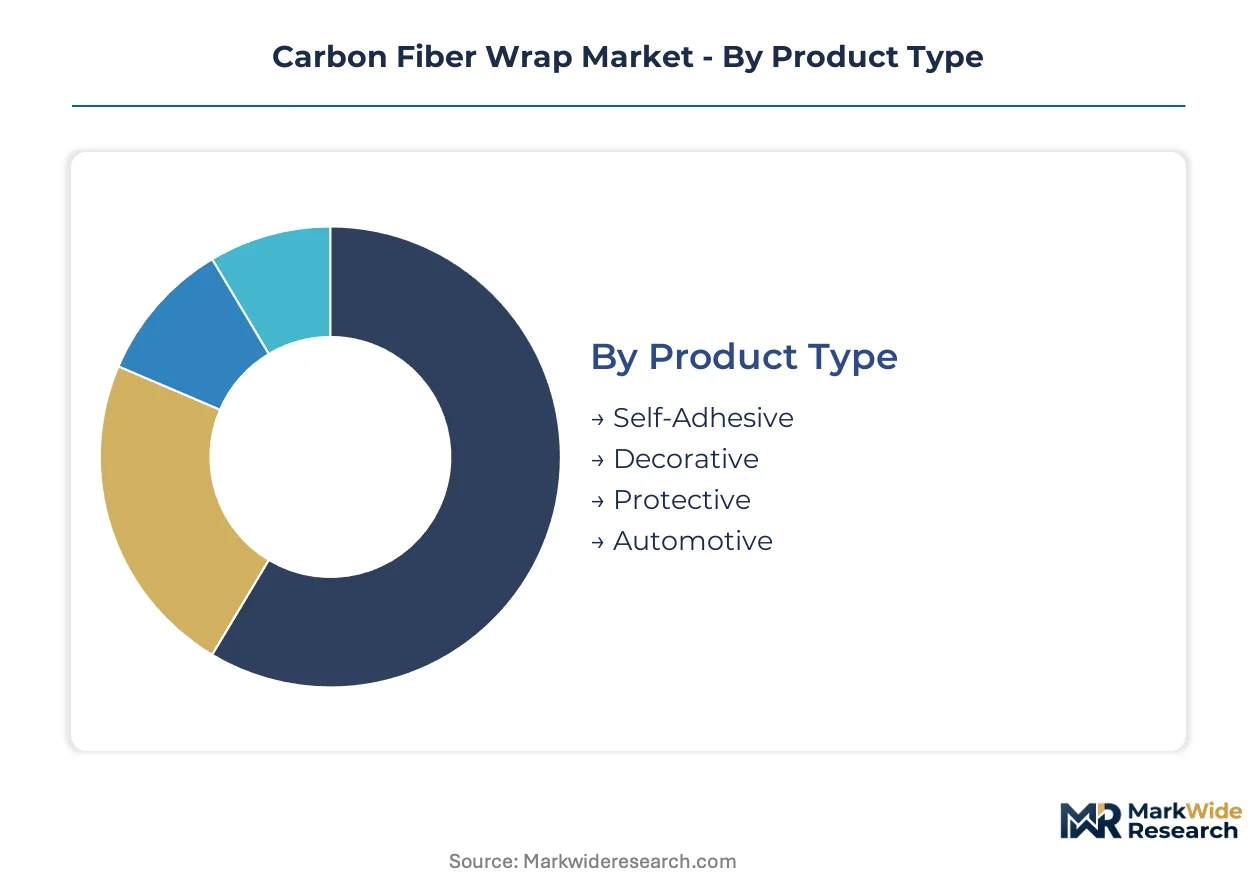
Segmentation in carbon fiber wrap markets separates structural reinforcement demand from aesthetic applications, each carrying distinct margin profiles and technical qualification requirements. Understanding these divides clarifies why protective wraps command infrastructure lifecycle contracts while decorative variants face commoditization pressure.
Product Type:
The use-case spectrum spans load-bearing structural reinforcement to surface-level aesthetic transformation, with resin chemistry and fiber architecture determining performance tier.
- Self-Adhesive:Pressure-sensitive backing eliminates field mixing of epoxy resins, reducing installation skill barriers for small-scale contractors. Demand concentrates in US residential basement waterproofing and Japanese seismic retrofit applications where rapid deployment offsets premium pricing.
- Protective:High-modulus unidirectional prepregs with epoxy or thermoplastic matrices deliver tensile strengths exceeding 3,000 megapascals for infrastructure lifecycle extension. Bridge rehabilitation authorities in Germany and Japan specify these systems for multi-year performance warranties, creating the deepest margin pools in the category.
- Decorative:Woven aesthetic films prioritize visual carbon fiber pattern replication over mechanical properties.
- Automotive:Pre-cut kits and roll formats serve both OEM structural reinforcement and aftermarket customization channels.
Established volume favors Protective wraps in civil engineering procurement; emerging adoption favors Self-Adhesive formats in residential and light commercial segments.
Application:
Cost tier separation distinguishes capital-intensive infrastructure deployments from consumer-accessible surface treatments.
- Exterior:UV-stabilized epoxy systems resist environmental degradation on bridge soffits, wind turbine blades, and building facades. North Sea offshore wind installations specify erosion-resistant overlays extending blade service intervals beyond gelcoat limitations.
- Industrial Components:Corrosion-resistant wraps protect chemical processing equipment and pressure vessels in Texas and Louisiana petrochemical corridors where dig-and-replace downtime costs exceed material premiums.
- Interior:Low-VOC formulations meet confined-space workplace exposure limits for architectural feature walls and retail fixtures.
- Sports Equipment:Lightweight reinforcement for bicycle frames, hockey sticks, and racing shells prioritizes gram-counting performance over durability metrics.
Industrial and Exterior applications anchor contract visibility through multi-year warranties; Sports Equipment shows steepest expansion trajectory as composite manufacturing democratizes.
Customer Type:
Procurement patterns separate specification-driven engineering relationships from price-sensitive transactional purchasing.
- OEMs:BMW and Volkswagen structural reinforcement programs in Bavaria and Lower Saxony integrate carbon fiber wrap into electric vehicle architectures, with qualified supplier relationships extending 5-7 year contract horizons.
- DIY Enthusiasts:Marketplace platform expansion in California and Florida aftermarket channels drives self-selection through tutorial content, representing the most rapidly scaling customer acquisition pathway despite lower per-transaction values.
- Custom Builders:Specialist automotive and marine fabricators demand technical support and batch consistency for one-off projects.
- Retail Consumers:Unbranded Chinese alternatives flood automotive aftermarket channels with pattern-matched films lacking structural certification.
OEM relationships sustain longest revenue visibility; DIY channels climb the fastest through digital distribution fragmentation.
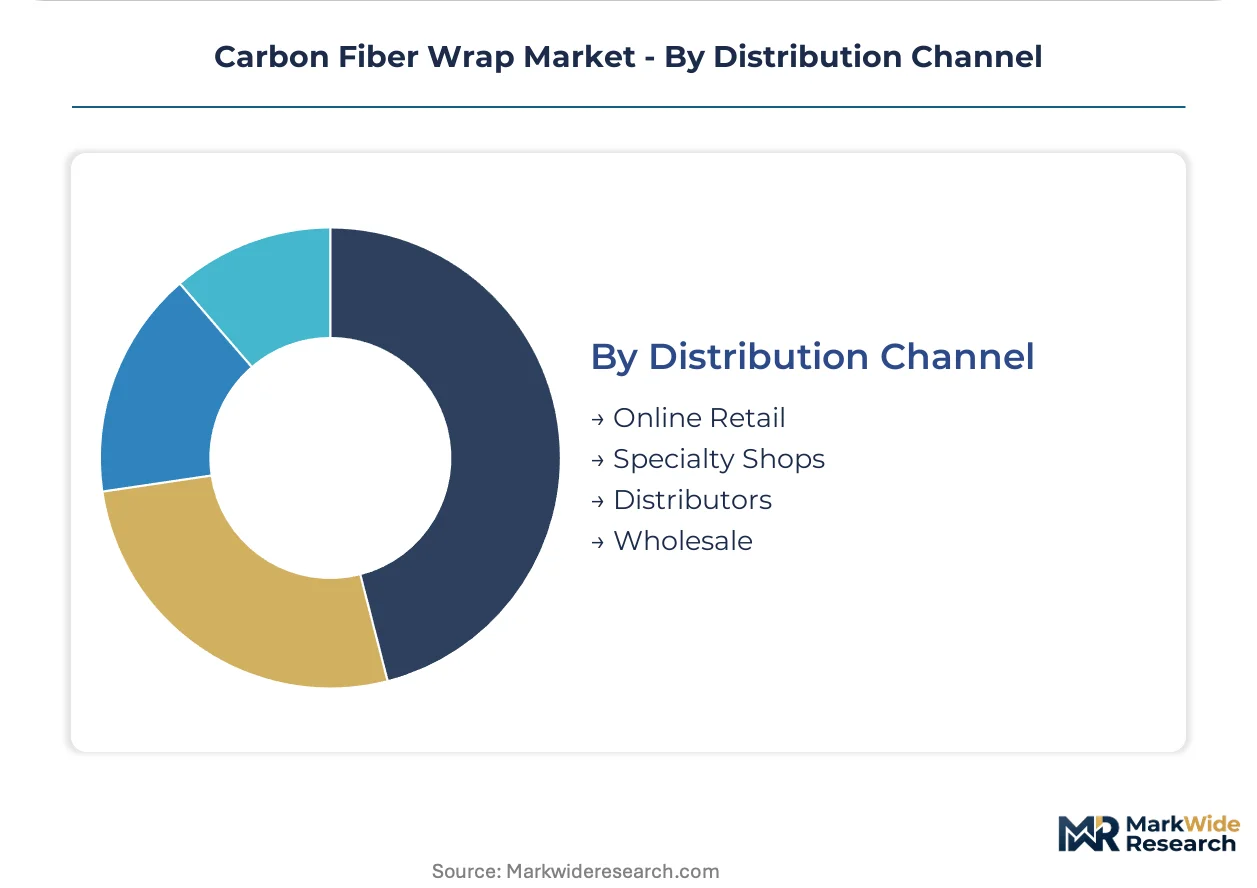
Distribution Channel:
Margin retention varies sharply between specification-controlled technical sales and price-transparent marketplace transactions.
- Distributors:Regional technical specialists maintain relationships with civil engineering contractors and aerospace maintenance programs, preserving pricing power through application engineering support and qualification documentation.
- Online Retail:Amazon and specialty marketplace platforms compress information asymmetries for decorative and automotive aftermarket segments, eroding traditional distributor margin pools in California and Florida.
- Specialty Shops:Installation service bundling captures value-added revenue for complex structural applications.
- Wholesale:Volume pricing serves large contractors and OEM direct procurement with minimized service overhead.
Distributor networks defend position in protective and industrial specification sales; Online Retail gains share fastest in decorative and automotive consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber wrap manufacturing concentrates in three distinct supply basins spanning North America, East Asia, and Western Europe. Precursor production and weaving capacity cluster where petrochemical feedstock access intersects with aerospace and automotive engineering demand.
United States
FAA airworthiness directives drive aerospace-grade qualification cycles for defense and commercial aviation maintenance programs. OSHA workplace exposure limits and EPA volatile organic compound regulations constrain resin formulation chemistry in domestic manufacturing. California and Texas municipal water infrastructure authorities specify carbon fiber wrap for concrete pressure pipe rehabilitation, creating structural reinforcement demand outside traditional aviation channels.
Germany
BMW and Volkswagen structural reinforcement programs in Bavaria and Lower Saxony integrate carbon fiber wrap into electric vehicle platform architectures. ECHA sunset date mechanics under REACH authorization requirements force accelerated substitution investments toward bio-epoxy feedstocks. Stuttgart and Wolfsburg automotive engineering corridors host pilot programs for polyamide and PEEK-based thermoplastic prepregs with sub-10-minute cycle times.
China
Domestic precursor and weaving investments scale across Jiangsu and Shandong provinces, rewriting capacity dynamics in carbon fiber wrap manufacturing. GB composite material specifications fragment compliance requirements for cross-border suppliers entering construction-grade markets. Shanghai and Beijing infrastructure authorities increasingly specify composite reinforcement for bridge seismic retrofit applications, extending demand visibility through multi-year performance warranties.
Japan
Toray Industries and Mitsubishi Chemical Carbon Fiber dominate qualified defense and aviation material pools, creating single-source concentration for aerospace-grade supply. METI industrial standards govern construction-grade composite certification, with harmonized pathways reducing cross-border qualification friction for European entrants. Tokyo and Osaka metropolitan prefectures specify carbon fiber wrap for tunnel and bridge rehabilitation, anchoring protective wrap demand in lifecycle extension contracts.
United Kingdom
Offshore wind installations in the North Sea require erosion-resistant composite overlays extending blade service intervals beyond gelcoat limitations. EASA certification standards parallel FAA tracks for aerospace-grade wrap qualification, though UK-specific civil aviation protocols maintain distinct documentation requirements. Scotland and Northeast England wind energy clusters drive protective wrap specification for turbine leading-edge protection in harsh marine environments.
Carbon Fiber Wrap Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor and fabric production. The vendor base separates into consolidated aerospace-grade suppliers with qualified military platforms and fragmented automotive aftermarket entrants facing commoditization pressure. Three archetypes dominate: vertically integrated chemical conglomerates with captive precursor supply, specialized carbon fiber manufacturers with weaving-to-prepreg pipelines, and diversified materials companies leveraging cross-selling into adjacent composite markets. Competitive moves concentrate on backward integration into polyacrylonitrile production and geographic expansion through qualified distributor networks.
Among Japanese chemical conglomerates, Toray Industries and Mitsubishi Chemical Holdings Corporation occupy positions anchoring premium aerospace-grade output through proprietary polyacrylonitrile-to-fabric pipelines. SGL Carbon exemplifies the specialized European carbon fiber manufacturer archetype, leveraging heritage positioning to serve German automotive structural reinforcement programs. These three represent distinct competitive vectors: Toray and Mitsubishi Chemical Holdings sit within integrated chemical platforms with defense qualification depth, while SGL Carbon occupies the independent specialist tier with regional automotive OEM relationships.
| Leading Market Players |
|---|
| Hexcel Corporation |
| 3M |
| Toray Industries |
| DowAksa Advanced Composites |
| Zoltek |
| SGL Carbon |
| Teijin Limited |
| Formosa Plastics Corporation |
| Mitsubishi Chemical Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile precursor cost volatility compresses margin predictability while simultaneously widening pricing tier spreads between aerospace-grade qualified suppliers and commoditized decorative wrap producers, forcing supply chain architects to choose between captive upstream integration or downstream specification control.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating elimination of high-global-warming-potential processing agents, creating a three-tier pricing structure across premium aerospace-qualified, standard industrial-grade, and economy decorative levels. Price differentiation hinges on certification depth—FAA and EASA airworthiness tiers command substantial premiums over construction-grade alternatives—and volume scale, with OEM structural reinforcement programs securing multi-year contract pricing while DIY aftermarket channels face spot-market volatility. Cost compression in decorative segments is intensifying because Chinese unbranded entrants flood automotive aftermarket channels. OEM procurement teams exhibit lowest price sensitivity due to performance warranty requirements; retail consumers through marketplace platforms show highest sensitivity, driving race-to-bottom dynamics in pattern-matched films.
Supply Chain Analysis
Specialized carbon fiber manufacturers including Toray Industries, SGL Carbon, and Hexcel Corporation hold qualified prepreg capacity, with geographic supply concentration centering on Japan, Germany, and the United States for aerospace-grade output while China scales weaving capacity across Jiangsu and Shandong provinces. Raw material dependencies rest on polyacrylonitrile precursor from propylene and ammonia feedstocks, epoxy resin formulations constrained by REACH authorization timelines, and high-modulus carbon fiber tows qualified for defense platforms. Single-source vulnerability pervades Japanese aerospace-grade supply, where Toray and Mitsubishi Chemical Carbon Fiber dominate qualified material pools. Distribution runs through regional technical specialists for protective and industrial specification sales, while online retail platforms fragment control over decorative and automotive aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber wrap demand sits in early-cycle expansion as infrastructure lifecycle extension contracts proliferate across seismic retrofit and corrosion protection applications, with municipal authorities in Japan, Germany, and the United States increasingly specifying composite reinforcement over structural replacement.
For Market Incumbents: Build certification moats by accelerating parallel FAA and EASA qualification tracks for next-generation bio-epoxy formulations ahead of ECHA sunset date enforcement. Prioritize backward integration into polyacrylonitrile precursor production to insulate margin structures from propylene and ammonia commodity swings. Secure captive supply of aerospace-grade carbon fiber tows to defend against Japanese supply concentration vulnerability threatening North American and European airframe integrators.
For New Entrants and Emerging Players: Municipal water infrastructure rehabilitation across California and Texas represents the most penetrable entry point, where carbon fiber wrap outperforms dig-and-replace alternatives on disruption metrics and procurement authorities lack entrenched supplier relationships. Wind turbine blade leading-edge protection for North Sea and Baltic Sea offshore installations offers second white-space target, with erosion-resistant composite overlays extending service intervals beyond current gelcoat limitations. Partner with specialized composite technician training programs to overcome skilled trades scarcity blocking market access.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated specialists with captive precursor supply and qualified aerospace platforms. Long-term viability across the analysis window hinges on positioning ahead of EU Green Deal embodied carbon threshold enforcement and bio-based resin scale-up timelines. Target acquisition archetypes include European automotive-tier prepreg specialists with BMW and Volkswagen program relationships. Monitor ECHA substance restriction announcements as inflection indicator for conventional epoxy system obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries and SGL Carbon anchor margin control through captive polyacrylonitrile supply. |
| Bio-Epoxy Formulation Development | German automotive engineering corridors accelerate lignin-derived feedstock substitution ahead of REACH enforcement. |
| Concurrent FAA-EASA Qualification Investment | Hexcel Corporation leverages parallel certification tracks to compress 18-36 month product development cycles. |
| Direct-to-Installer Digital Distribution | Marketplace platforms serving California and Florida DIY enthusiasts fragment traditional distributor margin pools. |
| Specialized Technician Training Partnerships | Vocational programs in Germany and the United States address skilled trades scarcity constraining installation capacity. |
Methodological Framework
The analysis maps protective structural reinforcement, decorative aesthetic films, automotive pre-cut kits, and self-adhesive seismic retrofit formats, each validated through composite materials procurement managers at civil engineering contractors, technical directors at aerospace maintenance programs, automotive Tier-1 supplier sourcing leads, and aftermarket distribution channel partners. Primary fieldwork combined structured interviews with secondary validation against FAA airworthiness directive filings, EASA certification databases, ECHA REACH authorization timelines, Japan METI industrial standard documentation, and China GB composite material specifications. Bottom-up demand modeling across application segments triangulated with top-down supply capacity assessments from precursor through prepreg fabrication.
Assumptions held fixed include current EU F-Gas Regulation compliance mandates, ECHA sunset date mechanics for bisphenol-A derivatives, and FAA-EASA concurrent qualification timelines; variables tested encompass bio-epoxy feedstock cost curves, Chinese weaving capacity expansion rates, and infrastructure procurement budget trajectories across the projection horizon. Segmentation dimensions modeled span product type, application environment, customer procurement pattern, and regional regulatory cluster. CAGRs derived from installed base growth in bridge rehabilitation, wind turbine blade protection, and electric vehicle structural reinforcement, with sensitivity analysis on acrylonitrile price volatility and qualified technician supply constraints.
Macroeconomic conditions sit as an overlay; deviation in infrastructure stimulus allocation, propylene-ammonia feedstock pricing, or EU Green Deal embodied carbon threshold enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding bio-based resin scale-up timelines and harmonized certification pathway adoption. Quarterly review of ECHA substance restriction announcements, FAA airworthiness directive issuances, and Chinese precursor capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Viscose Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Fiberglass Resin Market
Fibers
Precision Fiber Molding Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Fiber Intermediates Market
Fibers
Viscose Staple Fiber Market
Fibers
Global Fiberglass Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Carbon Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Thermoformed Fiber Market