
 Fiberglass Cloth Market | 2026-2036
Fiberglass Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Cloth Market Analysis
The EU Green Deal is repositioning fiberglass cloth specifications across European supply chains, forcing mills to certify lower-carbon production methods for construction and automotive qualification. Owens Corning leverages its North American mineral sourcing to sustain cost advantages in electrical-grade woven products. China Jushi Co., Ltd. anchors global volume through integrated glass-melting and textile operations in Zhejiang province. Saint-Gobain differentiates via specialty coatings that extend fire-retardant performance in marine laminates.
Fiberglass cloth consists of interlaced glass fiber yarns, typically E-glass or S-glass composition, manufactured through loom weaving or stitch-bonding processes to achieve controlled tensile strength and thermal resistance for structural reinforcement. Woven products dominate value capture due to established qualification protocols in aerospace primary structures, while non-woven formats gain traction in automated automotive press molding where drapeability reduces labor cycle time. High-strength grade commands premium positioning in wind blade spar cap applications, whereas standard grade occupies volume slots in construction mesh and asphalt reinforcement.
REACH compliance in Europe, EPA air toxics standards in the United States, and China's GB standards on industrial glass fiber emissions collectively shape resin compatibility requirements and factory siting decisions for cloth finishers. The EU AI Act's manufacturing traceability provisions will soon extend to composite supply chain documentation, adding compliance layers for batch-level fiber provenance. Stakeholders must monitor evolving per-fluorinated compound restrictions in textile sizing chemistry, as these formulations determine bonding performance with epoxy and vinyl ester matrices.
Market Dynamics
Wind turbine blade manufacturers in China are consolidating procurement around localized fiberglass textile supply chains, compressing lead times and forcing European and North American mills to reconfigure finishing operations for just-in-time aerospace qualification.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:European manufacturers must substitute carbon-intensive materials in construction and automotive laminates, expanding addressable demand for certified low-carbon fiberglass cloth.
- Automated automotive press molding:Non-woven fiberglass formats with superior drapeability are displacing hand-layup woven products, reducing labor cycle time in high-volume vehicle component production.
- Next-generation airframe structures:Aerospace composite manufacturers are expanding procurement of high-strength fiberglass fabrics for primary structural applications previously reserved for carbon fiber.
Market Restraints
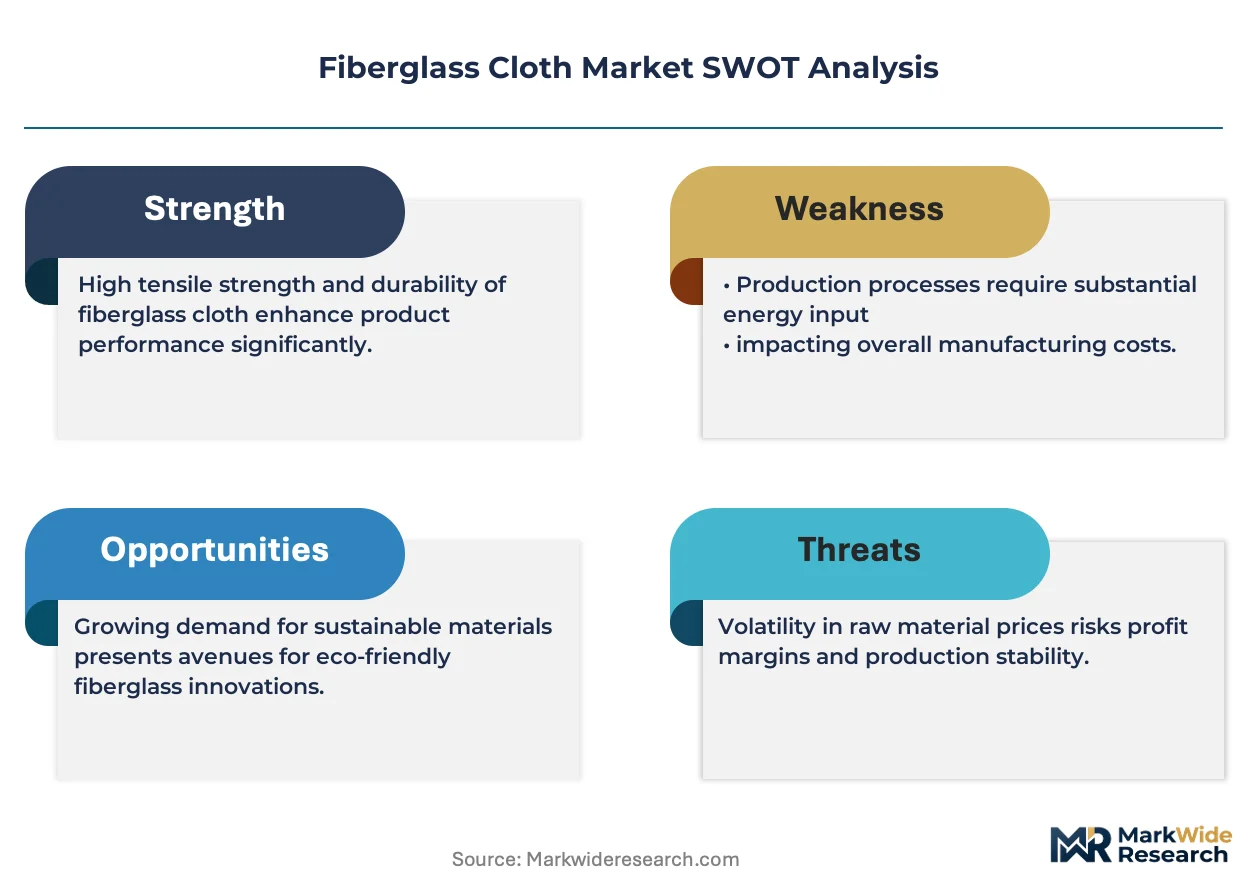
- Borosilicate glass batch cost volatility:E-glass and S-glass formulations depend on boron and rare earth mineral inputs subject to Chinese export quota fluctuations and energy surcharge pass-throughs.
- Zhejiang production cluster concentration:Integrated glass-melting and textile operations in China's Zhejiang province control critical upstream capacity, creating single-point vulnerability for global supply continuity.
- Per-fluorinated compound restrictions:REACH and EPA air toxics standards are phasing out legacy textile sizing chemistries, forcing reformulation of epoxy and vinyl ester bonding systems with unproven field performance.
Strategic Opportunities
- India wind energy manufacturing:Domestic blade production under the PLI scheme is accelerating, creating white space for localized fiberglass cloth finishing operations to serve emerging turbine OEM clusters in Gujarat and Tamil Nadu.
- EU AI Act traceability mandates:Batch-level fiber provenance documentation requirements will favor cloth finishers with integrated digital quality systems, creating compliance-based differentiation against commodity importers.
- Marine fire-retardant laminates:Specialty coated fiberglass fabrics meeting IMO SOLAS standards command premium positioning in cruise ship and naval vessel construction, with limited qualified supplier bases in Europe and East Asia.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous qualification under FAA, EASA, and CAAC airworthiness standards for aerospace-grade woven products extends development cycles and strains technical documentation resources.
- Legacy loom operator scarcity:Automated weaving equipment requires skilled technicians for pattern programming and tension calibration, with training pipelines failing to replace retiring workforce cohorts in European textile regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Cloth Market |
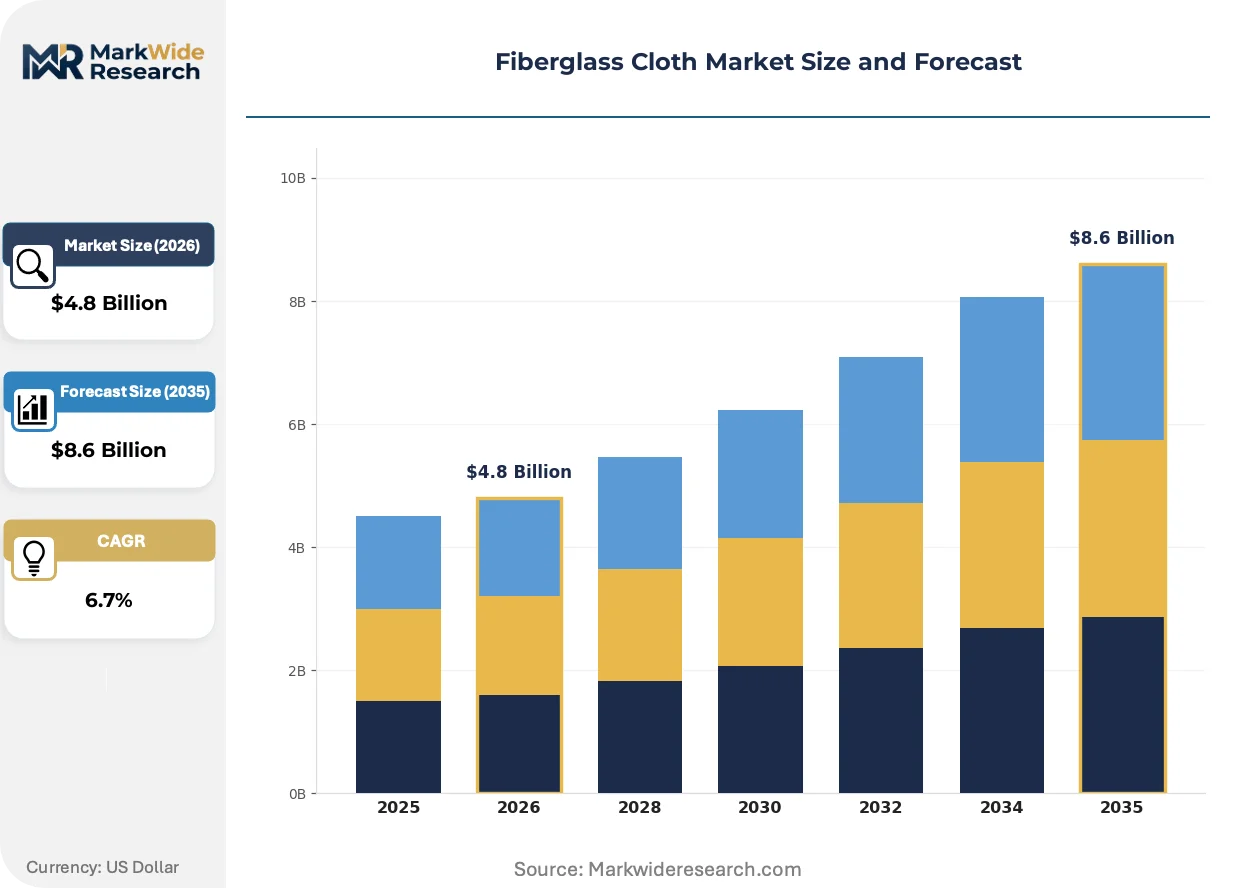
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-Woven, Chopped Strand, Specialty Application: Aerospace, Automotive, Marine, Construction Grade: Standard, High-Strength, Electrical, Fire-Retardant End User: Manufacturers, Contractors, OEMs, Distributors |
| Companies Covered | Owens Corning, China Jushi Co., Ltd., Saint-Gobain, Hexcel Corporation, Nippon Electric Glass, SAERTEX GmbH & Co. KG, Nitto Boseki Co., Ltd., Gurit, BGF Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Cloth Market Emerging Trajectories
Digital manufacturing traceability and automated textile processing are converging to reshape qualification protocols and procurement patterns across aerospace, automotive, and wind energy end-uses.
Stitch-bonded non-woven fiberglass fabrics with engineered fiber orientation are overtaking traditional woven constructions in automotive structural components. Tier-1 suppliers to German and Japanese OEMs are qualifying these formats for hood, decklid, and floor pan applications where complex curvature demands rapid drape without wrinkling. The technology is overtaking established supply relationships by collapsing the number of processing steps between fiber and finished composite.
REACH authorization requirements for per-fluorinated compounds in textile sizing formulations are forcing reformulation of glass fiber surface treatments across European finishing operations. Industrial emissions benchmarks under the EU Green Deal now extend to upstream glass-melting energy intensity, pressuring mills to certify renewable power sourcing for construction and automotive qualification. Marine laminate producers in France and Italy are accelerating qualification of alternative chemistries to maintain CE marking compliance.
Direct mill-to-OEM contracting is displacing traditional distributor intermediaries in wind blade procurement. Chinese turbine manufacturers are establishing captive textile finishing capacity or long-term offtake agreements with Zhejiang-based integrated producers, compressing margin pools for independent European and North American converters. The pattern is most visible in blade spar cap applications where volume concentration enables dedicated production line allocation.
Fiberglass Cloth Market Segmentation
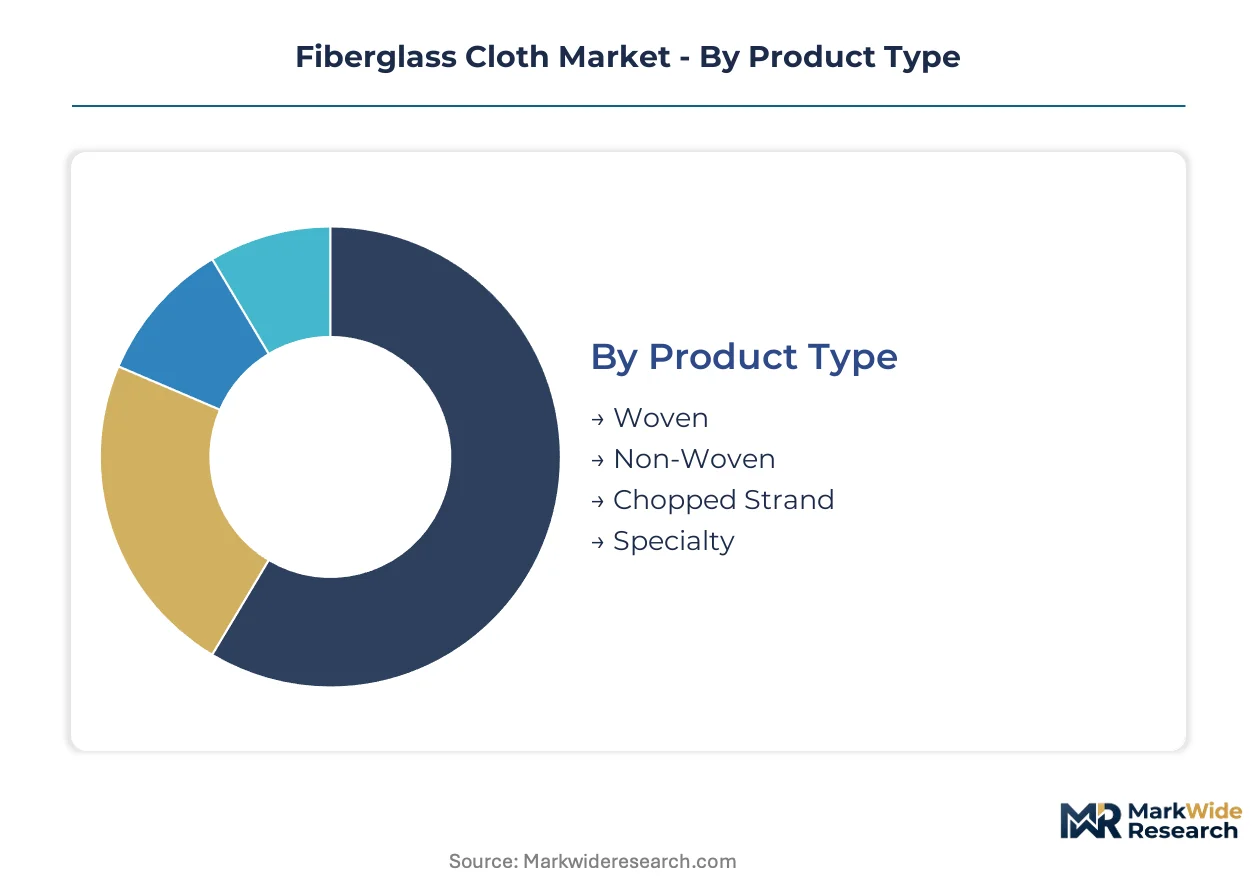
Segmentation in fiberglass cloth markets determines capital allocation, margin capture, and qualification barriers across aerospace, automotive, and renewable energy supply chains. Product format, application specificity, and performance grade each impose distinct technical and commercial requirements on producers.
Product Type:
Woven and non-woven formats demand fundamentally different capital equipment, with weaving looms requiring higher upfront investment but locking in aerospace qualification premiums.
- Woven:Interlaced E-glass or S-glass yarns produced on projectile or rapier looms deliver controlled tensile strength and thermal resistance for structural reinforcement. Aerospace primary structures in Germany and Japan concentrate procurement here, driven by FAA and EASA qualification protocols that extend development cycles but sustain price premiums.
- Non-Woven:Stitch-bonded or needle-punched fabrics with engineered fiber orientation achieve superior drapeability for complex curvature. Automotive press molding operations in Michigan and Bavaria are displacing hand-layup methods, reducing labor cycle time in hood and decklid production.
- Chopped Strand:Short-cut glass fibers bonded into mat format for rapid resin wet-out in closed-mold processes. Construction and marine repair applications in Florida and Queensland dominate consumption.
- Specialty:Custom weaves including 3D orthogonal constructions and hybrid glass-carbon architectures. Satellite and defense contractors in California and Toulouse specify these for thermal protection systems.
Woven products absorb the bulk of installed capacity; non-woven formats are expanding most quickly as automotive automation accelerates.
Application:
End-use concentration determines geographic sourcing patterns and regulatory exposure, with aerospace and marine facing the most stringent certification burdens.
- Aerospace:Primary and secondary structural laminates for commercial and military airframes. High-strength S-glass fabrics from Owens Corning and Saint-Gobain facilities in Ohio and France supply Boeing and Airbus tier-1 converters, with qualification under FAA, EASA, and CAAC standards extending procurement timelines.
- Automotive:Structural composites for body-in-white and underbody components. German and Japanese OEMs are qualifying stitch-bonded non-woven formats for electric vehicle battery enclosures, where fire-retardant performance intersects with lightweighting mandates.
- Marine:Hull laminates, deck structures, and interior components for pleasure craft and commercial vessels. IMO SOLAS fire-retardant standards in Mediterranean shipyards drive specialty coated fabric demand.
- Construction:Reinforcement mesh, asphalt overlays, and facade cladding systems. Chinese infrastructure spending and US highway rehabilitation programs sustain volume procurement of standard-grade woven and chopped products.
Construction absorbs the bulk of installed capacity; aerospace applications command the steepest expansion trajectory in value terms.
Grade:
Performance tier directly correlates with raw material chemistry, melting energy intensity, and downstream qualification scope.
- Standard:E-glass formulations with borosilicate chemistry for general-purpose reinforcement. Construction mesh and asphalt applications in Texas and Guangdong provinces consume volume production from Zhejiang integrated mills.
- High-Strength:S-glass and advanced E-glass variants with elevated silica and alumina content. Wind blade spar caps in Denmark and India require these grades for fatigue resistance under cyclic loading.
- Electrical:Low-alkali E-glass with controlled dielectric properties. Electrical-grade woven products from Owens Corning's North American mineral sourcing serve transformer and printed circuit board laminators.
- Fire-Retardant:Specialty coatings and inherent glass chemistry meeting IMO SOLAS and ASTM E-84 standards. Cruise ship construction in Italy and Finland mandates these for interior composite panels.
Standard grade absorbs the bulk of installed capacity; high-strength formulations are gaining share fastest as wind turbine dimensions increase.
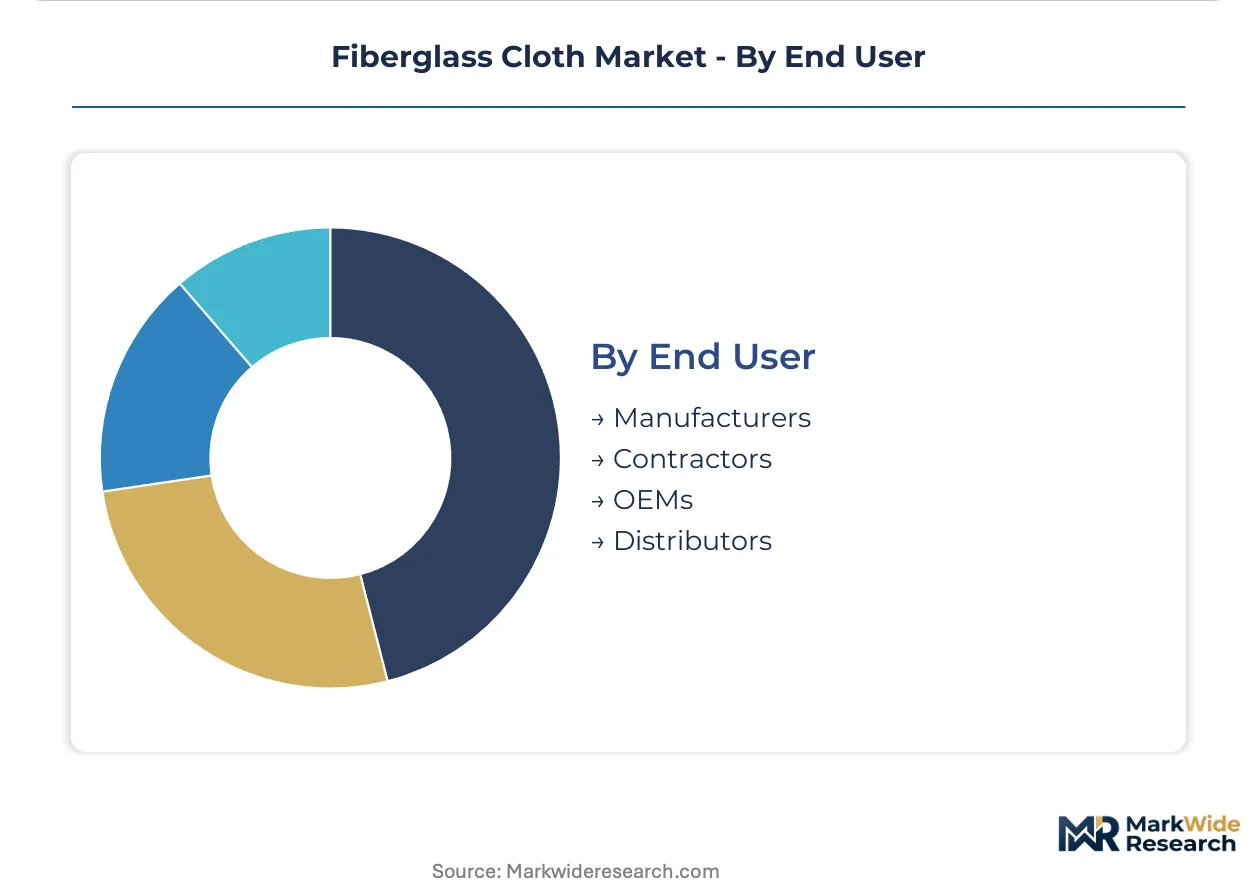
End User:
Channel structure determines margin distribution, with direct mill-to-OEM contracting displacing traditional distribution in concentrated end-uses.
- Manufacturers:Composite part producers serving tier-1 aerospace and automotive supply chains. These buyers qualify specific fabric constructions under long-term agreements, locking in volume commitments.
- Contractors:Construction and marine repair operators purchasing through distribution. Price sensitivity dominates here, with spot purchasing patterns and limited technical specification involvement.
- OEMs:Original equipment manufacturers in wind energy and automotive establishing captive finishing capacity or direct offtake agreements. Chinese turbine producers in Jiangsu province exemplify this vertical consolidation.
- Distributors:Independent converters and stocking distributors serving fragmented regional markets. Margin compression from direct sourcing is forcing these intermediaries toward technical services and kitting operations.
Manufacturers absorb the bulk of installed capacity; OEM direct procurement is climbing the fastest as wind and automotive volumes concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors fiberglass cloth manufacturing through integrated glass-melting and textile corridors serving wind turbine blade producers. Demand geography spans aerospace clusters in Ohio and Toulouse, automotive press molding operations in Michigan and Bavaria, and marine laminate yards across Mediterranean shipbuilding centers.
United States
Aerospace composite demand from Boeing tier-1 converters in Washington and Kansas drives high-strength S-glass procurement. FAA airworthiness standards extend qualification timelines for primary structural fabrics. Owens Corning leverages North American mineral sourcing from South Carolina operations to sustain electrical-grade woven product margins.
Germany
Automotive OEMs in Munich and Stuttgart are qualifying stitch-bonded non-woven formats for electric vehicle battery enclosures. REACH authorization requirements for per-fluorinated compounds force reformulation of glass fiber surface treatments. KBA vehicle certification protocols intersect with EU Green Deal industrial emissions benchmarks for laminate suppliers.
China
Domestic wind turbine blade producers in Jiangsu province scale localized fiberglass textile supply chains under MIIT industrial guidance. GB standards on industrial glass fiber emissions shape factory siting decisions for cloth finishers. Zhejiang integrated mills control critical upstream capacity through captive glass-melting operations.
India
Domestic blade production accelerates under the PLI scheme, creating demand for localized fiberglass cloth finishing in Gujarat and Tamil Nadu. CEA renewable energy mandates expand wind installation targets. Emerging turbine OEM clusters around Ahmedabad and Chennai compress lead times through regional sourcing.
France
Marine laminate producers in Marseille and Saint-Nazaire accelerate qualification of alternative sizing chemistries to maintain CE marking compliance. ECHA REACH provisions phase out legacy textile formulations. Specialty coated fabrics meeting IMO SOLAS standards command premium positioning in cruise ship construction at Chantiers de l'Atlantique.
Fiberglass Cloth Market Vendor Landscape
Premium-margin players sit above commodity-margin players across qualification depth and raw material integration. The vendor base organizes into three tiers: integrated glass-melting and textile operators, independent finishing converters, and specialty coating specialists. Strategic moves concentrate on captive upstream capacity and digital traceability systems for EU AI Act compliance.
Within the integrated-tier archetype, China Jushi Co., Ltd. exemplifies backward control over mineral sourcing and melting operations. Owens Corning and Saint-Gobain occupy positions spanning North American electrical-grade markets and European marine specialty coatings respectively. These three anchors represent divergent geographic and grade-specialization strategies.
| Leading Market Players |
|---|
| Owens Corning |
| China Jushi Co., Ltd. |
| Saint-Gobain |
| Hexcel Corporation |
| Nippon Electric Glass |
| SAERTEX GmbH & Co. KG |
| Nitto Boseki Co., Ltd. |
| Gurit |
| BGF Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Boron and rare earth mineral inputs trace from Chinese export quotas through E-glass and S-glass batch formulations into three-tier pricing structures across premium aerospace qualification, standard construction mesh, and economy-grade asphalt reinforcement tiers. Energy surcharge pass-throughs from Zhejiang glass-melting operations compress margin pools for independent European and North American converters unable to match integrated mill cost bases.
Pricing Analysis
Yield-locked pricing for aerospace-grade S-glass fabrics ties contract values to airframe qualification longevity and fatigue test performance. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified primary structures from construction mesh and chopped strand mat applications. Cost compression in standard-grade tiers is intensifying because Chinese integrated mills leverage captive mineral sourcing and renewable power certifications under EU Green Deal benchmarks. Contractors purchasing through distribution channels exhibit highest price sensitivity, while OEMs executing direct mill-to-OEM contracting absorb qualification premiums for assured volume allocation.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang province integrated glass-melting and textile corridors controlling critical upstream capacity for global wind blade spar cap supply. Raw material feeds draw from Australian mineral concentrates, Chinese boron processing facilities, and South Carolina silica operations. Tariff exposure runs through legacy textile sizing chemistry dependencies subject to REACH per-fluorinated compound phase-outs. Distribution runs through direct mill-to-OEM contracting in concentrated wind and automotive end-uses, with independent converters retreating toward technical services and kitting operations in fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH authorization timelines and EU AI Act traceability mandates force sub-scale finishers into technical obsolescence or acquisition.
For Market Incumbents: Acquire captive glass-melting capacity in Zhejiang or South Carolina mineral corridors to defend against borosilicate batch cost volatility. Invest in digital batch-level fiber provenance systems to capture EU AI Act compliance premiums against commodity importers lacking integrated quality infrastructure.
For New Entrants and Emerging Players: EU Green Deal industrial emissions benchmarks in Germany and France open a window for low-carbon certified finishing operations serving construction and automotive laminate qualification. Target India wind energy manufacturing under PLI scheme incentives, positioning localized Gujarat or Tamil Nadu facilities to serve emerging turbine OEM clusters with compressed lead times against Chinese supply chains.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty coating specialists with IMO SOLAS marine fire-retardant qualifications in France and Italy. Watch for ECHA REACH enforcement acceleration against legacy sizing chemistry formulations as the inflection signal triggering distressed divestitures from non-compliant European finishers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Owens Corning's South Carolina silica operations sustain electrical-grade woven product margins against Chinese import competition. |
| Digital Traceability System Deployment | Batch-level fiber provenance documentation captures EU AI Act compliance premiums in aerospace qualification protocols. |
| Alternative Sizing Chemistry Qualification | Saint-Gobain marine coating specialists maintain CE marking access as ECHA REACH phases out per-fluorinated compounds. |
| Localized Finishing Capacity in India | Gujarat and Tamil Nadu facilities compress lead times for PLI scheme wind blade producers around Ahmedabad and Chennai. |
| Long-term Offtake Agreements with OEMs | Direct mill-to-OEM contracting locks in volume allocation for blade spar cap applications against distributor margin compression. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fiberglass cloth market assessment. Primary interviews with composite part procurement managers at tier-1 aerospace converters, plant managers at Zhejiang integrated glass-melting facilities, marine laminate technical directors at Mediterranean shipyards, and wind blade supply chain executives at Jiangsu turbine OEMs were cross-validated against GB standards documentation, ECHA REACH authorization databases, FAA airworthiness certification records, and SEC 10-K disclosures from publicly traded textile producers. Bottom-up capacity and consumption estimates were reconciled with top-down trade flow analysis across the analysis window.
Data-stream reconciliation combined production capacity surveys, import-export trade statistics, and end-use consumption modeling across woven and non-woven product formats, aerospace and automotive application segments, standard and high-strength grade tiers, and manufacturer versus OEM direct procurement channels. CAGRs were derived from slope-log regression against normalized production indices, with wind turbine blade dimension scaling and automated automotive press molding adoption curves serving as primary demand drivers.
Caveats apply where borosilicate mineral export quota fluctuations, per-fluorinated compound restriction enforcement timelines, or aerospace airworthiness certification delays could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Bioglass Fiber Market
Fibers
Keratin Market
Fibers
Fiberglass Mat Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Global Nylon Monofilament Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market