
 Global Bicomponent Fiber Market | 2026-2036
Global Bicomponent Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bicomponent Fiber Market Foresight
Dual-polymer melt spinning is reshaping how engineered textiles achieve functional surfaces without chemical finishing. Teijin Limited leverages its polymer science heritage to anchor premium industrial applications across Japan and Southeast Asia. Huvis Corporation dominates staple bicomponent supply for Korean hygiene brands, while Far Eastern New Century extends its filament capacity to serve Taiwanese technical textile exporters. Indorama Ventures navigates feedstock integration from purified terephthalic acid through to finished fiber.
Bicomponent fibers consist of two distinct polymer components arranged in defined cross-sectional geometries such as core-sheath or side-by-side configurations, manufactured through co-extrusion processes that bond dissimilar materials into a single filament capable of thermal self-crimping or selective solubility. These fibers serve industrial and commercial purposes including thermal bonding in nonwovens, elastic recovery in apparel, and controlled filtration porosity. Core-sheath structures lead volume output because the outer polymer determines surface properties while the inner core provides mechanical backbone, creating margin pools for producers mastering precise concentricity control. Islands-in-the-sea variants represent the fastest-expanding technical category as microfiber producers exploit sea-component dissolution to achieve sub-denier filaments for advanced filtration media.
REACH registration requirements in Europe and China's GB standards under SAMR oversight constrain unrestricted use of certain glycol-modified polyesters in consumer-facing applications, forcing reformulation toward bio-based alternatives or enhanced recyclability certifications. The EPA's emerging framework for per- and polyfluoroalkyl substance restrictions in the United States is additionally redirecting nonwoven producers toward bicomponent solutions that deliver water repellency through physical structure rather than fluorochemical treatment. Stakeholders must monitor polymer price spreads between PET and PP feedstocks alongside evolving extended producer responsibility schemes to determine optimal material composition strategies.
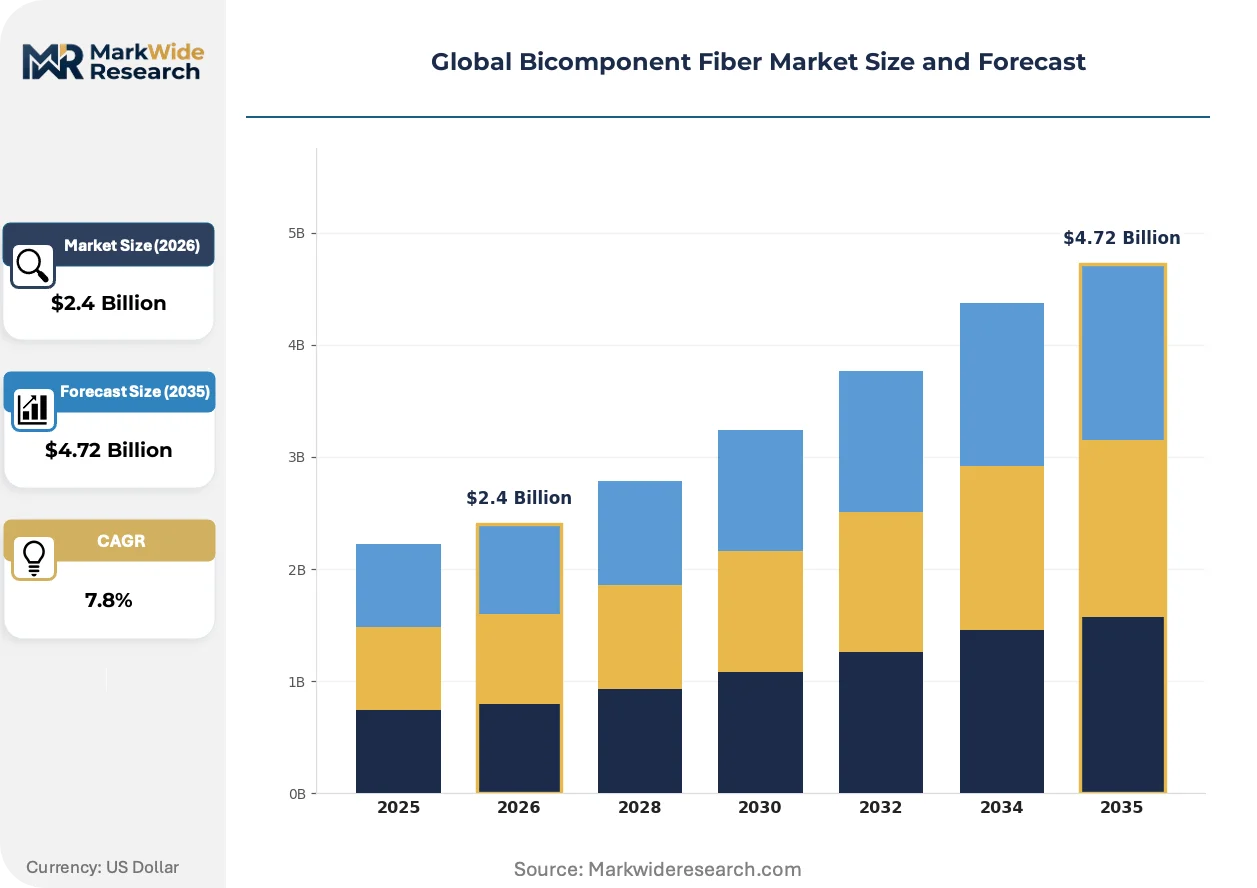
Market Dynamics
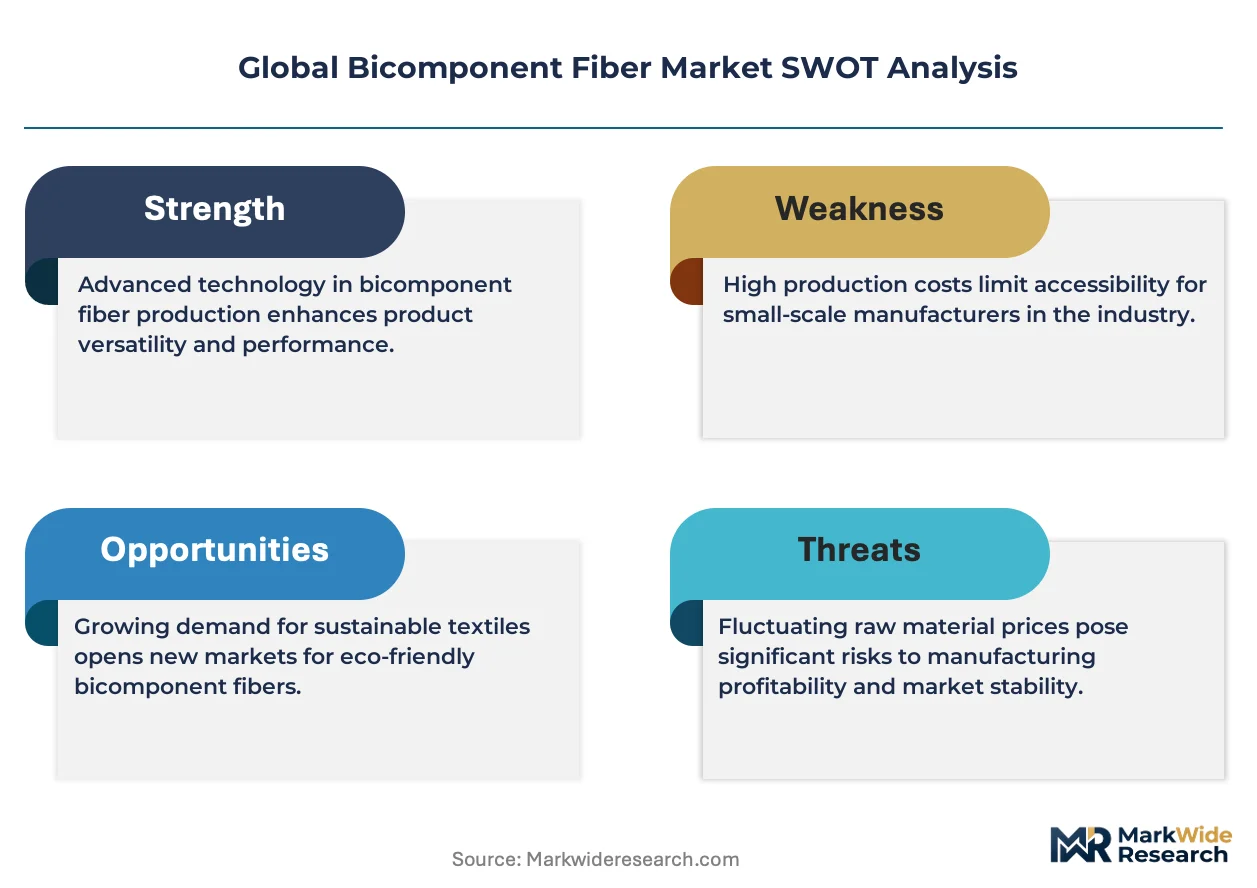
Dual-polymer melt spinning is compressing the traditional chemical finishing supply chain by embedding functional properties directly into fiber architecture, forcing incumbent textile chemical suppliers to reposition toward polymer modification services.
Growth Catalysts
- EPA PFAS Restrictions:The EPA's emerging per- and polyfluoroalkyl substance framework is redirecting nonwoven producers toward bicomponent structures that deliver water repellency through physical geometry rather than fluorochemical treatment.
- Asia-Pacific Hygiene Expansion:Manufacturers in China's Yangtze River Delta textile cluster are expanding procurement of core-sheath fibers for disposable hygiene applications.
- Islands-in-the-Sea Technology:Microfiber producers are exploiting sea-component dissolution to achieve sub-denier filaments for advanced filtration media, creating new technical specifications.
Market Restraints
- PET-PP Feedstock Spread Volatility:Margin pressure intensifies when purified terephthalic acid and polypropylene price differentials widen unpredictably.
- REACH Registration Burden:ECHA compliance requirements constrain unrestricted use of glycol-modified polyesters in European consumer-facing applications.
- Concentricity Control Threshold:Precise core-sheath geometry demands capital-intensive spinneret technology that smaller producers cannot access.
Strategic Opportunities
- India Technical Textiles:BIS certification gaps in engineered fiber standards create first-mover potential for producers establishing local compounding partnerships.
- EU Green Deal Alignment:Extended producer responsibility schemes reward bio-based polyester formulations with preferential recycling stream access.
- Medical Barrier Fabrics:MDR compliance timelines for single-use surgical textiles favor bicomponent thermal-bonding over adhesive lamination.
Industry Challenges
- Polymer Rheology Expertise Gap:Co-extrusion process engineers with simultaneous PET and PP melt experience command scarcity premiums.
- SAMR Certification Timelines:China's GB standards revision cycles delay market entry for reformulated bio-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bicomponent Fiber Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Side-by-Side, Core-Sheath, Islands-in-the-Sea, Segmented Pie, Sandwich Material Composition: Polyester, Polypropylene, Nylon, Acrylic, Acetate, Rayon End Use Application: Nonwovens, Apparel, Home Textiles, Industrial Textiles, Filtration, Furnishing Production Technology: Melt Spinning, Dry Spinning, Wet Spinning, Electrospinning |
| Companies Covered | Huvis Corporation, Teijin Limited, Indorama Ventures, FiberVisions Corporation, Freudenberg Performance Materials, Toray Industries, JNC Corporation, Kuraray Co. Ltd, Far Eastern New Century, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bicomponent Fiber Market Shifts & Advancements
Functional surface engineering is migrating from chemical baths to polymer architecture, with fiber producers now competing directly against finishing houses for technical textile specifications.
Sheath-core bicomponent spinning is hybridizing polyester and polypropylene into single-filament structures where the outer polymer determines surface energy while the inner core maintains mechanical integrity. Hygiene nonwoven converters in Southeast Asia are adopting these structures at accelerating rates for thermal-bonding applications. This hybridization is compressing demand for separate binder fibers and standalone surface treatments.
REACH registration requirements in Europe are forcing reformulation toward bio-based alternatives or enhanced recyclability certifications for glycol-modified polyesters. Industrial consequence includes shorter formulation lifecycles and accelerated R&D amortization. Consumer-facing hygiene applications face the tightest substitution pressures, with producers pivoting toward mass-balance certified feedstocks.
Direct mill relationships are displacing traditional fiber trader intermediaries as technical specifications tighten and lot-traceability requirements harden. Korean hygiene brands now contract staple bicomponent supply through multi-year offtake agreements rather than spot markets. This pattern concentrates procurement leverage among vertically integrated nonwoven producers in East Asia.
Global Bicomponent Fiber Market Segmentation
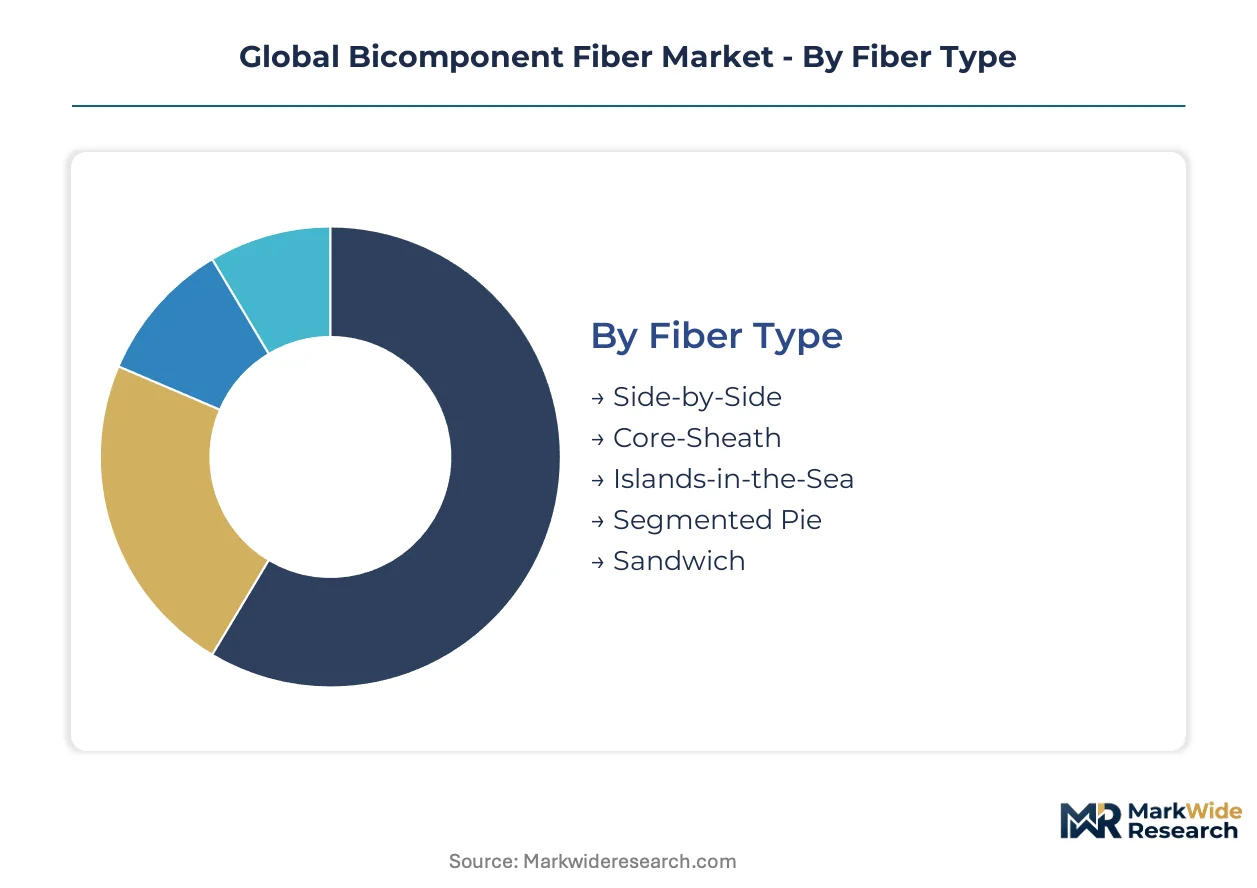
Bicomponent fiber segmentation reflects divergent technical requirements across hygiene disposables and industrial filtration. Manufacturers align polymer selection and cross-sectional geometry to specific bonding temperatures and surface energy targets.
Fiber Type:
Use-case spectrum spans thermal bonding convenience to sub-denier precision engineering.
- Core-Sheath:Concentric polymer arrangement places lower-melting sheath material around higher-melting core, enabling thermal bonding without bulk fiber degradation. Hygiene nonwoven producers in China's Yangtze River Delta specify these structures for disposable diaper acquisition layers.
- Islands-in-the-Sea:Dissolvable sea polymer releases multiple microfibers after processing, achieving sub-denier filaments for advanced filtration media. Microfiber specialists exploit this geometry for HEPA-grade air purification specifications.
- Side-by-Side:Asymmetric polymer pairing generates self-crimping through differential shrinkage, serving stretch applications in apparel without elastic additives.
- Segmented Pie:Wedge-shaped polymer sectors split into microfibers through mechanical separation rather than dissolution, offering cost advantages for wipes and polishing cloths.
- Sandwich:Flat layered construction bonds three polymer strata for controlled stiffness in carpet backing and geotextile applications.
The dominant share belongs to Core-Sheath, while Islands-in-the-Sea is closing the gap fastest.
Material Composition:
Cost tier stratification separates commodity feedstocks from performance-engineered alternatives.
- Polyester:PET-based formulations dominate thermal-bonding applications through tunable melting points and established recycling infrastructure. REACH registration pressures in Europe are accelerating bio-based PET pilot programs.
- Polypropylene:Lower density and chemical resistance position PP for medical barrier fabrics and liquid filtration. Korean hygiene brands specify PP-sheath structures for cost-sensitive diaper components.
- Nylon:Superior abrasion resistance serves industrial belting and tire cord applications where mechanical durability outweighs raw material premiums.
- Acrylic:Wool-like aesthetics and moisture wicking properties target premium apparel and furnishing segments with limited volume scale.
- Acetate:Controlled moisture absorption and draping characteristics serve cigarette filter tow and specialty textile markets.
- Rayon:Cellulosic base offers biodegradability positioning for single-use applications facing extended producer responsibility scrutiny.
Polyester commands volume leadership, though Polypropylene shows the steepest expansion trajectory in medical and hygiene specifications.
End Use Application:
Customer type concentration separates high-volume contract converters from specification-driven industrial buyers.
- Nonwovens:Thermal-bonded webs for wipes, diapers, and medical drapes represent the largest addressable volume. Japanese converters are expanding core-sheath procurement for adult incontinence products.
- Filtration:Sub-denier microfiber requirements for HVAC and liquid filtration command premium pricing with exacting lot-traceability standards.
- Apparel:Stretch recovery and moisture management specifications serve activewear and intimate apparel with shorter product lifecycles.
- Industrial Textiles:Reinforcement applications in composites and belting demand high tenacity with resistance to chemical and thermal degradation.
- Home Textiles:Carpet and upholstery backing utilize sandwich and core-sheath structures for dimensional stability during finishing.
- Furnishing:Decorative and functional applications in mattresses and furniture require fire-retardant compliant sheath formulations.
Nonwovens maintains the dominant position, while Filtration is gaining share fastest on technical specification premiums.
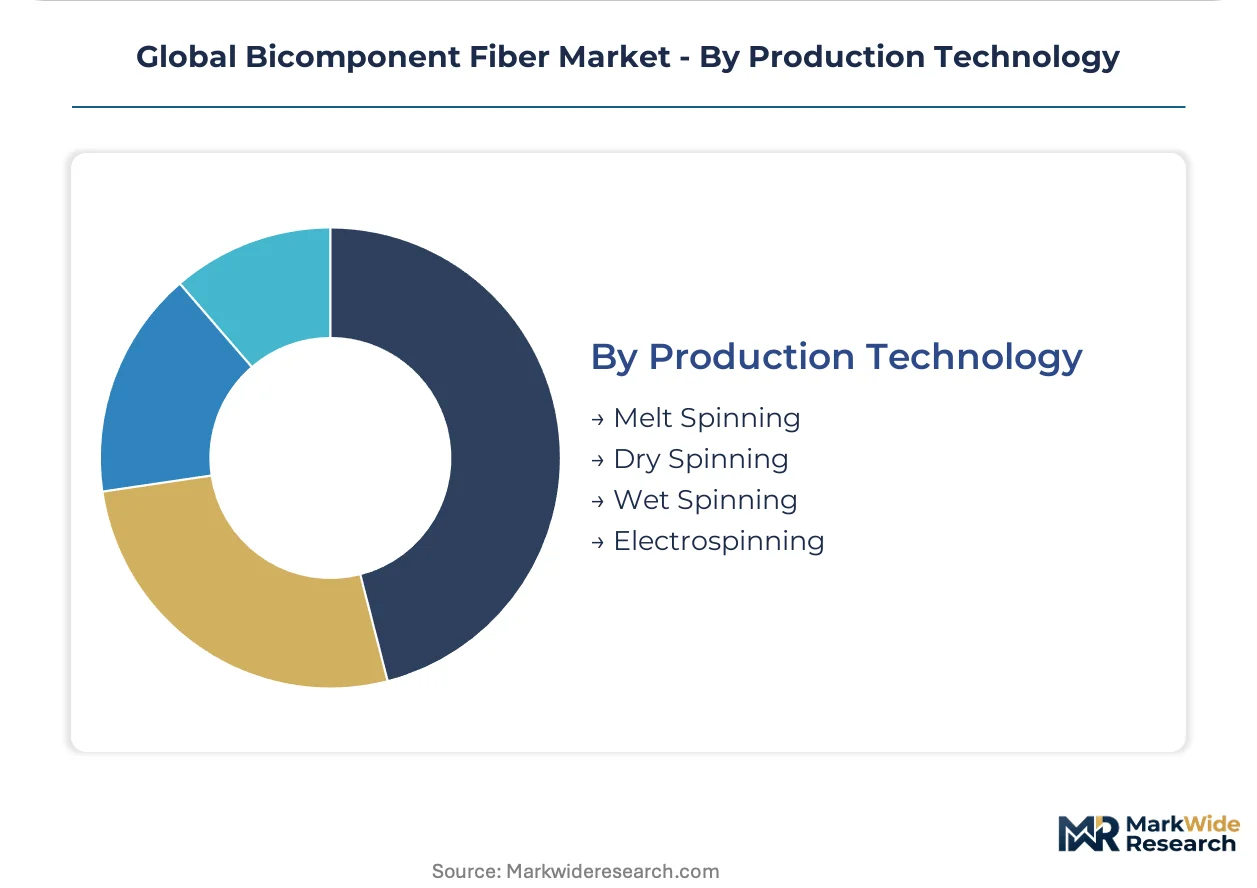
Production Technology:
Volume concentration favors melt-based methods with electrospinning occupying emerging niches.
- Melt Spinning:Dual-polymer extrusion through precision spinnerets dominates commercial output for hygiene and industrial applications. Teijin and Huvis operate scaled melt-spinning capacity across Japan and Korea.
- Dry Spinning:Solvent-based processing serves acetate and acrylic systems where thermal degradation prevents melt extrusion.
- Wet Spinning:Coagulation bath methods accommodate rayon and specialty polymers with limited thermoplastic character.
- Electrospinning:Electric field-driven nanofiber formation occupies research and medical membrane applications with throughput constraints limiting commercial scale.
Melt Spinning holds the dominant share, while Electrospinning is climbing the fastest in advanced membrane development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta textile cluster drives net export surpluses in core-sheath bicomponent fiber, while Germany and the United States remain deficit markets importing technical grades for filtration and medical applications. Japan and South Korea maintain balanced trade positions with specialized outputs serving regional hygiene supply chains. This geographic distribution reflects divergent feedstock access, polymer science capabilities, and end-use manufacturing concentrations.
China
GB standards under SAMR oversight tighten chemical disclosure rules for synthetic fiber imports, accelerating domestic substitution in hygiene nonwovens. The Yangtze River Delta cluster around Shanghai and Ningbo anchors expanding procurement of core-sheath structures for disposable diaper acquisition layers. Local producers exploit captive purified terephthalic acid supply to compress export pricing against Korean and Japanese competitors.
United States
EPA PFAS restrictions redirect nonwoven producers toward bicomponent water-repellency solutions, creating import dependency for islands-in-the-sea microfiber grades. The Southeast textile corridor spanning North Carolina and Georgia concentrates thermal-bonding capacity for wipes and medical drapes. Domestic melt-spinning investment lags Asian scale, forcing converters to source specialized filament from Korean and Taiwanese suppliers.
Germany
ECHA REACH registration requirements constrain glycol-modified polyester formulations in consumer-facing applications, favoring bio-based alternative development. The Baden-Württemberg technical textile belt around Stuttgart and Karlsruhe hosts advanced filtration media producers demanding sub-denier precision. Industrial nonwoven converters there negotiate multi-year offtake agreements to secure lot-traceability compliance for automotive and HVAC specifications.
Japan
METI industrial standards promote mass-balance certification for recycled-content bicomponent fibers in premium apparel applications. The Nagoya-Tokyo manufacturing corridor concentrates sheath-core hybridization expertise serving Southeast Asian hygiene brand technical specifications. Domestic producers leverage polymer science heritage to maintain pricing premiums against Korean volume competitors in industrial filtration segments.
South Korea
MFDS medical device regulations align with MDR compliance timelines, favoring bicomponent thermal-bonding over adhesive lamination in surgical textile specifications. The Busan-Ulsan petrochemical complex enables backward integration from propylene feedstock through finished staple fiber. Huvis Corporation anchors domestic supply for regional hygiene brands expanding procurement across Vietnam and Indonesia.
Global Bicomponent Fiber Market Competitive Landscape
On the supply side, the industry is consolidating around polymer science specialists with captive feedstock positions and precision spinneret capabilities. Tiered competitive dynamics separate vertically integrated petrochemical conglomerates from mid-scale staple specialists and niche microfiber technology licensors. Two dominant archetypes emerge: integrated PTA-to-fiber operators exploiting raw material cost curves, and hygiene-focused compounders mastering thermal-bonding specification partnerships. Capacity expansion and strategic raw material partnerships constitute the primary competitive vectors, with M&A activity concentrating in Southeast Asian hygiene supply chain integration.
Among Asia-Pacific-based producers, Teijin Limited, Huvis Corporation, and Far Eastern New Century exemplify divergent strategic positioning within regional supply chains. Teijin occupies a heritage-driven anchor position in Japanese industrial and premium technical textile specifications. Huvis represents the volume-focused archetype dominating Korean hygiene staple supply with regional procurement leverage. Far Eastern New Century sits within the Taiwanese filament specialization tier serving technical textile exporters with islands-in-the-sea capacity. These three entities collectively illustrate how geographic feedstock access and end-use application focus determine competitive positioning without overlapping core market territories.
| Leading Market Players |
|---|
| Huvis Corporation |
| Teijin Limited |
| Indorama Ventures |
| FiberVisions Corporation |
| Freudenberg Performance Materials |
| Toray Industries |
| JNC Corporation |
| Kuraray Co. Ltd |
| Far Eastern New Century |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta textile cluster around Shanghai and Ningbo anchors global core-sheath fiber capacity, concentrating upstream supply power among Chinese producers with captive purified terephthalic acid access. This geographic concentration enables aggressive export pricing against Korean and Japanese competitors while forcing downstream hygiene converters into multi-year offtake negotiations to secure volume commitments.
Pricing Analysis
Conventional melt-spun core-sheath structures command commodity pricing against premium islands-in-the-sea microfiber grades that capture filtration specification premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and lot-traceability depth. Cost compression in standard-grade thermal-bonding fibers is intensifying because Chinese PTA-integrated producers are expanding melt-spinning capacity. Hygiene nonwoven converters exhibit highest price sensitivity, while HEPA-grade filtration buyers prioritize technical compliance over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for islands-in-the-sea microfiber imports serving EPA-compliant water-repellency applications. Manufacturing concentrates in China, South Korea, and Japan, with each hub drawing from distinct feedstock bases—captive PTA in China, propylene-backward integration in Korea, polymer science specialization in Japan. Raw material dependencies span purified terephthalic acid, polypropylene resin, and precision spinneret components sourced from German and Japanese equipment specialists. Distribution runs through vertically integrated nonwoven producers in Southeast Asia that have displaced traditional fiber trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical specification partnerships and lot-traceability certification services are expanding faster than base fiber sales, creating recurring-revenue layers that outpace hardware volume growth. This service-attach dynamic favors producers with embedded polymer science expertise and regulatory compliance infrastructure.
For Market Incumbents: Build specification-lock moats through multi-year thermal-bonding parameter co-development with hygiene brand technical teams. Deepen backward integration into bio-based polyester feedstocks to preempt REACH-driven reformulation cycles. Anchor capacity expansion in Vietnam and Indonesia to capture regional procurement leverage as Korean hygiene brands diversify supply sources beyond Chinese dominance. For New Entrants and Emerging Players: Establish a beachhead in India's technical textiles segment where BIS certification gaps in engineered fiber standards create first-mover positioning. Target medical barrier fabric specifications where MFDS-MDR compliance timelines favor bicomponent thermal-bonding over adhesive lamination. Lead with islands-in-the-sea microfiber technology licensing rather than capital-intensive melt-spinning scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors polymer science specialists with captive feedstock and precision spinneret capabilities over commodity staple producers. Long-term viability hinges on extended producer responsibility scheme alignment and mass-balance certification infrastructure. Watch bio-based PET pilot program conversion rates as the inflection signal for feedstock transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | REACH and EPA PFAS restrictions are redirecting formulation toward mass-balance certified alternatives with preferential recycling access. |
| Precision Spinneret Technology Acquisition | Concentricity control thresholds in core-sheath production favor producers with capital-intensive equipment capabilities. |
| Multi-year Offtake Agreement Structuring | Korean and Japanese hygiene brands are displacing spot markets with contract procurement for lot-traceability compliance. |
| Islands-in-the-Sea Capacity Expansion | Sub-denier microfiber demand for HEPA-grade filtration commands premium pricing with exacting technical specifications. |
| Regional Compounding Partnership Formation | India's BIS certification gaps create first-mover potential for localized technical textile supply chain integration. |
Research Methodology
Desk research of customs trade databases, ECHA REACH registration filings, and SEC chemical company disclosures preceded structured interviews with melt-spinning plant managers, hygiene nonwoven procurement leads, and filtration media R&D directors. Primary fieldwork across Japan, South Korea, and China's Yangtze River Delta was cross-validated against secondary sources including MFDS medical device filings and SAMR GB standards revision notices. Bottom-up fiber production estimates were triangulated against top-down end-use consumption models.
Assumptions around PET-PP feedstock price spreads, REACH registration timeline adherence, and EPA PFAS restriction implementation pace were held fixed across baseline scenarios while islands-in-the-sea technology adoption curves and bio-based polyester substitution rates were stress-tested. Segmentation modeling spanned fiber type geometry, material composition tiers, end-use application specifications, and regional production hub concentration. CAGRs were derived from logarithmic trend fitting against historical capacity and consumption trajectories, with polymer rheology expertise scarcity and spinneret equipment lead times incorporated as supply-side constraints.
Stress conditions across feedstock volatility bands, regulatory compliance timeline slippage, and hygiene brand inventory destocking cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about SAMR certification cycle duration and ECHA bio-based alternative approval pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Viscose Market
Fibers
Precision Fiber Molding Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Carbon Fiber Filament Market
Fibers
Renewable Carbon Fibers Market
Fibers
Keratin Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Acoustical Fiber Board Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Metal Fiber Market