
 North America Carbon Fiber Market | 2026-2036
North America Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Carbon Fiber Market Outlook
Buyer concentration in aerospace tier-one suppliers is restructuring procurement patterns across the North America carbon fiber value chain. Hexcel Corporation leverages its Utah and California manufacturing footprint to sustain long-term supply agreements with Boeing and Lockheed Martin. Toray Composite Materials America anchors its position through backward integration into precursor acrylic fiber production in Alabama. Teijin Carbon America competes on thermoplastic composite technology leadership, differentiating its product portfolio from conventional thermoset competitors.
Carbon fiber consists of filaments approximately five to ten microns in diameter, composed primarily of carbon atoms bonded in aligned crystalline structures, manufactured through controlled oxidation and carbonization of polyacrylonitrile precursor under temperatures exceeding one thousand degrees Celsius. Continuous carbon fiber dominates structural applications where directional strength-to-weight ratios determine performance, while prepreg formats command premium positioning due to controlled resin content and handling consistency. Aerospace application requirements for FAA-certified material traceability create margin pools that exceed those available in sports equipment or industrial segments.
The FAA's material qualification standards and the EPA's National Emission Standards for Hazardous Air Pollutants govern manufacturing facility permitting and product certification across U.S. production sites. Health Canada's PMRA evaluates chemical emissions from composite curing processes for facilities operating near the U.S.-Canada border. Stakeholders must monitor evolving FAA certification timelines for thermoplastic composites and EPA enforcement patterns around precursor acrylonitrile handling to anticipate capacity allocation decisions.
Market Dynamics
EPA emissions standards for commercial aviation are forcing material substitution toward carbon fiber-reinforced polymers across Boeing and Airbus supply chains in the southeastern United States. This regulatory pressure concentrates procurement power among tier-one aerospace suppliers while compressing qualification timelines for alternative composites.
Growth Catalysts
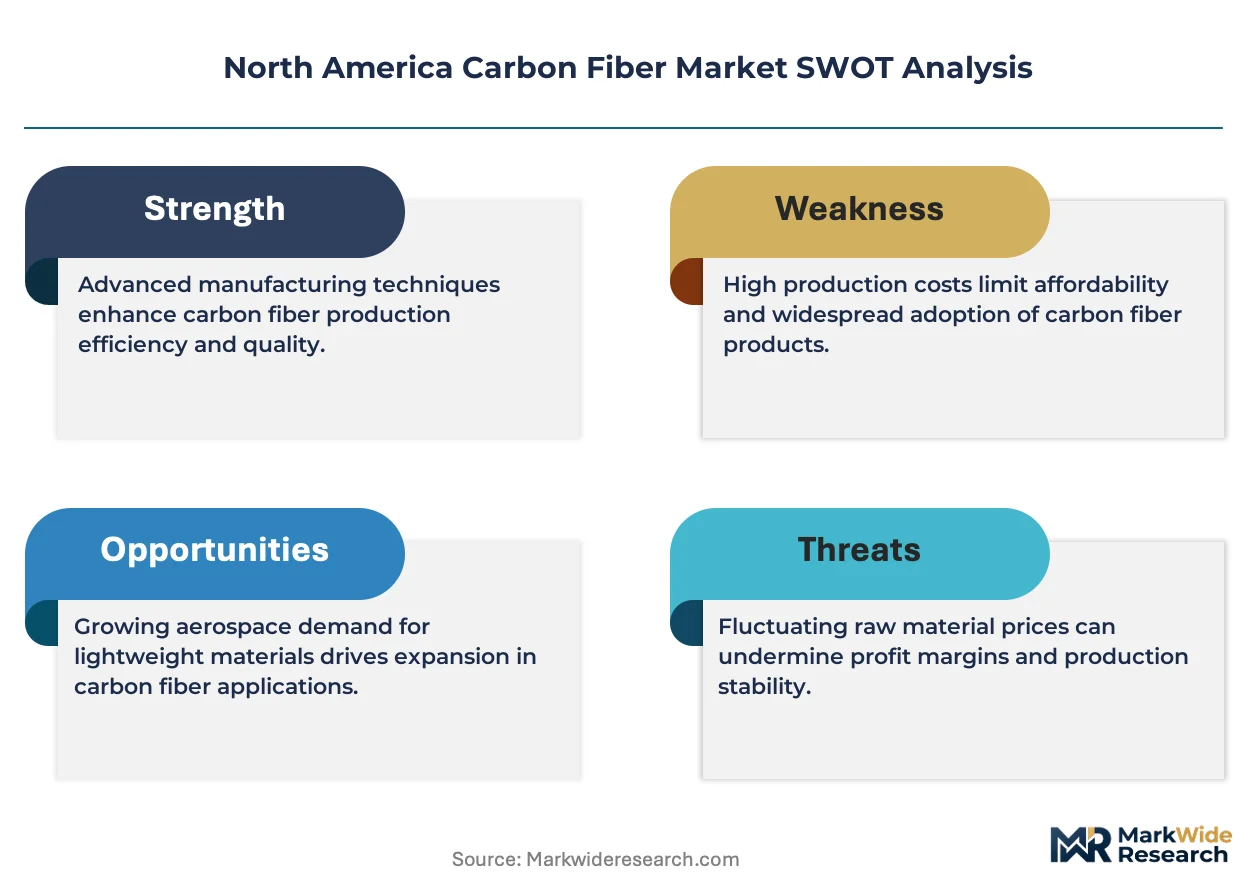
- FAA Certification Pathways:Accelerated qualification timelines for thermoplastic composites enable faster adoption in primary aircraft structures. The FAA's evolving material traceability requirements create premium positioning for certified suppliers.
- Automotive Lightweighting Mandates:NHTSA fuel economy standards drive OEM substitution of metal components with carbon fiber-reinforced polymers in electric vehicle platforms.
- Precursor Supply Security:Backward integration into polyacrylonitrile production in Alabama and Utah reduces acrylonitrile price volatility exposure for domestic manufacturers.
Market Restraints
- Acrylonitrile Cost Volatility:Petroleum-derived precursor pricing fluctuates with propylene feedstock markets, compressing margin stability for non-integrated producers.
- Oxidation Oven Capacity Bottlenecks:Carbonization furnace availability concentrates in legacy production corridors, limiting geographic diversification of new capacity.
- Thermoset Recycling Limitations:Cross-linked epoxy matrices resist end-of-life recovery, exposing aerospace OEMs to extended producer responsibility frameworks under evolving EPA guidelines.
Strategic Opportunities
- Canadian Wind Energy Expansion:Blade manufacturers in Ontario and Quebec seek domestic carbon fiber supply to reduce trans-Pacific logistics exposure for turbine components.
- Pressure Vessel Applications:Hydrogen storage systems for heavy-duty transport create demand for high-modulus fiber formats currently underpenetrated outside aerospace.
- Digital Thread Integration:Blockchain-enabled material pedigree tracking aligns with FAA traceability mandates while reducing qualification documentation overhead for tier-two suppliers.
Industry Challenges
- Specialized Technician Scarcity:Carbonization furnace operation and composite layup automation programming require skills concentrated in legacy aerospace clusters, constraining greenfield facility staffing.
- Qualification Timeline Compression:FAA material certification cycles extend 18-36 months, misaligning with automotive OEM product development velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Carbon Fiber Market |
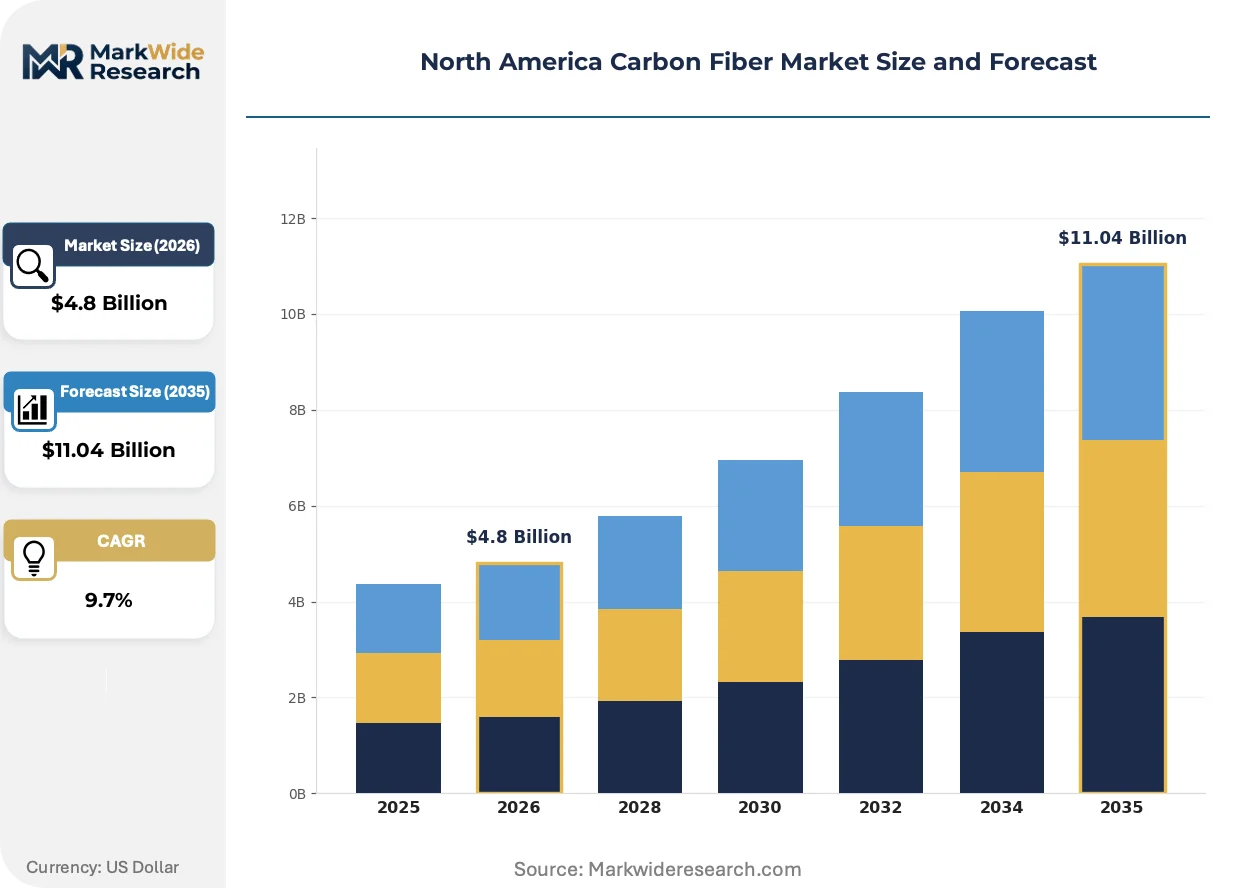
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Carbon Fiber, Short Carbon Fiber, Fabric, Prepreg Application: Aerospace, Automotive, Sports Equipment, Wind Energy End User: Manufacturers, Composite Industry, Construction, Medical Devices Form: Tows, Sheets, Rods, Chopped Strands |
| Companies Covered | Hexcel Corporation, Toray Composite Materials America, Teijin Carbon America, Solvay Composite Materials, Zoltek Companies, SGL Carbon, Mitsubishi Chemical Group, Syensqo, HS Hyosung Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Carbon Fiber Market Strategic Shifts
Thermoplastic composite formats are unifying processing speed with recyclability, reshaping competitive positioning across aerospace and automotive procurement specifications. Three convergent developments are compressing traditional thermoset dominance while enabling new manufacturing economics.
Thermoplastic unidirectional tapes are unifying automated fiber placement with in-situ consolidation, eliminating autoclave curing cycles. Boeing and Airbus tier-one suppliers in Kansas and Washington State are adopting these formats for non-critical structures. The technology is unifying cost structures previously separated by batch processing scale, enabling mid-volume automotive applications.
The EPA's National Emission Standards for Hazardous Air Pollutants are tightening acrylonitrile handling requirements at precursor production facilities. Carbon fiber manufacturers in Alabama and Utah face capital expenditure decisions for emission control upgrades. Aerospace-grade material qualification delays are accelerating as facilities reconcile environmental compliance with FAA certification timelines.
Consolidated procurement specifications from Boeing and Lockheed Martin are compressing supplier qualification diversity toward dual-source strategies. Tier-two prepeg converters in the southeastern United States are consolidating order books around long-term agreements with minimum volume commitments. Canadian automotive suppliers near the Ontario-Michigan corridor report extended lead times as fiber allocation prioritizes certified aerospace contracts.
North America Carbon Fiber Market Segmentation
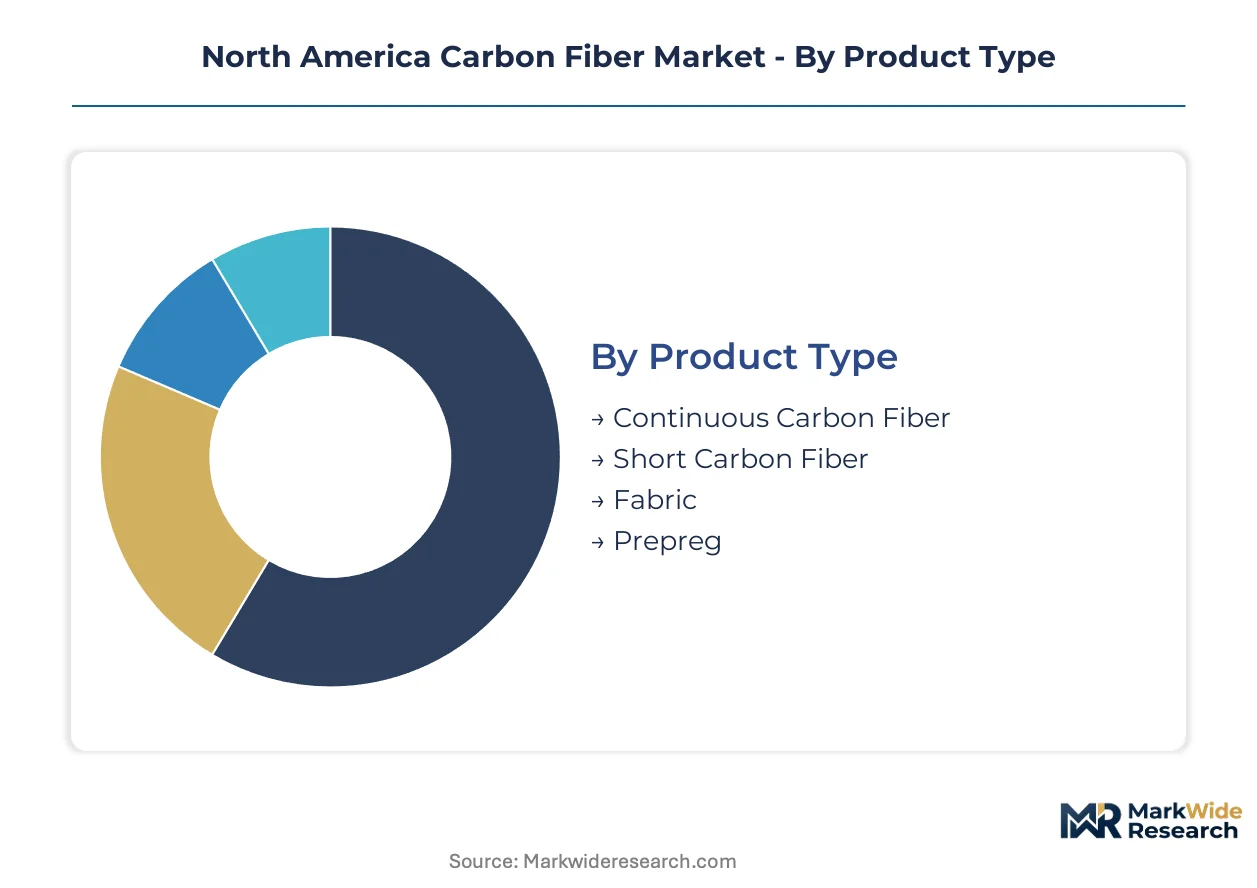
Carbon fiber segmentation in North America reflects divergent technical requirements across aerospace certification cycles and automotive platform refresh timelines. Procurement specifications from Boeing and Detroit OEMs create distinct performance tiers that reshape manufacturing priorities and qualification investments.
Product Type:
Replacement cycles for primary aircraft structures favor formats with established FAA qualification pathways, while automotive lightweighting mandates accelerate adoption of processable alternatives.
- Continuous Carbon Fiber:Unidirectional filaments manufactured through PAN precursor carbonization deliver maximum tensile strength-to-weight ratios for primary load-bearing structures. Boeing 787 and Airbus A350 wing box assemblies in Washington State and Kansas anchor procurement volumes; EPA aviation emissions standards tighten substitution economics away from aluminum alloys.
- Prepreg:Pre-impregnated unidirectional tapes and woven fabrics with controlled resin content enable autoclave-cured aerospace components with batch-to-batch consistency. Hexcel's Utah facilities and Toray's Alabama operations supply tier-one converters; FAA material traceability requirements sustain premium positioning over dry fiber formats.
- Short Carbon Fiber:Chopped 3-50mm segments compound into thermoplastic matrices for injection-molded automotive brackets and housings.
- Fabric:Woven 2D and 3D textile architectures provide drapability for complex curvature tooling in motorsport and industrial applications.
Volume placements concentrate in Continuous Carbon Fiber; the faster expansion belongs to Prepreg.
Application:
Cost tier differentiation separates qualification-intensive aerospace contracts from price-sensitive industrial procurement.
- Aerospace:Primary and secondary structures for commercial, defense, and general aviation platforms require FAA-certified material pedigree with full lot traceability. Boeing's South Carolina 787 final assembly line and Lockheed Martin's Fort Worth F-35 operations in Texas concentrate demand; NHTSA fuel economy standards indirectly reinforce substitution through supply chain prioritization.
- Automotive:Battery enclosures, structural members, and body panels for electric vehicle platforms exploit carbon fiber's stiffness-to-mass advantages against steel and aluminum. Michigan-Ontario corridor OEMs face compressed development cycles; qualification timeline misalignment with FAA aerospace standards constrains fiber allocation.
- Wind Energy:Blade spar caps and root inserts in Ontario and Quebec seek domestic supply security against trans-Pacific logistics exposure.
- Sports Equipment:Bicycle frames, hockey sticks, and golf shafts in recreational manufacturing clusters absorb commodity-grade fiber volumes.
Revenue concentration sits with Aerospace; Automotive climbs the fastest as EV platform scale materializes.
End User:
Customer type fragmentation creates divergent service requirements from technical partnership to commodity fulfillment.
- Composite Industry:Tier-one and tier-two converters serving aerospace and automotive OEMs demand certified material with dedicated technical service support. Southeastern U.S. prepreg manufacturers in Alabama and Georgia consolidate long-term supply agreements; backward integration into precursor production secures allocation priority.
- Manufacturers:OEMs with in-house composite fabrication capabilities, including Boeing's vertical integration in South Carolina, source direct for critical structures.
- Construction:Infrastructure reinforcement and seismic retrofit applications in California and British Columbia utilize carbon fiber-reinforced polymer composites.
- Medical Devices:Imaging equipment components and prosthetic structures exploit radiolucency and biocompatibility characteristics.
Procurement scale concentrates in the Composite Industry; Medical Devices demonstrates the steepest expansion trajectory.
Form:
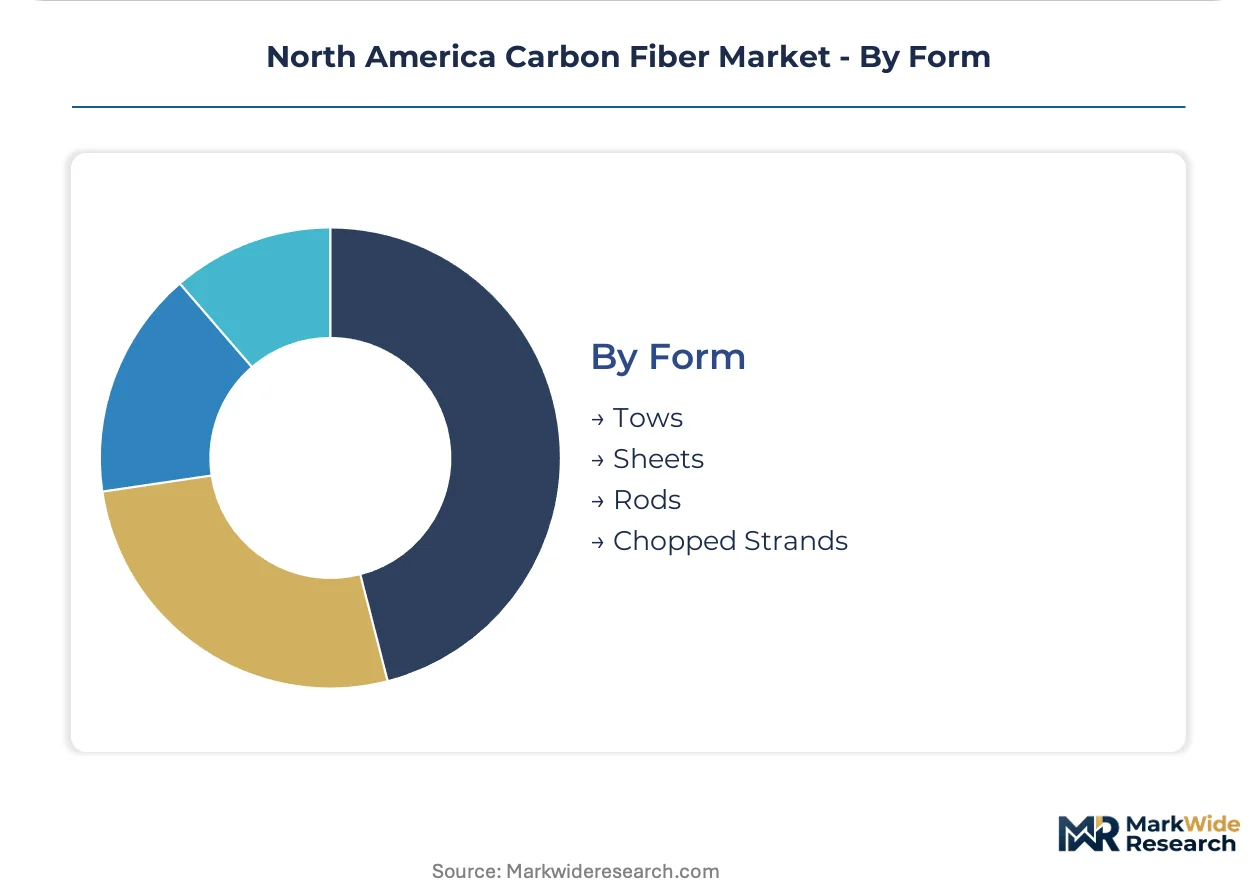
Supply concentration in legacy production corridors favors tow formats while emerging applications test alternative geometries.
- Tows:Bundled continuous filaments in 3K, 6K, 12K, and 24K filament counts constitute the feedstock for weaving, prepregging, and pultrusion. Utah and Alabama carbonization facilities optimize for aerospace-grade tow production; oxidation oven capacity constraints limit geographic diversification.
- Sheets:Unidirectional and bidirectional laid-up preforms serve automated fiber placement and hand layup operations.
- Rods:Pultruded solid sections provide stiffness for civil engineering reinforcement and industrial automation.
- Chopped Strands:Short-length discontinuous fiber enables thermoplastic compounding for injection molding throughput.
Manufacturing throughput concentrates in Tows; Sheets gain share fastest through automated processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyacrylonitrile precursor production in Alabama and Utah anchors carbon fiber manufacturing capacity across the continent. The southeastern United States concentrates aerospace demand through Boeing and Airbus operations. Canadian wind energy developers seek domestic fiber supply to reduce trans-Pacific logistics exposure.
United States
Boeing's 787 final assembly in South Carolina and Lockheed Martin's F-35 production in Texas drive aerospace-grade fiber consumption. The FAA's material qualification standards govern certification timelines for primary aircraft structures. Utah and Alabama carbonization facilities supply tier-one prepreg converters in Georgia and Kansas.
Canada
Wind turbine blade manufacturers in Ontario and Quebec pursue domestic carbon fiber sourcing for spar caps and root inserts. Health Canada's PMRA evaluates chemical emissions from composite curing processes near the U.S. border. British Columbia infrastructure projects utilize carbon fiber-reinforced polymers for seismic retrofit applications.
Mexico
Automotive suppliers in Nuevo León and the Bajío Region compound short carbon fiber for injection-molded EV components. Mexico's federal environmental authority monitors acrylonitrile handling at border-state precursor facilities. Querétaro's aerospace cluster attracts tier-two composite converters serving U.S. OEM supply chains.
North America Carbon Fiber Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue thermoplastic composite specialization and hydrogen storage applications. The market structure consolidates around precursor-integrated manufacturers with FAA-certified material pedigree. Three archetypes dominate: backward-integrated precursor producers, thermoplastic technology specialists, and commodity-grade industrial fiber suppliers. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines compress.
Among U.S.-based producers, Hexcel Corporation and Zoltek Companies exemplify distinct scale-positioning strategies within the aerospace and industrial tiers respectively. Toray Composite Materials America anchors the Japanese multinational presence through its Alabama precursor integration. Solvay Composite Materials and SGL Carbon represent European-origin specialty chemical and carbon material specialists competing on thermoset and thermoplastic format diversity.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Composite Materials America |
| Teijin Carbon America |
| Solvay Composite Materials |
| Zoltek Companies |
| SGL Carbon |
| Mitsubishi Chemical Group |
| Syensqo |
| HS Hyosung Advanced Materials |
| Others |
Value Chain & Pricing Dynamics
Thermoplastic unidirectional tape adoption is compressing autoclave curing economics while concentrating procurement leverage among Boeing and Airbus tier-one suppliers in Kansas and Washington State. This manufacturing transition simultaneously reduces batch processing scale requirements and elevates qualification barriers, reshaping how fiber allocation prioritizes certified aerospace contracts over automotive spot demand.
Pricing Analysis
Technical service bundling separates aerospace-grade prepreg contracts from commodity dry fiber transactions, with FAA-certified material pedigree commanding substantial premiums over uncertified industrial grades. Three-tier pricing structure across certified aerospace, automotive-qualified, and commodity industrial levels reflects differentiation by qualification investment and traceability documentation. Cost compression in automotive-grade fiber is intensifying because Michigan-Ontario EV platform procurement competes for limited qualified supply. Tier-two automotive converters demonstrate highest price sensitivity; Boeing tier-one suppliers exhibit lowest sensitivity due to pass-through contract structures.
Supply Chain Analysis
Dual-sourcing mandates from Lockheed Martin and Boeing tier-one procurement specifications are consolidating order books around qualified precursor-integrated producers in Alabama and Utah. Geographic supply concentration centers on United States carbonization capacity with Canadian wind blade manufacturers seeking domestic alternatives to trans-Pacific logistics. Raw material dependencies draw from petroleum-derived acrylonitrile, polyacrylonitrile precursor, and specialized epoxy resin formulations. Single-source vulnerability concentrates in oxidation oven equipment supply, constraining geographic diversification of new capacity. Distribution runs through southeastern U.S. prepreg converters serving aerospace final assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American carbon fiber manufacturing is consolidating around precursor-integrated producers as FAA qualification timelines and EPA emission compliance costs eliminate marginal non-integrated capacity.
For Market Incumbents: Anticipate thermoplastic composite qualification acceleration by securing dedicated technical service teams for Boeing and Airbus tier-one suppliers in Kansas and Washington State. Deepen backward integration into Alabama and Utah precursor production to defend margin position against acrylonitrile price volatility. Prioritize oxidation oven capacity expansion over greenfield carbonization investments to capture allocation priority from supply-constrained competitors. For New Entrants and Emerging Players: Launch via direct supply partnerships with Ontario and Quebec wind turbine blade manufacturers seeking domestic fiber alternatives to Asian imports. Target hydrogen pressure vessel applications for heavy-duty transport as the most penetrable high-modulus fiber segment outside aerospace certification barriers. Pursue thermoplastic composite specialization as the primary go-to-market angle, bypassing thermoset qualification bottlenecks that protect incumbent market positions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Japanese or European multinational chemical conglomerates seeking North American aerospace certification assets. Long-term viability favors producers with captive precursor supply and established FAA material pedigree over commodity-grade industrial fiber specialists. Monitor EPA enforcement patterns around acrylonitrile emission standards as the critical inflection indicator for forced capacity rationalization among non-compliant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply in Alabama and Utah insulates margin stability from petroleum feedstock volatility. |
| Thermoplastic Composite Qualification Investment | FAA certification for unidirectional tapes enables faster adoption in Boeing and Airbus non-critical structures. |
| Oxidation Oven Capacity Expansion | Equipment availability constraints in legacy corridors limit geographic diversification of new carbonization facilities. |
| Long-term Supply Agreement with Tier-One Suppliers | Minimum volume commitments from Kansas and Washington State converters secure fiber allocation priority. |
| Joint Venture with Canadian Wind Blade Manufacturers | Ontario and Quebec developers seek domestic supply security against trans-Pacific logistics exposure. |
Study Parameters
Document review covered FAA certification databases, EPA National Emission Standards filings, and SEC 10-K disclosures from publicly traded composite manufacturers, complemented by interviews with carbonization plant managers, aerospace tier-one procurement directors, automotive OEM materials engineers, and precursor supply specialists. Secondary validation drew from U.S. Census Bureau trade data, American Chemistry Council reports, and Health Canada PMRA emission evaluations. Bottom-up fiber demand modeling triangulated against top-down aerospace and automotive production forecasts.
Segment-level projections across continuous fiber, prepreg, short fiber, and fabric formats were generated through analysis window modeling incorporating propulsion architecture evolution, content-per-vehicle trajectories, and regional production cluster shifts. CAGRs were derived from regression analysis against historical aerospace build rates and automotive platform refresh timelines. Key forecast inputs included Boeing and Airbus delivery schedules, NHTSA fuel economy compliance pathways, and hydrogen storage system adoption curves for heavy-duty transport.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic composite consolidation would alter the outlook if FAA qualification timelines compress faster than baseline assumptions. Forecasts reflect documented assumptions regarding EPA enforcement intensity and acrylonitrile price volatility. Deviation in FAA certification priority for thermoplastic formats would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Basalt Fiber Market
Fibers
Global Nylon Monofilament Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Viscose Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Global R-Glass Fiber Market
Fibers
Vinylon Market
Fibers
Bioglass Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Global Fiberglass Market
Fibers
Triacetate Cellulose Market
Fibers
Viscose Staple Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market