
 High Temperature Superconducting Fibers Market | 2026-2036
High Temperature Superconducting Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Superconducting Fibers Market Outlook
Modular coil configurations for MRI machines is shifting procurement patterns toward pre-assembled superconducting subsystems rather than raw fiber purchases. Sumitomo Electric Industries leverages its vertical integration from wire drawing to cable assembly to dominate magnet-grade supply chains. Bruker Energy & Supercon Technologies anchors its position through specialized R&D intensity in niobium-titanium formulations for research magnets. Fujikura competes by extending its optical fiber manufacturing expertise into precision-coated conductor architectures for power transmission.
High temperature superconducting fibers are ceramic or alloy-composite conductors engineered to exhibit zero electrical resistance at temperatures achievable with liquid nitrogen cooling, typically formulated from yttrium-barium-copper-oxide or magnesium diboride compositions through metal-organic deposition or powder-in-tube processing. Their primary industrial purpose centers on enabling compact, high-field electromagnets and loss-free power cables that conventional copper cannot match. Coated conductors command the dominant value share due to their superior current-carrying capacity in high magnetic fields, while MgB2 fibers represent the fastest-expanding category as lower-cost alternatives for medium-field applications. Energy storage applications concentrate emerging margin pools where grid-scale magnetic energy storage prototypes demand customized fiber geometries.
FDA device regulations govern superconducting fiber integration into commercial MRI systems, while the EU F-Gas Regulation and REACH frameworks restrict cryogenic coolant chemistries and mandate material traceability across European supply chains. Japan's METI standards for superconducting power equipment create additional compliance thresholds for grid-connected installations. Stakeholders must monitor how evolving national superconducting grid demonstration programs alter qualification timelines and volume commitments before committing to capacity expansion.
Market Dynamics
Modular coil configurations for MRI machines are shifting procurement patterns toward pre-assembled superconducting subsystems rather than raw fiber purchases, compressing margins for standalone fiber suppliers while elevating system integrators.
Growth Catalysts
- The EU F-Gas Regulation:Tightening requirements for energy-efficient power infrastructure are accelerating grid-scale superconducting cable demonstrations across European utilities.
- MRI machine installations:Healthcare systems in Germany and Japan are expanding high-field magnet capacity, driving coated conductor demand for compact electromagnet designs.
- MgB2 fiber processing:Powder-in-tube manufacturing advances are lowering production costs for medium-field applications, opening industrial motor and generator markets previously blocked by yttrium-barium-copper-oxide economics.
Market Restraints
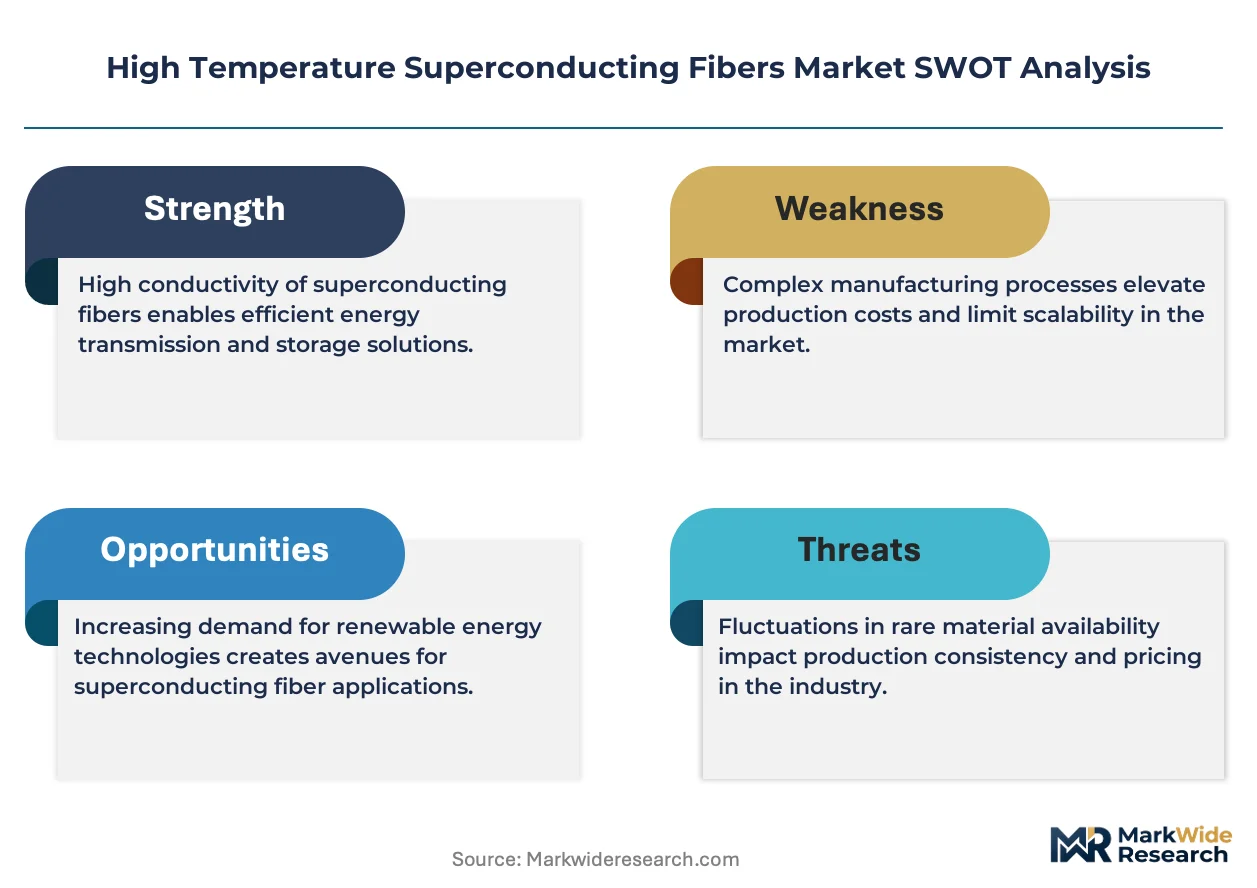
- Silver substrate costs:Coated conductor architectures require precious metal buffer layers, exposing manufacturers to London Bullion Market Association price volatility that erodes fabrication margins.
- Cryogenic coolant chemistry restrictions:The EU REACH framework limits perfluorinated compound formulations used in liquid nitrogen production, forcing supply chain requalification.
- Helium-4 supply concentration:Qatar and the United States control over 75% of global helium refining capacity, creating input risk for low-temperature superconducting hybrid systems.
Strategic Opportunities
- Grid-scale magnetic energy storage:Prototype installations in South Korea and Italy are demanding customized fiber geometries for loss-free energy cycling.
- Japan's METI superconducting power equipment standards:New certification pathways for grid-connected installations are creating first-mover advantages for qualified suppliers.
- Additive manufacturing convergence:Laser powder bed fusion of niobium-titanium composites is enabling complex magnet geometries impossible through conventional wire drawing.
Industry Challenges
- Thin-film deposition technician scarcity:Metal-organic chemical vapor deposition expertise concentrates in legacy semiconductor clusters, constraining coated conductor capacity expansion.
- FDA 510(k) certification timelines:Superconducting fiber integration into commercial MRI systems requires 18-24 month qualification cycles that lock working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Superconducting Fibers Market |
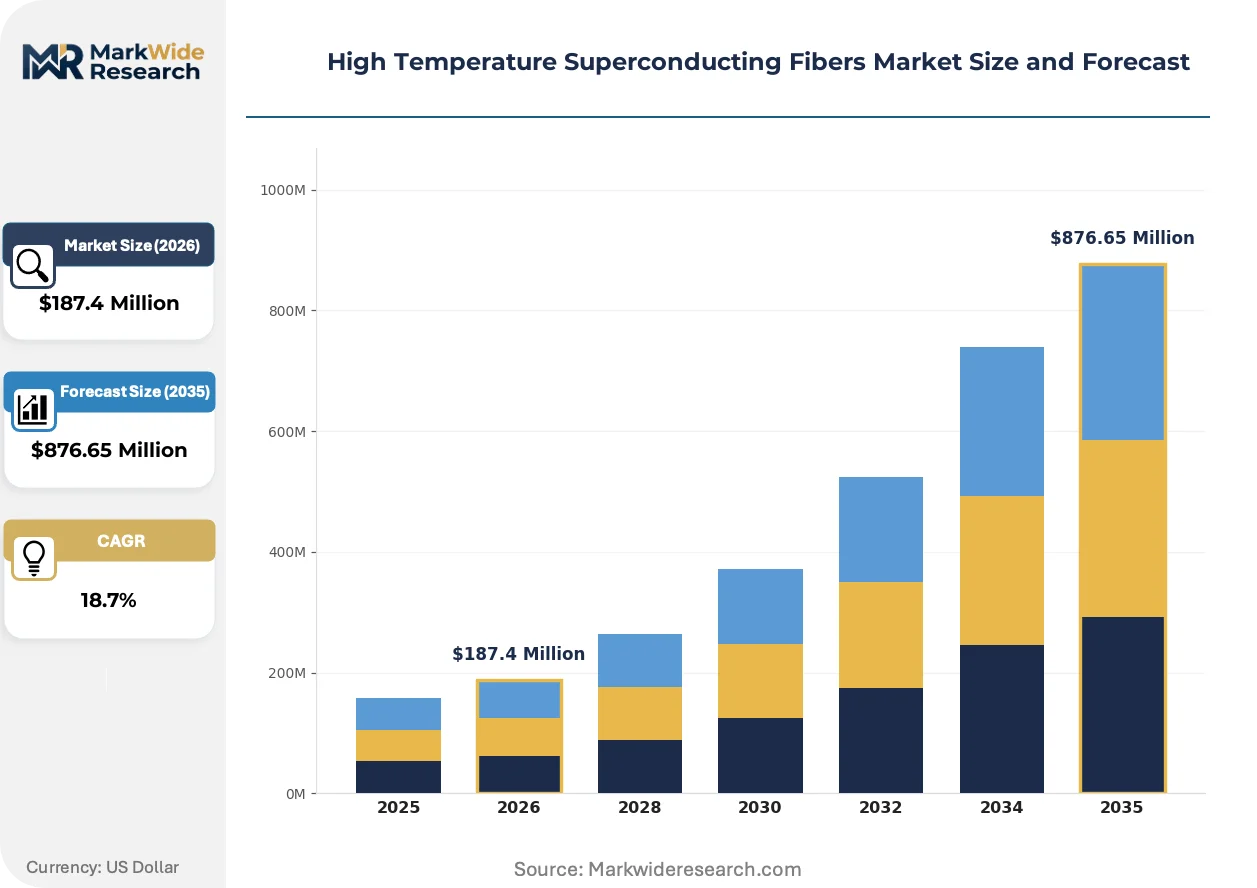
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Conductors, YBCO Fibers, NbTi Wires, MgB2 Fibers Application: Power Transmission, MRI Machines, Magnets, Energy Storage End User: Healthcare, Aerospace, Energy Sector, Research Institutions Distribution Channel: Direct Sales, Distributors, Online, Retailers |
| Companies Covered | American Superconductor Corporation, Bruker Energy & Supercon Technologies, Hyper Tech Research, Superconductor Technologies, SuperPower, Sumitomo Electric Industries, Furukawa Electric, Fujikura, THEVA Dünnschichttechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Superconducting Fibers Market Strategic Shifts
Processing technologies and regulatory frameworks are compressing the gap between laboratory performance and industrial reliability, enabling superconducting fiber deployment beyond niche research applications.
Reel-to-reel metal-organic deposition is unifying buffer layer and superconducting film growth into continuous inline processes. Equipment suppliers in Germany and Japan are retrofitting optical fiber draw towers for kilometer-length coated conductor production. This consolidation is collapsing unit costs for high-field magnets and eroding the cost advantage of copper-based alternatives in premium MRI segments.
The EU Green Deal's 2030 decarbonization targets are mandating transmission loss reductions that conventional aluminum-copper composites cannot achieve. Grid operators in Denmark and the Netherlands are procuring superconducting cable pilot projects under revised network code exemptions. Manufacturers are responding with magnesium diboride formulations optimized for 20-30 Kelvin operation using closed-cycle cryocoolers.
Healthcare procurement groups are consolidating magnet purchases through multi-hospital framework agreements that specify total-cost-of-ownership metrics rather than capital expenditure alone. Equipment lessors in the United States are bundling cryogen management and field service into 10-year operating contracts. This shift favors suppliers with captive service networks over component-only vendors.
High Temperature Superconducting Fibers Market Segmentation
Superconducting fiber procurement splits sharply between standardized commodity grades and application-engineered specifications. Coil manufacturers demand geometrically precise conductor architectures that raw fiber suppliers cannot deliver without subsystem integration.
Product Type:
Customization intensity varies from fully engineered coated conductor stacks to semi-standardized MgB2 round wires, with cost and field performance determining where buyers land on this spectrum.
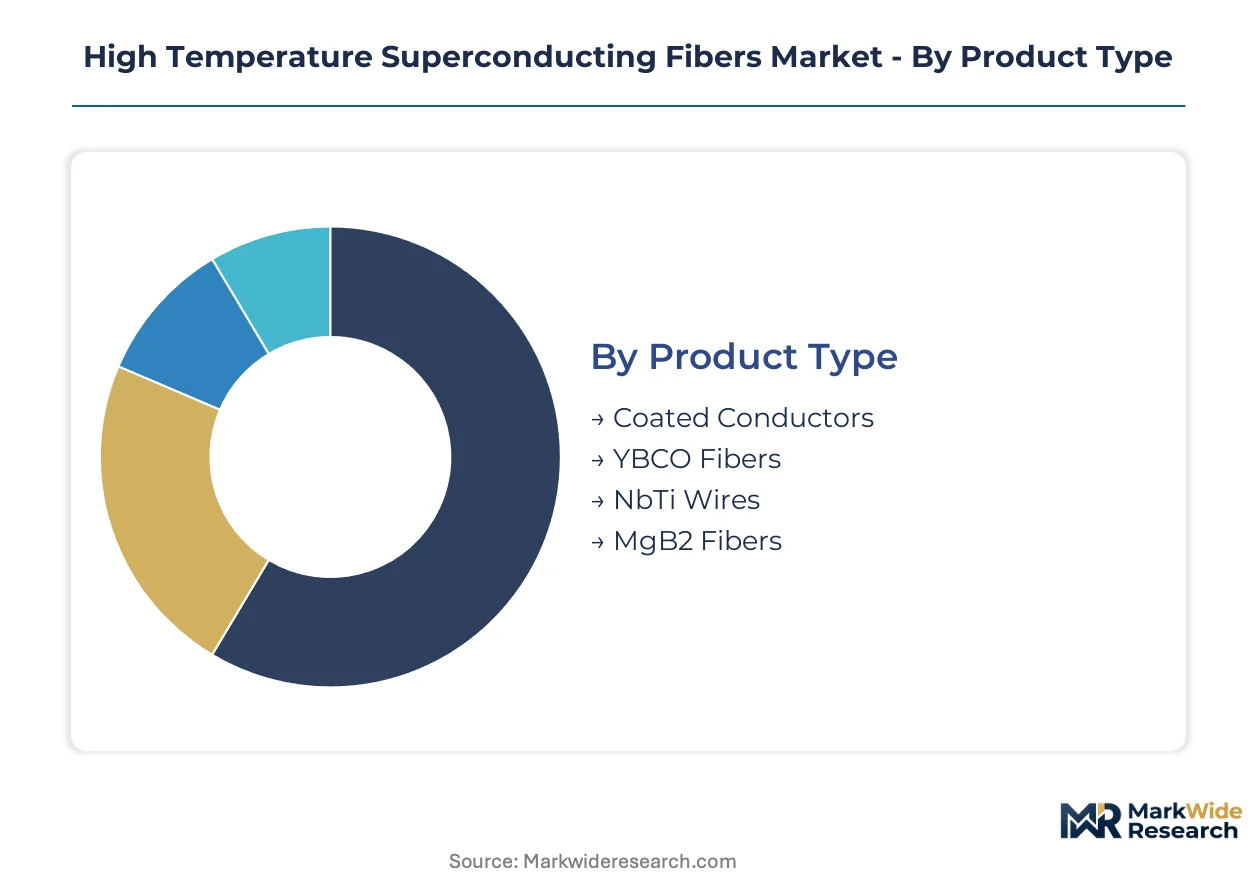
- Coated Conductors:Multi-layer thin-film architectures combining silver-buffered hastelloy substrates with yttrium-barium-copper-oxide superconducting films deposited via metal-organic chemical vapor deposition. Germany's THEVA Dünnschichttechnik GmbH concentrates production capacity here for high-field MRI magnets where current density requirements exclude alternatives.
- MgB2 Fibers:Magnesium diboride composite conductors manufactured through powder-in-tube processing, offering medium-field performance at cryocooler-accessible temperatures. Industrial motor manufacturers in Japan are adopting these for 20-30 Kelvin operating regimes previously uneconomical with YBCO formulations.
- YBCO Fibers:Textured ceramic filaments demanding precise oxygen annealing protocols for critical current optimization.
- NbTi Wires:Niobium-titanium alloys serving as workhorse conductors for research magnets and hybrid systems requiring helium-4 cooling infrastructure.
Most installed capacity flows through coated conductors. Expansion is steepest in MgB2 fibers.
Application:
Volume concentration tilts toward established medical imaging infrastructure while emerging grid applications command premium engineering margins.
- MRI Machines:Compact superconducting magnets for diagnostic imaging systems require precisely dimensioned racetrack coils with persistent current joints. FDA 510(k) certification cycles and helium-4 supply constraints shape procurement timelines for magnet OEMs.
- Energy Storage:Grid-scale magnetic energy storage prototypes in South Korea and Italy demand customized fiber geometries for loss-free energy cycling between superconducting coils and power conditioning systems.
- Power Transmission:Underground superconducting cable demonstrations under EU F-Gas Regulation exemptions.
- Magnets:Research and industrial separation systems with field strength requirements spanning 2-20 Tesla.
Healthcare procurement dominates current offtake. Energy storage projects are gaining share fastest.
End User:
Customer sophistication ranges from institutional research laboratories specifying raw conductor properties to healthcare systems purchasing fully integrated magnet subsystems.
- Healthcare:Hospital networks and imaging center operators procuring through multi-hospital framework agreements that bundle cryogen management into decade-long operating contracts.
- Energy Sector:Grid operators in Denmark and the Netherlands piloting superconducting cable installations under revised network code exemptions.
- Research Institutions:National laboratories and university facilities with in-house magnet engineering capabilities.
- Aerospace:Specialized defense and space applications requiring radiation-hardened conductor formulations.
Healthcare systems absorb the largest volume share. Energy sector procurement is expanding most quickly.
Distribution Channel:
Channel selection tracks order complexity and technical support requirements from standardized wire spools to fully engineered coil assemblies.
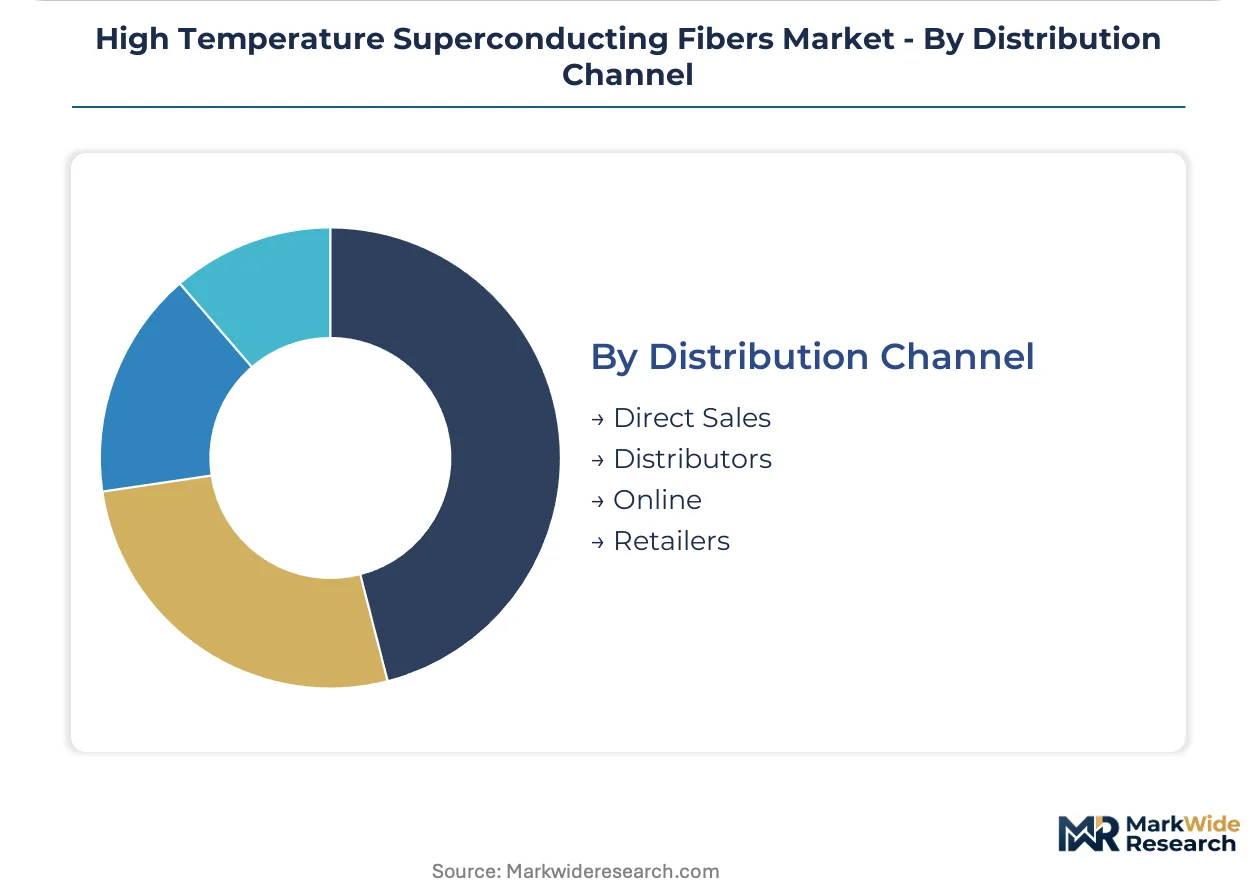
- Direct Sales:Magnet OEMs and cable manufacturers negotiate directly with fiber producers for volume commitments and geometric customization.
- Distributors:Regional stocking intermediaries serving research institutions and smaller industrial users with standard wire gauges.
- Online:Catalog sales for experimental quantities and replacement spools.
- Retailers:Minimal presence limited to educational and demonstration quantities.
Direct sales channels handle the majority of volume. Distributor networks are expanding fastest to serve fragmented research demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High temperature superconducting fiber manufacturing originated in Japan during the 1980s oxide-ceramic breakthroughs, then migrated to German precision-coating expertise and American power-grid demonstration projects. Today production clusters concentrate where cryogenic engineering infrastructure and magnet-system integration capabilities overlap.
Japan
METI superconducting power equipment standards drive grid-connected installation demand while powder-in-tube processing advances lower MgB2 fiber costs for industrial motor applications. Tokyo and Osaka host the dominant coated conductor research clusters where metal-organic deposition expertise concentrates in legacy semiconductor facilities.
Germany
EU F-Gas Regulation exemptions accelerate superconducting cable pilot procurement across Danish and Dutch grid operators sourcing through German manufacturing channels. Bavaria anchors European coated conductor capacity where THEVA Dünnschichttechnik GmbH operates kilometer-length production lines retrofitted from optical fiber draw towers.
United States
FDA 510(k) certification cycles shape MRI magnet procurement timelines while equipment lessors bundle decade-long cryogen management contracts favoring captive service networks. Massachusetts and California concentrate superconducting subsystem integrators serving consolidated healthcare procurement groups.
South Korea
Grid-scale magnetic energy storage prototypes demand customized fiber geometries for loss-free energy cycling between superconducting coils and power conditioning systems. Seoul-based research institutes collaborate with Italian counterparts on demonstration installations under revised network code frameworks.
China
Dual carbon goals mandate transmission loss reductions beyond aluminum-copper composite capabilities while MIIT standards evolve for superconducting power equipment certification. Shanghai and Beijing industrial zones attract reel-to-reel metal-organic deposition equipment retrofits for domestic coated conductor scale-up.
High Temperature Superconducting Fibers Market Competitive Environment
The competitive structure tilts toward vertically integrated magnet-system suppliers over standalone fiber manufacturers. Three tiers have crystallized: global conglomerates with captive cryogenic service networks, regional specialists in powder-in-tube MgB2 processing, and research-laboratory spinouts commercializing novel deposition protocols. Capacity expansion and strategic technology licensing dominate competitive moves as qualification timelines lock working capital.
Among Japanese industrial conglomerates, Sumitomo Electric Industries and Fujikura occupy positions spanning wire drawing through cable assembly, representing the integrated-system archetype. Bruker Energy & Supercon Technologies exemplifies the R&D-intensive specialist model anchored in niobium-titanium formulations. American Superconductor Corporation sits within the power-grid demonstration tier where utility-scale project execution determines supplier selection.
| Leading Market Players |
|---|
| American Superconductor Corporation |
| Bruker Energy & Supercon Technologies |
| Hyper Tech Research |
| Superconductor Technologies |
| SuperPower |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Fujikura |
| THEVA Dünnschichttechnik GmbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned precision-coating specialists in Germany and Japan anchor coated conductor production, creating supply discipline that resists spot-price volatility even when silver substrate costs spike. Their long-tenured relationships with MRI magnet OEMs lock in multi-year offtake contracts with built-in raw material pass-through clauses, insulating margins while compressing bargaining power for buyers outside consolidated healthcare procurement groups.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified magnet-grade coated conductors from industrial MgB2 fibers and research-laboratory surplus spools. Price differentiation hinges on helium-4 cooling infrastructure bundling and METI certification tier for grid-connected installations. Cost compression in economy-grade MgB2 round wire is intensifying because powder-in-tube processing advances collapse unit economics for medium-field industrial motors. Healthcare systems purchasing through multi-hospital framework agreements exhibit lowest price sensitivity, while fragmented research institutions drive hardest volume discounts.
Supply Chain Analysis
Silver substrate supply rests on London Bullion Market Association trading desks and German precious metal refiners, with hastelloy tape drawing concentrated in Japanese specialty steel mills and Bavarian precision-metal workshops. Reel-to-reel metal-organic deposition equipment feeds from legacy semiconductor fabrication clusters in Tokyo, Osaka, and Munich. Single-source vulnerability concentrates in helium-4 refining where Qatar and the United States control over three-quarters of global capacity. Distribution runs through direct sales channels for magnet OEMs and cable manufacturers, with regional distributors serving fragmented research demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coated conductor specifications for high-field MRI magnets represent a late-cycle quality story as healthcare procurement shifts toward total-cost-of-ownership metrics that favor premium subsystem integrators over commodity fiber suppliers.
For Market Incumbents: Anchor position through captive cryogenic service networks spanning helium-4 logistics and field magnet maintenance, locking out standalone fiber vendors from decade-long hospital operating contracts. Add powder-in-tube MgB2 capacity in Japan to intercept industrial motor demand before lower-cost Chinese entrants qualify under evolving MIIT standards. Defend against Sumitomo Electric Industries' backward integration into cable assembly by securing exclusive racetrack coil jointing IP. For New Entrants and Emerging Players: The gap between premium FDA-certified coated conductors and economy-grade research spools offers entry space for MgB2 fiber specialists targeting 20-30 Kelvin industrial generator retrofits. South Korean grid-scale magnetic energy storage prototypes present the most penetrable geography, with Italian demonstration projects under EU network code exemptions validating technical specifications. Pursue joint development agreements with Seoul-based research institutes rather than direct magnet OEM competition. For Investors and Strategic Acquirers: Valuations sit cheapest among reel-to-reel deposition equipment suppliers retrofitting optical fiber draw towers, where technical capability scarcity meets capital-light scale-up potential. Five-to-ten year viability hinges on superconducting cable procurement acceleration under EU F-Gas Regulation tightening. Watch South Korean and Italian energy storage demonstration commissioning timelines as inflection indicators for grid-scale demand materialization.| Strategic Initiative | Industry Significance |
|---|---|
| Reel-to-Reel Deposition Scale-Up | Retrofitting optical fiber towers collapses coated conductor unit costs for MRI magnet OEMs. |
| Powder-in-Tube Process Advancement | MgB2 fiber cost reduction opens industrial motor markets previously blocked by YBCO economics. |
| Cryogenic Service Network Expansion | Captive helium-4 logistics and field maintenance lock in decade-long hospital operating contracts. |
| Grid-Connected Certification Pathway | METI and EU network code qualification creates first-mover advantage for utility-scale cable suppliers. |
| Magnetic Energy Storage Joint Development | Seoul and Rome demonstration projects validate customized fiber geometries for loss-free cycling. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MRI magnet OEM procurement directors, superconducting cable project developers at European utilities, powder-in-tube process engineers at Japanese industrial conglomerates, and hospital GPO contract managers with secondary validation against FDA 510(k) filings, METI certification databases, EU F-Gas Regulation exemption records, and SEC disclosures from listed superconducting equipment suppliers. Bottom-up fiber volume estimates triangulated against top-down healthcare imaging infrastructure deployment data.
Across the analysis window, projections anchored to historical coated conductor and MgB2 fiber deployment trajectories through segmented modeling by product architecture, application end-use, cooling infrastructure requirement, and regional regulatory cluster. CAGRs derived from curve-fitting installation ramp rates against superconducting grid demonstration program announcements. Forecast inputs incorporated silver price volatility bands and helium-4 supply concentration risk premiums.
Caveats apply where FDA 510(k) certification timeline extensions or EU REACH cryogenic coolant chemistry restrictions could materially shift the outlook for magnet-grade fiber demand. A small set of named triggers warrants ongoing watch: South Korean energy storage commissioning schedules, Chinese MIIT standard finalization, and Qatar helium-4 export policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Metal Fiber Felt Market
Fibers
Acoustical Fiber Board Market
Fibers
Viscose Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Global Fiberglass Mold Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Fiber Intermediates Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
High Performance Fibers for Defense Market
Fibers
Triacetate Cellulose Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Viscose Staple Fiber Market
Fibers
Carbon Fiber Filament Market
Fibers
Sisal Market