
 Renewable Carbon Fibers Market | 2026-2036
Renewable Carbon Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Carbon Fibers Market Analytics
Direct supply agreements between precursor producers and aerospace tier suppliers is rewriting procurement patterns for renewable carbon fibers. Toray Industries leverages its integrated precursor-to-prepreg chain to sustain long-term contracts with Japanese and European airframers. Solvay anchors its position through proprietary thermoplastic resin systems compatible with bio-based fiber grades. Zoltek Companies, Inc. competes on cost at industrial scale, dominating large-tow formats for wind and automotive applications.
Renewable carbon fibers comprise filaments derived from lignin, cellulose, or bio-based acrylonitrile precursors, typically achieving tensile modulus above 230 GPa and serving as lightweight reinforcement in structural composites. Their primary commercial purpose centers on displacing petroleum-derived fibers in applications where Scope 3 emissions reporting creates procurement pressure. Thermoplastic formats are gaining fastest as recyclability mandates harden across European automotive supply chains, while thermoset grades still occupy the bulk of aerospace qualification pathways. Biocomposite segments lead margin pools where construction and consumer goods buyers prioritize visible sustainability credentials over performance parity.
The EU Green Deal, REACH, and FDA biocompatibility frameworks collectively shape fiber qualification timelines and end-market access, with REACH substance restrictions forcing reformulation of sizing chemistries and FDA pathways opening medical device applications. Germany's national implementation of EU taxonomy rules adds a secondary compliance layer for suppliers targeting automotive OEMs headquartered in Bavaria and Baden-Württemberg. Stakeholders must monitor evolving precursor certification schemes and pre-emptively secure mass-balance chain-of-custody documentation before customer mandates crystallize.
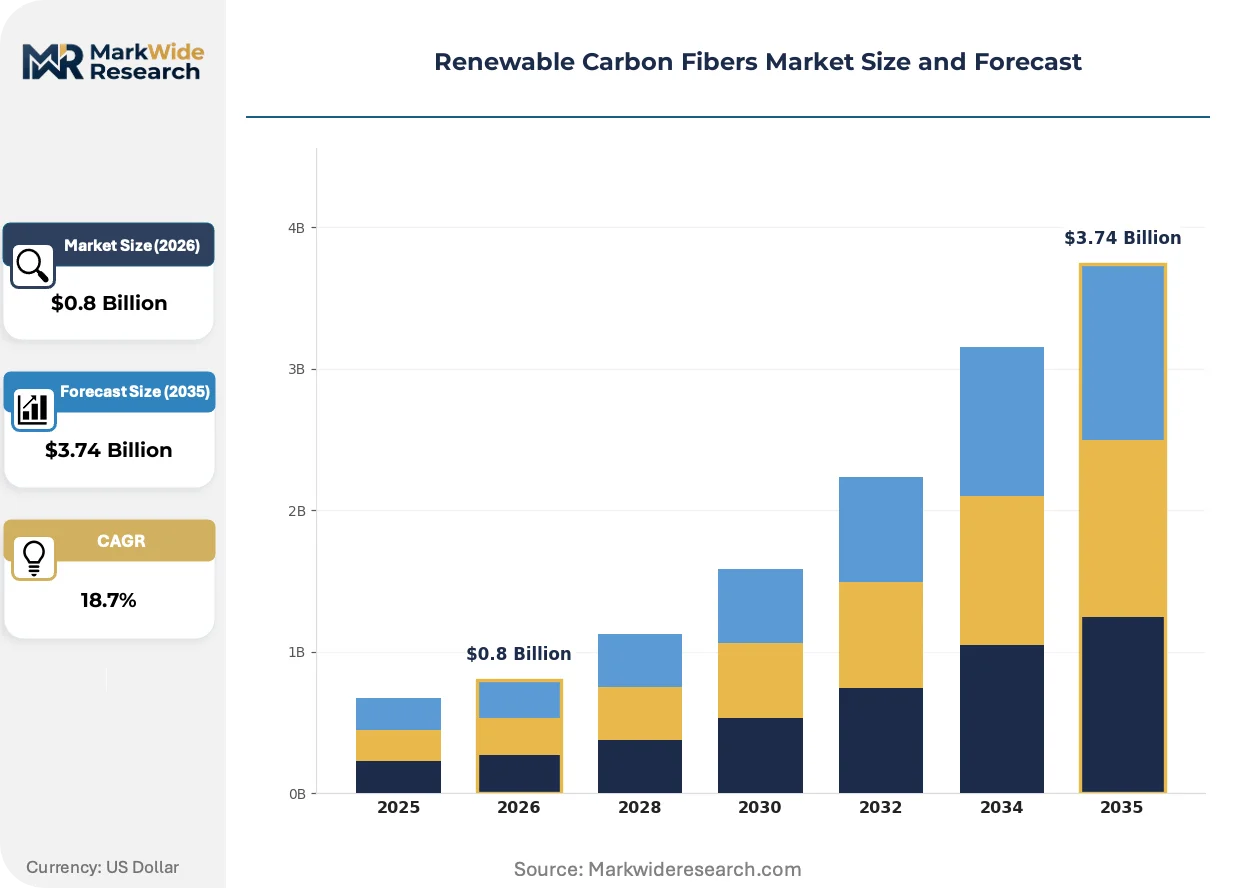
Market Dynamics
REACH substance restrictions and EU Green Deal carbon footprint thresholds are forcing reformulation of sizing chemistries across the renewable carbon fiber supply chain, compressing qualification timelines and redrawing procurement relationships between precursor producers and aerospace tier suppliers.
Growth Catalysts
- EU Green Deal compliance mandates:Automotive OEMs in Germany now require mass-balance chain-of-custody documentation for bio-based reinforcement materials, accelerating supplier certification investments.
- Thermoplastic format adoption:Recyclability mandates across European automotive supply chains are pulling demand toward melt-processable fiber grades compatible with automated fiber placement.
- Aerospace Scope 3 reporting pressure:Airframers face disclosure requirements for embodied carbon in structural composites, creating procurement pull for lignin-derived precursors.
Market Restraints
- Precursor yield volatility:Lignin purification energy intensity and agricultural feedstock price swings compress margins for bio-based acrylonitrile alternatives.
- Japanese precursor concentration:Toray Industries and Mitsubishi Chemical control PAN precursor supply for aerospace-qualified grades, creating bottleneck risk for new renewable entrants.
- Performance parity gaps:Cellulose-derived fibers exhibit modulus variability above 5% versus petroleum benchmarks, limiting load-bearing structural applications.
Strategic Opportunities
- Indian industrial scaling:Reliance Industries and Aditya Birla Group are piloting lignin fiber production for domestic wind blade and automotive component markets.
- Construction biocomposite penetration:Visible sustainability credentials in building facades and interior panels command 15-20% procurement premiums over glass fiber alternatives.
- FDA biocompatibility pathway expansion:Medical device manufacturers are qualifying cellulose-derived fibers for orthopedic implants and surgical instruments.
Industry Challenges
- Carbonization furnace capex intensity:Continuous carbonization line installation requires $50-80 million per 1,000-ton annual capacity, constraining mid-scale producer expansion.
- Aerospace qualification timeline compression:OEM specification lock-in cycles extend 7-10 years, forcing renewable fiber suppliers to front-load R&D against uncertain volume commitments.
- Sizing chemistry reformulation complexity:REACH substance restrictions on epoxy-based sizings demand simultaneous fiber-matrix compatibility testing across thermoplastic and thermoset resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Carbon Fibers Market |
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $3.74 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermoset, Biocomposite, Hybrid End User: Aerospace, Automotive, Sports Equipment, Construction Application: Reinforcement, Insulation, Structural Components, Consumer Goods Technology: Pultrusion, Filament Winding, Compression Molding, Resin Transfer Molding |
| Companies Covered | Trillium Renewable Chemicals, Solvay, Zoltek Companies, Inc., Toray Industries, Cargill, Carbon Clean Solutions, Mitsubishi Chemical Carbon Fiber and Composites, Carbon Conversions, Hexcel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Carbon Fibers Market Evolving Landscape
Electrification of industrial carbonization processes and AI-driven precursor quality control are compressing energy intensity and yield variability in renewable fiber production, while regulatory frameworks harden recyclability mandates across automotive and wind energy supply chains.
Microwave-assisted carbonization technology is collapsing energy consumption per kilogram of finished fiber by 30-40% versus conventional furnace systems. Pilot installations at Swedish and German production facilities are achieving tow-tensile consistency within 3% variation. This thermal efficiency gain is collapsing the production cost gap between lignin-derived and petroleum-based precursors for industrial-grade applications.
EU CSRD disclosure requirements and REACH authorization timelines are forcing composite manufacturers to document Scope 3 emissions across tier-three suppliers. German automotive OEMs headquartered in Bavaria and Baden-Württemberg now mandate renewable content percentages in structural component specifications. Suppliers without mass-balance certification face exclusion from 2027 model-year platform bids.
Direct offtake agreements between wind turbine manufacturers and fiber producers are displacing distributor-mediated procurement in the multi-tow industrial segment. Vestas and Siemens Gamesa are locking 3-5 year supply contracts with renewable fiber specialists for blade spar cap applications. This channel consolidation is most visible in Denmark and northern Germany, where blade production clusters sit adjacent to carbonization pilot facilities.
Renewable Carbon Fibers Market Segmentation
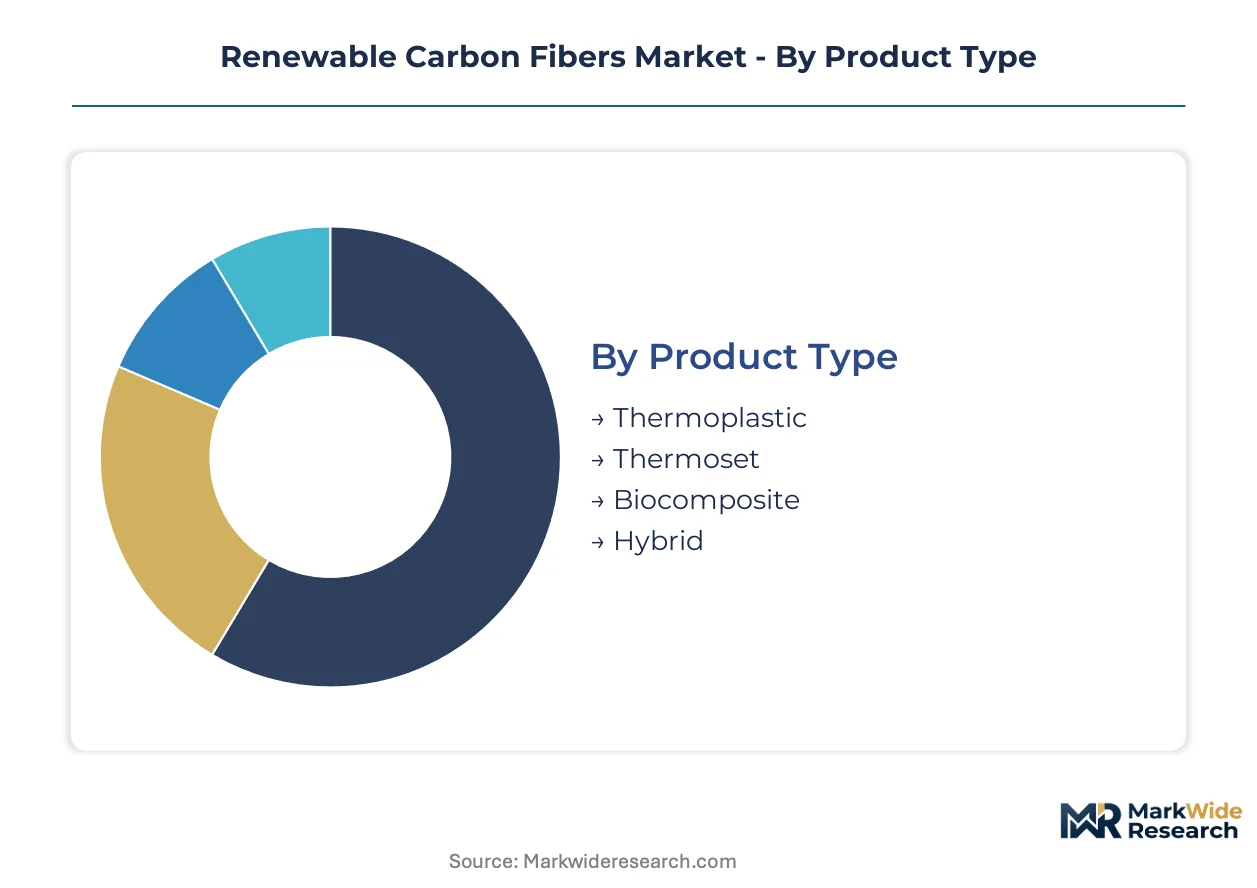
Renewable carbon fiber segmentation reveals how precursor chemistry, processing format, and end-use qualification requirements create distinct commercial battlegrounds. Each dimension carries different margin structures, certification barriers, and customer concentration patterns that reshape supplier strategy.
Product Type:
Thermoset formats dominate mature aerospace pathways, while thermoplastic grades emerge fastest as automotive recyclability mandates harden across European supply chains.
- Thermoplastic:Melt-processable fiber grades compatible with automated fiber placement and in-situ consolidation. German automotive OEMs in Bavaria and Baden-Württemberg now mandate thermoplastic formats for structural components to satisfy EU end-of-life vehicle directives. Recyclability without pyrolysis drives procurement premiums.
- Thermoset:Epoxy-compatible fiber sizings qualified through aerospace OEM specification lock-in cycles spanning 7-10 years. REACH substance restrictions on conventional sizing chemistries force simultaneous reformulation across multiple resin systems, compressing supplier margins.
- Biocomposite:Natural fiber hybrids targeting visible sustainability credentials in construction facades and consumer goods, commanding procurement premiums over glass fiber alternatives.
- Hybrid:Blended petroleum and bio-based fiber architectures bridging performance parity gaps in load-bearing applications.
Thermoset handles the majority of throughput; thermoplastic is the fastest mover on share.
End User:
Customer concentration varies sharply by qualification intensity, with aerospace demanding decade-long certification cycles and construction rewarding rapid sustainability messaging.
- Aerospace:Airframers face Scope 3 emissions disclosure requirements for embodied carbon in structural composites. Lignin-derived precursors gain traction in secondary structures where modulus variability above 5% is tolerable.
- Automotive:OEM procurement clusters around Stuttgart and Munich drive demand for mass-balance chain-of-custody documentation. Suppliers without certification face exclusion from platform bids.
- Sports Equipment:Premium bicycle frames and racing equipment prioritize weight reduction with visible bio-based branding.
- Construction:Building facade panels and interior systems command 15-20% procurement premiums where sustainability credentials are specified.
Automotive generates the highest volume throughput; aerospace maintains the steepest pricing tier.
Application:
Functional role determines fiber modulus requirements and matrix compatibility constraints across industrial and consumer markets.
- Reinforcement:Primary load-bearing applications in wind blade spar caps and automotive structural members. Direct offtake agreements between Vestas, Siemens Gamesa, and fiber producers displace distributor channels in Denmark and northern Germany.
- Insulation:Thermal and electrical barrier applications with lower modulus thresholds, enabling broader bio-based precursor acceptance.
- Structural Components:Load-bearing assemblies requiring tensile modulus above 230 GPa, limiting cellulose-derived fiber penetration.
- Consumer Goods:Electronics housings and lifestyle products where visible sustainability credentials outweigh performance parity requirements.
Reinforcement absorbs the dominant share of industrial fiber output; consumer goods expands most quickly as sustainability labeling proliferates.
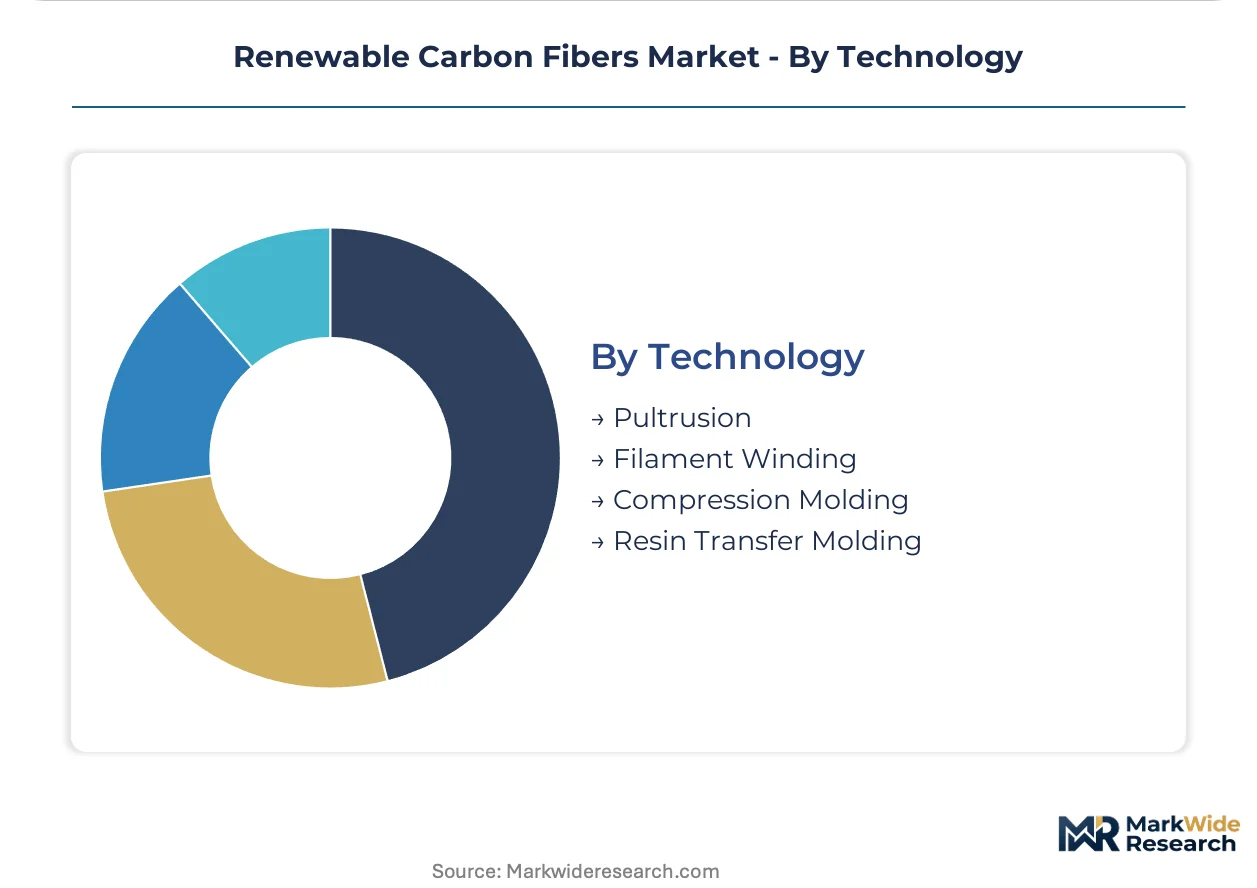
Technology:
Processing method selection hinges on part geometry complexity, production rate requirements, and fiber format compatibility.
- Pultrusion:Continuous profile manufacturing for construction and industrial applications. Swedish and German facilities achieve tow-tensile consistency within 3% variation using microwave-assisted carbonization.
- Filament Winding:Pressure vessel and pipe manufacturing with high fiber volume fractions. Wind blade spar cap production clusters in Denmark leverage this format for renewable fiber integration.
- Compression Molding:Automotive structural component production with short cycle times. Compatible with both thermoplastic and thermoset fiber formats.
- Resin Transfer Molding:Complex geometry aerospace parts requiring precise fiber placement and void control.
Pultrusion handles the bulk of industrial throughput; filament winding gains share fastest in wind energy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's carbon-neutral logistics corridor underwrites Europe's renewable carbon fiber trade flows, connecting German automotive clusters to Atlantic precursor suppliers. This infrastructure backbone positions the continent as the primary demand center for bio-based reinforcement materials.
Germany
Automotive OEM procurement concentrates around Stuttgart and Munich, with BMW and Mercedes-Benz mandating mass-balance chain-of-custody documentation for structural composites. The EU Green Deal's carbon footprint thresholds, enforced through Germany's national taxonomy implementation, compress supplier qualification timelines. Bavarian and Baden-Württemberg production clusters now host pilot carbonization facilities serving tier-one automotive suppliers.
United States
FDA biocompatibility pathways open medical device applications for cellulose-derived fibers, with orthopedic implant manufacturers in Massachusetts and Minnesota driving qualification programs. The EPA's emerging focus on embodied carbon in federal procurement creates pull for lignin-based precursors. Wind blade production clusters in Iowa and Colorado anchor direct offtake agreements with renewable fiber specialists.
Japan
Toray Industries and Mitsubishi Chemical maintain aerospace-qualified PAN precursor supply chains, creating structural barriers for renewable entrants seeking airfrer certification. METI's carbon neutrality roadmap funds pilot lignin fiber production at Nagoya-area facilities. Chubu region industrial parks host collaborative R&D between chemical conglomerates and automotive tier suppliers.
Sweden
Microwave-assisted carbonization pilot installations achieve 30-40% energy reduction versus conventional furnaces, collapsing production cost gaps for lignin-derived fibers. The Swedish Energy Agency funds industrial scaling programs linking forest product companies to composite manufacturers. Stockholm-Uppsala corridor research institutes coordinate precursor quality standardization with German automotive customers.
India
Reliance Industries and Aditya Birla Group pilot lignin fiber production for domestic wind blade and automotive component markets. The PLI scheme for advanced materials subsidizes carbonization line installation costs for qualified producers. Gujarat and Maharashtra industrial zones attract precursor purification technology partnerships with European engineering firms.
Renewable Carbon Fibers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying precursor and intermediate formats to qualified end-users. The renewable carbon fiber market exhibits tiered concentration, with aerospace-qualified grades dominated by integrated chemical conglomerates and industrial-scale formats fragmenting across regional specialists. Three archetypes prevail: integrated precursor-to-prepreg conglomerates, industrial-scale large-tow producers, and emerging bio-based precursor pure-plays. Competitive moves center on backward integration into agricultural feedstock supply and strategic partnerships for carbonization capacity sharing.
Among integrated chemical conglomerates, Toray Industries and Mitsubishi Chemical Carbon Fiber and Composites exemplify the precursor-to-prepreg archetype, anchoring long-term aerospace supply relationships through captive raw material control. Solvay occupies a position bridging resin system formulation with fiber compatibility qualification. Zoltek Companies, Inc. represents the industrial-scale vector, competing on cost in large-tow formats for wind and automotive applications where performance parity requirements relax.
| Leading Market Players |
|---|
| Trillium Renewable Chemicals |
| Solvay |
| Zoltek Companies, Inc. |
| Toray Industries |
| Cargill |
| Carbon Clean Solutions |
| Mitsubishi Chemical Carbon Fiber and Composites |
| Carbon Conversions |
| Hexcel Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's carbon-neutral logistics corridor compresses freight differentials between lignin precursor suppliers and German automotive clusters, concentrating pricing power with integrated producers who control both feedstock purification and carbonization capacity while tiering downstream contract structures by volume commitment and certification grade.
Pricing Analysis
Volume-discount tiering structures separate aerospace-qualified grades from industrial large-tow formats, with modulus certification above 230 GPa and REACH-compliant sizing chemistry commanding substantial premiums over construction-grade alternatives. Price differentiation rests on mass-balance chain-of-custody documentation and precursor yield consistency, as agricultural feedstock volatility compresses margins for bio-based acrylonitrile alternatives. Cost compression in industrial-grade segments is intensifying because microwave-assisted carbonization pilots achieve 30-40% energy reduction. Wind blade manufacturers exhibit highest price sensitivity due to direct offtake contract structures, while aerospace tier suppliers accept premium positioning for qualification security.
Supply Chain Analysis
Export-control regimes on continuous carbonization furnace technology limit equipment flows to Indian and Chinese producers, constraining capacity expansion outside established Japanese and European manufacturing bases. Geographic supply concentration centers on Germany, Japan, and Sweden, with precursor purification chemistry and agricultural lignin feedstocks anchoring upstream dependencies. Single-source vulnerability runs through Toray Industries and Mitsubishi Chemical's PAN precursor supply for aerospace-qualified grades. Distribution runs through direct offtake agreements between fiber producers and wind turbine manufacturers, displacing distributor channels in Denmark and northern Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renewable carbon fibers sit in early-cycle expansion as EU Green Deal carbon footprint thresholds harden procurement mandates across German automotive supply chains, accelerating penetration beyond pilot-scale qualification programs.
For Market Incumbents: Harden qualification timelines by front-loading R&D against aerospace OEM specification lock-in cycles spanning 7-10 years, securing captive lignin feedstock supply through backward integration into Nordic forest product partnerships, and preempting REACH substance restrictions on sizing chemistries through simultaneous thermoplastic and thermoset compatibility testing. For New Entrants and Emerging Players: Pursue construction biocomposite segments where visible sustainability credentials command procurement premiums over glass fiber alternatives, targeting building facade and interior panel applications with lower modulus thresholds that tolerate cellulose-derived fiber variability, and anchor go-to-market strategy through direct specification relationships with sustainability-focused architects and developers. For Investors and Strategic Acquirers: Bio-based precursor pure-plays with pilot carbonization capacity and mass-balance certification infrastructure represent the most defensible acquisition archetype, as long-term viability over the next decade hinges on securing automotive platform bids before 2027 model-year qualification deadlines crystallize. The signal to watch is German OEM publication of renewable content percentage mandates in structural component specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Feedstock | Captive agricultural supply secures margin stability against commodity price swings for bio-based acrylonitrile alternatives. |
| Microwave-Assisted Carbonization Scale-Up | Swedish and German pilot facilities demonstrate 30-40% energy reduction, collapsing production cost gaps with petroleum benchmarks. |
| Mass-Balance Chain-of-Custody Certification | EU Green Deal compliance documentation enables participation in Bavarian and Baden-Württemberg automotive platform bids. |
| Thermoplastic Format Qualification Investment | Recyclability mandates across European automotive supply chains pull demand toward melt-processable fiber grades. |
| Direct Offtake Agreement Structuring | Vestas and Siemens Gamesa lock 3-5 year supply contracts, displacing distributor-mediated procurement in wind energy. |
Research Methodology
Cross-validation between executive interviews and trade data anchors the qualitative findings, combining primary discussions with carbonization plant managers, automotive tier supplier procurement leads, aerospace composite engineers, and distribution channel partners with secondary validation through customs records, SEC filings of listed chemical conglomerates, EU ECHA substance restriction databases, and national energy agency funding disclosures. Bottom-up capacity installations and top-down end-use demand estimates triangulate market sizing.
Calibration against historical precursor yield improvements and energy intensity reductions across Swedish pilot facilities informs the analytical framework across the projection horizon. Segmentation dimensions modeled include precursor chemistry, processing format, end-use qualification intensity, and regional regulatory cluster. CAGRs derive from installed carbonization capacity expansion schedules mapped against OEM platform bid timelines. Forecast inputs incorporate EU CSRD disclosure rollout pace and REACH authorization timeline compression.
Sensitivities concentrate around agricultural feedstock price volatility, carbonization furnace equipment import restrictions, and aerospace qualification timeline extensions. Forecasts reflect documented assumptions on precursor yield convergence and energy cost trajectories. Material shifts in EU taxonomy implementation strictness or Japanese precursor export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Bicomponent Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Carbon Fiber Wrap Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Carbon Fiber Tapes Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Carbon Fiber Filament Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Citrus Pulp Fiber Market
Fibers
Viscose Market
Fibers
Bleached Linter Cellulose Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market