
 Asia-Pacific Carbon Fiber Market | 2026-2036
Asia-Pacific Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Carbon Fiber Market Outlook
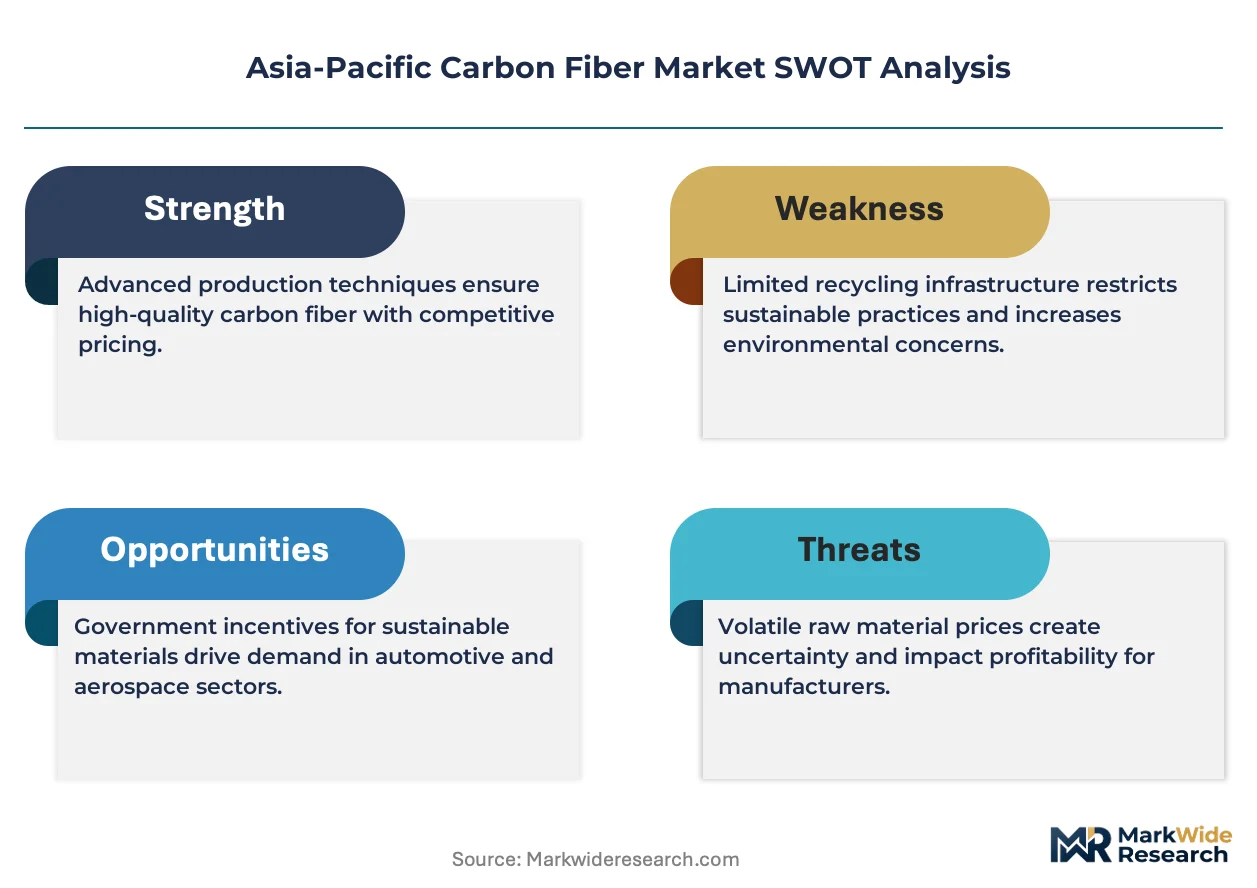
ISO 14001 environmental management certification is rotating as a baseline qualifier for Tier-1 supplier status across the Asia-Pacific carbon fiber value chain. TORAY INDUSTRIES, INC. leverages its precursor-to-composite vertical integration to dominate aerospace-grade supply in Japan. Hyosung Advanced Materials anchors South Korean demand through its Jeonju facility, which specializes in industrial-grade carbon fiber for pressure vessels and construction reinforcement. Zhongfu Shenying Carbon Fiber Co. Ltd competes aggressively on PAN-based precursor cost, extending its reach into wind energy blade manufacturers across China.
Carbon fiber consists of filaments composed primarily of carbon atoms arranged in crystalline formations, typically achieving tensile strengths exceeding 3,500 MPa and modulus values ranging from 230 to 600 GPa depending on precursor grade and heat treatment temperature. Manufacturers produce these fibers through controlled oxidation and carbonization of polyacrylonitrile (PAN), pitch, or rayon precursors, creating lightweight reinforcement materials that substitute for metals in weight-critical structures. Continuous fiber commands the dominant volume position across the region due to its load-bearing efficiency in aerospace primary structures and wind turbine blades. Prepreg segments capture disproportionate margin pools because of tighter process control requirements and longer qualification cycles with OEMs. Short fiber applications in automotive compression molding are gaining traction as cycle-time improvements reduce per-part costs.
Japan's METI enforces JIS standards for carbon fiber quality grading, while China's SAMR administers GB standards that increasingly align with aerospace OEM specifications to reduce import dependency. REACH-equivalent chemical controls under China's MEE framework are raising precursor plant compliance costs, effectively filtering smaller producers from qualification pipelines. South Korea's MFDS and KATS coordinate with METI on medical-device composite standards, opening adjacent demand channels. Stakeholders must monitor how China's evolving carbon emission accounting rules for chemical processes reshape the cost structure of domestic versus imported fiber.
Market Dynamics
China's dual carbon goals under MEE are compressing the cost structure of domestic precursor manufacturing while simultaneously filtering smaller producers from qualification pipelines. This regulatory pressure is reshaping competitive positioning across the Asia-Pacific carbon fiber value chain.
Growth Catalysts
- Wind energy blade demand:Offshore wind installations in Jiangsu and Shandong provinces are consuming industrial-grade carbon fiber at unprecedented scale. Blade manufacturers are qualifying domestic suppliers to reduce import dependency.
- MEE emission accounting rules:China's evolving carbon emission frameworks for chemical processes are accelerating capacity consolidation. Integrated carbon fiber parks in eastern China now capture economies of scale unavailable to fragmented competitors.
- JIS aerospace qualification:Japan's METI quality grading standards are creating exportable certification credentials. Korean and Chinese producers are aligning heat treatment protocols to access Japanese aerospace OEM supply chains.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs track petrochemical feedstock fluctuations. Producers without captive acrylonitrile supply face margin compression during energy price spikes.
- Japan-Korea supply concentration:Aerospace-grade fiber capacity clusters in specific prefectures and industrial zones. Disruption to TORAY INDUSTRIES or Hyosung Jeonju facilities would cascade through regional OEM procurement.
- Thermoplastic composite substitution:Glass fiber reinforced thermoplastics are capturing automotive interior applications. Cost-sensitive OEMs are relaxing performance specifications where weight reduction targets permit.
Strategic Opportunities
- Vietnam manufacturing footprint:Underpenetrated precursor and fiber capacity exists in Southeast Asia. Producers establishing operations near Ho Chi Minh City can access ASEAN tariff preferences and evade US-China trade friction.
- Pressure vessel hydrogen storage:South Korea's hydrogen economy roadmap is mandating Type IV composite tanks. Industrial-grade fiber demand from transportation and stationary storage applications is creating new volume pools.
- Digital twin process control:Convergence of AI-driven quality monitoring with carbonization furnace management is reducing defect rates. Early adopters are compressing qualification timelines with aerospace OEMs.
Industry Challenges
- Carbonization furnace engineering talent:Specialized thermal process engineers are concentrated at established Japanese and Korean producers. Chinese facilities are competing for limited personnel with semiconductor and battery manufacturing sectors.
- ISO 14001 certification timelines:Environmental management system implementation requires 12-18 months for chemical process facilities. Smaller Chinese producers are missing Tier-1 supplier windows while documentation matures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Carbon Fiber Market |
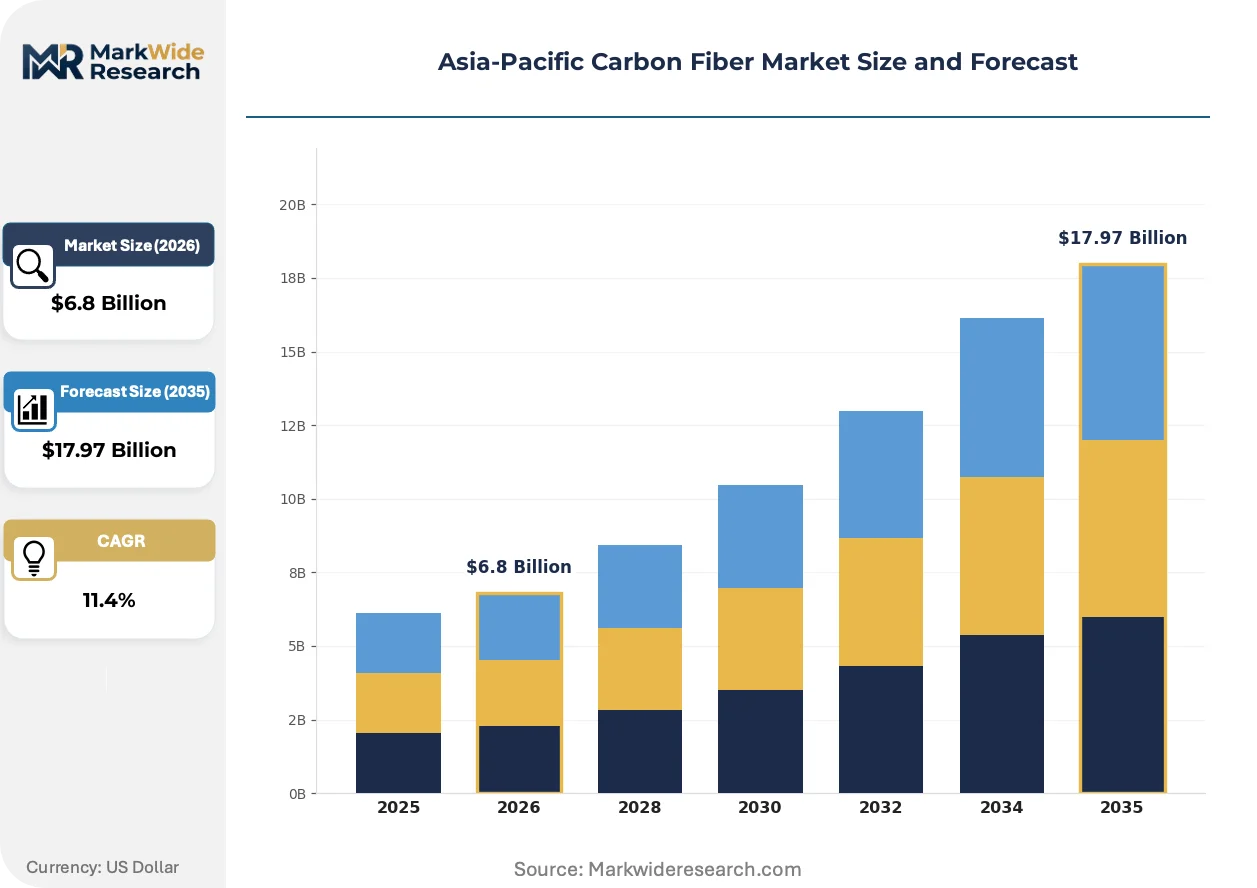
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Short Fiber, Fabric, Prepreg Application: Aerospace, Automotive, Wind Energy, Sporting Goods End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Composite Manufacturers Technology: Pultrusion, RTM, Filament Winding, Compression Molding |
| Companies Covered | SGL Carbon, Hyosung Advanced Materials, TORAY INDUSTRIES, INC., Zhongfu Shenying Carbon Fiber Co. Ltd, Formosa Plastics Corporation, TEIJIN LIMITED, Solvay, Hexcel Corporation, Mitsubishi Chemical Carbon Fiber and Composites Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Carbon Fiber Market Strategic Shifts
Active transformation across the Asia-Pacific carbon fiber market centers on three vectors: manufacturing process intensification, regulatory alignment with aerospace OEM specifications, and procurement model consolidation among wind energy developers.
Recycled carbon fiber through pyrolysis reclamation is decomposing the traditional virgin fiber cost floor. Wind turbine blade decommissioning programs in China and Japan are generating feedstock for reclaimed fiber production. Composite manufacturers serving automotive and construction sectors are adopting reclaimed fiber at 30-40% cost discounts, compressing margins for industrial-grade virgin fiber producers.
METI's updated JIS standards for carbon fiber quality grading are forcing alignment across Korean and Chinese export facilities. The industrial consequence is accelerated precursor plant automation to meet tighter tow-to-tow consistency requirements. Aerospace-grade segments in Japan and South Korea are responding with captive laboratory investments to maintain qualification credentials.
Consolidated procurement by wind farm developers is displacing fragmented blade manufacturer purchasing. Vestas and Goldwind are negotiating direct fiber supply agreements, bypassing traditional prepreg converter intermediaries. This channel compression is most visible in Jiangsu province, where integrated carbon fiber parks now host blade OEM co-location facilities.
Asia-Pacific Carbon Fiber Market Segmentation
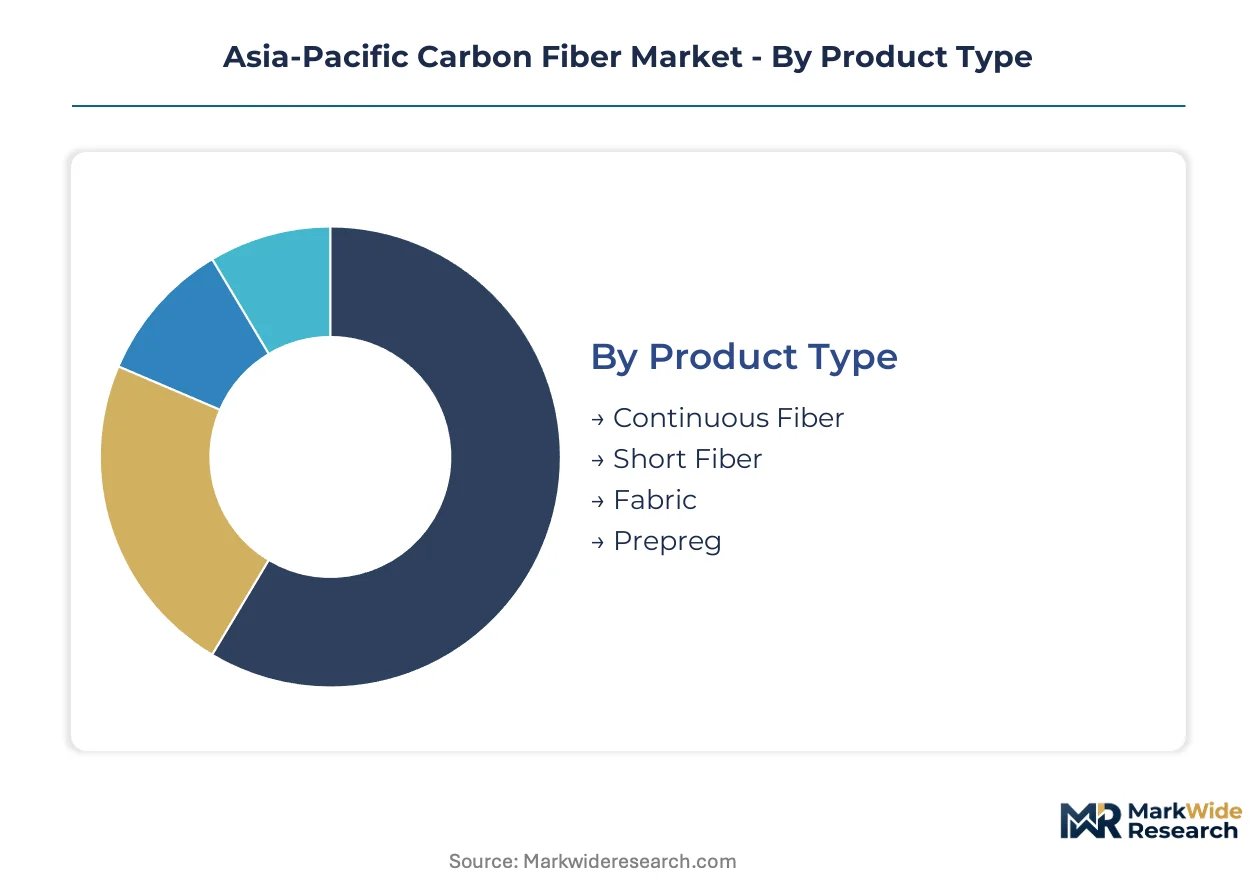
Carbon fiber segmentation in Asia-Pacific reflects divergent channel economics. Aerospace-grade material flows through qualified converter networks, while industrial-grade fiber moves via direct mill relationships. Understanding these channel dynamics separates pricing power from commodity exposure.
Product Type:
Continuous fiber and prepreg command premium channel positioning through aerospace converter networks, while short fiber and fabric compete on mill-direct volume pricing.
- Continuous Fiber:Unidirectional tows of aligned filaments deliver maximum load-bearing efficiency in primary structures. Demand concentrates in Jiangsu province wind blade facilities and Japanese aerospace OEM supply chains, where tow consistency requirements filter non-integrated producers. Heat treatment protocols at 1,500–3,000°C determine modulus grades.
- Prepreg:Pre-impregnated fiber sheets with controlled resin content require frozen supply chains and qualified converter relationships. Aerospace OEMs in Japan and South Korea specify prepreg for wing skins and fuselage sections, creating 18–24 month qualification barriers. METI JIS standards govern tow areal weight tolerances.
- Short Fiber:Chopped filaments 3–50mm in length serve automotive compression molding. Shandong province compounders integrate short fiber into thermoplastic pellets for interior panels.
- Fabric:Woven or non-crimp textiles enable complex contour layup. Marine and construction applications in Southeast Asia source fabric via distributor networks.
Continuous fiber dominates installed base. Prepreg is where expansion concentrates.
Application:
Cost tiers separate aerospace qualification premiums from industrial-grade commodity pricing, with wind energy capturing intermediate positioning through blade OEM direct procurement.
- Aerospace:Primary structures require T800-grade fiber with 5.9 GPa tensile strength. Japanese METI JIS certification and OEM-specific process specifications create dual-lock qualification. TORAY INDUSTRIES and Hyosung Advanced Materials anchor regional supply through captive laboratory investments.
- Wind Energy:Industrial-grade T700 fiber satisfies blade spar cap stiffness requirements at 40% cost discount to aerospace grades. Goldwind and Vestas negotiate direct fiber agreements in Jiangsu integrated parks, bypassing traditional prepreg converters.
- Automotive:Compression-molded structural components balance cycle time against fiber volume fraction. South Korean battery enclosure programs drive qualification activity.
- Sporting Goods:Intermediate modulus fiber serves bicycle frames and golf shafts. Taiwan-based manufacturers source via established trading house relationships.
Wind energy captures volume leadership. Aerospace commands margin concentration.
End User:
Customer type determines contract structure, with OEMs extracting qualification leverage while composite manufacturers compete on resin formulation and layup speed.
- OEMs:Boeing, Airbus, and COMAC specify fiber grades through design control documents. Procurement teams in Japan and South Korea enforce dual-source requirements despite limited qualified suppliers.
- Tier-1 Suppliers:Prepreg converters and component fabricators carry inventory risk and qualification documentation. ISO 14001 certification rotates as baseline supplier status requirement.
- Composite Manufacturers:Wind blade and pressure vessel fabricators blend fiber sourcing across domestic and import origins. Jiangsu province facilities achieve 70% domestic fiber integration.
- Aftermarket Providers:Repair stations and MRO facilities source certified material through authorized distributor channels. JIS traceability requirements limit gray market penetration.
OEMs dictate specification standards. Composite manufacturers drive volume scaling.
Technology:
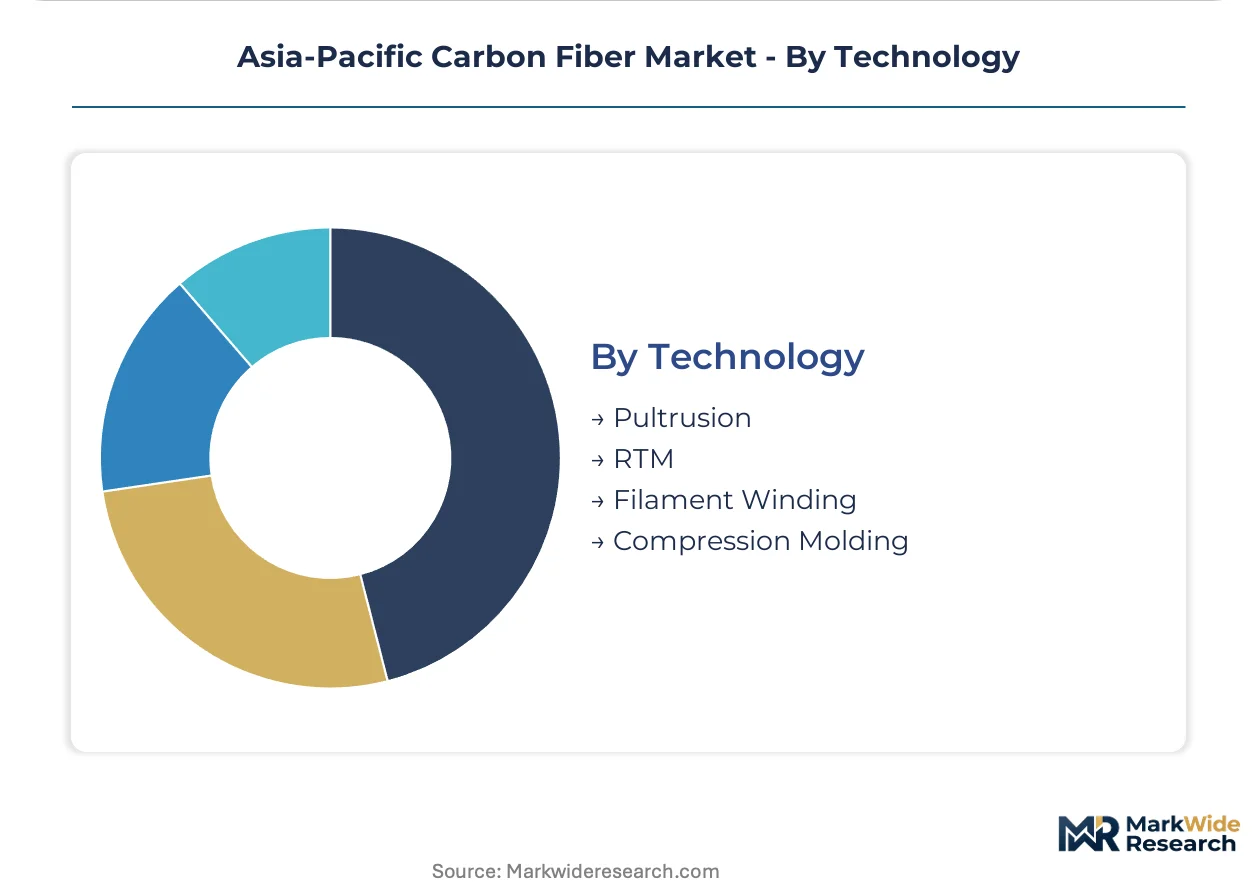
Process maturity separates high-automation aerospace methods from cost-optimized industrial techniques, with filament winding capturing hydrogen storage growth.
- Filament Winding:Automated fiber placement onto rotating mandrels produces pressure vessels with optimized hoop strength. South Korea's hydrogen economy roadmap mandates Type IV composite tanks, concentrating demand at Hyosung Jeonju and Chinese competitors.
- RTM (Resin Transfer Molding):Closed-mold infusion enables complex automotive structural geometries. Cycle time improvements below three minutes unlock high-volume electric vehicle applications.
- Pultrusion:Continuous profile production serves construction reinforcement and electrical infrastructure. Shandong province producers achieve 50-meter-per-minute line speeds.
- Compression Molding:Matched-die forming of SMC and BMC compounds dominates automotive secondary structures. Thermoplastic conversion is displacing thermoset in interior applications.
Filament winding leads process-specific growth. Compression molding retains volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals under MEE are redirecting investment flows across the Asia-Pacific carbon fiber value chain. Japan's METI quality standards are creating exportable certification credentials that Korean and Chinese producers now pursue. South Korea's hydrogen economy roadmap is opening adjacent demand channels for pressure vessel applications.
China
Wind energy blade demand from Goldwind and Vestas is concentrating procurement in Jiangsu and Shandong provinces. SAMR-administered GB standards are aligning with aerospace OEM specifications to reduce import dependency. Multiple integrated carbon fiber parks in eastern China now operate with 70% domestic fiber integration rates.
Japan
Aerospace OEMs are expanding carbon fiber procurement for next-generation aircraft programs. METI enforces JIS standards for carbon fiber quality grading that filter non-integrated producers. TORAY INDUSTRIES leverages its precursor-to-composite captive supply to dominate aerospace-grade supply chains.
South Korea
Type IV composite tank mandates under the national hydrogen economy roadmap are driving industrial-grade fiber demand. MFDS coordinates with METI on medical-device composite standards. Hyosung Advanced Materials anchors demand through its Jeonju facility specializing in pressure vessels and construction reinforcement.
Taiwan
Sporting goods manufacturers source intermediate modulus fiber for bicycle frames and golf shafts through established trading house relationships. The region's electronics supply chain expertise is transferring into composite process automation. Taipei-based fabricators are qualifying for Japanese aerospace converter networks.
Vietnam
Underpenetrated precursor and fiber capacity is attracting producers seeking ASEAN tariff preferences. Operations near Ho Chi Minh City evade US-China trade friction while serving Southeast Asian wind energy growth. Chinese and Korean investors are evaluating greenfield carbonization furnace deployments.
Asia-Pacific Carbon Fiber Market Competitive Environment
Listed leaders compete with private specialists across qualification credentials and captive precursor supply. The vendor base clusters around three tiers: integrated aerospace-grade producers with JIS certification, industrial-grade specialists serving wind and hydrogen storage, and emerging Chinese cost competitors scaling PAN-based precursor output. Consolidation pressure is filtering smaller producers from qualification pipelines while early adopters of AI-driven quality monitoring compress aerospace OEM approval timelines.
Within the integrated tier, TORAY INDUSTRIES, INC. and Mitsubishi Chemical Carbon Fiber and Composites Inc. exemplify Japanese producers with backward control over precursor supply. Hyosung Advanced Materials represents Korean industrial-grade specialization. Zhongfu Shenying Carbon Fiber Co. Ltd occupies a position among Chinese cost-optimized competitors extending into wind energy blade supply chains.
| Leading Market Players |
|---|
| SGL Carbon |
| Hyosung Advanced Materials |
| TORAY INDUSTRIES, INC. |
| Zhongfu Shenying Carbon Fiber Co. Ltd |
| Formosa Plastics Corporation |
| TEIJIN LIMITED |
| Solvay |
| Hexcel Corporation |
| Mitsubishi Chemical Carbon Fiber and Composites Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month qualification timelines for aerospace-grade fiber inventory compress pricing power toward integrated producers with captive precursor supply. Japanese and Korean facilities holding six-to-nine months of PAN acrylonitrile buffer stock command premium positioning against Chinese competitors facing spot-market volatility.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade and industrial-grade fiber tiers. Three-tier pricing structure across JIS-certified aerospace, industrial-grade wind energy, and reclaimed fiber economy levels dominates contract negotiations. Cost compression in industrial-grade segments is intensifying because pyrolysis reclamation from decommissioned wind blades offers 30-40% discounts. Wind energy blade manufacturers exhibit highest price sensitivity, while Japanese aerospace OEMs prioritize tow consistency over unit cost.
Supply Chain Analysis
Inventory concentration in Jiangsu and Shandong provinces feeds downstream converter networks across China, Japan, and South Korea. The regional value chain draws from petrochemical-derived acrylonitrile, polyacrylonitrile precursor, and carbonization furnace equipment inputs. Single-source vulnerability clusters around Japanese aerospace-grade capacity in specific prefectures. Distribution runs through qualified prepreg converters for aerospace, with direct mill relationships dominating wind energy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific carbon fiber market is emerging from a cyclical trough driven by offshore wind installation acceleration in eastern China. Recovery durability hinges on sustained blade OEM direct procurement and hydrogen storage tank qualification timelines.
For Market Incumbents: Consolidate precursor supply security through backward integration into acrylonitrile production or long-term offtake agreements with petrochemical partners. Defend JIS certification credentials against emerging Chinese competitors by accelerating AI-driven quality monitoring adoption. Channel control through co-location facilities in Jiangsu integrated parks protects volume relationships with Goldwind and Vestas.
For New Entrants and Emerging Players: Anchor in Vietnam manufacturing to access ASEAN tariff preferences and evade US-China trade friction. The most penetrable segment is industrial-grade fiber for Southeast Asian wind energy growth, where qualification barriers remain lower than aerospace. A go-to-market angle targeting pressure vessel hydrogen storage for South Korea's Type IV tank mandates offers faster revenue conversion than aerospace certification pathways.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized carbon fiber assets stranded by MEE emission accounting compliance costs. Long-term viability favors producers with demonstrated aerospace qualification credentials and captive laboratory infrastructure. The signal to watch is consolidation velocity among Jiangsu province integrated parks as smaller producers miss ISO 14001 certification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive precursor supply insulates margins from petrochemical volatility affecting PAN costs. |
| AI-Driven Quality Monitoring Deployment | Machine vision carbonization control compresses JIS qualification timelines with Japanese aerospace OEMs. |
| Vietnam Greenfield Capacity Buildout | ASEAN tariff access and trade friction evasion attract Chinese and Korean capital deployment. |
| Pyrolysis Reclamation Facility Investment | Decommissioned wind blade feedstock creates 30-40% cost-advantaged reclaimed fiber supply. |
| Pressure Vessel Filament Winding Expansion | South Korea's hydrogen economy roadmap mandates Type IV composite tank demand acceleration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SAMR GB standard filings, METI JIS certification registries, and SEC 10-K disclosures from listed chemical producers. Primary interviews engaged carbonization furnace engineers, wind blade procurement directors at Goldwind and Vestas, aerospace OEM material qualification leads, and precursor plant operations managers. Bottom-up fiber volume estimates from Jiangsu and Shandong province facilities triangulate against top-down demand modeling from wind energy installation forecasts and aircraft production schedules.
Segmentation dimensions modeled include fiber grade tier, end-use application, manufacturing technology, and regional production hub across the projection horizon. CAGRs derive from regression analysis of historical capacity utilization against qualified demand growth. Industry-specific forecast inputs incorporate MEE dual carbon policy implementation timelines and METI JIS standard revision cycles affecting qualification barriers.
Material uncertainties — acrylonitrile price volatility, aerospace program delays, and MEE emission accounting rule changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about precursor plant automation adoption and wind blade OEM procurement consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Bioglass Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Artificial Muscle Fibers Market
Fibers
Carbon Fiber Market
Fibers
Europe Carbon Fiber Market
Fibers
North America Carbon Fiber Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Bleached Linter Cellulose Market
Fibers
Viscose Market
Fibers
Vinylon Market
Fibers
Asia-Pacific Nanofiber Market