
 Global Ultra-High Molecular Weight Polyethylene Market | 2026-2036
Global Ultra-High Molecular Weight Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra-High Molecular Weight Polyethylene Market Foresight
Asian producers is consolidating capacity around high-purity grades for medical and defense applications. dsm-firmenich leverages its polymerization expertise to anchor premium medical-grade supply in Europe. Mitsui Chemicals sustains long-standing relationships with Japanese orthopedic OEMs through consistent batch quality. Celanese Corporation competes on scale in North American industrial segments while building Asian compounding presence.
Ultra-High Molecular Weight Polyethylene is a linear polyethylene with molecular weights exceeding 3.5 million g/mol, processed by gel-spinning or compression molding to yield exceptional abrasion resistance and impact strength. Its primary purpose centers on replacing metals in load-bearing surfaces, fiber reinforcement, and protective systems where low friction and chemical inertness prove critical. Medical implants command the highest margin pools within the application taxonomy, driven by stringent purification and traceability requirements for joint replacement components. Powder and granule forms dominate upstream supply, while sheets and rods capture value through downstream fabrication and precision machining.
FDA biocompatibility standards, EU MDR implant-grade material traceability rules, and ISO 5834 orthopedic polymer specifications collectively determine market access and pricing tiers for medical applications. Japan's PMDA and METI coordinate domestic quality benchmarks that align with global harmonization efforts for cross-border device approvals. Stakeholders must monitor regulatory divergence between FDA and EU MDR testing protocols as a decisive factor in regional manufacturing location decisions.
Market Dynamics
Medical-grade purification requirements are compressing supplier margins while concentrating volume among polymerization specialists capable of ISO 5834 traceability. Orthopedic OEMs now demand batch-level molecular weight certification that smaller compounders cannot deliver.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined biocompatibility testing for implant-grade UHMWPE accelerates joint replacement component approvals. Device manufacturers expand polymer qualification programs.
- German Precision Machining Clusters:Concentrated medical technology fabrication around Stuttgart and Tuttlingen creates captive demand for rod and sheet stock. Local supply chains reduce lead times for European orthopedic OEMs.
- Gel-Spinning Process Refinement:Enhanced fiber orientation control expands ballistic protection applications. Defense procurement agencies specify UHMWPE composites for next-generation personal armor systems.
Market Restraints
- Ethylene Feedstock Volatility:Crude oil price swings directly compress polymerization margins. Producers lack pricing power to pass through input cost spikes in industrial segments.
- Japanese Supply Concentration:Mitsui Chemicals and limited domestic competitors control high-purity medical-grade output. Geographic concentration creates single-source risk for Asian orthopedic device manufacturers.
- Cross-Linked Polyethylene Substitution:Irradiated XLPE variants compete directly in acetabular cup applications. Joint replacement designers evaluate wear-rate trade-offs between material classes.
Strategic Opportunities
- Indian Orthopedic Expansion:Domestic joint replacement manufacturing under CDSCO oversight creates demand for imported medical-grade resin. Local compounding partnerships reduce import duty exposure.
- EU MDR Traceability Mandates:Implant-grade polymer documentation requirements favor established suppliers with quality management systems. Premium pricing tiers open for batch-certified material.
- Additive Manufacturing Convergence:Powder-bed fusion and fused filament fabrication processes adapt UHMWPE for patient-specific implant geometries. Orthopedic device startups prototype custom joint components.
Industry Challenges
- ISO 5834 Certification Timeline:Extended testing protocols for implant-grade polymer qualification delay new supplier entry. Device manufacturers face eighteen-month material validation cycles.
- Cleanroom Compounding Capacity:Medical-grade production requires ISO Class 7 environments and dedicated extrusion lines. Capital intensity restricts mid-scale participants from margin-rich segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra-High Molecular Weight Polyethylene Market |
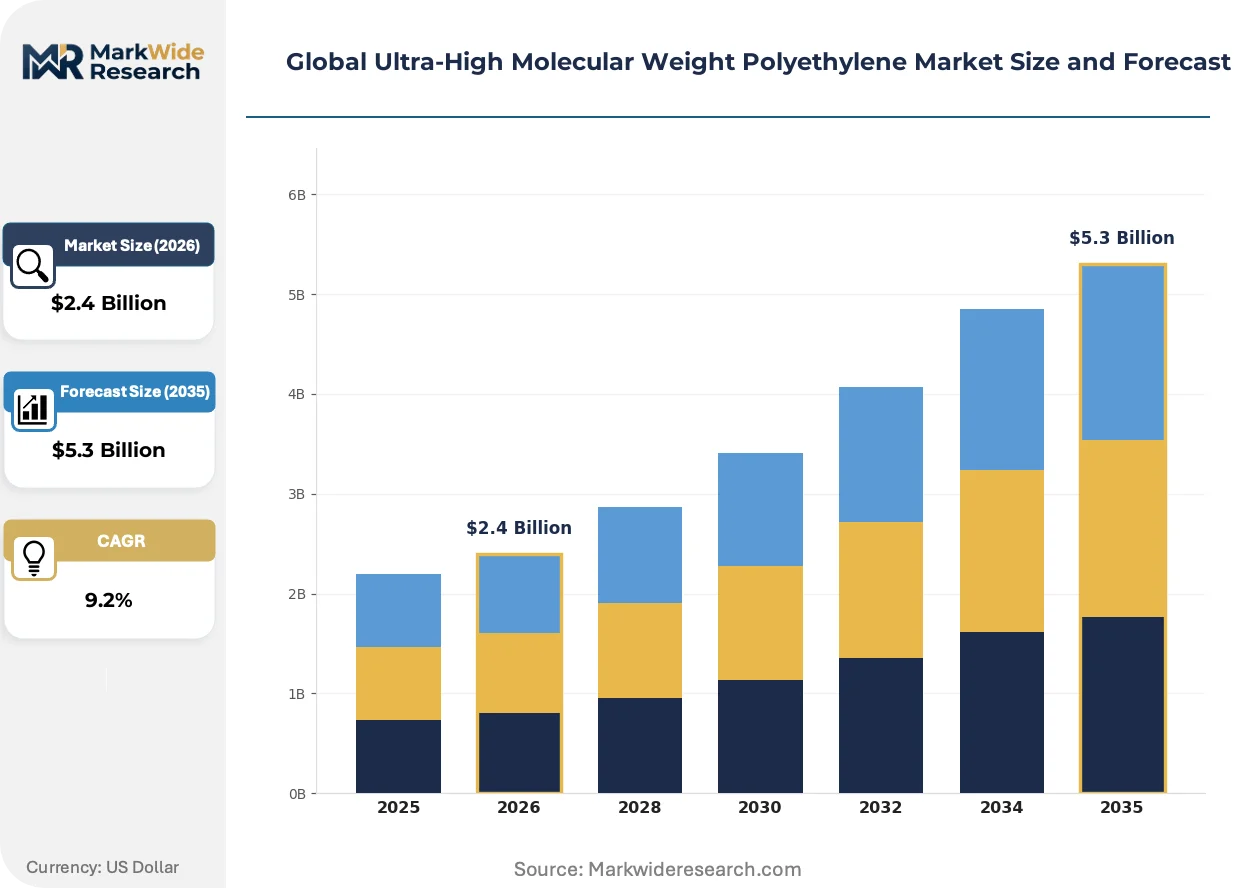
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Sheets, Rods, Films Application: Protective Gear, Conveyor Components, Medical Implants, Marine Fenders, Wear Liners End User Industry: Automotive Suppliers, Construction Firms, Medical Device Manufacturers, Packaging Companies, Renewable Energy Firms Form: Solid, Powdered, Slurry, Coated, Reinforced |
| Companies Covered | dsm-firmenich, Mitsui Chemicals Inc., Celanese Corporation, Asahi Kasei Corporation, Avient Corporation, Braskem, Honeywell International Inc., Röchling Group, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra-High Molecular Weight Polyethylene Market Shifts & Advancements
Advanced purification technologies and regulatory harmonization efforts are restructuring competitive positioning across medical and industrial segments. Material scientists pursue molecular weight distribution control as the primary differentiation vector.
Vitamin E-stabilized UHMWPE is integrating antioxidant protection directly into polymer chains to inhibit oxidative degradation in joint implants. Major orthopedic OEMs in Germany and the United States specify stabilized grades for extended-duration replacements. This formulation shift is integrating long-term clinical performance data into procurement specifications, compressing demand for conventional gamma-sterilized alternatives.
EU MDR implant-grade material traceability rules now require documented supply chain provenance from resin to finished device. German notified bodies enforce batch-specific testing protocols that exceed prior MEDDEV guidelines. European orthopedic polymer distributors invest in blockchain-based documentation systems to satisfy conformity assessment demands.
Japanese orthopedic OEMs consolidate supplier relationships around single-source UHMWPE partnerships with guaranteed molecular weight consistency. PMDA quality benchmarks align with FDA biocompatibility standards, enabling cross-border device submissions. METI coordinates domestic polymer producers to maintain export competitiveness through standardized certification packages.
Global Ultra-High Molecular Weight Polyethylene Market Segmentation
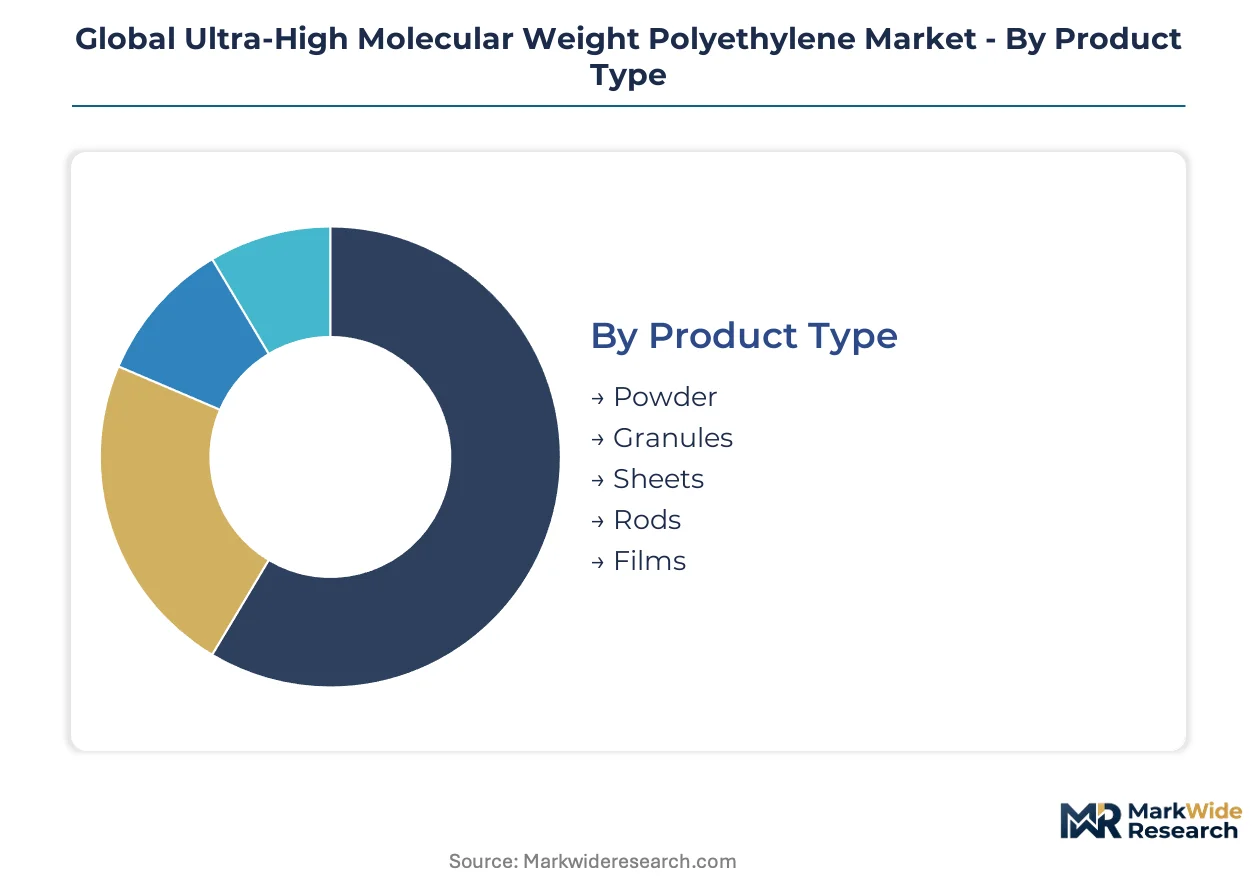
UHMWPE segmentation reflects divergent purity requirements across medical and industrial buyers. Product form and certification grade determine pricing tiers and supplier qualification pathways. End-use specifications fragment demand into discrete procurement channels with limited cross-segment substitution.
Product Type:
Powder and granule buyers prioritize molecular weight consistency and lot-to-lot reproducibility for downstream fabrication.
- Powder:Fine particulate form serves gel-spinning operations for fiber production and compression molding of complex geometries. Medical device manufacturers in Germany specify sub-200 micron particle size distributions for implant preforms.
- Granules:Pelletized resin feeds extrusion and injection molding lines with controlled melt flow indices. Automotive suppliers in Michigan favor granule feedstock for continuous conveyor component production.
- Sheets:Compression-molded plates enable CNC machining of bearing surfaces and wear pads. Marine fender fabricators in Singapore stock standard thickness sheets for dock protection systems.
- Rods:Solid cylindrical stock supports precision turning of bushings and rollers. Precision machining clusters around Stuttgart consume rod stock for orthopedic instrument components.
- Films:Thin-gauge extruded layers provide chemical barrier protection and release surfaces. Packaging companies in Japan specify film grades for high-temperature processing aids.
Powder leads on scale; rods lead on momentum.
Application:
Performance requirements range from ballistic energy absorption to decades-long biostability in physiological environments.
- Protective Gear:Gel-spun fibers woven into ballistic panels and helmets for military and law enforcement procurement. Defense agencies in the United States specify UHMWPE composites for next-generation personal armor under NIJ standards.
- Conveyor Components:Machined rollers, guides, and wear strips exploit low friction coefficients and abrasion resistance. Bulk material handling operations in Australia's mining sector replace steel components with UHMWPE equivalents.
- Medical Implants:Acetabular liners, tibial inserts, and patellar components demand ISO 5834-certified resin with full traceability. Joint replacement OEMs in Germany and the United States validate batch-specific molecular weight certificates.
- Marine Fenders:Impact-absorbing dock protection systems withstand saltwater exposure and UV degradation. Port authorities in the Netherlands specify UHMWPE facing plates for heavy-vessel berthing infrastructure.
- Wear Liners:Bulk material handling chutes and hopper surfaces reduce maintenance intervals in abrasive service. Cement producers in India install bolt-in liner systems for clinker processing equipment.
Medical implants command premium pricing; protective gear expands most quickly.
End User Industry:
Regulatory exposure and volume scale determine supplier relationship structures across buyer categories.
- Automotive Suppliers:Tier-1 and tier-2 component manufacturers specify UHMWPE for conveyor systems and assembly line wear parts. Suppliers in Germany integrate resin into just-in-time production workflows.
- Construction Firms:Infrastructure contractors deploy UHMWPE for temporary works, formwork liners, and heavy equipment wear surfaces. Tunneling projects in Switzerland specify the polymer for segment gasket applications.
- Medical Device Manufacturers:Orthopedic OEMs and surgical instrument producers drive demand for implant-grade and instrument-grade material. FDA and EU MDR compliance requirements restrict qualified supplier pools.
- Packaging Companies:Food processing and pharmaceutical packaging machinery builders specify UHMWPE for guide rails and star wheels. Cleanroom-compatible grades meet FDA food contact regulations.
- Renewable Energy Firms:Offshore wind turbine operators specify UHMWPE for cable protection systems and bearing components. Developers in Denmark deploy the polymer in wave and tidal energy installations.
Medical device manufacturers lead on margin capture; renewable energy firms lead on growth trajectory.
Form:
Physical state at point of use determines processing equipment requirements and supply chain logistics.
- Solid:Finished machined components and near-net-shape preforms eliminate customer-side fabrication. German orthopedic instrument suppliers procure solid rod and bar stock for precision machining.
- Powdered:Virgin and compounded powders feed sintering, compression molding, and additive manufacturing processes. Research institutions in Japan evaluate powder-bed fusion for patient-specific implant geometries.
- Slurry:Aqueous dispersions enable coating applications and wet processing of fiber precursors. Textile finishers in the United States deploy slurries for fabric treatments.
- Coated:Substrate-bonded UHMWPE layers combine wear resistance with structural backing materials. Conveyor belt manufacturers in Australia specify coated fabrics for bulk handling applications.
- Reinforced:Composite formulations with glass, carbon, or aramid fibers enhance stiffness and load-bearing capacity. Ballistic armor producers in the United States specify reinforced sheets for vehicle protection systems.
Solid forms lead on revenue concentration; reinforced formulations lead on technology advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping UHMWPE production location decisions as manufacturers weigh EU MDR compliance costs against FDA pathway efficiencies. The cost-of-compliance gap between jurisdictions is concentrating medical-grade polymerization in jurisdictions with streamlined biocompatibility frameworks.
United States
Joint replacement OEMs in Warsaw, Indiana and Memphis, Tennessee drive demand for implant-grade resin with batch-level molecular weight certification. FDA's updated 510(k) pathways accelerate biocompatibility testing timelines for orthopedic device submissions. Precision machining clusters in Massachusetts and Minnesota fabricate instrument components from rod and sheet stock.
Germany
Medical technology manufacturers around Stuttgart and Tuttlingen consume rod stock for orthopedic instruments and implant preforms. EU MDR traceability mandates enforced by German notified bodies exceed prior MEDDEV guidelines for implant-grade polymer documentation. Berlin-based distributors invest in blockchain-based supply chain provenance systems to satisfy conformity assessment demands.
Japan
Orthopedic OEMs in the Kansai region consolidate supplier relationships around guaranteed molecular weight consistency for acetabular components. METI coordinates domestic polymer producers to maintain export competitiveness through PMDA-aligned certification packages. Osaka-based device manufacturers leverage standardized quality benchmarks for cross-border submissions to FDA.
China
Domestic joint replacement manufacturing under NMPA oversight creates demand for high-purity medical-grade resin with ISO 5834 alignment. MIIT industrial policies support polymerization capacity expansion for defense and medical applications. Yangtze River Delta compounding facilities serve Asian orthopedic device manufacturers seeking reduced import duty exposure.
India
Domestic joint replacement manufacturing under CDSCO oversight generates demand for imported medical-grade UHMWPE resin. Maharashtra-based orthopedic device startups prototype custom joint components through additive manufacturing partnerships. Gujarat compounding facilities explore local production partnerships to reduce import duty exposure on medical-grade feedstock.
Global Ultra-High Molecular Weight Polyethylene Market Competitive Landscape
Dutch and German producers anchor the premium medical-grade tier; Japanese specialists hold dominant positions in high-purity fiber and implant resin. The vendor base stratifies across polymerization specialists with ISO 5834 traceability systems, regional compounders serving industrial segments, and integrated chemical conglomerates with captive ethylene feedstock. Three archetypes dominate: purification-focused medical-grade specialists, scale-driven industrial commodity producers, and vertically integrated petrochemical majors. Competitive moves center on cleanroom compounding capacity expansion and strategic partnerships with orthopedic OEMs for batch-certification programs.
Within the medical-grade specialization tier, dsm-firmenich and Mitsui Chemicals Inc. occupy positions defined by polymerization expertise and long-standing orthopedic OEM relationships. Celanese Corporation exemplifies the scale-driven archetype competing in North American industrial segments. These three entities represent distinct competitive vectors: European purification leadership, Japanese batch consistency, and North American industrial scale.
| Leading Market Players |
|---|
| dsm-firmenich |
| Mitsui Chemicals Inc. |
| Celanese Corporation |
| Asahi Kasei Corporation |
| Avient Corporation |
| Braskem |
| Honeywell International Inc. |
| Röchling Group |
| LyondellBasell Industries |
| Others |
Supply & Pricing Matrix
Ethylene feedstock benchmarks cascade through polymerization economics to stratify UHMWPE pricing across medical and industrial tiers. Purification intensity for implant-grade resin amplifies cost differentials that compounders cannot absorb without ISO 5834 certification investments.
Pricing Analysis
Distributor margins compress at the medical-grade tier while direct-to-OEM contracts secure volume commitments through batch-certification programs. Pricing stratifies across implant-grade, instrument-grade, and industrial commodity tiers driven by molecular weight consistency and traceability documentation. Cost compression in industrial segments intensifies as ethylene volatility outpaces polymerization pricing power. Automotive conveyor component buyers exhibit highest price sensitivity; orthopedic OEMs prioritize batch consistency over unit cost.
Supply Chain Analysis
ISO 5834 certification gates concentrate medical-grade supply among polymerization specialists in the Netherlands, Germany, and Japan. Virgin resin production draws from ethylene feedstock, catalyst systems, and cleanroom compounding infrastructure. Single-source vulnerability pervades Asian medical-grade sourcing where Mitsui Chemicals dominates high-purity output. Distribution runs through authorized distributors for implant-grade material and direct mill relationships for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR traceability mandates and FDA 510(k) modernization collectively expand qualified supplier premiums.
For Market Incumbents: Extend cleanroom compounding capacity into Asian medical technology clusters before NMPA and CDSCO localization requirements mature. Consolidate batch-certification partnerships with orthopedic OEMs in Germany and the United States to lock out compounders lacking ISO 5834 traceability systems. Cross-linked polyethylene substitution in acetabular applications demands antioxidant-stabilized formulation R&D investment. For New Entrants and Emerging Players: Launch via additive manufacturing powder partnerships with Indian orthopedic device startups prototyping patient-specific geometries under CDSCO oversight. Target renewable energy cable protection systems in Denmark and offshore wind markets where UHMWPE specifications remain less stringent than implant-grade barriers. Pursue compounding joint ventures in Gujarat to circumvent import duty exposure on medical-grade feedstock. For Investors and Strategic Acquirers: Asymmetric upside sits with purification-focused specialists possessing captive ethylene integration and established orthopedic OEM relationships. Five-to-ten year viability hinges on regulatory harmonization rather than commodity scale. Monitor FDA-EU MDR testing protocol divergence as the decisive inflection signal for regional manufacturing location premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Compounding Expansion | ISO Class 7 capacity captures implant-grade margin pools in Stuttgart and Tuttlingen clusters. |
| Backward Integration into Ethylene | Captive feedstock supply insulates polymerization margins from crude oil volatility swings. |
| Batch-Certification Partnerships | Molecular weight documentation programs lock orthopedic OEMs into multi-year supply agreements. |
| Additive Manufacturing Powder Development | Powder-bed fusion compatibility opens patient-specific implant geometries for device startups. |
| Antioxidant Stabilization Formulation | Vitamin E integration inhibits oxidative degradation for extended-duration joint replacements. |
Research Methodology
Bottom-up orthopedic implant modeling reconciled against top-down polymerization capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, polymerization plant managers, and distribution channel partners combine with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, customs trade data, and SEC 10-K polymer segment disclosures. Triangulation across supply-side capacity registers and demand-side procurement patterns ensures segmentation integrity.
Historical trendline analysis of gel-spinning fiber output, compression-molded sheet production, and implant-grade resin volumes establishes baseline trajectories across the projection horizon. Segmentation modeling incorporates grade tier, end-use industry, product form, and regional production hub dimensions. CAGRs derive from elasticity-adjusted penetration rates calibrated against molecular weight certification timelines and orthopedic device approval cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene feedstock volatility extremes or regulatory divergence between FDA and EU MDR testing protocols. Forecasts reflect assumptions regarding certification harmonization progress and cleanroom capacity expansion schedules. A model refresh is warranted upon material change in EU MDR enforcement intensity or NMPA medical-grade localization mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Global Unsaturated Polyester Resins Market