
 Global Basalt Fiber Market | 2026-2036
Global Basalt Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Basalt Fiber Market Intelligence
Buyer concentration across European infrastructure consortiums is recalibrating procurement volumes toward specialty fiber suppliers with proven regulatory dossiers. Kamenny Vek anchors its position through captive melt-feedstock operations in Russia's Leningrad region. Zhejiang GBF Basalt Fiber Co., Ltd. leverages integrated pultrusion lines to serve domestic wind blade manufacturers. Mafic SA differentiates through ISO-certified continuous filament output aimed at aerospace qualification programs.
Basalt fiber consists of extruded filaments drawn from molten volcanic rock at temperatures exceeding 1,400°C, yielding amorphous silica-alumina-iron oxide filaments with tensile strength comparable to S-2 glass and superior alkali resistance. Its primary industrial purpose centers on structural reinforcement where thermal stability, chemical inertness, and non-conductive properties outperform conventional alternatives. Continuous filament commands the dominant volume share in wind energy and pressure vessel applications, while chopped strand registers the fastest expansion in sprayed concrete and thermoplastic compounding where dispersion uniformity determines performance. Pultrusion technology leads margin capture by converting raw roving into dimensionally stable profiles with minimal waste, whereas wet processing lines serving marine laminates face yield compression from resin volatility and longer cure cycles.
REACH registration requirements in Europe and EPA emissions protocols in the United States constrain market access for producers lacking full chemical safety documentation, effectively filtering out smaller melt operations with limited compliance budgets. China's GB standards and MIIT industrial material directives establish domestic basalt fiber as a strategic substitute for imported carbon fiber in designated defense and civil infrastructure applications. Stakeholders must monitor evolving fire-safety certification thresholds in transportation and building codes, as these specifications will determine which filament diameters and sizing chemistries achieve qualified supplier status.
Market Dynamics
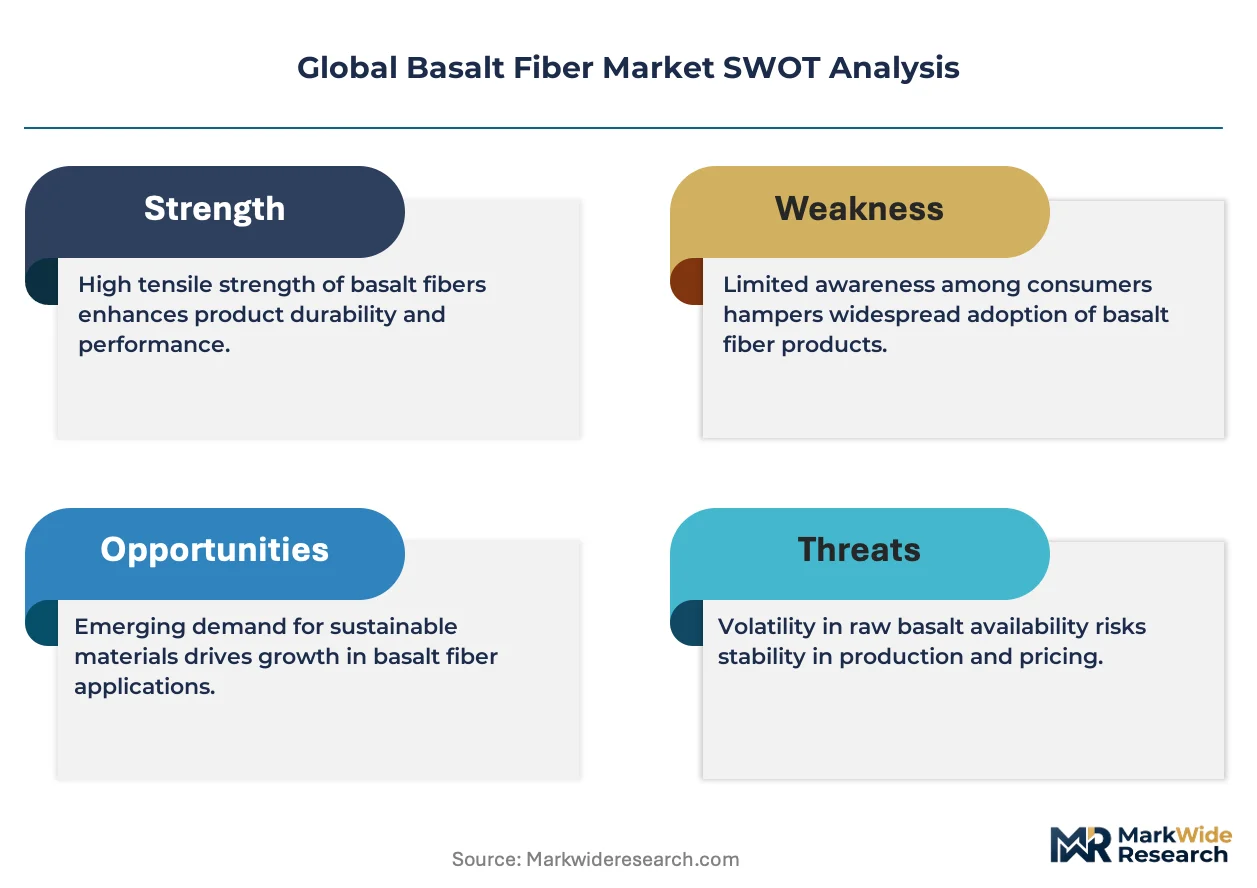
Basalt fiber procurement is consolidating around suppliers with captive melt capacity and certified regulatory dossiers as infrastructure buyers face tightening fire-safety and corrosion-resistance mandates across multiple jurisdictions.
Growth Catalysts
- REACH compliance in Europe:ECHA registration requirements are redirecting specification decisions toward non-corrosive reinforcement materials with full chemical safety documentation.
- Wind blade manufacturing:Pultruded basalt profiles are displacing E-glass in turbine structural components due to superior fatigue resistance and alkali stability.
- China's MIIT directives:State-backed infrastructure programs designate basalt fiber as a strategic substitute for imported carbon fiber in civil engineering applications.
Market Restraints
- Energy-intensive melting:Basalt filament production requires sustained temperatures exceeding 1,400°C, creating input cost exposure to natural gas and electricity volatility.
- Feedstock concentration:High-quality volcanic rock deposits suitable for continuous filament drawing concentrate in Russia's Leningrad region and select Chinese provinces.
- Resin system incompatibility:Standard epoxy and vinyl ester chemistries require modified sizing agents to achieve adequate interfacial bonding with basalt surfaces.
Strategic Opportunities
- India's infrastructure buildout:Coastal highway and port projects present untapped demand for alkali-resistant rebar in chloride-rich environments.
- Transportation fire-safety codes:Evolving FAA and EASA interior material standards are creating qualification pathways for basalt-based thermoplastic composites.
- Recyclable thermoplastic compounding:Chopped strand integration with polypropylene and polyamide matrices enables closed-loop automotive component manufacturing.
Industry Challenges
- Continuous filament certification:Aerospace and pressure vessel qualification programs require multi-year testing cycles under ISO and ASTM protocols.
- Process control expertise:Platinum-rhodium bushing maintenance and fiber diameter uniformity demand specialized metallurgical and glass-ceramic engineering skills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Basalt Fiber Market |
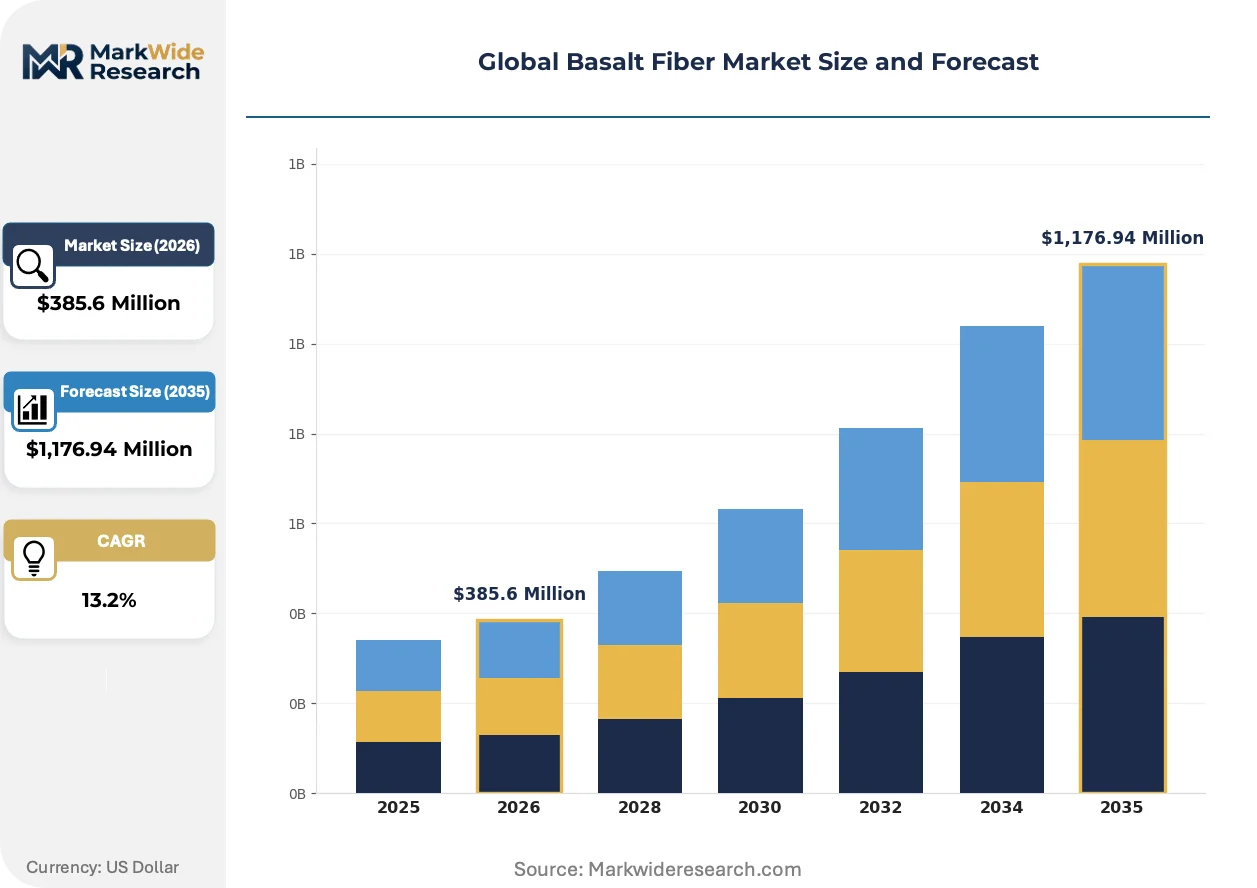
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,176.94 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Strand, Continuous Filament, Woven Roving, Mat, Yarn Application: Construction, Marine, Energy, Aerospace, Electronics, Sports Equipment End User Industry: Building Materials, Transportation Manufacturers, Power Generation, Defense Sector, Consumer Goods Technology: Dry Processing, Wet Processing, Pultrusion, Needle Puncture |
| Companies Covered | Kamenny Vek, Zhejiang GBF Basalt Fiber Co., Ltd., Mafic SA, Technobasalt-Invest LLC, ISOMATEX SA, Deutsche Basalt Faser GmbH, Sudaglass Fiber Technology, INCOTELOGY GmbH, Shanxi Basalt Fiber Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Basalt Fiber Market Strategic Shifts & Innovations
Continuous filament drawing technology is consolidating market position as energy efficiency and yield improvements reshape supplier competitiveness. Regulatory fire-safety thresholds are hardening across transportation and building codes. Procurement patterns are concentrating volume among infrastructure consortiums with integrated materials engineering capabilities.
Direct melt feeding with electric furnace technology is consolidating operational control for basalt fiber producers. Wind blade manufacturers in Germany and Denmark are adopting larger-diameter rovings to reduce layup labor. This consolidation is compressing margins for wet-processing laminators dependent on resin volatility-exposed supply chains.
EPA emissions protocols in the United States are tightening volatile organic compound thresholds for composite manufacturing facilities. Wet processing lines serving marine and infrastructure laminates face yield compression from extended cure cycles and ventilation requirements. California and Texas-based pressure vessel fabricators are accelerating qualification of pre-impregnated basalt tapes to bypass on-site resin handling.
Specification decisions are concentrating among European infrastructure consortiums with captive materials engineering teams. Standardized design libraries are displacing project-specific composite development for bridge decks and tunnel linings. This concentration is most visible in France and the Netherlands, where public-private partnership procurement mandates bundled performance warranties.
Global Basalt Fiber Market Segmentation
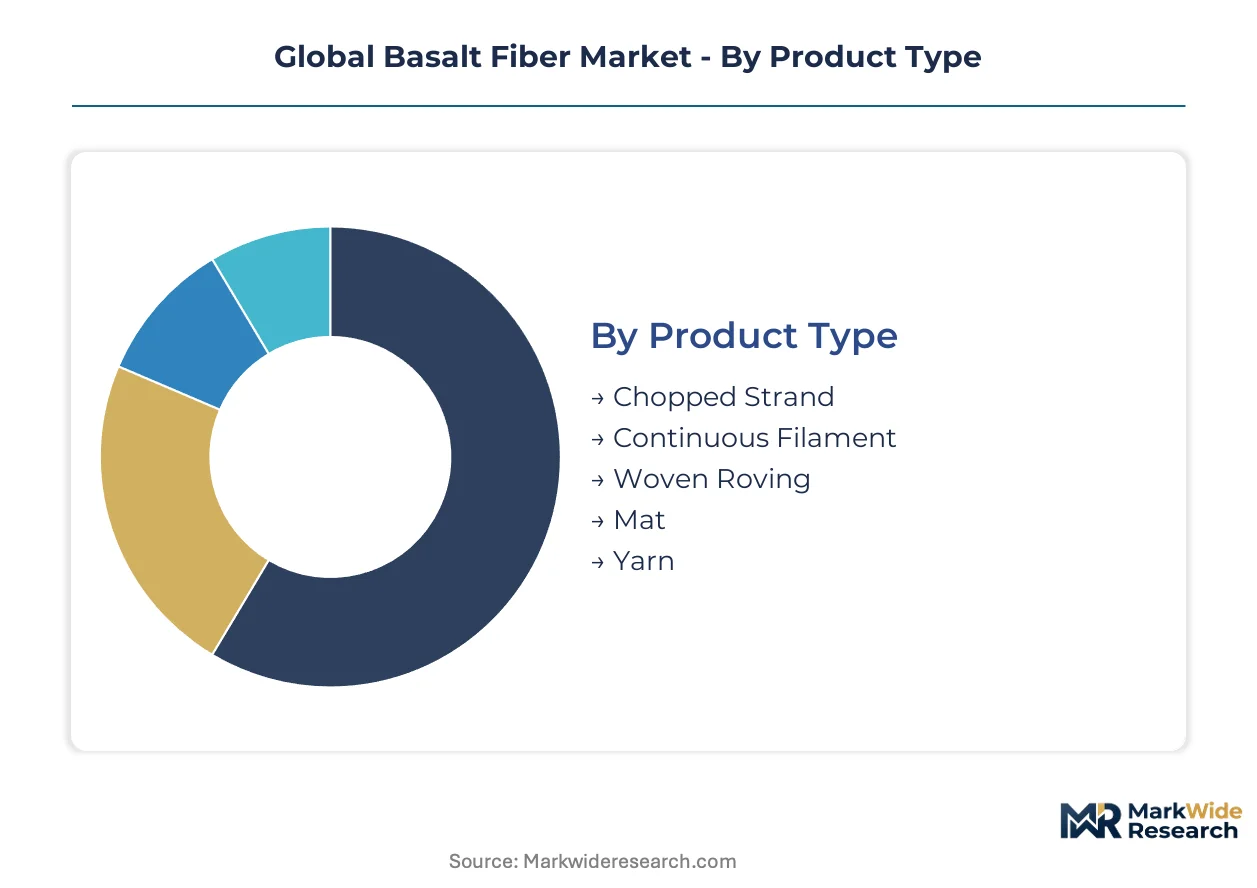
Basalt fiber procurement decisions pivot on filament geometry and processing method. Specification choices cascade through composite performance, manufacturing compatibility, and regulatory qualification pathways. Segmentation clarity enables buyers to match volcanic rock-derived reinforcements to precise load-bearing and environmental exposure requirements.
Product Type:
Continuous filament drawing technology and chopped strand dispersion characteristics define specification hierarchies across wind energy, construction, and thermoplastic compounding.
- Continuous Filament:Extruded as unidirectional rovings with diameters ranging from 9 to 25 microns, continuous filament delivers tensile strength comparable to S-2 glass. Procurement concentrates in Germany and Denmark for wind blade structural spar caps where fatigue resistance under cyclic loading determines turbine lifetime. REACH-registered sizing chemistries from Kamenny Vek and Zhejiang GBF anchor qualified supplier status for European and Chinese blade manufacturers respectively.
- Chopped Strand:Cut to 3-50mm lengths with proprietary surface treatments for thermoplastic and thermoset compatibility, chopped strand enables automated spray-up and injection molding processes. Demand climbs fastest in China's infrastructure programs where MIIT-designated basalt fiber substitutes for steel rebar in sprayed concrete tunnel linings and bridge deck overlays requiring alkali resistance in chloride-rich environments.
- Woven Roving:Plain and twill weaves constructed from continuous filament bundles serve marine laminate and pressure vessel applications requiring multi-axial load distribution.
- Mat:Chopped strand mats held by powder or emulsion binders provide conformable layers for hand lay-up and resin transfer molding in corrosion-resistant tank fabrication.
- Yarn:Twisted continuous filament bundles enable textile processing for fire-resistant insulation sleeving and high-temperature gasket applications.
Mature deployment sits with continuous filament in qualified aerospace and pressure vessel programs. Newer deployment is concentrated in chopped strand for thermoplastic automotive and infrastructure applications.
Application:
End-use performance requirements and fire-safety certification thresholds segment procurement across structural reinforcement, environmental protection, and weight-sensitive mobility systems.
- Construction:Basalt-reinforced concrete and composite rebar address infrastructure resilience mandates tightening across France, the Netherlands, and China's coastal provinces. Pultruded profiles substitute for steel in bridge decks and seawalls where chloride-induced corrosion degrades conventional reinforcement. Public-private partnership procurement in Europe bundles performance warranties favoring suppliers with captive melt capacity and ISO-certified continuous output.
- Marine:Hull laminates, deck structures, and offshore platform components exploit basalt's moisture resistance and non-conductive properties. Wet processing lines serving boatbuilders in Italy and Turkey face margin compression from extended epoxy cure cycles and EPA-aligned volatile organic compound ventilation requirements.
- Energy:Wind turbine blade spar caps and nacelle housings represent the dominant volume concentration for continuous filament rovings.
- Aerospace:Interior panel and cargo liner applications drive qualification programs under FAA and EASA fire-smoke-toxicity protocols.
- Electronics:Printed circuit board substrates and cable insulation leverage thermal stability and dielectric properties.
- Sports Equipment:Bicycle frames, skis, and hockey sticks adopt basalt-epoxy prepregs for vibration damping and impact resistance.
Volume leadership resides with construction and energy applications. Steepest expansion trajectory appears in aerospace interior qualification pathways as FAA and EASA standards harden.
End User Industry:
Procurement authority and technical specification control concentrate among integrated materials engineering teams within infrastructure consortiums and prime manufacturers.
- Building Materials:Precast concrete producers and composite rebar fabricators in China, Russia, and Germany drive specification of alkali-resistant chopped strand and pultruded profiles. State-backed infrastructure programs and tightening corrosion-resistance codes redirect procurement from E-glass and steel toward basalt alternatives with full chemical safety documentation.
- Transportation Manufacturers:Automotive tier suppliers and rail interior fabricators integrate basalt-thermoplastic composites for recyclable, fire-resistant components. India's coastal highway buildout presents emerging demand for chloride-resistant reinforcement in bridge and port structures.
- Power Generation:Wind turbine OEMs in Northern Europe anchor continuous filament volume with larger-diameter roving adoption reducing layup labor.
- Defense Sector:Ballistic protection and structural applications in designated civil infrastructure programs favor domestic Chinese supply under MIIT directives.
- Consumer Goods:Sporting equipment and appliance manufacturers specify basalt for thermal insulation and vibration control.
Procurement scale concentrates with building materials and power generation. Emerging specification authority is shifting toward transportation manufacturers as recyclable thermoplastic compounding matures.
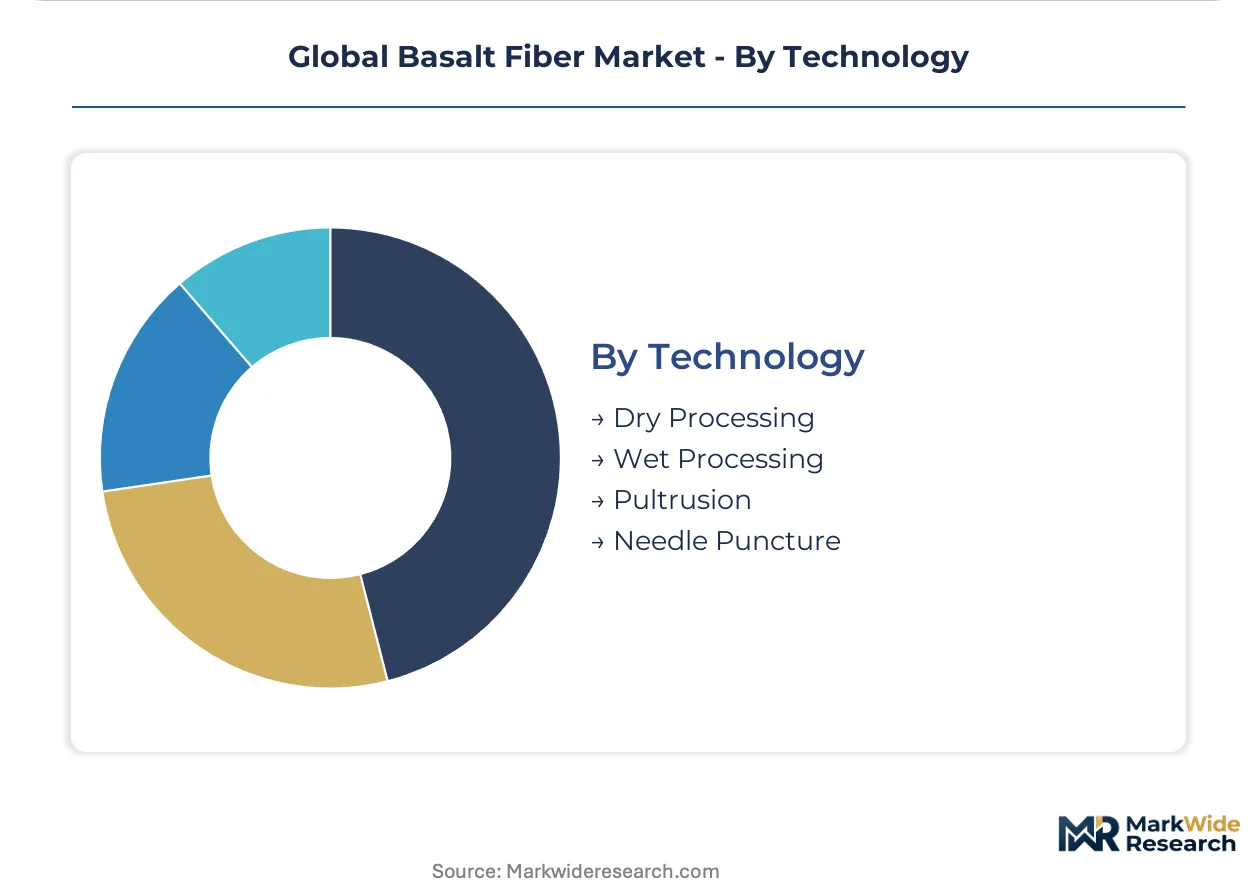
Technology:
Energy efficiency, yield rates, and resin system compatibility differentiate processing approaches for filament conversion into finished composite forms.
- Pultrusion:Continuous pulling of resin-impregnated rovings through heated dies produces dimensionally stable profiles with fiber volume fractions exceeding 60%. Margin capture exceeds wet processing through minimal waste and automated production. German and Danish wind blade manufacturers specify pultruded basalt spar caps for fatigue resistance and dimensional precision.
- Dry Processing:Direct melt feeding with electric furnace technology consolidates operational control for producers with captive volcanic rock feedstock. Kamenny Vek's Leningrad region operations exemplify energy-efficient filament drawing with reduced natural gas exposure.
- Wet Processing:Hand lay-up and resin infusion of fabrics and mats serves marine and infrastructure laminates. California and Texas pressure vessel fabricators accelerate pre-impregnated tape qualification to bypass on-site resin handling and EPA emissions protocols.
- Needle Puncture:Mechanical entanglement of chopped fibers produces three-dimensional mats for filtration and insulation applications without chemical binders.
Technology maturity centers on pultrusion for structural profiles. Fastest capability investment flows into dry processing electric furnace conversions for energy cost management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Volcanic rock deposits in Russia's Leningrad region anchor the raw-material foundation for premium filament supply, while Chinese basalt provinces and European infrastructure hubs shape demand trajectories across three distinct procurement zones.
China
State-backed wind blade programs and coastal highway construction drive specification of alkali-resistant reinforcement. MIIT industrial directives designate domestic basalt fiber as a strategic import substitute for carbon fiber in civil infrastructure. Zhejiang province hosts integrated pultrusion operations serving turbine manufacturers with captive melt-to-profile capabilities.
Russia
High-purity volcanic feedstock in the Leningrad region underpins continuous filament output for export-qualified suppliers. Eurasian Economic Union technical regulations align with REACH documentation standards for European market access. St. Petersburg industrial corridors concentrate electric furnace operations with reduced natural gas exposure through grid integration.
Germany
Wind turbine OEMs in Hamburg and Bremen anchor procurement of large-diameter rovings for structural spar caps. ECHA registration requirements filter supplier qualification toward REACH-registered sizing chemistries. Bavarian automotive tier suppliers pilot basalt-thermoplastic composites for recyclable interior components under EU Green Deal circularity mandates.
United States
California and Texas pressure vessel fabricators accelerate pre-impregnated tape qualification to bypass EPA emissions protocols for on-site resin handling. FAA fire-safety certification programs for aerospace interiors create qualification pathways in Wichita and Seattle manufacturing clusters. Infrastructure resilience codes in Florida and coastal states redirect rebar procurement toward chloride-resistant alternatives.
India
Coastal highway and port authority projects in Maharashtra and Gujarat generate procurement demand for alkali-resistant reinforcement in chloride-rich environments. Bureau of Indian Standards certification timelines constrain market entry for uncertified imports. Tamil Nadu automotive corridors explore basalt-polyamide compounding for closed-loop component manufacturing under PLI scheme incentives.
Global Basalt Fiber Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty certification pathways in aerospace and pressure vessel segments. The supplier base concentrates around captive melt operations with documented regulatory dossiers, while smaller filament drawers compete on regional infrastructure contracts. Three archetypes dominate: vertically integrated volcanic rock processors, pultrusion-focused profile converters, and qualification-driven specialty fiber suppliers. Competitive dynamics center on ECHA registration completion and electric furnace capacity expansion to offset energy cost volatility.
Among Russian-origin suppliers, Kamenny Vek exemplifies the captive melt archetype with Leningrad region feedstock control. Zhejiang GBF Basalt Fiber Co., Ltd. occupies a position within the integrated processing tier, while Mafic SA represents the qualification-focused specialist segment targeting aerospace certification pathways. These three anchors illustrate how geographic feedstock access, downstream integration depth, and regulatory documentation maturity stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Kamenny Vek |
| Zhejiang GBF Basalt Fiber Co., Ltd. |
| Mafic SA |
| Technobasalt-Invest LLC |
| ISOMATEX SA |
| Deutsche Basalt Faser GmbH |
| Sudaglass Fiber Technology |
| INCOTELOGY GmbH |
| Shanxi Basalt Fiber Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Platinum-rhodium bushing specialists in Russia's Leningrad region anchor the skilled-labor concentration that shapes pricing-tier spreads, with wage differentials between St. Petersburg engineering corridors and Chinese filament operations creating three-tier pricing stratification across premium aerospace-grade, standard wind-blade, and economy construction-grade supply tiers.
Pricing Analysis
Volume leadership sits with construction-grade chopped strand while margin capture concentrates in aerospace-qualification continuous filament. Price differentiation hinges on REACH/ECHA registration completeness and ISO-certified melt capacity, with unregistered Chinese supply facing discount pressure from European procurement exclusion. Project developers in India's coastal infrastructure sector exhibit highest price sensitivity, whereas German wind OEMs prioritize fatigue-performance guarantees over unit cost.
Supply Chain Analysis
Freight cost exposure from Leningrad-region feedstock to European wind-blade fabricators elevates landed pricing for Russian-origin filament against Chinese coastal supply. Raw material security draws from volcanic rock deposits in Russia's Leningrad region, Sichuan and Zhejiang provinces in China, and selective Ukrainian and Georgian quarries. Single-source vulnerability concentrates in platinum-rhodium alloy bushings sourced from South African and Russian metallurgical suppliers. Distribution runs through direct mill relationships for qualified aerospace programs and regional distributors for construction-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric furnace direct-melt technology is displacing natural gas-dependent legacy melting operations, compressing cost structures for producers with grid-integration capabilities and reshaping competitive viability across the value chain.
For Market Incumbents: Extend captive melt capacity through electric furnace conversion in St. Petersburg industrial corridors to offset natural gas volatility exposure. Deepen ECHA registration dossiers for sizing chemistry variants before 2025 regulatory deadlines tighten. Certification investment in FAA/EASA fire-smoke-toxicity protocols represents the critical defensive moat against carbon fiber substitution in aerospace interiors. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian coastal infrastructure procurement creates white-space opportunity for BIS-certified chopped strand supply. Target Maharashtra and Gujarat port authority projects with alkali-resistant rebar specifications. A joint-venture route with established Chinese pultrusion operators accelerates technical qualification without multi-year melt-capacity buildout. For Investors and Strategic Acquirers: The window for entry favors electric furnace-equipped mid-cap producers with incomplete REACH documentation but proven filament quality. Long-term viability rests on regulatory dossier completion timelines rather than raw capacity scale. Monitor ECHA registration completion rates among Russian and Chinese suppliers as the inflection signal for qualified-supplier status consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Capacity Conversion | Grid-integrated melting in St. Petersburg corridors reduces natural gas cost exposure for Kamenny Vek and Leningrad-region competitors. |
| REACH Sizing Chemistry Registration | ECHA dossier completion filters European wind-blade procurement toward Zhejiang GBF and registered Chinese suppliers. |
| FAA Fire-Safety Qualification | Pre-impregnated tape certification opens Wichita and Seattle aerospace interior manufacturing clusters to basalt substitution. |
| Backward Integration into Volcanic Feedstock | Captive quarry control in Sichuan province secures melt consistency for Chinese producers serving MIIT-designated infrastructure programs. |
| Joint Venture with Thermoplastic Compounder | Automotive tier supplier partnerships in Tamil Nadu enable closed-loop polyamide-basalt component manufacturing under PLI incentives. |
Research Approach
Trade statistics from Russian Customs Service, Chinese General Administration of Customs, and Eurostat COMEXT formed the secondary backbone for volume-flow validation. Primary interviews with wind blade procurement directors, ECHA regulatory consultants, basalt melt plant engineers, and Indian port authority materials engineers supplied operational parameter calibration. Technical specifications from Deutsche Basalt Faser and Zhejiang GBF product datasheets anchored quality-grade segmentation. Bottom-up filament capacity estimates triangulated against top-down composite demand projections across construction, energy, and transportation end-uses.
Bottom-up modeling aggregated named-producer capacity declarations with assumed utilization rates, while top-down demand estimation derived from wind turbine installation forecasts and infrastructure spending pipelines. Segmentation dimensions included filament geometry, processing technology, end-use application, and regional regulatory cluster. CAGRs emerged from curve-fitting historical price-volume relationships against projected substitution elasticities for E-glass and steel rebar. Energy cost scenarios incorporated natural gas futures curves and Chinese grid carbon-intensity trajectories.
Inputs from ECHA registration databases and MIIT industrial directives were available through the study window; gaps in Indian BIS certification timelines for basalt-reinforced concrete introduce uncertainty bands for subcontinent demand scaling. Forecasts reflect assumptions about electric furnace conversion rates and aerospace qualification cycle durations. Stakeholders should weight assumptions against their own operating context and regional regulatory engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Carbon Fiber Filament Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Fiberglass Resin Market
Fibers
Renewable Carbon Fibers Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Vinylon Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Fiberglass Cloth Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Fiberglass Mat Market
Fibers
Ceramic Fiber Market