
 Asia Pacific Ceramic Fiber Market | 2026-2036
Asia Pacific Ceramic Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Ceramic Fiber Market Intelligence
Asset-light leasing models for high-temperature furnace retrofits is fragmenting competitive dynamics across the Asia Pacific Ceramic Fiber Market. Morgan Advanced Materials leverages its spun fiber manufacturing scale to serve steel plant operators seeking flexible insulation procurement. Luyang Energy-Saving Materials anchors its position through backward integration into alumina silicate raw material sourcing. Isolite Insulating Products differentiates via specialized vacuum formed fiber boards for chemical manufacturing end users.
Ceramic fiber comprises alumina-silica based synthetic mineral wool produced through melt spinning or blowing processes, engineered to withstand continuous operating temperatures exceeding 1,200°C while delivering thermal insulation in kilns, furnaces, and boilers. Alumina silicate products dominate volume shipments due to cost efficiency in standard furnace insulation applications across steel plants and power generation facilities. Needled blanket technology captures expanding share in fire protection systems where installation speed and conformability reduce labor costs. Zirconia grades command premium positioning in ultra-high temperature kilns where mullite compositions reach performance limits.
China's MIIT enforces GB standards on refractory fiber emissions and energy efficiency in industrial heat equipment, while India's BIS mandates thermal conductivity benchmarks for insulating materials used in foundries and chemical manufacturing. Japan's METI promotes JIS-certified ceramic fiber adoption through industrial decarbonization incentives targeting power generation boiler upgrades. Stakeholders must monitor evolving national carbon accounting rules that tie insulation performance credits to verified lifecycle assessments rather than single-point thermal metrics.
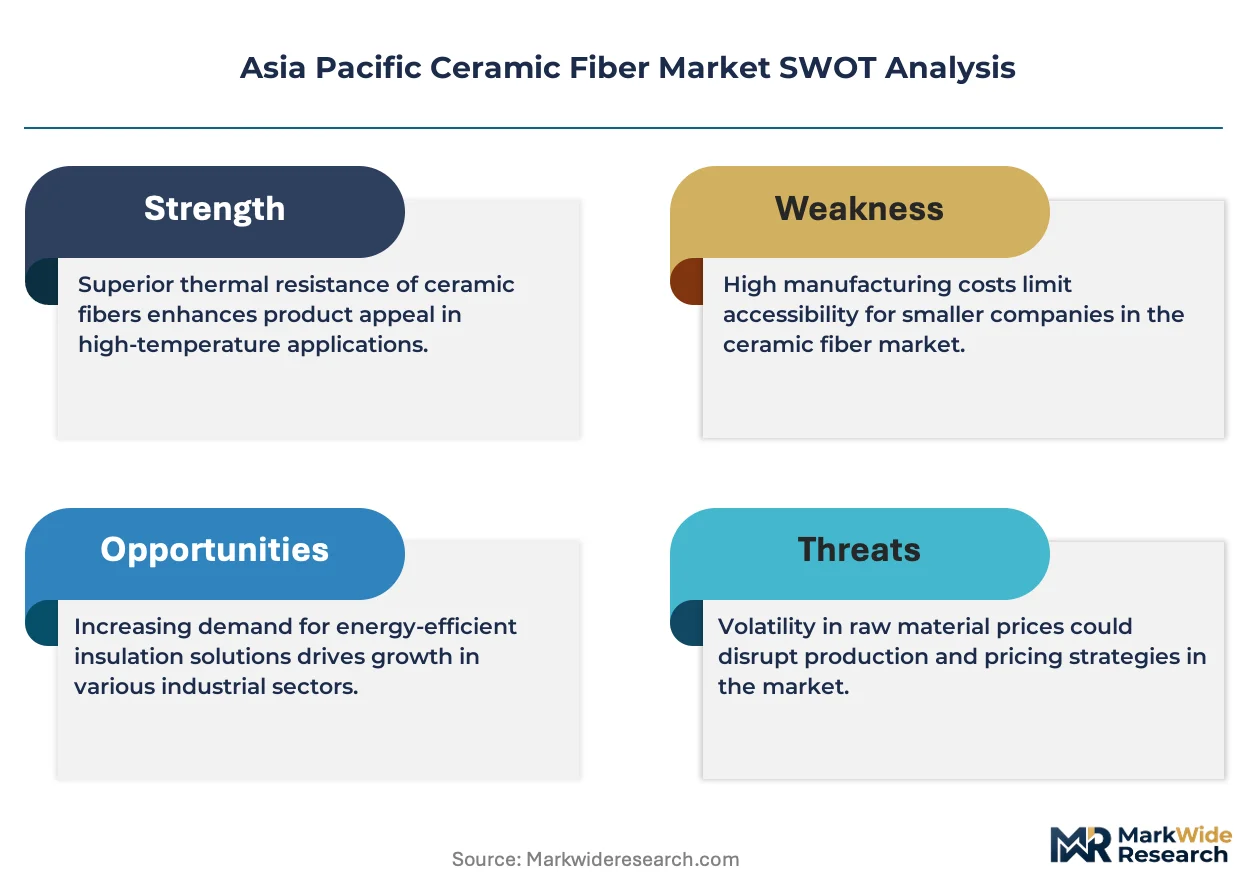
Market Dynamics
China's MIIT GB standards on refractory fiber emissions are forcing furnace operators across Shandong province to replace legacy insulation with low-biopersistent fiber grades, compressing product lifecycles and rewiring supplier qualification protocols.
Growth Catalysts
- Dual carbon goals:China's national carbon neutrality targets mandate industrial heat equipment upgrades, accelerating ceramic fiber deployment in steel plant reheating furnaces across Hebei and Jiangsu provinces.
- Steel production intensity:India's National Steel Policy drives capacity expansion in Odisha and Jharkhand, where new electric arc furnaces require high-temperature insulation solutions.
- Needled blanket technology:Faster installation speeds and reduced labor requirements in fire protection systems are displacing rigid board formats in commercial building applications.
Market Restraints
- Alumina price volatility:Raw material cost swings in bauxite-derived alumina silicate feedstocks squeeze margin predictability for blanket and board manufacturers.
- Shandong supply concentration:Over 60% of Chinese ceramic fiber production clusters in this single province, exposing buyers to localized environmental enforcement disruptions.
- Refractory ceramic fiber health classifications:IARC monograph concerns regarding respirable fiber toxicity trigger additional PPE and handling compliance costs across foundry end uses.
Strategic Opportunities
- Vietnam manufacturing expansion:Underpenetrated furnace insulation demand in emerging steel and ceramics sectors offers first-mover positioning for technical service providers.
- Japan METI decarbonization incentives:JIS-certified ceramic fiber adoption in power generation boiler retrofits unlocks subsidy-backed procurement channels.
- Digital thermal monitoring integration:Convergence of IoT sensor networks with predictive insulation maintenance is creating outcome-based service contract models.
Industry Challenges
- Refractory engineer scarcity:Specialized furnace design expertise required for high-temperature system integration outpaces vocational training output in India and Southeast Asia.
- BIS thermal conductivity certification timelines:Extended laboratory testing protocols delay product launches for insulating materials targeting Indian foundry markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Ceramic Fiber Market |
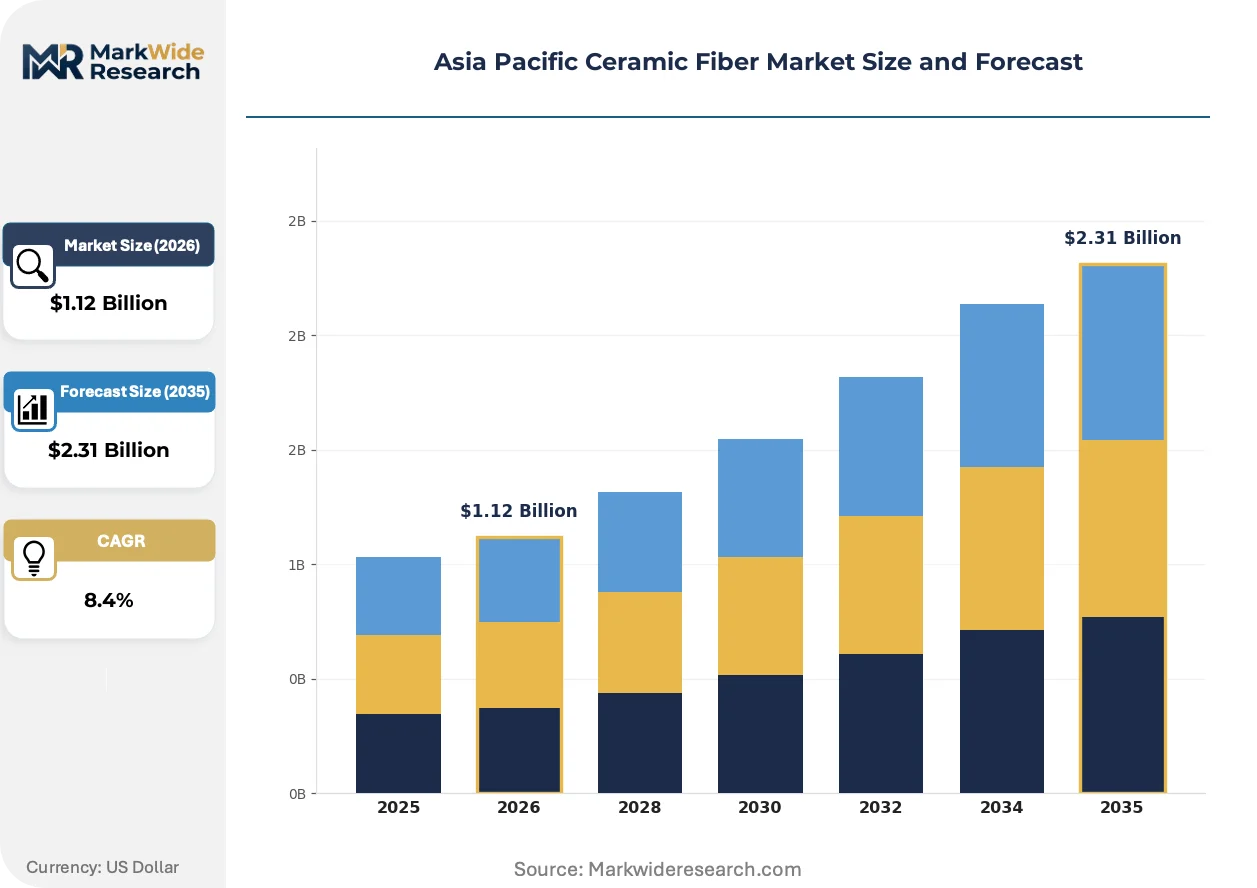
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina Silicate, High Alumina, Mullite, Zirconia, Calcium Silicate Technology: Spun Fiber, Vacuum Formed Fiber, Needled Blanket, Board, Paper Application: Furnace Insulation, Heat Shields, Fire Protection, Kilns, Boilers End User: Steel Plants, Power Generation, Chemical Manufacturing, Foundries |
| Companies Covered | IBIDEN Co., Ltd., RATH Group, Morgan Advanced Materials, Toshiba Materials, Nutec, Unifrax, Isolite Insulating Products, Yeso Insulating Products, Luyang Energy-Saving Materials, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Ceramic Fiber Market Strategic Shifts & Innovations
Digital twin technology is virtualizing furnace thermal performance modeling, compressing the design-validation cycle for insulation specification. This shift rewires how ceramic fiber suppliers engage engineering procurement teams.
Sol-gel derived biosoluble fiber formulations is virtualizing the traditional melt-spinning production paradigm. Japanese power utilities and Korean petrochemical complexes are piloting these grades for continuous operating temperatures above 1,000°C. The technology is virtualizing capital requirements for entry-level fiber manufacturing, enabling regional compounders to challenge incumbent spun fiber dominance.
India's BIS thermal insulation standards revision mandates stricter thermal conductivity benchmarks for materials deployed in chemical manufacturing and foundry environments. Compliance testing costs are rising for imported fiber products. Domestic manufacturers with in-house laboratory certification capabilities are capturing specification authority in Gujarat's industrial corridor.
Asset-light leasing structures for high-temperature furnace retrofits are fragmenting traditional capital equipment procurement patterns. Steel plant operators in China's Shandong province and India's Maharashtra state now prioritize flexible insulation procurement over ownership. Technical service providers with spun fiber manufacturing partnerships are capturing recurring revenue streams previously held by refractory contractors.
Asia Pacific Ceramic Fiber Market Segmentation
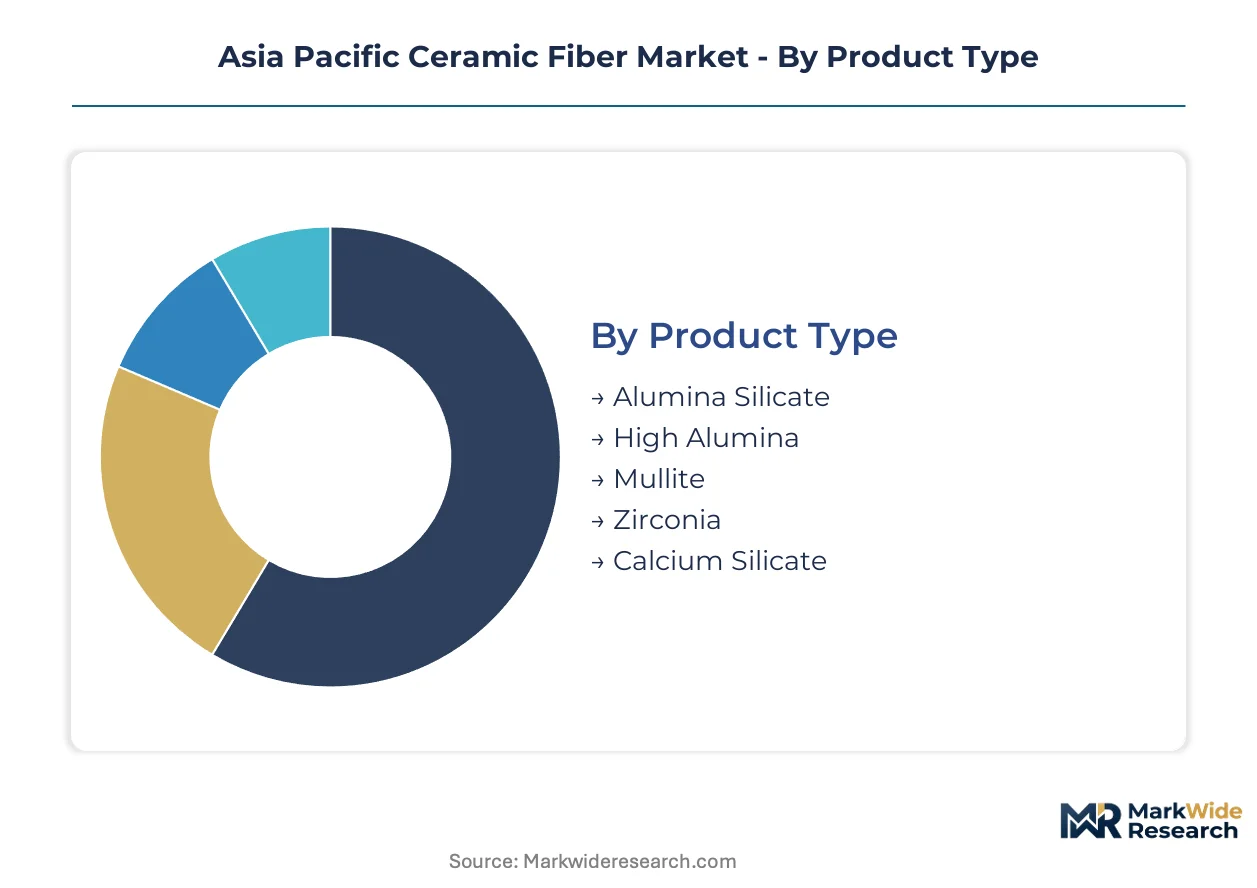
Ceramic fiber procurement decisions in Asia Pacific hinge on temperature thresholds, installation economics, and regulatory compliance across divergent industrial heat systems. Segmentation reveals how suppliers align technical specifications with end-use operating conditions and national certification requirements.
Product Type:
Alumina-silica chemistries span a use-case spectrum from standard furnace retrofits to ultra-high temperature kilns exceeding 1,400°C continuous operation.
- Alumina Silicate:Standard alumina-silica compositions deliver cost-efficient thermal insulation for continuous operating temperatures up to 1,260°C. Steel reheating furnaces across China's Hebei province and India's Odisha state consume the bulk of shipments as operators prioritize thermal efficiency compliance over premium grades.
- High Alumina:Elevated alumina content extends service temperature limits to 1,400°C while maintaining structural integrity under cyclic thermal loading. Electric arc furnace hoods in India's Jharkhand steel corridor specify this grade to meet BIS thermal conductivity benchmarks without zirconia cost premiums.
- Mullite:3:2 alumina-silica ratio compositions bridge performance gaps between standard and high-purity grades for kiln car insulation in Vietnam's emerging ceramics sector.
- Zirconia:Zirconia-stabilized fibers withstand 1,600°C+ environments in glass melting furnaces and specialty steel ladles where mullite degradation accelerates.
- Calcium Silicate:Non-fibrous rigid insulation competes in sub-1,000°C boiler applications where health classification concerns restrict traditional ceramic fiber deployment.
The dominant share belongs to Alumina Silicate, while Zirconia is closing the gap fastest in ultra-high temperature niches.
Technology:
Manufacturing processes segment by capital intensity, fiber morphology, and installation labor economics across retrofit versus greenfield projects.
- Spun Fiber:Long, continuous filaments produced through high-speed spinning deliver superior tensile strength and handling durability for module fabrication. Luyang Energy-Saving Materials leverages captive alumina silicate feedstock to supply spun fiber at scale for China's Shandong steel cluster furnace rebuilds.
- Vacuum Formed Fiber:Slurry-based forming creates rigid shapes with precise dimensional tolerances for burner blocks and combustion chamber linings. Isolite Insulating Products targets chemical manufacturing end users in Gujarat's industrial corridor with complex vacuum formed geometries that reduce field cutting waste.
- Needled Blanket:Mechanical needling interlocks fibers into conformable mats that compress installation time by 40% versus rigid boards in fire protection system retrofits.
- Board:Pressed and dried fiber sheets serve as backup insulation layers behind working linings in power generation boilers across Japan's METI-subsidized decarbonization programs.
- Paper:Thin, flexible sheets provide gasketing and expansion joint seals in kilns where thermal cycling demands compressible interfaces.
Spun Fiber commands the volume lead, though Needled Blanket is expanding most quickly in fire protection applications.
Application:
Operating temperature ranges and thermal cycling severity divide application segments by insulation lifecycle and replacement frequency.
- Furnace Insulation:Primary lining and backup layers in steel reheating furnaces represent the core demand driver across China and India. Dual carbon mandates in Hebei and Jiangsu provinces accelerate refractory fiber upgrades as plant operators seek emissions reduction credits tied to heat recovery efficiency.
- Heat Shields:Flexible blankets and rigid boards protect structural steel and personnel access points in high-temperature process equipment. Korean petrochemical complexes deploy multilayer heat shield configurations to meet insurer requirements for asset protection.
- Fire Protection:Passive fire containment systems in commercial and industrial buildings specify low-biopersistent fiber grades following IARC classification concerns. Needled blanket formats dominate this segment for rapid installation in curtain wall and penetration sealing.
- Kilns:Ceramics and refractory manufacturing kilns require zirconia or mullite grades for working faces exposed to direct flame impingement.
- Boilers:Power generation boiler upgrades under Japan's METI incentives drive JIS-certified ceramic fiber adoption for superheater and economizer insulation.
Furnace Insulation retains the largest installed base, yet Fire Protection is climbing the fastest on building code tightening.
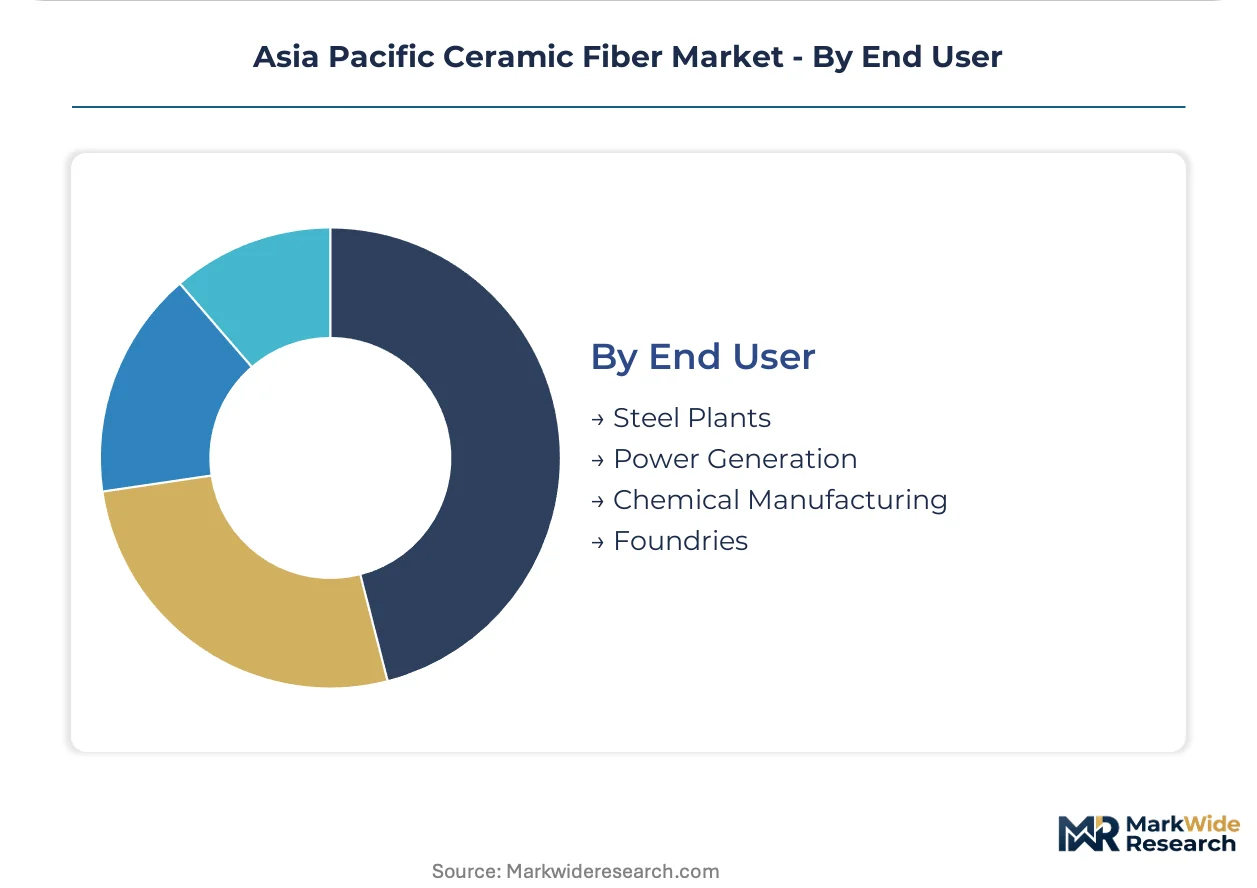
End User:
Capital expenditure cycles and regulatory compliance timelines differentiate end user segments by procurement velocity and technical service intensity.
- Steel Plants:Integrated mills and mini-mills in China and India drive bulk consumption of alumina silicate blankets and modules for reheating furnace rebuilds. China's National Steel Capacity Replacement Policy mandates insulation efficiency upgrades as a condition for new production permits.
- Power Generation:Coal, gas, and biomass boiler operators prioritize thermal performance verification under evolving carbon accounting rules. Japan's METI decarbonization incentives subsidize JIS-certified ceramic fiber retrofits that demonstrate measurable heat rate improvements.
- Chemical Manufacturing:Petrochemical crackers and syngas reactors specify vacuum formed shapes and high alumina grades for process containment. Gujarat's industrial corridor concentrates demand as domestic BIS-certified suppliers displace imports.
- Foundries:Ferrous and non-ferrous melting operations face elevated PPE and handling compliance costs due to refractory ceramic fiber health classifications.
Steel Plants anchor current demand, while Power Generation is gaining share fastest on boiler upgrade subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and Japan's METI decarbonization incentives are rewiring procurement patterns across the region. India's BIS thermal conductivity mandates and Vietnam's emerging steel capacity create divergent compliance environments. Industrial clusters in Shandong, Gujarat, and Kanto concentrate specification authority.
China
Steel reheating furnaces in Hebei and Jiangsu provinces drive alumina silicate blanket consumption as operators pursue emissions reduction credits. MIIT GB standards on refractory fiber emissions force Shandong-based manufacturers to retool for low-biopersistent grades. The Shandong production cluster supplies over sixty percent of national output, exposing buyers to localized environmental enforcement actions.
India
Electric arc furnace builds in Odisha and Jharkhand under the National Steel Policy expand addressable demand for high-temperature insulation. BIS thermal conductivity certification timelines extend product launch cycles for imported fiber manufacturers. Gujarat's industrial corridor concentrates chemical manufacturing demand where domestic suppliers with in-house testing capabilities displace foreign competitors.
Japan
METI subsidizes JIS-certified ceramic fiber adoption in power generation boiler retrofits targeting measurable heat rate improvements. Kanto region utilities pilot sol-gel derived biosoluble formulations for continuous operation above 1,000°C. Technical service providers integrate IoT thermal monitoring to capture outcome-based maintenance contracts.
South Korea
Petrochemical complexes deploy multilayer heat shield configurations to satisfy insurer requirements for asset protection in high-temperature process equipment. Busan-Ulsan industrial belt operators specify vacuum formed shapes for combustion chamber linings in crackers and syngas reactors. National carbon accounting rules tie insulation performance credits to verified lifecycle assessments.
Vietnam
Emerging steel and ceramics sectors generate first-mover opportunities for technical service providers with furnace retrofit expertise. Northern industrial zones around Hai Phong attract Chinese manufacturers seeking lower-cost production bases outside Shandong's regulatory perimeter. Local foundry operators face elevated compliance costs as health classification concerns trigger additional PPE requirements.
Asia Pacific Ceramic Fiber Market Key Industry Players
On the supply side, the industry is consolidating around scale-driven spun fiber manufacturers and specialized vacuum formed producers. Three archetypes dominate: backward-integrated raw material controllers, technology licensors with sol-gel capabilities, and technical service providers capturing leasing revenue streams. Competitive moves center on captive alumina silicate feedstock acquisition and digital thermal monitoring integration.
Among Asia-Pacific-based manufacturers, Luyang Energy-Saving Materials exemplifies the backward-integrated archetype through captive alumina silicate sourcing. Morgan Advanced Materials occupies a position as a scale-driven spun fiber supplier serving flexible procurement models. Isolite Insulating Products represents the specialization vector with vacuum formed capabilities for complex geometries.
| Leading Market Players |
|---|
| IBIDEN Co., Ltd. |
| RATH Group |
| Morgan Advanced Materials |
| Toshiba Materials |
| Nutec |
| Unifrax |
| Isolite Insulating Products |
| Yeso Insulating Products |
| Luyang Energy-Saving Materials |
| Others |
Cost & Logistics Intelligence
Shandong province's alumina silicate production cluster commands disproportionate pricing leverage across the Asia Pacific Ceramic Fiber Market as environmental enforcement actions periodically constrain furnace-ready fiber availability. Buyers in India's Gujarat corridor and Japan's Kanto utilities face volatile procurement costs when Shandong manufacturers retool for low-biopersistent grades under MIIT GB standards.
Pricing Analysis
Certification level creates the primary spread across product tiers, with JIS-certified grades for Japan's METI-subsidized boiler retrofits commanding premiums over standard BIS-compliant shipments for Indian foundries. Pricing stratifies across premium, standard, and economy tiers based on thermal performance verification and lifecycle assessment documentation. Cost compression in standard alumina silicate blankets is intensifying as Chinese spun fiber manufacturers exploit captive bauxite-derived feedstock advantages. Steel plant operators in Hebei province exhibit the highest price sensitivity, prioritizing thermal efficiency compliance over premium grades, while Korean petrochemical complexes demonstrate lower sensitivity due to insurer-mandated asset protection specifications.
Supply Chain Analysis
Bauxite-derived alumina and zirconia feedstocks anchor upstream material flows, with Chinese refineries and Australian mineral processors serving as primary sources. Manufacturing capacity concentrates in China, India, and Japan, with Shandong province alone supplying the majority of Chinese domestic output. The supply chain hinges on single-province concentration risk, exposing buyers to localized environmental enforcement disruptions and forced production halts. Distribution runs through technical service providers who bundle insulation procurement with furnace retrofit engineering, displacing traditional refractory contractor channels across Maharashtra and Shandong steel clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Ceramic Fiber Market sits in early-cycle expansion as dual carbon mandates across China and Japan accelerate furnace insulation replacement schedules ahead of regulatory deadlines. Penetration remains shallow in Vietnam's emerging steel sector and biosoluble fiber applications above 1,000°C.
For Market Incumbents: Entrench position through backward integration into alumina silicate feedstock sourcing and captive laboratory certification capabilities for BIS and JIS compliance. Sol-gel derived biosoluble formulations threaten spun fiber dominance in Japanese power utility applications, requiring R&D investment in non-melt-spinning production platforms. Capacity addition in Vietnam's northern industrial zones around Hai Phong reduces exposure to Shandong environmental enforcement volatility. For New Entrants and Emerging Players: Pursue technical service partnerships with steel plant operators in Vietnam's Hai Phong corridor and ceramics manufacturers in emerging Southeast Asian markets. Fire protection systems specify needled blanket formats where installation speed advantages displace rigid board incumbents. A go-to-market angle combining IoT thermal monitoring integration with flexible leasing structures captures recurring revenue streams previously held by established refractory contractors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with sol-gel capabilities and technical service providers with digital thermal monitoring integration. Long-term viability over the next decade rests on regulatory tailwinds from carbon accounting rules that tie insulation performance credits to verified lifecycle assessments. Acquisition targets should demonstrate in-house certification laboratory infrastructure and spun fiber manufacturing scale. The signal to watch is MIIT enforcement intensity in Shandong province, which would accelerate low-biopersistent grade adoption and compress legacy product lifecycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Captive bauxite-derived supply secures margin stability against raw material volatility in Shandong. |
| JIS Certification Investment | Unlocks METI-subsidized procurement channels for power generation boiler retrofits across Kanto utilities. |
| Sol-Gel Biosoluble Formulation Development | Enables entry into ultra-high temperature niches above 1,000°C without melt-spinning capital requirements. |
| IoT Thermal Monitoring Integration | Creates outcome-based service contracts that displace traditional refractory procurement in steel clusters. |
| Vietnam Manufacturing Footprint Expansion | Hai Phong positioning captures emerging steel and ceramics demand outside Shandong regulatory perimeter. |
Research Approach
Operator-level perspectives from furnace maintenance directors, steel plant procurement leads, refractory engineers, and technical service providers anchored the qualitative base. Primary interviews across China's Shandong and Hebei provinces, India's Gujarat and Odisha corridors, and Japan's Kanto region combined with secondary validation from MIIT GB standard filings, BIS certification registries, METI decarbonization program disclosures, and customs trade data. Bottom-up shipment analysis triangulated against top-down industrial heat equipment investment forecasts.
Scenario-bracketing around regulatory enforcement intensity and dual carbon compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, manufacturing technology format, application temperature threshold, and end-user capital expenditure cycle. CAGRs derived from fitted growth curves applied to verified installation volumes in steel reheating furnaces, power generation boilers, and chemical process equipment. Forecast inputs incorporated BIS thermal conductivity certification timelines and sol-gel formulation pilot adoption rates.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, alumina spot markets, or carbon credit valuation would shift the trajectory. Forecasts reflect assumptions regarding MIIT enforcement consistency and METI subsidy continuity. Cross-checking against refractory contractor order backlogs and furnace rebuild announcement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Sisal Market
Fibers
North America Nanofiber Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Global Metal Fiber Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Viscose Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global Electronic Fiberglass Market
Fibers
Global Fiberglass Market
Fibers
Global Nylon Monofilament Market
Fibers
Global Fiberglass Mold Market
Fibers
Carbon Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Precision Fiber Molding Market