
 Europe Downstream Processing Market | 2026-2036
Europe Downstream Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Downstream Processing Market Insights
CE marking under the EU Medical Device Regulation is rotating the competitive landscape for downstream processing equipment in Europe. Thermo Fisher Scientific leverages its chromatography portfolio to anchor positions in protein purification workflows across the region. Sartorius AG sustains technology leadership through membrane filtration systems designed for single-use bioprocessing. Lonza Group differentiates via integrated contract development and manufacturing services that extend from upstream cell culture to downstream polishing steps.
Downstream processing encompasses the isolation, purification, and concentration of biologically derived products from cell culture harvest through final formulation, employing unit operations such as depth filtration, protein A affinity capture, and viral clearance validated to log reduction targets. Chromatography resin consumption dominates material expenditure in monoclonal antibody production, where protein A media account for the largest margin pool despite growing interest in multimodal alternatives. Membrane technology competes for share in continuous bioprocessing adoption, while contract manufacturing organizations represent the fastest-growing end user segment as pharmaceutical firms outsource purification capacity.
EMA guidelines on biosimilar comparability and the EU Green Deal's sustainability reporting requirements through CSRD shape equipment selection and process validation protocols for European biomanufacturers. REACH compliance for chromatography resin chemistries and the F-Gas Regulation's phase-down of perfluorinated compounds constrain solvent choices in certain purification modalities. Stakeholders must monitor evolving EMA guidance on continuous manufacturing quality standards to anticipate retrofit demand for existing batch purification trains.
Market Dynamics
Contract manufacturing organizations in Germany's Rhine-Main biotechnology cluster are consolidating purification services, compressing equipment procurement cycles and reshaping vendor relationships across European biopharmaceutical supply chains.
Growth Catalysts
- EMA biosimilar comparability guidelines:These protocols mandate rigorous analytical characterization for downstream processing, expanding demand for high-resolution chromatography systems in monoclonal antibody manufacturing workflows.
- Single-use bioprocessing adoption:Membrane filtration technologies designed for disposable configurations reduce cross-contamination risk and facility turnaround times, accelerating deployment in multi-product contract manufacturing facilities.
- France's biocluster expansion:Paris-Saclay and Lyon biotech corridors are attracting purification-focused CDMO investments, concentrating demand for integrated downstream processing equipment in these metropolitan regions.
Market Restraints
- Protein A resin supply concentration:Three suppliers dominate high-performance affinity chromatography media, creating vulnerability in monoclonal antibody capture steps when geopolitical or manufacturing disruptions occur.
- REACH compliance burden:Registration requirements for novel chromatography chemistries extend development timelines and elevate regulatory costs for resin manufacturers introducing multimodal alternatives.
- F-Gas Regulation solvent constraints:The phase-down of perfluorinated compounds limits certain purification modalities dependent on specific solvent systems, forcing process revalidation for established biopharmaceutical products.
Strategic Opportunities
- Continuous bioprocessing integration:Perfusion cell culture coupled with continuous capture chromatography enables smaller facility footprints and higher productivity, appealing to capacity-constrained European manufacturers.
- CSRD sustainability reporting:The Corporate Sustainability Reporting Directive mandates supply chain transparency, creating competitive advantage for equipment vendors with verified carbon footprint data and circular economy service models.
- Spain's emerging CDMO presence:Barcelona's growing contract manufacturing base currently lacks indigenous purification expertise, representing white space for technology providers establishing regional application laboratories.
Industry Challenges
- Process analytical technology integration:Real-time quality attribute monitoring requires specialized data science capabilities scarce among traditional downstream processing engineering teams, slowing smart manufacturing adoption.
- Legacy batch train retrofit complexity:Existing stainless-steel purification infrastructure in established European facilities faces technical and economic barriers when adapting to continuous processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Downstream Processing Market |
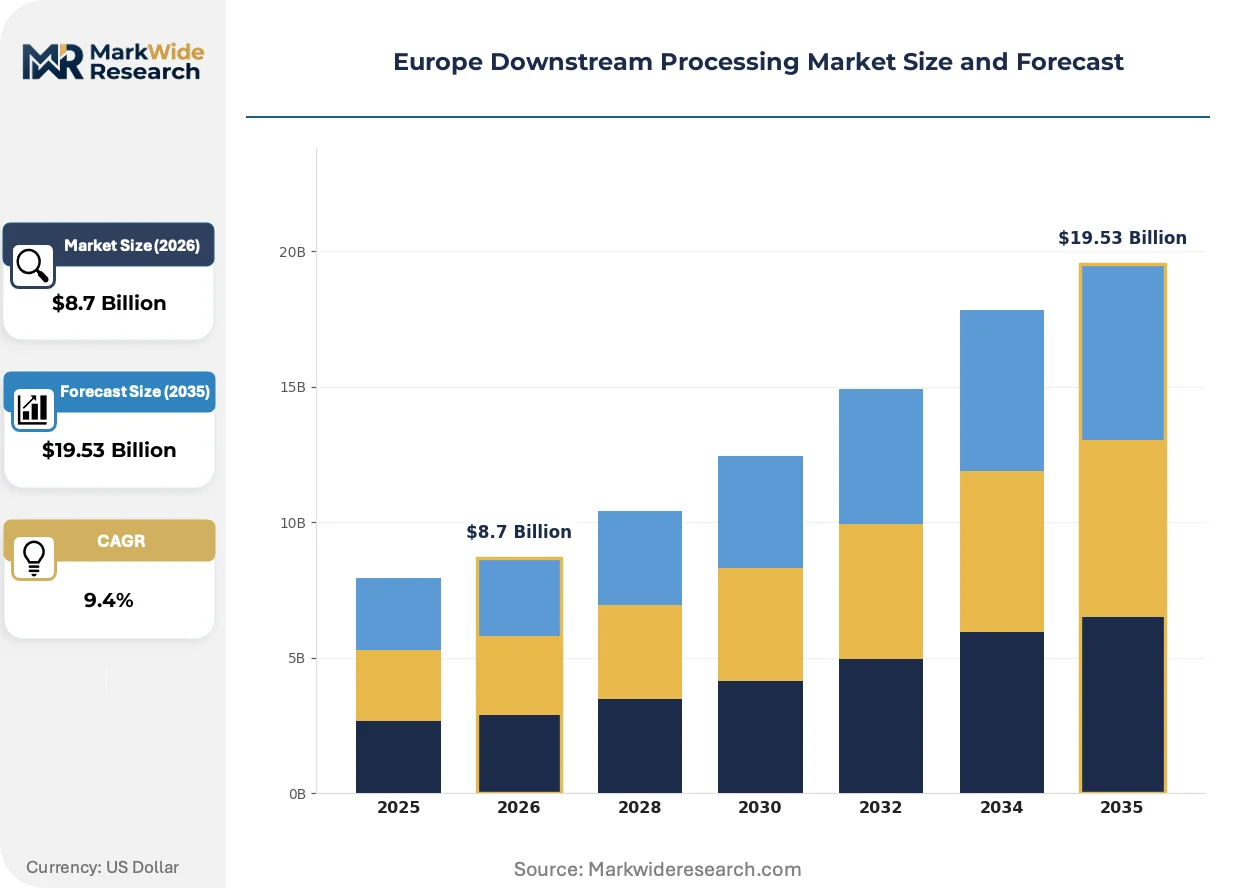
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography, Filtration, Precipitation, Centrifugation Technology: Membrane Technology, Affinity Chromatography, Ion Exchange, Normal Phase Chromatography End User: Pharmaceuticals, Biotechnology Firms, Academic Research Institutes, Contract Manufacturing Organizations Application: Vaccine Development, Monoclonal Antibody Production, Protein Purification, Enzyme Production |
| Companies Covered | Thermo Fisher Scientific, Eppendorf AG, Cytiva, Lonza Group, Getinge AB, Sartorius AG, Pall Corporation, Boehringer Ingelheim, Merck KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Downstream Processing Market Trends and Innovations
European downstream processing equipment is evolving through three interconnected vectors: manufacturing modality transitions, regulatory compliance architectures, and procurement relationship restructuring. Each vector carries distinct implications for technology providers and end-users.
Multimodal chromatography resins is bifurcating the capture landscape by combining ion exchange and hydrophobic interaction functionalities in single media, reducing column volume requirements and buffer consumption. Mid-sized biopharmaceutical firms in the Netherlands and Belgium are piloting these systems for bispecific antibody programs. This technology is bifurcating vendor competitive positions between established protein A suppliers and specialized resin developers targeting next-generation modalities.
EU Green Deal implementation through the CSRD framework is mandating lifecycle environmental impact disclosure for bioprocessing equipment, compelling manufacturers to redesign supply chains and service models. Equipment vendors must now document embodied carbon in chromatography systems and establish take-back programs for spent resins. German and Swiss biopharmaceutical firms are prioritizing suppliers with verified sustainability credentials in tender evaluations.
Service unbundling from capital equipment contracts is fragmenting traditional vendor-customer relationships, with European CDMOs separately sourcing installation qualification, operational training, and maintenance services. This disintermediation pressures original equipment manufacturers to defend margin through proprietary consumables and software subscriptions rather than integrated project pricing. The pattern is most pronounced among Netherlands-based contract manufacturers optimizing operational expenditure structures.
Europe Downstream Processing Market Segmentation
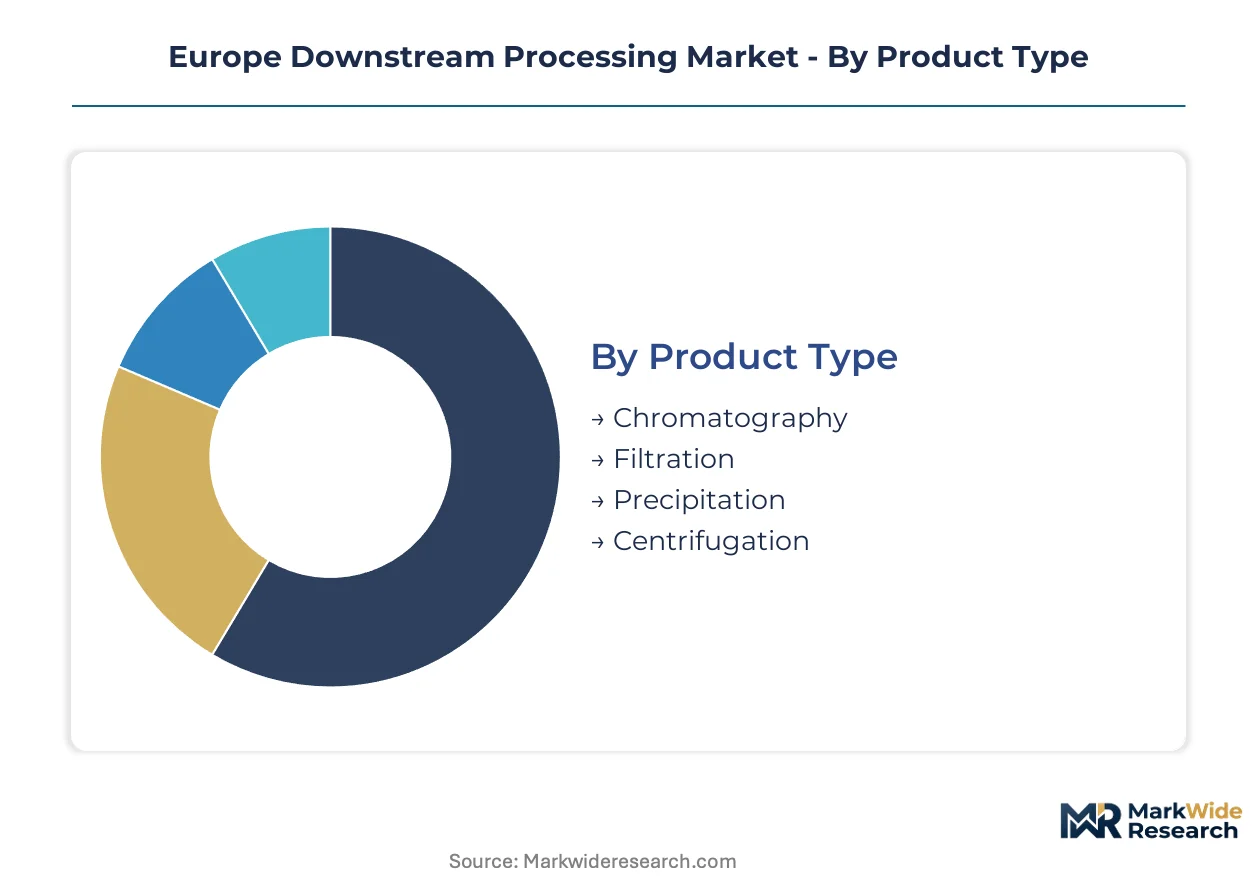
Downstream processing equipment flows through distinct procurement channels shaped by end-user scale and regulatory complexity. CDMOs favor bundled technology packages, while pharmaceutical manufacturers prioritize validated single-unit operations for monoclonal antibody workflows.
Product Type:
Chromatography systems and filtration equipment move through different commercial channels, with resins and membranes flowing via specialized distributors while capital equipment routes through direct manufacturer relationships.
- Chromatography:Affinity, ion exchange, and multimodal resin systems dominate material expenditure in monoclonal antibody capture steps. Protein A media consumption concentrates in Germany's Rhine-Main cluster where CDMOs are expanding purification capacity to serve biosimilar manufacturers.
- Filtration:Depth, tangential flow, and viral clearance membrane assemblies enable sterile processing and contaminant removal. Single-use configurations accelerate adoption among Netherlands-based contract manufacturers reducing cross-contamination risk in multi-product facilities.
- Precipitation:Salt and solvent-based separation methods persist for plasma-derived products and certain vaccine antigens where chromatography costs prove prohibitive.
- Centrifugation:Disk-stack and continuous flow systems handle harvest clarification upstream of polishing steps, with demand steady in established French biomanufacturing facilities.
By volume, Filtration leads. By growth pace, Chromatography is ahead.
Technology:
Technology selection hinges on target molecule characteristics and process economics, with affinity methods commanding premium pricing for high-purity therapeutic proteins.
- Membrane Technology:Tangential flow filtration and single-use capsule formats reduce facility infrastructure requirements. Adoption accelerates in Belgium and Dutch CDMOs optimizing operational expenditure through disposable processing architectures.
- Affinity Chromatography:Protein A and engineered ligand systems deliver selective capture of immunoglobulins from complex harvest matrices. Supply concentration among three dominant resin manufacturers creates vulnerability for European monoclonal antibody producers.
- Ion Exchange:Cation and anion exchange media provide intermediate polishing and contaminant removal at lower cost than affinity methods.
- Normal Phase Chromatography:Polar stationary phase separations serve specialized applications in peptide and oligonucleotide purification where reversed-phase alternatives underperform.
Membrane Technology holds the largest installed base. Affinity Chromatography commands the steepest expansion trajectory.
End User:
Procurement authority varies by organization type, with pharmaceutical giants running centralized sourcing and CDMOs delegating equipment selection to facility managers.
- Contract Manufacturing Organizations:Purification-focused service providers in Germany and France are consolidating multi-client capacity, driving demand for flexible, validated equipment platforms. Rhine-Main cluster CDMOs specifically prioritize chromatography skid configurations enabling rapid product changeover.
- Pharmaceuticals:Established biopharmaceutical manufacturers in Switzerland and Denmark maintain captive purification infrastructure for blockbuster monoclonal antibodies, sourcing replacement resins through long-term supply agreements.
- Biotechnology Firms:Emerging drug developers in Belgium and the Netherlands outsource manufacturing early, limiting direct equipment purchases to process development scale systems.
- Academic Research Institutes:University-based bioprocessing laboratories in France and Germany acquire smaller-scale purification equipment through public procurement frameworks.
Pharmaceuticals account for the greatest equipment value. Contract Manufacturing Organizations are gaining share fastest.
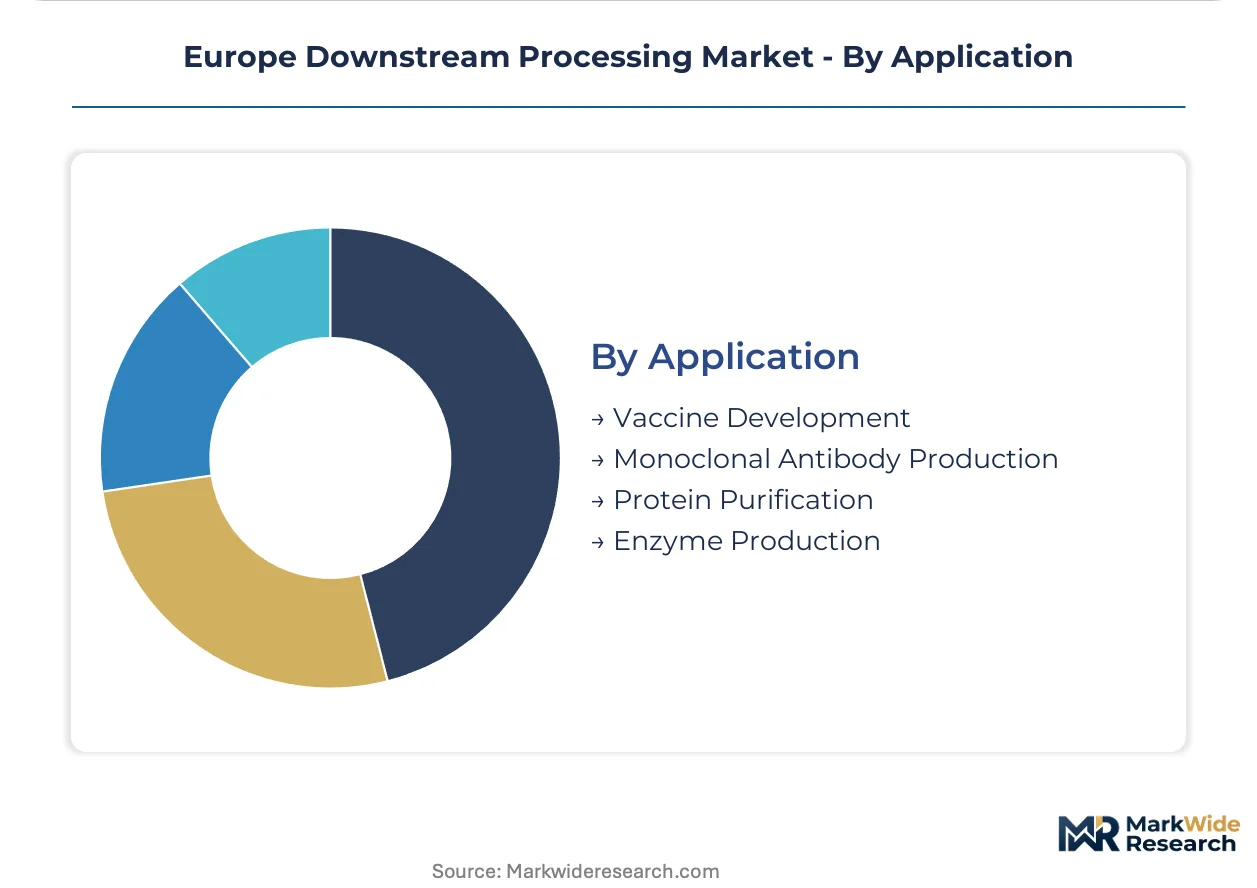
Application:
Application-specific requirements dictate equipment specifications, with viral safety and host cell protein clearance standards varying across therapeutic categories.
- Monoclonal Antibody Production:Standardized platform processes using protein A capture and viral filtration dominate capacity planning. EMA biosimilar comparability guidelines mandate rigorous analytical characterization, expanding demand for high-resolution polishing systems in German manufacturing facilities.
- Vaccine Development:Diverse antigen types require adaptable purification trains combining multiple modalities. Adjuvanted and mRNA vaccine manufacturing in Belgium and France drives interest in scalable downstream platforms.
- Protein Purification:Recombinant therapeutic proteins and enzymes employ multimodal chromatography to achieve target purity specifications.
- Enzyme Production:Industrial and diagnostic enzyme manufacturers prioritize cost-efficient recovery methods over pharmaceutical-grade purification.
Monoclonal Antibody Production represents the largest addressable market. Vaccine Development shows the most rapid demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European biopharmaceutical manufacturers concentrate procurement authority in contract manufacturing organizations and established biotechnology clusters. Germany, France, Switzerland, and the Netherlands anchor equipment demand through CDMO consolidation and monoclonal antibody production expansion.
Germany
EMA biosimilar comparability guidelines and REACH compliance requirements shape equipment selection for Rhine-Main cluster manufacturers. Protein A resin consumption concentrates in Hesse and Baden-Württemberg facilities serving biosimilar developers. Thermo Fisher Scientific and Sartorius AG anchor chromatography supply relationships across Frankfurt and Heidelberg biotech corridors.
France
Paris-Saclay and Lyon biotech corridors attract purification-focused CDMO investments from international drug developers. ANSM oversight of manufacturing quality standards drives validation requirements for downstream equipment procurement. Île-de-France contract manufacturers consolidate multi-client capacity, compressing vendor negotiation cycles for chromatography skids and single-use filtration systems.
Switzerland
Swissmedic regulatory frameworks mandate rigorous viral clearance validation for biopharmaceutical exports to EU markets. Basel and Zurich biomanufacturing facilities maintain captive purification infrastructure for blockbuster monoclonal antibodies. Lonza Group anchors integrated contract development services extending from cell culture through downstream polishing steps.
Netherlands
Belgian and Dutch CDMOs optimize operational expenditure through disposable processing architectures and service unbundling from capital equipment contracts. Leiden and Rotterdam biotech facilities prioritize membrane filtration technologies reducing cross-contamination risk in multi-product configurations. EMA centralized procedures accelerate market access for purified biologics manufactured in Dutch contract facilities.
United Kingdom
MHRA post-Brexit regulatory divergence creates parallel validation requirements for UK-based biomanufacturers serving EU and domestic markets. Cambridge and Oxford biotech clusters sustain demand for process development-scale purification equipment. British CDMOs navigate dual compliance burdens when exporting purified biologics to continental European markets.
Europe Downstream Processing Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with chromatography and filtration portfolios, creating tiered competitive positions around technology breadth and geographic footprint. Market structure concentrates in three supplier archetypes: integrated platform providers, specialized consumables manufacturers, and contract development organizations with captive equipment capabilities. Consolidation pressure intensifies as CDMOs demand bundled technology packages compressing standalone equipment vendor margins. Strategic moves center on sustainability credentialing under CSRD frameworks and continuous bioprocessing technology licensing.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions spanning chromatography systems through analytical instrumentation, representing the integrated platform archetype. Sartorius AG exemplifies the specialized consumables manufacturer with membrane filtration and single-use bioprocessing expertise. Lonza Group sits within the CDMO-with-captive-capability tier, differentiating through vertical integration from upstream cell culture to downstream polishing. Cytiva and Pall Corporation anchor positions in resin and filtration media supply, though their strategic postures reflect ownership transitions in recent years. Eppendorf AG represents mid-scale equipment specialists serving process development and academic research segments where validation requirements remain less stringent than commercial manufacturing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf AG |
| Cytiva |
| Lonza Group |
| Getinge AB |
| Sartorius AG |
| Pall Corporation |
| Boehringer Ingelheim |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German chromatography resin plants shapes both supply concentration and price floors across European downstream processing. Rhine-Main cluster CDMOs negotiate multi-year offtake agreements that lock in baseline volumes while allowing quarterly price adjustments tied to agarose and protein A ligand input costs.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate chromatography resin procurement, with protein A media pricing tied to agarose commodity benchmarks and engineered ligand synthesis costs. Price differentiation hinges on GMP certification tier and single-use versus stainless-steel configuration compatibility, with validated systems commanding substantial premiums. Pricing pressure stems from CDMO consolidation in Germany and France compressing vendor margins through bundled technology tenders. Small biotechnology firms exhibit highest price sensitivity, while established Swiss pharmaceutical manufacturers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Just-in-time inventory strategies predominate among Netherlands-based CDMOs operating multi-product facilities, whereas German manufacturers maintain strategic stockpiles of protein A resins to mitigate supply disruption risks. Production concentrates in Germany, Sweden, and the United States for high-performance affinity media, with tangential flow filtration membranes sourcing primarily from German and Swiss suppliers. Raw material dependencies include agarose polysaccharides, perfluorinated solvents constrained by F-Gas Regulation phase-downs, and engineered protein ligands. Single-source vulnerability in protein A resin supply creates structural risk for European monoclonal antibody producers. Distribution runs through authorized distributors for consumables and direct manufacturer relationships for capital equipment skids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
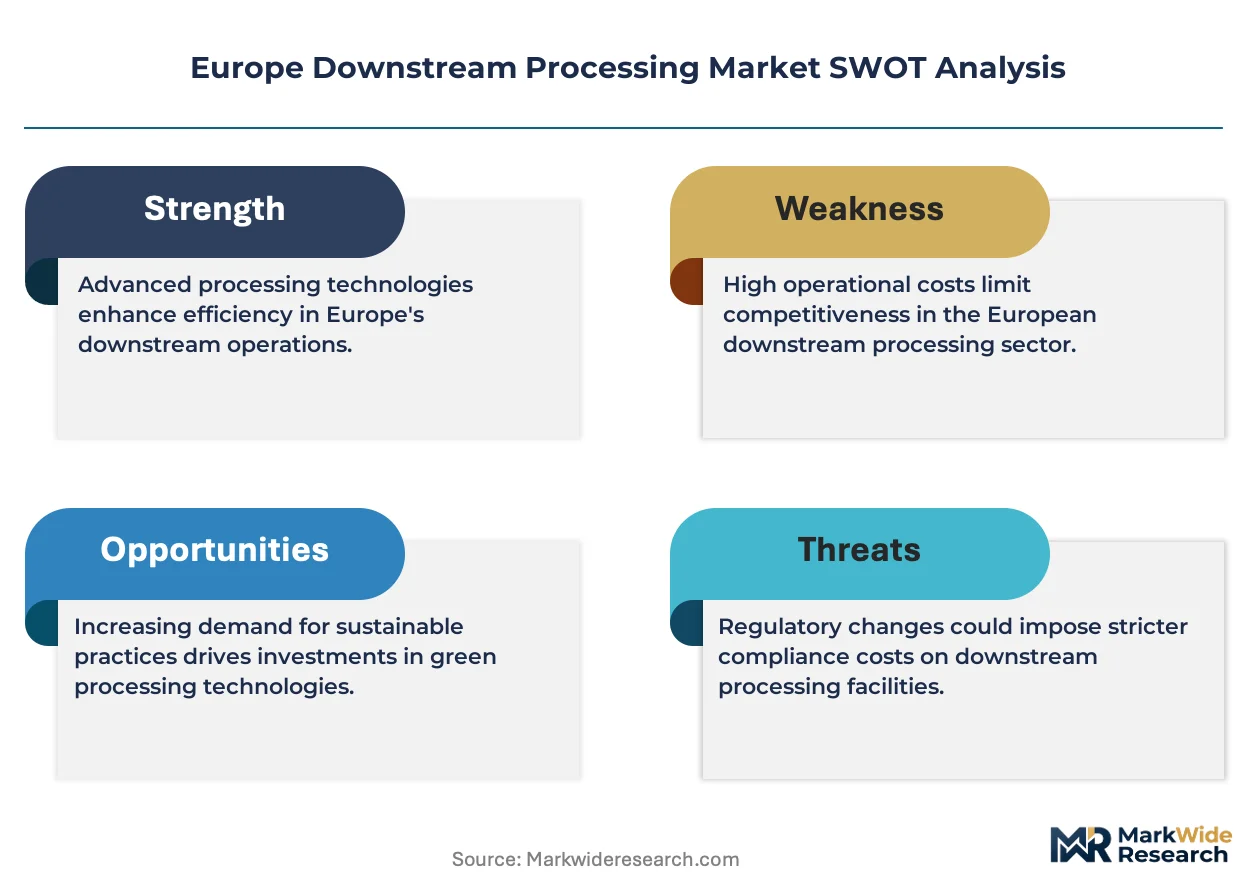
Fragmentation opportunity exists across European downstream processing as CDMO service unbundling creates niches for specialized consumables vendors and independent validation service providers. Outsourced purification demand from mid-sized biotechnology firms generates entry points below integrated platform provider radar.
For Market Incumbents: Fortify chromatography resin supply positions through backward integration into agarose cultivation or captive ligand synthesis capabilities. Lock in Rhine-Main cluster CDMO relationships via circular economy take-back programs that satisfy CSRD disclosure requirements. Defend against multimodal resin substitutes by accelerating protein A productivity improvements and single-use configuration breadth.
For New Entrants and Emerging Players: CE marking fast-track for continuous bioprocessing skids opens regulatory pathways into Spain's Barcelona CDMO corridor, where indigenous purification expertise remains underdeveloped. Target vaccine manufacturing applications in Belgium and France requiring adaptable multimodal trains. Establish regional application laboratories demonstrating viral clearance validation capabilities to differentiate from remote technical support models.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration specialists with single-use bioprocessing expertise over chromatography resin developers facing protein A substitution pressure. Long-term viability hinges on sustainability credentialing depth and continuous processing architecture readiness. Watch EMA guidance publication on continuous manufacturing quality standards as inflection indicator for retrofit demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Circular Economy Service Model | CSRD-compliant resin take-back programs differentiate vendors in German pharmaceutical tenders. |
| Continuous Bioprocessing Licensing | Perfusion-coupled capture chromatography enables smaller facility footprints for capacity-constrained European manufacturers. |
| Regional Application Laboratory Expansion | Barcelona presence addresses Spain's emerging CDMO purification expertise gap. |
| Multimodal Resin Development | Ion exchange-hydrophobic interaction combinations reduce buffer consumption for Netherlands bispecific antibody programs. |
| Strategic Stockpile Partnerships | Long-term offtake agreements with Rhine-Main CDMOs secure protein A resin allocation during supply disruptions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocessing engineers, CDMO procurement directors, EMA regulatory affairs specialists, and chromatography resin product managers; and secondary validation through EMA guideline documents, REACH registration databases, EU Green Deal implementation texts, and SEC filings from publicly traded life science conglomerates. Bottom-up equipment procurement tracking across German, French, Swiss, and Dutch manufacturing facilities triangulated against top-down market sizing from disclosed resin consumption patterns and CDMO capacity expansion announcements.
Forecasts spanning the projection horizon employed segment-level modeling across product type, technology modality, end-user organization scale, and therapeutic application categories. CAGRs derived from equipment replacement cycles, biosimilar pipeline progression timelines, and CDMO consolidation velocity assumptions. Industry-specific inputs included protein A resin productivity improvements, F-Gas Regulation solvent phase-down compliance costs, and EMA continuous manufacturing guidance development status.
Underlying assumptions cover regulatory timeline adherence, CDMO consolidation pace, and resin supply concentration stability, with deviation risk concentrated in REACH compliance timeline extensions and geopolitical disruption to engineered ligand synthesis capabilities. Revision becomes warranted when EMA continuous manufacturing guidance crosses publication thresholds or when protein A resin supply concentration shifts through manufacturer consolidation or facility closures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market