
 Germany Insulin Drugs and Delivery Devices Market | 2026-2036
Germany Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Insulin Drugs and Delivery Devices Market Foresight
Market Context
Home care is pivoting toward connected insulin delivery systems that reduce clinical dependency and improve glycemic control. Novo Nordisk leverages its integrated portfolio spanning analog insulins and smart pens to sustain leadership across outpatient channels. Sanofi anchors its position through long-acting insulin formulations optimized for basal-bolus regimens, while Ypsomed competes with compact, rechargeable patch pumps designed for discreet wearability.
Technical Definition and Segment Structure
Germany Insulin Drugs and Delivery Devices encompasses recombinant human and analog insulin formulations alongside mechanical and electronic systems for subcutaneous administration, including pen injectors with dose memory, tethered pumps with predictive low-glucose suspend, and disposable patch pumps operating at fixed basal rates with bolus triggers. Long-acting insulin products occupy the deepest margin pools due to patent-protected analogs and chronic daily dosing requirements, while insulin pumps represent the fastest-growing delivery method as Type 1 diabetes patients and intensive Type 2 regimens shift toward algorithm-assisted therapy. Rapid-acting insulin sustains volume leadership through pre-meal correction dosing paired with carbohydrate counting protocols.
Regulatory Framework and Outlook
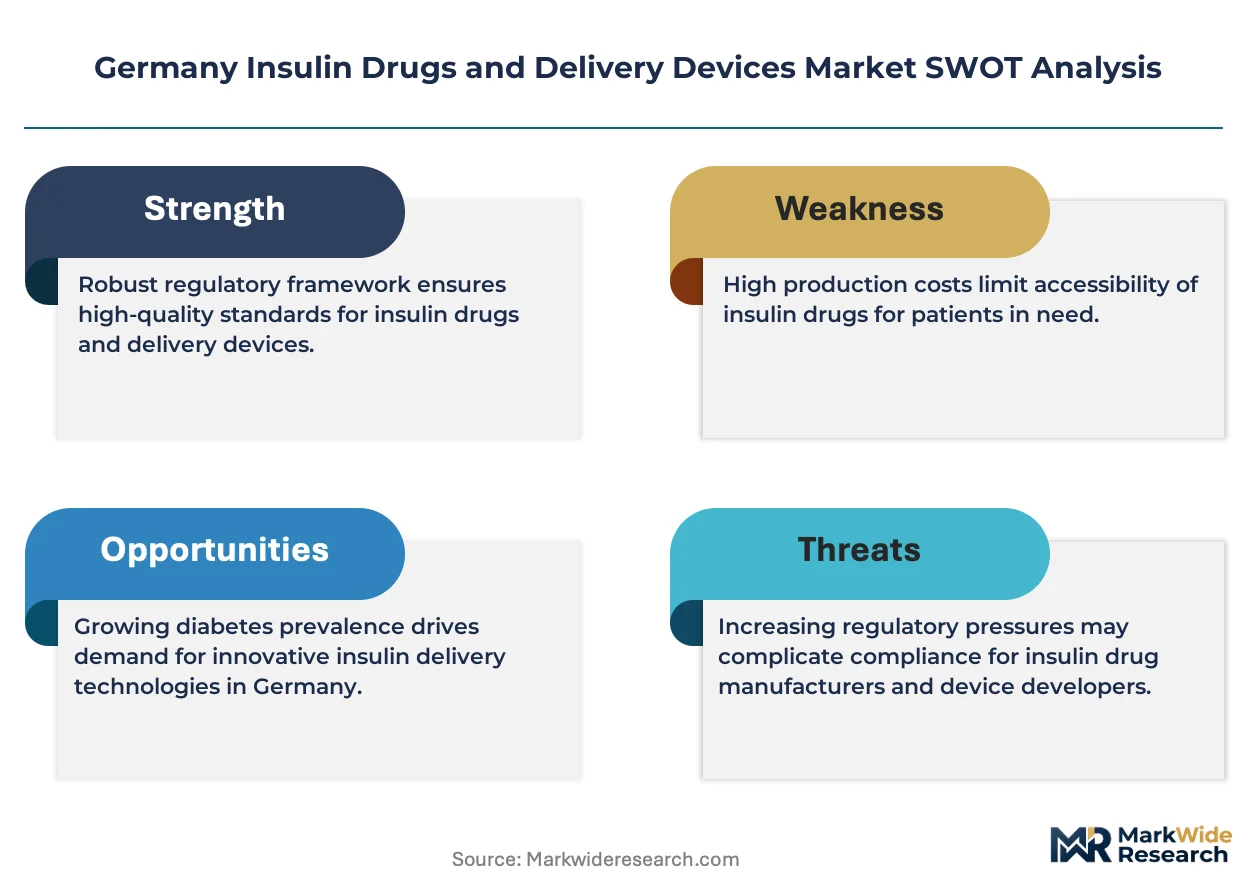
The BfArM governs pharmaceutical marketing authorizations for insulin products under German Medicines Act provisions aligned with EMA centralized procedures, while the BfArM's DiGA directory regulates digital companion applications that dose-adjust based on continuous glucose monitor feeds. CE marking under the EU MDR governs active delivery devices, with notified body scrutiny intensifying for software-controlled pumps with automated insulin delivery algorithms. Stakeholders must monitor reimbursement negotiations between the G-BA and manufacturers, as reference pricing dynamics for biosimilar insulins will reshape competitive positioning across statutory health insurance channels.
Market Dynamics
The BfArM's DiGA fast-track pathway is compressing development cycles for algorithm-driven insulin delivery, forcing manufacturers to restructure R&D around software validation rather than hardware iteration alone.
Growth Catalysts
- DiGA Directory Expansion:The BfArM's digital health approval framework enables connected pens and dose-optimizing apps to reach reimbursement faster than traditional medical devices.
- Home Care Migration:Outpatient diabetes management is shifting from hospital-based infusion centers to patient-controlled systems, expanding addressable volume for self-administered delivery devices.
- Algorithm-Assisted Therapy:Predictive low-glucose suspend functions in next-generation pumps are converting intensive Type 2 regimens from multiple daily injections to automated delivery.
Market Restraints
- Reference Pricing Pressure:The G-BA's biosimilar insulin negotiations compress margins for originator analogs, squeezing R&D budgets for incremental delivery innovation.
- Notified Body Bottleneck:EU MDR scrutiny of software-controlled pumps with automated delivery algorithms extends CE marking timelines by 12-18 months for new entrants.
- Active Pharmaceutical Ingredient Concentration:Recombinant insulin bulk manufacturing clusters in Denmark and the United States, exposing German formulators to single-source supply risk.
Strategic Opportunities
- North Rhine-Westphalia Specialist Networks:University hospital clusters in Düsseldorf and Cologne offer pilot environments for closed-loop system validation before national rollout.
- Carbohydrate Counting App Integration:DiGA-classified digital companions that sync continuous glucose monitor data with insulin dose calculations represent uncaptured reimbursement bandwidth.
- Disposable Patch Pump White Space:Compact, rechargeable wearable designs for discreet basal-bolus delivery remain underdeveloped relative to tethered pump saturation.
Industry Challenges
- Software-Hardware Competency Fusion:Traditional device manufacturers lack embedded systems engineering depth for FDA/BfArM-aligned algorithm validation.
- Legacy System Interoperability:Existing continuous glucose monitor installations use proprietary data protocols, complicating third-party insulin pump integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Insulin Drugs and Delivery Devices Market |
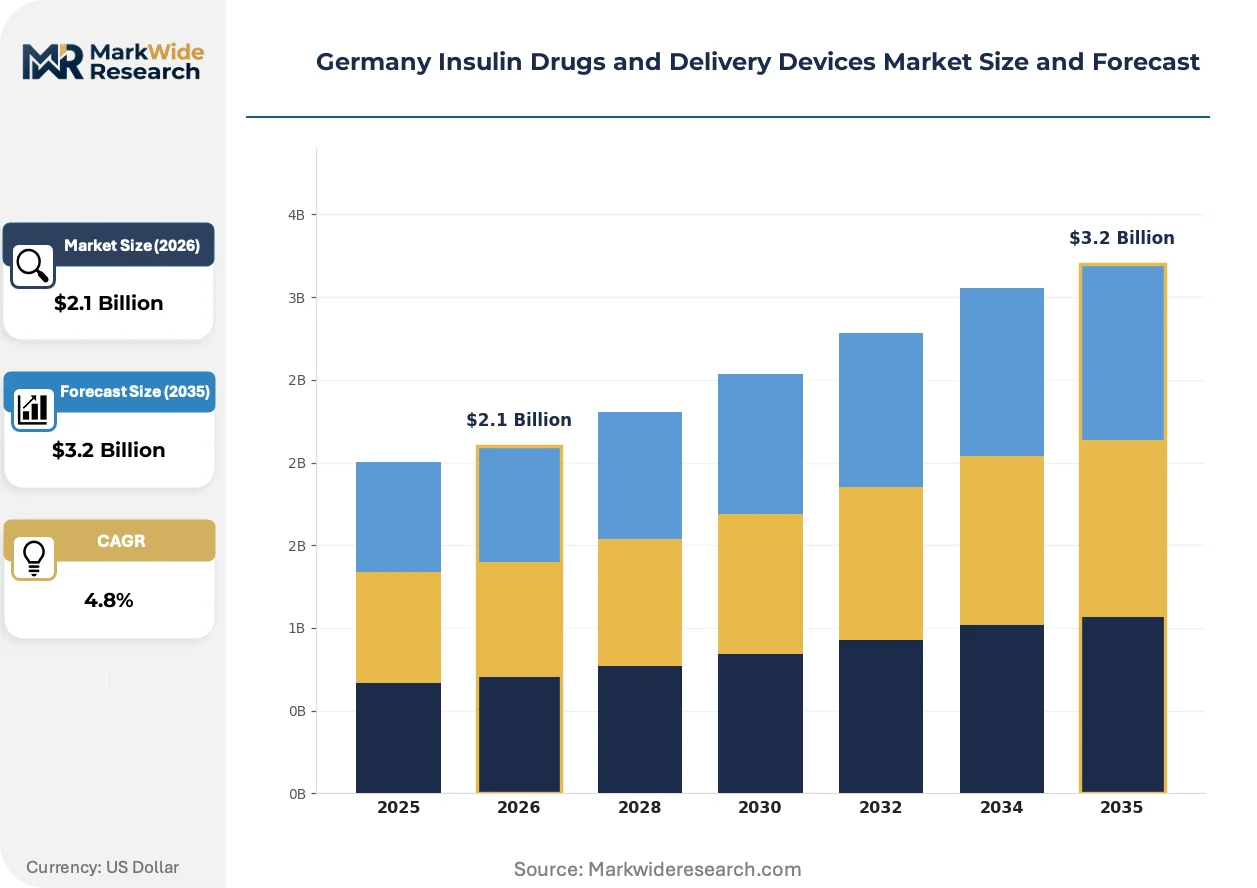
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Premixed Insulin, Insulin Pens, Insulin Pumps Delivery Method: Subcutaneous Injection, Inhalable Insulin, Transdermal Patches, Jet Injectors Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Latent Autoimmune Diabetes End User: Hospitals, Diabetes Clinics, Home Care, Specialized Pharmacies |
| Companies Covered | Novo Nordisk, Medtronic, Eli Lilly and Company, Sanofi, Ypsomed, Insulet Corporation, Roche, Abbott, Tandem Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Insulin Drugs and Delivery Devices Market Shifts & Advancements
Connected delivery systems are fragmenting the traditional pen-and-syringe market, with data-generating devices commanding reimbursement premiums over mechanical alternatives.
Smart pen injector platforms with dose memory and Bluetooth telemetry are modularizing the patient experience, allowing Type 1 diabetes users in Bavaria to segment basal tracking from bolus logging across multiple devices. Endocrinology practices are adopting these systems to reduce clinic visit frequency while maintaining glycemic visibility. This modularity is compressing the traditional pump-versus-pen decision into a spectrum of interoperable components.
The BfArM's DiGA fast-track under the German Medicines Act is accelerating software-based dose adjustment tools through parallel regulatory review, collapsing the historical gap between device approval and companion app reimbursement. Manufacturers are restructuring quality management systems around IEC 62304 medical software standards. Patch pump developers with integrated continuous glucose monitor feeds face the steepest compliance burden but capture the highest reimbursement tiers.
Patients in statutory health insurance channels are consolidating purchasing decisions through specialized diabetes centers rather than retail pharmacy, concentrating volume with centers offering integrated device training and remote monitoring. This channel compression disadvantages manufacturers without dedicated field clinical specialist teams. The shift is most pronounced in Baden-Württemberg, where integrated care contracts bundle device procurement with outcome guarantees.
Germany Insulin Drugs and Delivery Devices Market Segmentation
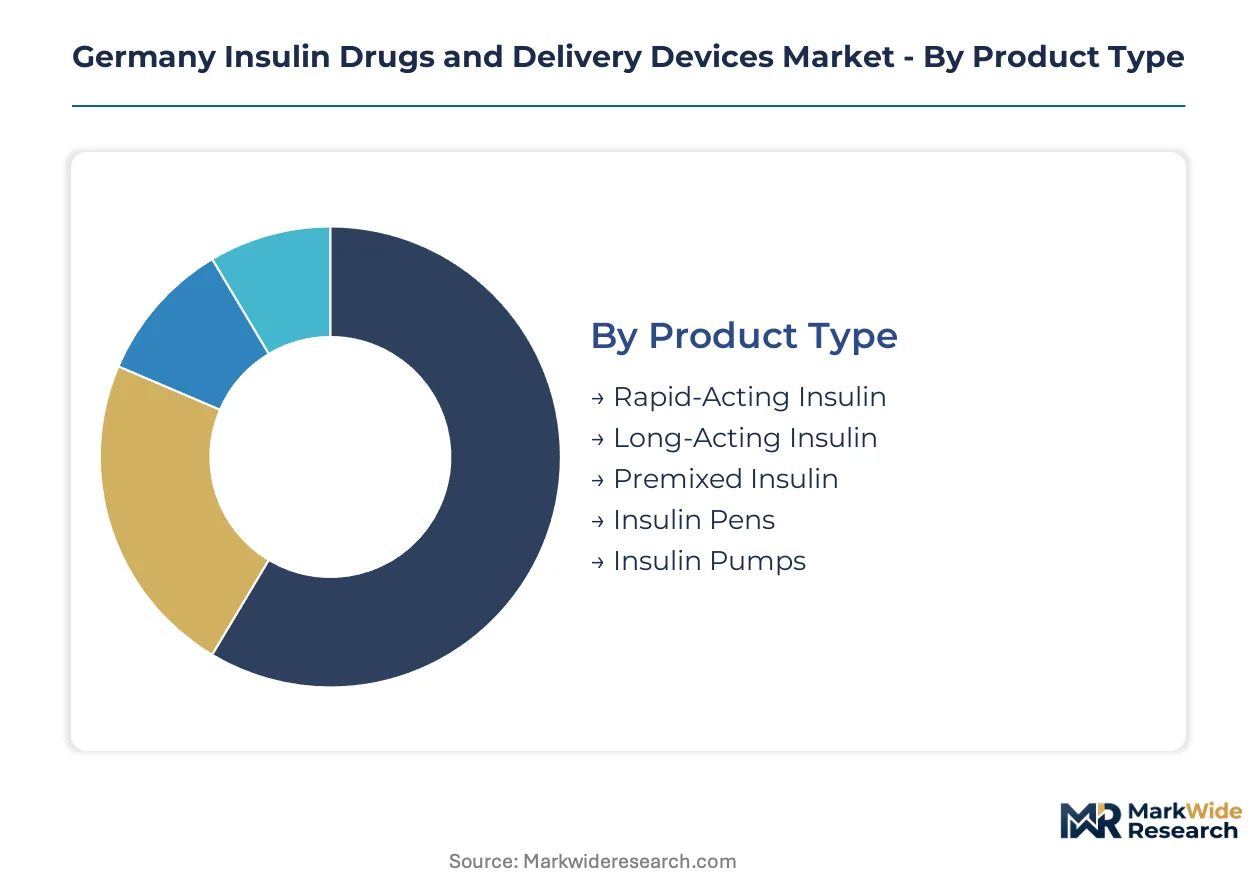
Segmentation reveals how reimbursement pathways and patient acuity reshape procurement patterns across German diabetes care. Each dimension exposes distinct margin structures and regulatory touchpoints that manufacturers must navigate.
Product Type:
Upgrade cycles in German diabetes management are compressing as algorithm-assisted devices displace legacy mechanical systems, forcing portfolio rebalancing toward connected delivery platforms.
- Rapid-Acting Insulin:Analog formulations engineered for 15-minute onset kinetics dominate pre-meal correction protocols. Demand clusters in Bavaria's university hospital networks where carbohydrate counting education programs are most intensive.
- Long-Acting Insulin:Patent-protected basal analogs with 24-hour flat profiles anchor chronic therapy regimens. North Rhine-Westphalia's statutory health insurance channels favor these formulations for their reduced hypoglycemia risk in elderly populations.
- Premixed Insulin:Fixed-ratio combinations simplify dosing for patients with limited numeracy or vision impairment.
- Insulin Pens:Reusable and disposable pen systems with dose memory functionality bridge the gap between syringes and pumps.
- Insulin Pumps:Tethered and patch pump configurations with predictive low-glucose suspend are gaining reimbursement traction through DiGA-aligned digital companions.
Volume placements concentrate in Long-Acting Insulin; the faster expansion belongs to Insulin Pumps.
Delivery Method:
Cost stratification across delivery technologies creates three distinct reimbursement tiers, with automated systems commanding premium codes over mechanical alternatives.
- Subcutaneous Injection:Pen and syringe-based administration remains the volume backbone, though smart pen telemetry is elevating this category into connected care pathways. Baden-Württemberg's integrated care contracts increasingly bundle device procurement with training outcomes.
- Inhalable Insulin:Pulmonary delivery systems bypass injection anxiety for needle-averse patients, though pulmonary function screening requirements limit addressable populations.
- Transdermal Patches:Microneedle array patches for basal delivery are emerging through BfArM's DiGA pathway as discreet alternatives to tethered pumps.
- Jet Injectors:Needle-free pressure delivery systems serve niche populations with severe phobia or lipohypertrophy complications.
Subcutaneous Injection captures the greatest prescription volume; transdermal patches are climbing the fastest as discreet wearability drives patient preference.
Application:
Patient acuity tiers determine device complexity requirements, with autoimmune etiologies demanding more intensive monitoring infrastructure than metabolic presentations.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive basal-bolus regimens or automated delivery systems. Pediatric and adolescent populations in Hamburg and Berlin generate concentrated demand for closed-loop pump-CGM integration.
- Type 2 Diabetes:Progressive beta-cell failure creates a gradient from oral agents through basal insulin to intensive injection or pump therapy. Saxony's elderly demographics drive volume for simplified pen systems with large dose displays.
- Gestational Diabetes:Temporary insulin requirements during pregnancy prioritize rapid-acting analogs with established fetal safety profiles.
- Latent Autoimmune Diabetes:Adult-onset autoimmune presentations often misdiagnosed as Type 2 require earlier escalation to insulin-intensive regimens than typical metabolic diabetes.
Type 2 Diabetes accounts for the largest patient population; Type 1 Diabetes shows the steepest expansion trajectory for automated delivery system adoption.
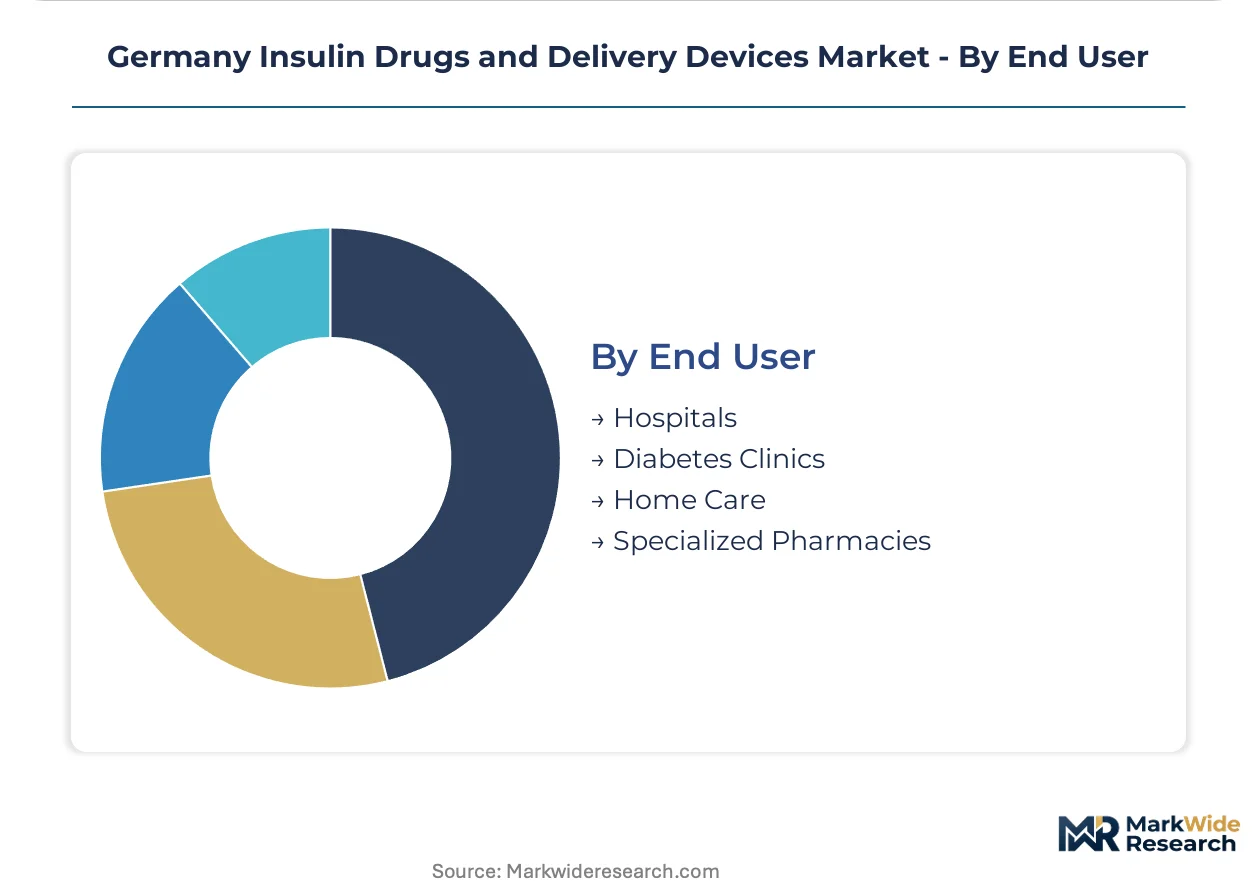
End User:
Channel consolidation through specialized diabetes centers is displacing retail pharmacy for device procurement, concentrating volume with institutions offering integrated training and remote monitoring capabilities.
- Hospitals:Acute care settings manage diabetic ketoacidosis and perioperative glycemic control with intravenous insulin protocols. University hospitals in Heidelberg and Tübingen anchor regional referral networks for complex case stabilization.
- Diabetes Clinics:Outpatient specialist centers bundle device dispensing with education and outcome monitoring. These clinics in North Rhine-Westphalia are piloting closed-loop system validation before broader statutory health insurance coverage.
- Home Care:Self-administered delivery systems with telemedicine support are expanding as DiGA-classified apps enable remote dose adjustment. This channel is most developed in Bavaria where rural access gaps favor decentralized management.
- Specialized Pharmacies:Community pharmacies with diabetes focus provide initial device training and supply continuity for stable patients on established regimens.
Volume placements concentrate in Diabetes Clinics; Home Care is gaining share fastest as reimbursement shifts toward outpatient management incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's BioRiver cluster anchors pharmaceutical manufacturing concentration, drawing insulin formulators and device developers to Leverkusen and Düsseldorf through tax-advantaged research zones and proximity to statutory health insurance decision centers.
Bavaria
Specialized diabetes centers around Munich and Erlangen drive demand for algorithm-assisted pump systems. The Bavarian State Ministry of Health funds integrated care pilots linking university hospitals with rural telemedicine networks. Nuremberg hosts device training facilities serving the southern statutory health insurance corridor.
Baden-Württemberg
Integrated care contracts in Stuttgart and Heidelberg bundle device procurement with outcome guarantees, compressing vendor selection cycles. The state's Ministry of Social Affairs mandates diabetes registry reporting that favors connected delivery systems with automated data transmission. Mannheim anchors a cluster of specialized pharmacies with device dispensing authority.
Lower Saxony
Hanover's university medical center validates closed-loop systems before broader G-BA reimbursement applications. The state's rural health ministry subsidizes home care device distribution to address access gaps in the Lüneburg Heath region. Wolfsburg's employer-funded diabetes programs generate concentrated demand for discreet wearable pumps.
Hamburg
Pediatric diabetes centers at University Medical Center Hamburg-Eppendorf pilot next-generation automated delivery for adolescent Type 1 populations. The city's Senate Chancellery for Health accelerates DiGA approval for local digital health developers. Altona's specialized diabetes clinics command disproportionate influence over northern statutory health insurance prescribing patterns.
Germany Insulin Drugs and Delivery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical-device portfolios commanding premium reimbursement tiers while component suppliers capture volume in mechanical delivery categories. The vendor base concentrates around three strategic archetypes: analog insulin originators with captive delivery ecosystems, pure-play device specialists with modular platform architectures, and digital health developers leveraging DiGA fast-track entry. Dominant competitive moves include algorithm licensing partnerships bridging pharmaceutical and technology competencies, and vertical integration into continuous glucose monitor data protocols to secure pump interoperability.
Among Swiss-based device specialists, Ypsomed exemplifies the rechargeable patch pump archetype with discreet form factors designed for patient-controlled basal-bolus regimens. Novo Nordisk and Sanofi occupy positions as integrated insulin originators with delivery ecosystem strategies spanning analog formulations to connected pen platforms. These three anchors represent distinct competitive vectors: modular hardware specialization, full-stack insulin-delivery integration, and long-acting formulation leadership with digital companion expansion.
| Leading Market Players |
|---|
| Novo Nordisk |
| Medtronic |
| Eli Lilly and Company |
| Sanofi |
| Ypsomed |
| Insulet Corporation |
| Roche |
| Abbott |
| Tandem Diabetes Care |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap device specialists in Baden-Württemberg and Bavaria anchor regional supply clusters, translating localized manufacturing control into pricing discipline that resists the margin erosion hitting multinational formulators exposed to G-BA reference pricing negotiations.
Pricing Analysis
Premium pricing attaches to devices with sub-48-hour fulfillment lead times, while spot inventory in secondary channels trades at 15-25% discounts. The dominant structure is a three-tier pricing framework across premium algorithm-assisted systems, standard connected pens, and economy mechanical syringes. Price differentiation rests on CE marking tier under EU MDR and bundled training service levels. Pricing pressure stems from biosimilar insulin negotiations compressing originator margins and forcing device subsidies. Statutory health insurance channels exhibit acute price sensitivity; private-pay segments tolerate premium positioning for discreet wearability.
Supply Chain Analysis
Reverse-logistics flows for insulin pump refurbishment and continuous glucose monitor sensor returns concentrate in Hamburg and Munich service hubs, extending asset life cycles and creating secondary supply pools. Active pharmaceutical ingredient production clusters in Denmark and the United States, while final device assembly concentrates in Germany, Switzerland, and Ireland. Raw material dependencies include recombinant insulin bulk, medical-grade plastics, and lithium-ion cells for rechargeable systems. Single-source vulnerability in Danish insulin bulk manufacturing exposes German formulators to supply interruption. Distribution runs through specialized diabetes centers rather than retail pharmacy for device procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm-driven insulin delivery is displacing legacy mechanical pen-and-syringe systems, with predictive low-glucose suspend functions and DiGA-classified companion apps now defining competitive viability.
For Market Incumbents: Cement algorithm licensing partnerships with continuous glucose monitor data protocol owners to secure pump interoperability against emerging modular competitors. Prioritize backward integration into sensor manufacturing to reduce third-party data dependency. Expand field clinical specialist teams in North Rhine-Westphalia to defend channel position as diabetes clinics consolidate procurement decisions. For New Entrants and Emerging Players: Rural home care patients in Bavaria represent an underserved buyer archetype with limited access to university hospital training infrastructure. Target disposable patch pump white space with discreet, rechargeable designs optimized for patient-controlled basal-bolus regimens. Pursue DiGA fast-track approval for carbohydrate counting app integration to capture reimbursement bandwidth before tethered pump saturation closes the window. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-hardware competency fusion targets in Berlin and Hamburg with embedded systems engineering depth for FDA/BfArM-aligned algorithm validation. Five-to-ten-year viability hinges on closed-loop system reimbursement expansion beyond pilot programs. Monitor G-BA coverage decisions for automated insulin delivery as the inflection signal determining category-scale timing.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | BfArM's accelerated pathway collapses 12-18 month approval gaps for algorithm-driven dose adjustment tools. |
| CGM Data Protocol Licensing | Securing interoperability with Abbott or Dexcom sensor feeds determines pump competitive positioning. |
| Specialized Diabetes Center Partnership | Integrated care contracts in Baden-Württemberg bundle device procurement with outcome guarantees. |
| Rechargeable Patch Pump Development | Compact wearable designs address patient preference for discreet basal-bolus delivery outside tethered systems. |
| Biosimilar Insulin Manufacturing Scale-Up | G-BA reference pricing dynamics favor cost-competitive analog production for statutory health insurance channels. |
Research Methodology
Multi-period observation of insulin pump reimbursement code expansions, DiGA directory entries, and G-BA coverage decisions anchored the trend analysis, supplemented by interviews with regulatory affairs leads at BfArM, formulary directors at statutory health insurance funds, hospital procurement managers in university diabetes centers, and biomedical engineers at device manufacturers. Secondary validation drew from BfArM DiGA registry filings, EMA centralized procedure documentation, EU MDR notified body guidance, and G-BA benefit assessment reports. Bottom-up patient population modeling and top-down pharmaceutical sales data triangulated market sizing.
Segment-weighting across insulin type, delivery method, diabetes application, and end-user channel structured the analytical framework throughout the forecast period. CAGRs were derived from patient cohort progression models, technology substitution curves for algorithm-assisted versus mechanical delivery, and reimbursement expansion scenarios for closed-loop systems. Forecast inputs included Type 1 diabetes incidence trajectories, intensive Type 2 insulin escalation rates, and DiGA adoption velocity in statutory health insurance channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to G-BA automated insulin delivery coverage decisions and EU MDR notified body capacity constraints. Practitioners should monitor BfArM DiGA approval velocity and G-BA pilot program expansions for early signals of category-scale timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
North America Monoclonal Antibody Market