
 Global Protein Purification and Isolation Market | 2026-2036
Global Protein Purification and Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Purification and Isolation Market Analysis
EU MDR is hardening the cost-of-entry calculus for protein purification consumables destined for in-vitro diagnostic workflows. Thermo Fisher Scientific leverages its chromatography resin manufacturing scale to serve high-throughput bioprocessing clients across North America and Europe. Danaher Corporation sustains competitive density through its Life Sciences segment's integrated filtration and separation platforms. Merck KGaA anchors its position with deep expertise in affinity chromatography ligand chemistry.
Protein purification and isolation encompasses the physical separation of target proteins from complex biological matrices using chromatographic, precipitation, or membrane-based methods, typically achieving purity thresholds of 95-99% for therapeutic-grade applications. The process serves as the critical downstream unit operation in recombinant protein manufacturing, enabling regulatory-compliant drug substance for fill-finish operations. Affinity chromatography commands the largest product type share due to its specificity for tagged recombinant proteins, while membrane filtration technologies gain traction in continuous bioprocessing architectures. Academic institutions represent a stable demand base for bench-scale purification kits, though pharmaceutical companies concentrate the highest value-per-unit spend on GMP-compliant systems.
FDA, EMA, and ISO 13485 collectively shape protein purification demand through divergent but converging purity verification requirements, with the FDA emphasizing process analytical technology and EMA stressing viral clearance validation for plasma-derived products. REACH compliance in Europe adds material qualification burdens for resin chemistries and single-use flow path components. Stakeholders must monitor how continuous manufacturing guidance from these regulators reshapes capital allocation between batch and integrated purification trains.
Market Dynamics
The transition from batch to continuous bioprocessing is compressing purification train footprints and forcing resin manufacturers to revalidate binding kinetics under flow-through conditions rather than static binding capacities.
Growth Catalysts
- FDA biosimilar guidance:The agency's tightened purity verification standards for interchangeable biologics compel manufacturers to upgrade chromatography resin specifications, driving replacement demand across existing installed bases.
- Monoclonal antibody pipelines:Biopharmaceutical developers scaling mAb manufacturing require affinity chromatography capacity expansion, particularly Protein A resin consumption for capture steps.
- Single-use flow paths:Pre-sterilized disposable chromatography systems reduce cross-contamination risk in multi-product facilities, accelerating adoption among contract manufacturing organizations.
Market Restraints
- Protein A resin supply concentration:Three manufacturers control affinity ligand production, creating vulnerability to force majeure disruptions or allocation decisions affecting downstream bioprocessing schedules.
- REACH compliance costs:ECHA's expanded substance of very high concern listings for acrylamide-based polymer chemistries force resin reformulation investments without performance guarantees.
- Membrane adsorber performance gaps:Current membrane technologies fail to match packed-bed resolution for certain post-translational modification separations, limiting substitution in high-value applications.
Strategic Opportunities
- India bioprocessing expansion:CDSCO's streamlined biosimilar approval pathways attract multinational investment in local purification capacity serving domestic and export markets.
- Cell and gene therapy vectors:AAV and lentiviral vector manufacturing requires novel affinity ligands and anion exchange chemistries distinct from mAb toolkits, opening specialized supplier positions.
- Continuous manufacturing incentives:FDA's quality-by-design framework rewards integrated purification trains with reduced inspection frequency, accelerating capital redeployment from batch infrastructure.
Industry Challenges
- Process analytical technology integration:Real-time protein titer and aggregate monitoring requires cross-functional expertise spanning chromatography engineering, spectroscopy, and data science that remains scarce in contract manufacturing hiring pools.
- Legacy system interoperability:Brownfield facilities running decade-old chromatography skids face control system incompatibility with modern distributed control architectures, complicating continuous processing retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Purification and Isolation Market |
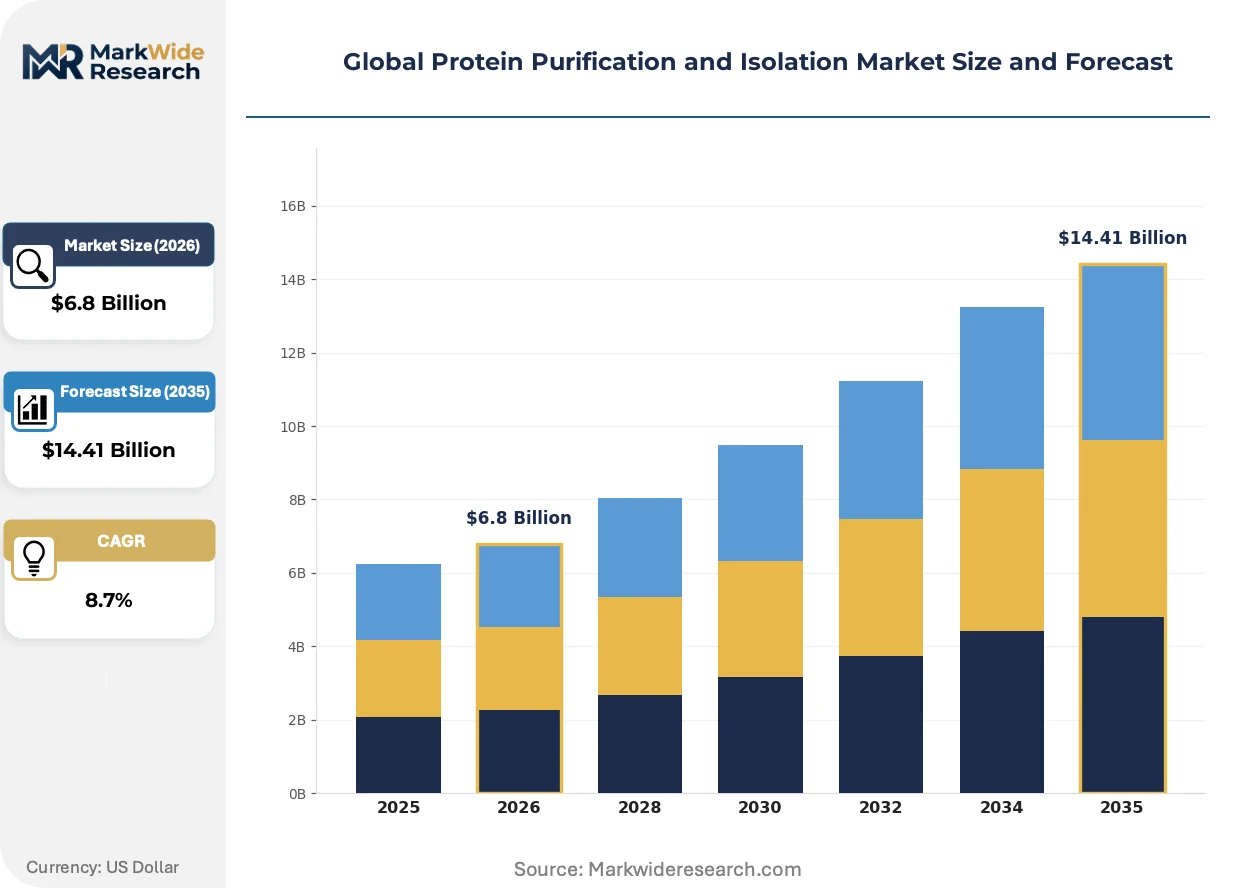
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Affinity Chromatography, Ion Exchange Chromatography, Gel Filtration Chromatography, Precipitation End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Laboratories Technology: High-Performance Liquid Chromatography, Ultrafiltration, Membrane Filtration, Magnetic Separation Application: Drug Development, Diagnostics, Vaccine Production, Nutraceuticals |
| Companies Covered | Bio-Rad Laboratories, Danaher Corporation, Thermo Fisher Scientific, Sartorius, Promega Corporation, Merck KGaA, Agilent Technologies, GE Healthcare, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Purification and Isolation Market Emerging Trajectories
Multimodal chromatography chemistries and automated buffer preparation systems are compressing downstream bottlenecks that previously limited overall bioprocess productivity. Equipment suppliers now compete on integration depth rather than standalone unit performance.
Multimodal res combining charge, hydrophobic, and hydrogen bonding interactions in single ligand architectures are unifying capture and intermediate purification steps previously requiring sequential column operations. Mid-sized biopharmaceutical developers are adopting these chemistries to reduce facility footprint and buffer consumption. This unification is compressing capital allocation toward integrated skid suppliers capable of delivering pre-validated purification trains rather than discrete column hardware.
EMA's revised viral clearance validation requirements for plasma-derived products mandate orthogonal demonstration across two distinct separation mechanisms, affecting validation protocols for albumin and immunoglobulin manufacturers. The regulation forces re-execution of legacy studies using nanofiltration combined with either anion exchange or solvent-detergent treatment. Plasma fractionators in Germany and Austria are responding by consolidating purification development under single vendor relationships to streamline documentation packages.
Biopharmaceutical procurement functions now specify total cost-of-ownership models incorporating resin lifetime cycling data rather than per-liter purchase price, disrupting traditional distributor relationships. Large-scale manufacturers in Massachusetts and North Carolina negotiate directly with resin chemists for customized ligand densities and particle size distributions. This specification-driven purchasing is most visible among CDMOs serving multiple sponsor molecules where resin interchangeability directly impacts campaign transition timelines.
Global Protein Purification and Isolation Market Segmentation
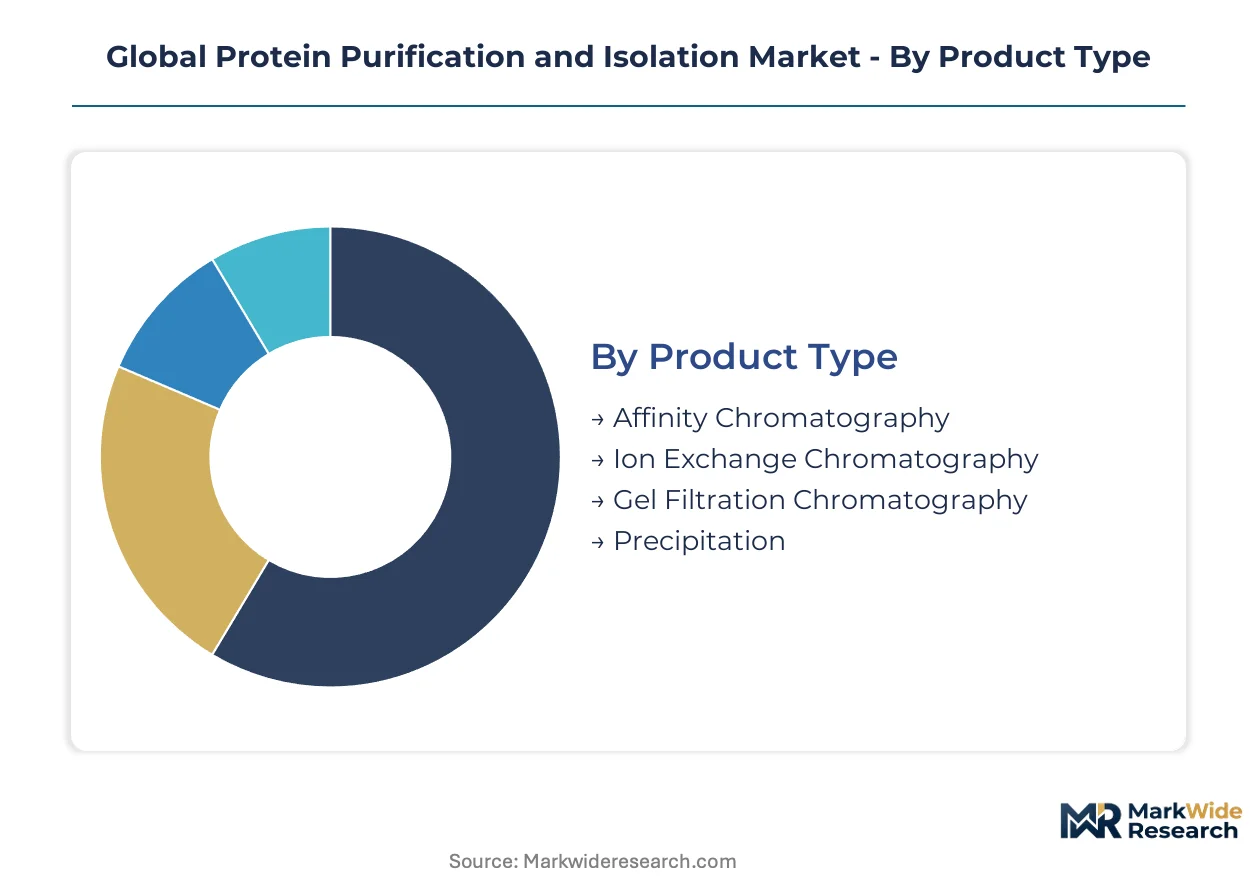
Segmentation in protein purification reveals how technical specifications, regulatory requirements, and scale economics split demand across incompatible equipment categories. Buyers face irreversible capital commitments when selecting between batch and continuous architectures.
Product Type:
Buyers in this category differentiate primarily by binding specificity requirements and resin lifetime economics under GMP cycling conditions.
- Affinity Chromatography:Protein A and other ligand-immobilized resins achieve selective capture of tagged recombinant proteins in a single step. Massachusetts and North Carolina biomanufacturing clusters drive concentrated demand as they scale monoclonal antibody capacity for FDA-regulated submissions.
- Ion Exchange Chromatography:Cation and anion exchange media separate proteins by surface charge distribution at varying pH conditions. German plasma fractionators anchor European demand following EMA's tightened viral clearance validation mandates for orthogonal separation mechanisms.
- Gel Filtration Chromatography:Size-exclusion matrices fractionate proteins by hydrodynamic radius without surface binding. Academic procurement in California and Massachusetts sustains steady bench-scale consumption.
- Precipitation:Salting-out and solvent-induced aggregation methods offer low-cost bulk fractionation for early-stage recovery. Contract manufacturers in India leverage these techniques for cost-sensitive biosimilar production under CDSCO oversight.
Affinity chromatography leads volumes today; precipitation is gaining share fastest in emerging manufacturing jurisdictions.
End User:
Scale requirements and regulatory exposure separate buyers, with GMP compliance obligations driving order-of-magnitude spending differences.
- Pharmaceutical Companies:Integrated biopharmaceutical manufacturers operate multi-ton protein production trains requiring validated chromatography skids. Swissmedic and FDA inspection schedules compel redundant purification capacity in Basel and Boston corridors.
- Biotechnology Firms:Venture-backed developers prioritize single-use flow paths to preserve facility flexibility across pipeline molecules. Cambridge and South San Francisco clusters concentrate early-phase demand for disposable chromatography systems.
- Academic Institutions:University core facilities run small-batch purification for basic research without regulatory filing obligations. NIH grant funding patterns shape purchasing cycles across United States research-intensive campuses.
- Research Laboratories:Government and private research institutes operate intermediate-scale protein production for reagent generation. CEA-supported facilities in France maintain distinct procurement specifications from pharmaceutical-grade buyers.
Pharmaceutical companies command the highest per-unit expenditure; biotechnology firms are expanding procurement most rapidly.
Technology:
Resolution requirements versus throughput imperatives determine technology selection, with continuous processing adoption reshaping competitive rankings.
- High-Performance Liquid Chromatography:Pressurized column systems deliver precise retention time control for analytical and preparative separations. Analytical method development groups in United States and Switzerland sustain replacement demand for UHPLC platforms.
- Ultrafiltration:Tangential flow filtration concentrates and diafilters protein solutions using molecular weight cut-off membranes. Process development teams in Denmark and Singapore deploy these systems for antibody formulation steps.
- Membrane Filtration:Adsorptive and size-based membrane chromatography enables flow-through processing with reduced buffer consumption. EMA's quality-by-design incentives accelerate adoption among German contract manufacturers.
- Magnetic Separation:Bead-based isolation leverages superparamagnetic particles for rapid batch processing without column packing. Cell therapy vector manufacturers in Maryland and Pennsylvania pioneer affinity-magnetic hybrid workflows.
High-performance liquid chromatography retains the largest installed base; membrane filtration is climbing the fastest in new facility construction.
Application:
Regulatory pathway complexity and product value per gram dictate purification investment intensity across therapeutic categories.
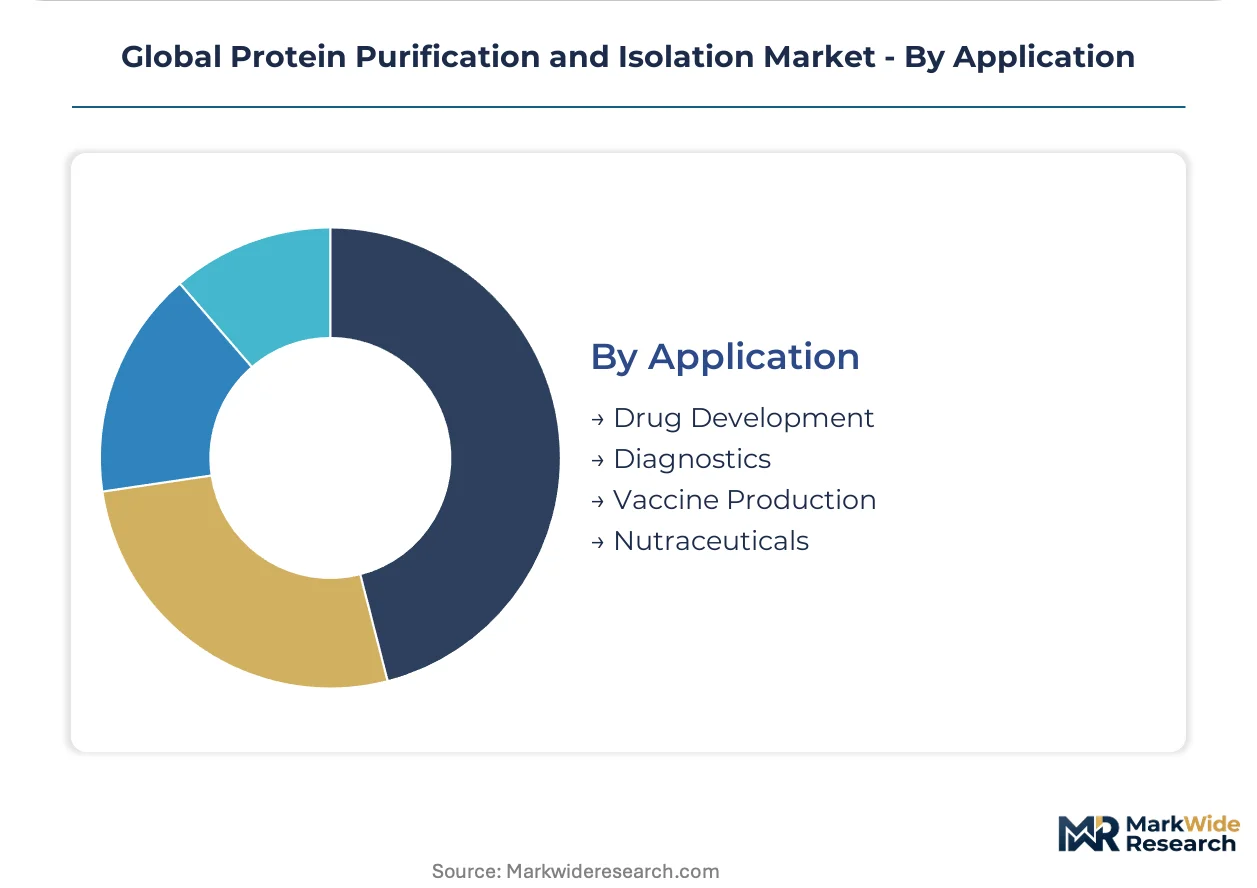
- Drug Development:Investigational new drug filings require documented purity profiles with validated analytical methods. FDA's biosimilar interchangeability standards intensify chromatography specification requirements for United States submissions.
- Diagnostics:In-vitro diagnostic manufacturers purify protein reagents under ISO 13485 quality systems. EU MDR's expanded technical documentation burdens reshape European consumables supply chains.
- Vaccine Production:Viral antigen purification demands orthogonal clearance strategies combining chromatography and filtration. Serum Institute of India and comparable facilities drive regional capacity expansion under CDSCO guidelines.
- Nutraceuticals:Functional protein isolates for dietary supplements operate under less stringent purity thresholds than pharmaceuticals. Chinese manufacturers serving domestic wellness markets prioritize cost-minimized precipitation approaches.
Drug development absorbs the greatest absolute spending; vaccine production is expanding most quickly in response to pandemic preparedness initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioprocessing talent concentrates in Massachusetts and North Carolina, where monoclonal antibody manufacturing expertise anchors North American demand. German plasma fractionation specialists and Swiss regulatory compliance professionals sustain European capacity. Indian contract development organizations now absorb expanding biologics purification workflows.
United States
FDA biosimilar interchangeability standards and monoclonal antibody pipeline expansion drive resin consumption. The agency's process analytical technology guidance compels real-time purity verification investments. Massachusetts and North Carolina biomanufacturing clusters host multi-ton Protein A capture capacity serving FDA-regulated submissions.
Germany
EMA viral clearance mandates for plasma-derived products reshape validation protocols across albumin and immunoglobulin production. REACH compliance burdens force acrylamide-based resin reformulation investments. Bavarian and Hesse plasma fractionators consolidate vendor relationships to streamline orthogonal separation documentation packages.
Switzerland
Swissmedic inspection schedules and biosimilar quality benchmarks sustain premium chromatography equipment demand. The country's central European logistics position serves multi-national biopharmaceutical distribution. Basel anchors integrated biomanufacturing corridors where redundant purification capacity addresses regulatory redundancy requirements.
India
CDSCO streamlined biosimilar pathways attract multinational investment in local GMP-grade purification capacity. Contract manufacturing organizations leverage cost-sensitive precipitation methods for domestic and export markets. Maharashtra and Telangana bioprocessing parks expand affinity chromatography resin consumption under emerging regulatory harmonization.
China
NMPA biologics approval acceleration and domestic monoclonal antibody pipeline growth expand chromatography system procurement. Yangtze River Delta biomanufacturing clusters invest in continuous processing architectures. Shanghai and Suzhou facilities now specify total cost-of-ownership models incorporating resin lifetime cycling data.
Global Protein Purification and Isolation Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across chromatography resin and system supply. The vendor base organizes around three strategic archetypes: integrated life sciences conglomerates with chromatography divisions, dedicated bioprocessing equipment specialists, and analytical instrumentation providers extending into preparative scale. Competitive moves concentrate on M&A for ligand chemistry capabilities and capacity expansion for Protein A resin manufacturing.
Among diversified life sciences conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions spanning filtration, separation, and analytical verification workflows. Merck KGaA exemplifies the specialized resin chemistry archetype through deep expertise in affinity ligand development. These three anchors collectively shape procurement specifications for GMP-compliant purification trains across North American and European biomanufacturing facilities.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Sartorius |
| Promega Corporation |
| Merck KGaA |
| Agilent Technologies |
| GE Healthcare |
| QIAGEN |
| Others |
Supply Flow & Price Mechanics
Acrylamide monomer price indices cascade through resin manufacturing into three-tier pricing structures across premium, standard, and economy levels. Biopharmaceutical procurement teams in Massachusetts and North Carolina negotiate resin specifications against REACH-driven reformulation costs that compress margins at the standard tier.
Pricing Analysis
Bundled purification train contracts dominate pharmaceutical procurement, while unbundled resin sales persist in academic and research laboratory segments. Price differentiation hinges on GMP certification grade and resin lifetime cycling performance under validated conditions. Cost compression in economy-tier precipitation reagents is intensifying because Indian contract manufacturers scale biosimilar production. Biotechnology firms demonstrate highest price sensitivity due to venture funding constraints, whereas integrated pharmaceutical companies prioritize total cost-of-ownership over per-unit resin pricing.
Supply Chain Analysis
Protein A ligand supply rests on three specialized manufacturers concentrated in the United States, Germany, and Sweden. Agarose bead matrices and synthetic polymer backbones draw from marine bioproduct harvesters and petrochemical feedstock suppliers respectively. Single-source vulnerability in affinity ligand production creates force majeure exposure for monoclonal antibody campaigns. Distribution runs through direct manufacturer relationships with large-scale biopharmaceutical facilities, supplemented by distributor networks serving mid-tier contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA biosimilar interchangeability standards harden purity verification requirements and sustain replacement demand across installed chromatography bases.
For Market Incumbents: Hedge against membrane adsorber substitution by deepening expertise in multimodal resin chemistries that unify capture and intermediate purification steps. Expand Protein A manufacturing capacity in Switzerland to address Swissmedic inspection redundancy requirements. Anchor vendor consolidation trends among German plasma fractionators by offering integrated documentation packages for orthogonal viral clearance validation. For New Entrants and Emerging Players: Contract manufacturing organizations represent the most penetrable channel partner type for novel affinity ligands targeting AAV and lentiviral vector production. White-space opportunities concentrate in India where CDSCO streamlined biosimilar pathways attract multinational investment in local GMP-grade capacity. Cell therapy vector manufacturers in Maryland and Pennsylvania offer entry points for magnetic separation hybrid workflows distinct from established mAb toolkits. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized resin chemistry firms possessing proprietary ligand development capabilities and validated manufacturing scale. Long-term viability through the next decade hinges on positioning for continuous bioprocessing architecture adoption rather than batch infrastructure replacement cycles. Watch FDA guidance on integrated purification train quality-by-design incentives as the inflection signal for capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Affinity Ligand Capacity Expansion | Addresses Protein A supply concentration vulnerability affecting Massachusetts and North Carolina biomanufacturing clusters. |
| Multimodal Resin Chemistry Development | Unifies capture and intermediate steps for mid-sized developers reducing facility footprint and buffer consumption. |
| Continuous Processing Skid Integration | Aligns with FDA quality-by-design incentives rewarding integrated trains with reduced inspection frequency. |
| Cell Therapy Vector Ligand Portfolio | Opens specialized supplier positions for AAV and lentiviral manufacturing distinct from monoclonal antibody toolkits. |
| REACH-Compliant Resin Reformulation | Mandatory acrylamide substitution investments protect European market access for German and Swiss manufacturers. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with downstream process development directors, regulatory affairs leads at plasma fractionators, resin procurement managers, and academic core facility directors informed demand-side dynamics. Secondary sources include FDA biosimilar guidance documents, EMA viral clearance validation protocols, REACH substance of very high concern listings, and CDSCO biologics approval pathway notifications. Bottom-up resin consumption modeling triangulated against top-down biopharmaceutical capacity expansion announcements.
Granularity-level modeling disaggregated revenue across product type, end user, technology, and application dimensions at the country level. The analytical framework incorporated purification train architecture choices between batch and continuous processing across the projection horizon. CAGRs derived from regression analysis against monoclonal antibody pipeline expansion rates and contract manufacturing organization capacity buildout schedules. Industry-specific inputs captured Protein A resin lifetime cycling data and multimodal chromatography adoption curves.
Revisions become necessary when regulatory guidance on continuous manufacturing validation materializes or when REACH expands substance restrictions affecting resin chemistries. Forecasts reflect assumptions regarding biosimilar approval pathway harmonization and bioprocessing talent availability in emerging manufacturing jurisdictions. A small set of named triggers—FDA quality-by-design incentive modifications, EMA viral clearance mandate updates, and Protein A ligand supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
GMO Testing Services Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market