
 Global Life Sciences Tools Market | 2026-2036
Global Life Sciences Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Life Sciences Tools Market Foresight
Aftermarket service revenue is rewriting profitability expectations for incumbent platforms. Thermo Fisher Scientific Inc. leverages its installed base of chromatography and mass spectrometry systems to capture recurring service contracts across pharmaceutical sites. Illumina, Inc. anchors its position through consumables pull tied to sequencing instrument placements. Danaher Corporation differentiates via operational excellence programs that tighten instrument uptime guarantees for diagnostic laboratories.
Life sciences tools encompass analytical and preparatory instrumentation engineered to resolution thresholds measured in picograms or single-base precision, deployed to characterize biological molecules, cellular structures, or environmental samples. Chromatography systems and mass spectrometry instruments command the largest share of capital expenditure budgets due to their centrality in quality control and metabolite identification workflows. Next Generation Sequencing platforms represent the fastest-expanding technology segment as clinical genomics pipelines scale from research into diagnostic reimbursement. Contract Research Organizations constitute a rapidly growing end user category as outsourced discovery models shift instrument ownership away from originator pharmaceutical manufacturers.
FDA 21 CFR Part 11, EU IVDR, and ISO 13485 collectively dictate electronic records integrity, in vitro diagnostic performance standards, and quality management system rigor for instrument suppliers seeking market access. These frameworks extend validation timelines but create structural advantages for vendors with established regulatory affairs infrastructure. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled diagnostic devices and the EU AI Act's risk classification rules reshape software-integrated tool requirements before committing to platform refresh cycles.
Market Dynamics
Biopharma R&D pipelines are pivoting from small molecules toward complex biologics and cell therapies, forcing analytical instrumentation vendors to recalibrate resolution specifications and throughput architectures for larger, more heterogeneous molecular targets.
Growth Catalysts
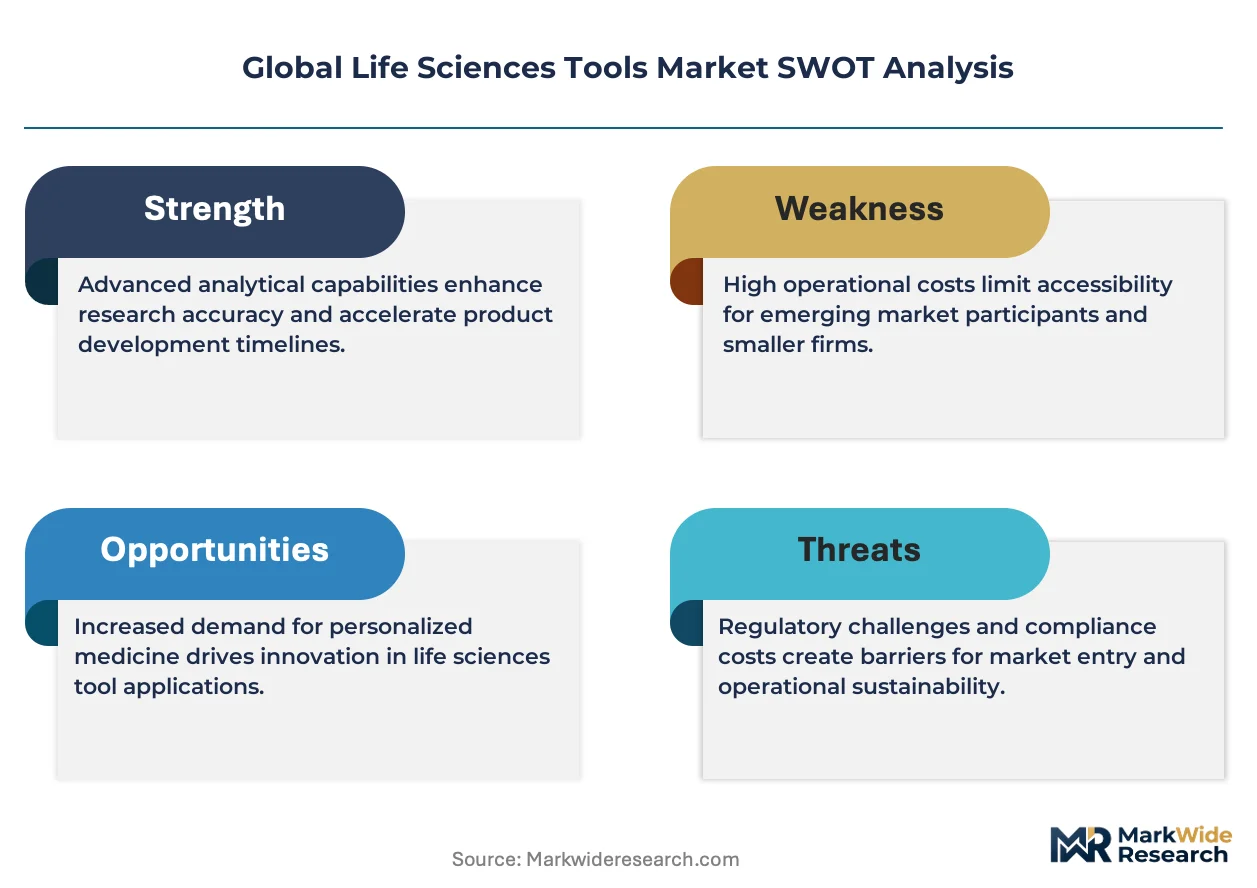
- EU IVDR framework:The In Vitro Diagnostic Regulation mandates enhanced clinical evidence for companion diagnostics, expanding demand for validated sequencing and mass spectrometry platforms across European clinical laboratories.
- Single-cell analysis workflows:Pharmaceutical manufacturers are integrating single-cell RNA sequencing into target validation pipelines, pulling instrument placements and consumable contracts from specialized vendors.
- China's precision medicine initiatives:National genomics programs and biobank construction in Beijing and Shanghai are concentrating capital expenditure for high-throughput sequencing systems.
Market Restraints
- Helium supply volatility:Mass spectrometry and NMR systems depend on helium for cryogenic cooling; sourcing disruptions from Qatar and Algeria inflate operating costs and extend procurement timelines.
- FDA 21 CFR Part 11 validation burden:Electronic records compliance for software-integrated instruments extends sales cycles by 6-18 months and elevates documentation costs for vendors without established quality infrastructure.
- Optical component concentration:Precision lasers and detectors for flow cytometry and microscopy concentrate among Japanese and German suppliers, exposing instrument OEMs to single-source fragility.
Strategic Opportunities
- India's biopharma manufacturing expansion:CDMO investments in Hyderabad and Bengaluru create demand for analytical QC instrumentation with localized service support and rupee-denominated pricing.
- Artificial intelligence-enabled device guidance:FDA's evolving framework for AI-integrated diagnostic tools creates first-mover advantages for vendors with pretrained algorithms and locked model architectures.
- Cloud-native instrument architectures:Browser-based control interfaces and remote diagnostics are hybridizing with traditional on-premise installations, enabling subscription revenue models for previously capital-only segments.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories and pharmaceutical sites struggle to recruit computational biologists capable of interpreting complex multi-omics datasets, creating bottlenecks in instrument utilization rates.
- Legacy system integration friction:Newer sequencing and chromatography platforms must interface with decades-old laboratory information management systems, requiring costly middleware development and validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Life Sciences Tools Market |
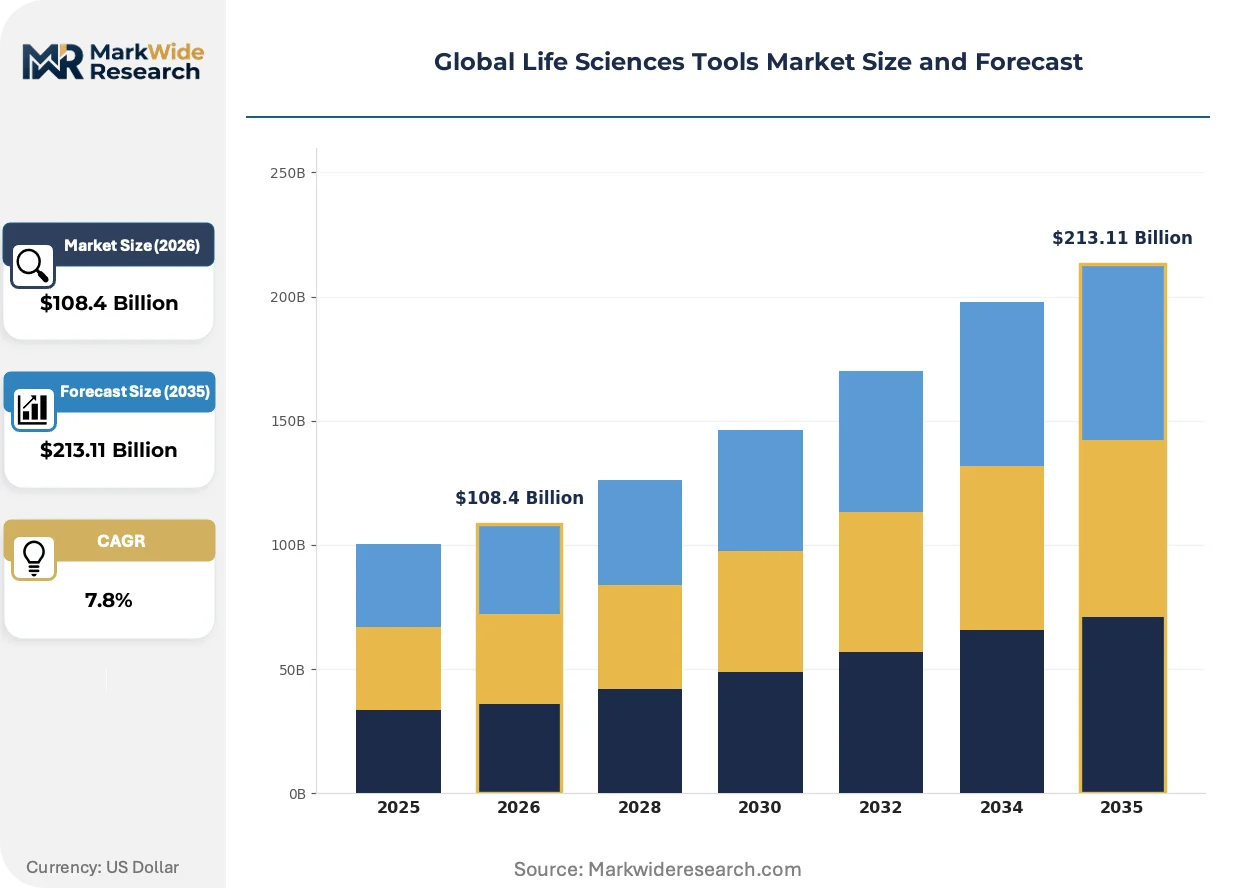
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $213.11 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Instruments, PCR Equipment, Microscopes, Centrifuges, Electrophoresis Apparatus Application: Genomic Analysis, Proteomics, Drug Discovery, Molecular Diagnostics, Cell Biology, Environmental Testing End User: Pharmaceutical Manufacturers, Research Institutes, Biotechnology Firms, Academic Laboratories, Diagnostic Centers, Contract Research Organizations Technology: Next Generation Sequencing, Mass Spectrometry, Fluorescence Imaging, Microfluidics, NMR Spectroscopy, Surface Plasmon Resonance |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina, Inc., Agilent Technologies, Inc., F. Hoffmann-La Roche Ltd., QIAGEN N.V., Danaher Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories, Inc., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Life Sciences Tools Market Shifts & Advancements
Instrumentation architectures are converging around modular, software-defined platforms that decouple hardware lifecycles from analytical capability upgrades, compressing replacement cycles while expanding vendor recurring revenue streams.
Mass spectrometry is hybridizing with automated sample preparation robotics to enable walk-up operation in pharmaceutical QC environments. Mid-sized biotechs with limited analytical chemistry staffing are adopting these integrated workflows to reduce method development timelines. The structural consequence is compression of specialist labor requirements while elevating instrument utilization metrics as primary competitive differentiators.
REACH authorization requirements for chemical substances used in reagent manufacturing are forcing reformulation of chromatography solvents and mass spectrometry matrices. European analytical laboratories face supply interruptions for legacy chemistries and must validate alternative formulations. Diagnostic instrument vendors with diversified chemical supply chains are capturing displaced demand from competitors dependent on restricted inputs.
Service contract unbundling is fragmenting traditional aftermarket revenue models. Large pharmaceutical procurement teams are negotiating à la carte maintenance, remote diagnostics, and spare parts sourcing rather than comprehensive coverage. This pattern concentrates among US and German sites with mature vendor management functions and internal metrology capabilities, pressuring incumbent service margins while creating openings for third-party ISO 17025-accredited calibration providers.
Global Life Sciences Tools Market Segmentation
Life sciences tools fragment across four intersecting dimensions that determine procurement priorities and vendor positioning. Product type and technology choices lock laboratories into decade-long capital commitments, while application and end-user segmentation dictates feature specifications and service intensity requirements.
Product Type:
Mature chromatography and microscopy platforms anchor installed bases across pharmaceutical quality control, while emerging microfluidic and advanced spectroscopy systems are capturing biologics process analytical technology budgets.
- Chromatography Systems:High-performance liquid chromatography and gas chromatography platforms separate complex biological mixtures with resolution thresholds measured in picograms. Pharmaceutical manufacturers in Germany and the United States deploy these systems for batch release testing, with helium supply volatility from Qatar and Algeria compressing gas chromatography utilization rates.
- Microscopes:Confocal and super-resolution fluorescence systems visualize cellular structures below the diffraction limit. Academic laboratories in Beijing and Shanghai are concentrating capital expenditure for lattice light-sheet architectures as China's precision medicine initiatives expand basic research infrastructure.
- Spectroscopy Instruments:UV-Vis and infrared systems quantify molecular concentration across drug formulation workflows.
- PCR Equipment:Thermal cyclers and real-time quantitative platforms amplify nucleic acid targets for diagnostic and research applications.
- Centrifuges:Ultracentrifugation and preparative systems separate cellular components by density gradient.
- Electrophoresis Apparatus:Gel and capillary systems separate proteins and nucleic acids by molecular weight and charge.
Chromatography Systems retain volume leadership; Microscopes hold the steepest expansion curve.
Application:
Cost tier segmentation separates high-value pharmaceutical discovery workflows from routine environmental compliance testing, with reimbursement-enabled molecular diagnostics commanding premium pricing.
- Drug Discovery:High-throughput screening and lead optimization workflows demand integrated liquid handling and detection platforms. Biotechnology firms in Boston and San Francisco are consolidating analytical instrumentation to accelerate biologics pipeline decisions, with single-cell analysis integration becoming a mandatory specification.
- Molecular Diagnostics:Clinical genomics and infectious disease testing platforms require FDA 21 CFR Part 11 compliance and EU IVDR technical documentation. Diagnostic centers across France and Germany are validating next-generation sequencing workflows for companion diagnostic reimbursement, expanding demand for locked-model software architectures.
- Genomic Analysis:DNA and RNA sequencing workflows support research and clinical applications.
- Proteomics:Mass spectrometry-based protein identification and quantification services.
- Cell Biology:Live-cell imaging and functional assays for therapeutic mechanism studies.
- Environmental Testing:Regulatory compliance monitoring for water, air, and soil matrices.
Drug Discovery commands the highest capital intensity per site; Molecular Diagnostics is gaining share fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical manufacturers negotiating enterprise service contracts while academic laboratories prioritize instrument flexibility over uptime guarantees.
- Pharmaceutical Manufacturers:Large-scale analytical chemistry and quality control departments operate validated instrumentation fleets under FDA and EMA inspection schedules. Sites in Basel and New Jersey are unbundling service contracts, negotiating à la carte maintenance rather than comprehensive coverage.
- Contract Research Organizations:Outsourced discovery models are shifting instrument ownership away from originator manufacturers. CDMO investments in Hyderabad and Bengaluru are creating demand for analytical QC instrumentation with localized service support and rupee-denominated pricing structures.
- Research Institutes:Government-funded basic science facilities with multi-instrument core facilities.
- Biotechnology Firms:Venture-backed development-stage companies with limited analytical chemistry staffing.
- Academic Laboratories:University departments with shared equipment access and grant-dependent procurement cycles.
- Diagnostic Centers:Clinical laboratories processing patient samples under reimbursement constraints.
Pharmaceutical Manufacturers retain volume leadership; Contract Research Organizations hold the steepest expansion curve.
Technology:
Supply concentration for precision optical components and rare gas dependencies fragment technology adoption timelines across geographies.
- Mass Spectrometry:Hybrid quadrupole-time-of-flight and orbitrap platforms identify metabolites and proteins with parts-per-billion sensitivity. Pharmaceutical QC environments in Switzerland and the United Kingdom are adopting automated sample preparation robotics to enable walk-up operation, compressing specialist labor requirements.
- Next Generation Sequencing:Illumina, Pacific Biosciences, and Oxford Nanopore platforms generate terabase-scale genomic datasets. Clinical genomics pipelines scaling from research into diagnostic reimbursement across China and the United States are pulling consumable contracts and instrument placements.
- Fluorescence Imaging:Confocal and light-sheet microscopy systems for cellular visualization.
- Microfluidics:Lab-on-chip systems for miniaturized biochemical reactions.
- NMR Spectroscopy:Nuclear magnetic resonance platforms for molecular structure elucidation.
- Surface Plasmon Resonance:Label-free binding kinetics measurement for drug-target interaction studies.
Mass Spectrometry retains volume leadership; Next Generation Sequencing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: pharmaceutical manufacturers in the United States and Germany prioritize compliance-validated platforms for biologics QC, while Chinese laboratories emphasize throughput scalability for population-scale genomics programs.
United States
FDA 21 CFR Part 11 mandates electronic records integrity for software-integrated instruments, extending sales cycles for vendors lacking established quality infrastructure. Boston and San Francisco biotechnology clusters are consolidating analytical instrumentation to accelerate biologics pipeline decisions. Pharmaceutical procurement teams in New Jersey are unbundling service contracts, negotiating à la carte maintenance rather than comprehensive coverage.
Germany
The EU IVDR framework mandates enhanced clinical evidence for companion diagnostics, expanding demand for validated sequencing platforms across clinical laboratories. EMA inspection schedules drive validated instrumentation fleet upgrades in Basel-adjacent pharmaceutical sites. Heidelberg and Munich precision medicine initiatives are concentrating capital expenditure for high-resolution microscopy systems.
China
National genomics programs and biobank construction in Beijing and Shanghai are pulling high-throughput sequencing instrument placements. NMPA regulatory pathways for innovative medical devices are compressing approval timelines for domestic sequencing platform vendors. Yangtze River Delta biopharma manufacturing investments are creating demand for analytical QC instrumentation with localized service support.
India
CDSCO regulatory harmonization with ICH guidelines is elevating documentation requirements for imported analytical platforms. CDMO investments in Hyderabad and Bengaluru are generating demand for chromatography and mass spectrometry systems with rupee-denominated pricing structures. The country's national pharmaceutical regulator is tightening GMP inspection protocols for analytical method validation.
Japan
PMDA quality management system requirements for in vitro diagnostics are extending validation timelines for sequencing platform vendors. Tokyo and Osaka pharmaceutical R&D sites are adopting automated sample preparation robotics to enable walk-up mass spectrometry operation. METI technology roadmaps for precision medicine are channeling public research funding toward single-cell analysis infrastructure.
Global Life Sciences Tools Market Competitive Landscape
Capability concentration sits with specialized optics and precision engineering firms; scale advantage sits with diversified conglomerates with global service networks. The vendor base organizes into three tiers: full-platform integrators with chromatography-to-sequencing portfolios; point-solution specialists dominating single technology verticals; and regional system integrators with localized compliance expertise. Dominant competitive moves include portfolio diversification through adjacent technology acquisitions and geographic expansion via in-country service infrastructure buildout.
Among diversified platform integrators, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the full-spectrum archetype spanning analytical instrumentation through diagnostic workflows. Illumina, Inc. occupies a specialized position within the sequencing vertical, anchoring consumables-pull business models tied to instrument placements. These three entities represent distinct competitive vectors: conglomerate scale, platform integration breadth, and technology-specific depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina, Inc. |
| Agilent Technologies, Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN N.V. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Helium supply volatility from Qatar and Algeria determines both the cost spread between gas chromatography and liquid chromatography platforms and the geographic relocation of mass spectrometry manufacturing capacity. Pharmaceutical procurement teams in New Jersey and Basel exploit this input-cost divergence to negotiate tiered instrument pricing based on cryogenic cooling requirements and regional service bundling.
Pricing Analysis
Long-term service contracts with embedded consumables offtake dominate capital equipment transactions, compressing upfront instrument margins while locking in decade-long recurring revenue streams. Price differentiation rests on FDA 21 CFR Part 11 validation tier and ISO 13485 certification depth, with diagnostic laboratories in Germany paying premiums for locked-model software architectures. Cost compression in mid-tier chromatography systems intensifies because CDMO procurement teams in India negotiate rupee-denominated pricing with localized calibration support. Academic laboratories exhibit highest price sensitivity; pharmaceutical manufacturers with enterprise fleet contracts show lowest.
Supply Chain Analysis
Extended payment terms from Japanese and German precision optics suppliers strain working capital for mass spectrometry and flow cytometry OEMs, forcing supply-chain finance facilities to bridge component procurement cycles. Manufacturing concentrates in Germany, Japan, and the United States for high-resolution detectors and precision lasers. Rare earth magnets for NMR systems and helium for cryogenic cooling anchor raw material dependencies. Single-source vulnerability for optical components exposes instrument builders to allocation risk during semiconductor fabrication cycles. Distribution runs through authorized dealer networks with certified field service engineers for validation-dependent installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The life sciences tools market operates as a regulatory-moat business where FDA and EU IVDR compliance infrastructure creates switching costs that entrench incumbent positions for validated platform vendors.
For Market Incumbents: Insulate installed base revenue by embedding cloud-native diagnostics and predictive maintenance algorithms that elevate switching costs for pharmaceutical QC laboratories. Backward integration into precision optics manufacturing reduces exposure to Japanese and German supplier concentration. Certification investment in locked-model AI architectures preempts FDA guidance on algorithm-enabled diagnostic devices. For New Entrants and Emerging Players: Pursue white-space opportunities in India's CDMO analytical QC segment where rupee-denominated pricing and localized service support displace premium-tier incumbents. Cloud-native instrument control platforms with subscription revenue models penetrate mid-sized biotechs in Boston and San Francisco lacking internal bioinformatics capacity. Go-to-market through ISO 17025-accredited third-party calibration partnerships bypasses entrenched service contract relationships. For Investors and Strategic Acquirers: Specialized microfluidics vendors with bioprocess analytical technology validation offer acquisition exposure to biologics manufacturing expansion. Long-term viability hinges on consumables-pull business models with instrument placement lock-in rather than capital-sales-dependent architectures. Watch FDA AI-enabled device guidance finalization as inflection signal for pretrained algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA 21 CFR Part 11 and EU IVDR validation compresses competitive field to established quality infrastructure vendors. |
| Cloud-Native Platform Migration | Browser-based control interfaces enable subscription revenue models and remote diagnostics for previously capital-only segments. |
| Consumables Supply Chain Integration | In-house production of chromatography solvents and sequencing reagents insulates against REACH authorization disruptions. |
| Localized Service Infrastructure Buildout | Rupee-denominated pricing and Hyderabad-based engineering teams capture India's CDMO analytical QC expansion. |
| AI-Enabled Device Pre-certification | Locked-model algorithm architectures secure first-mover positioning under FDA's evolving AI diagnostic guidance. |
Research Methodology
Desk research of FDA 510(k) filings, EU IVDR technical documentation, and ISO 13485 certification databases preceded structured interviews with regulatory affairs directors, pharmaceutical QC managers, diagnostic laboratory procurement heads, and chromatography field service engineers. Secondary validation drew from EMA inspection reports, NMPA medical device approvals, and SEC 10-K instrument revenue disclosures. Bottom-up instrument placement tracking across Beijing, Boston, and Basel clusters triangulated against top-down market sizing from consumables pull-through analysis.
The assumption set held helium supply volatility at observed Qatari and Algerian export patterns while varying biopharma R&D capital expenditure sensitivity to interest rate cycles across the projection horizon. Segmentation modeling spanned product type, application workflow, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from instrument replacement cycle compression and consumables attach rate expansion. Forecast inputs incorporated single-cell analysis adoption curves and CDMO outsourcing penetration by therapeutic modality.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform subsidies by emerging entrants would shift outcomes toward subscription-dominated revenue architectures. Macroeconomic deviation in biopharma M&A velocity, regulatory acceleration in AI diagnostic frameworks, or breakthrough displacement in sequencing chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Airlift Bioreactors Market