
 Global Western Blotting Market | 2026-2036
Global Western Blotting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Western Blotting Market Foresight
Modular reagent bundling is pivoting buyer choice away from standalone consumables toward integrated workflow packages. Thermo Fisher Scientific leverages its end-to-end platform portfolio to anchor large-account contracts across academic and pharmaceutical segments. Bio-Rad Laboratories competes through specialized electrophoresis and transfer systems that sustain loyalty among core protein research labs. Danaher differentiates via its Life Sciences segment, which controls distribution depth in clinical and biopharmaceutical quality-control channels.
Western blotting denotes a multi-step analytical technique separating proteins by gel electrophoresis, transferring them to nitrocellulose or PVDF membranes typically 0.2–0.45 μm in pore size, and detecting targets via antibody-mediated chemiluminescence or fluorescence for qualitative and semi-quantitative analysis. The method serves fundamental protein validation, biomarker confirmation, and regulatory-compliant biologics characterization. Detection reagents and imaging systems capture the deepest margin pools as laboratories trade up from film-based chemiluminescence to near-infrared and fluorescence platforms. Electrophoresis equipment remains structurally mature, with replacement cycles extending as precast gel formats reduce instrument utilization. Academic institutions and pharmaceutical companies represent the most concentrated demand endpoints, though biotechnology firms are expanding fastest as cell and gene therapy pipelines proliferate.
FDA guidance on bioanalytical method validation, EMA quality requirements for biologics characterization, and ISO 15189 standards for clinical laboratory competence collectively shape instrument specifications, reagent traceability demands, and vendor qualification protocols. REACH and RoHS frameworks in Europe constrain membrane and reagent chemistries, nudging suppliers toward reformulated blocking buffers and detection substrates. Stakeholders must monitor how evolving regulatory divergence between FDA and EMA analytical expectations reshapes R&D localization decisions and regional product registration strategies.
Market Dynamics
Automated imaging platforms are compressing detection workflows from hours to minutes, forcing reagent suppliers to bundle consumables with hardware subscriptions rather than sell standalone chemiluminescence kits.
Growth Catalysts
- FDA bioanalytical guidance:Updated validation requirements for biologics characterization are compelling pharmaceutical manufacturers to upgrade from film-based detection to quantitative fluorescence systems with full traceability.
- Cell therapy pipelines:Biotechnology firms expanding CAR-T and gene editing programs require western blotting for viral vector confirmation and protein expression validation at clinical scale.
- China:National research infrastructure investments under the 14th Five-Year Plan are funding proteomics facilities in Beijing, Shanghai, and Shenzhen with integrated western blotting workflows.
Market Restraints
- Antibody cost volatility:Polyclonal and monoclonal antibody prices fluctuate with serum supply constraints and bioreactor capacity, squeezing reagent margin pools for detection kit manufacturers.
- Precast gel standardization:Pre-formulated polyacrylamide gels reduce electrophoresis instrument utilization rates, extending replacement cycles and compressing capital equipment revenue.
- REACH chemical restrictions:ECHA constraints on acrylamide and methylene bisacrylamide chemistries force European suppliers to reformulate casting buffers and transfer membranes.
Strategic Opportunities
- India:CDSCO streamlining of biologics approval pathways is attracting contract research organizations to establish quality-control laboratories in Hyderabad and Bangalore.
- Near-infrared multiplexing:Li-COR and Azure Biosystems platforms enabling simultaneous four-target detection are opening high-throughput applications in biomarker screening panels.
- Cloud-connected imaging:Instrument vendors integrating AI-powered band analysis with laboratory information management systems are creating recurring software subscription revenue streams.
Industry Challenges
- Technician specialization gap:Automated systems reduce hands-on protocol steps but require expertise in imaging software calibration and quantitative normalization algorithms that core facility staff often lack.
- Legacy system integration:Academic laboratories with decade-old wet transfer tanks face capital allocation conflicts when vendors phase out compatible consumables for newer cassette formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Western Blotting Market |
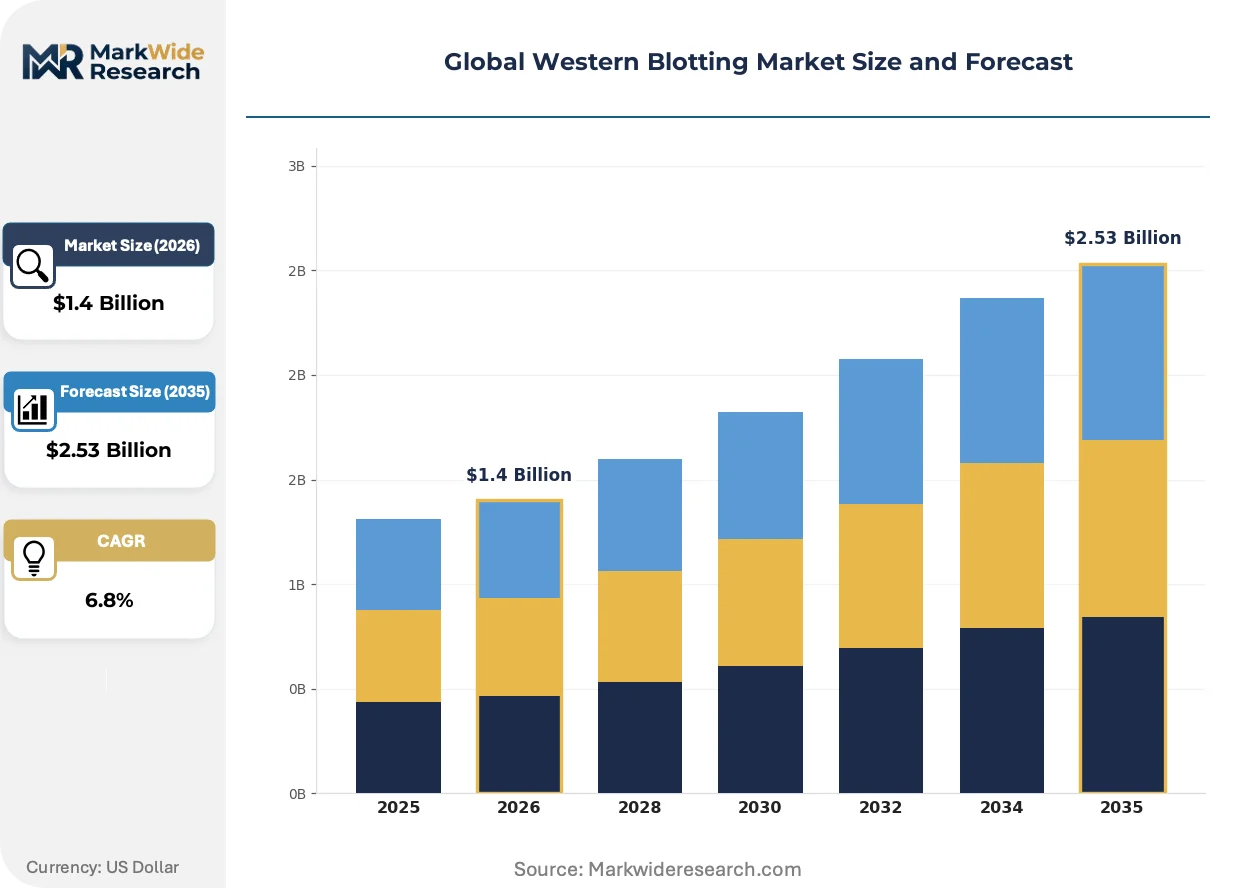
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Transfer Membranes, Detection Reagents, Electrophoresis Equipment, Blocking Buffers Technology: Chemiluminescence, Colorimetric, Fluorescence, Radioisotopic, Near-Infrared Application: Molecular Biology, Protein Research, Drug Discovery, Food Safety Testing, Forensic Analysis End User: Academic Institutions, Biotechnology Firms, Clinical Laboratories, Pharmaceutical Companies, Research Institutes |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, GE HealthCare, F. Hoffmann-La Roche Ltd, Lumigen, LI-COR Biosciences, Bio-Techne, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Western Blotting Market Shifts & Advancements
Detection chemistry is migrating from enzymatic substrates to direct fluorescence, while procurement contracts consolidate around workflow platforms rather than discrete consumable categories.
Capillary electrophoresis-based protein separation is absorbing share from traditional slab gel formats in pharmaceutical quality-control environments. Pfizer, Amgen, and Roche manufacturing sites have adopted automated capillary systems for lot-release testing of monoclonal antibodies. This technology is absorbing the high-volume, standardized assay segment that previously sustained precast gel and tank transfer hardware sales.
EMA quality requirements for biosimilar comparability studies now mandate orthogonal analytical methods including western blotting for post-translational modification profiling. European biopharmaceutical manufacturers must document antibody specificity and lot-to-lot consistency with enhanced traceability. CMOs in Germany and Switzerland are responding by qualifying multiple detection platforms to ensure regulatory redundancy.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships at major American research universities. The University of California system, Harvard, and MIT now negotiate enterprise licenses for reagent and instrument bundles spanning multiple core facilities. This concentration is most visible in Massachusetts and California, where shared services organizations centralize purchasing decisions across dozens of individual laboratories.
Global Western Blotting Market Segmentation
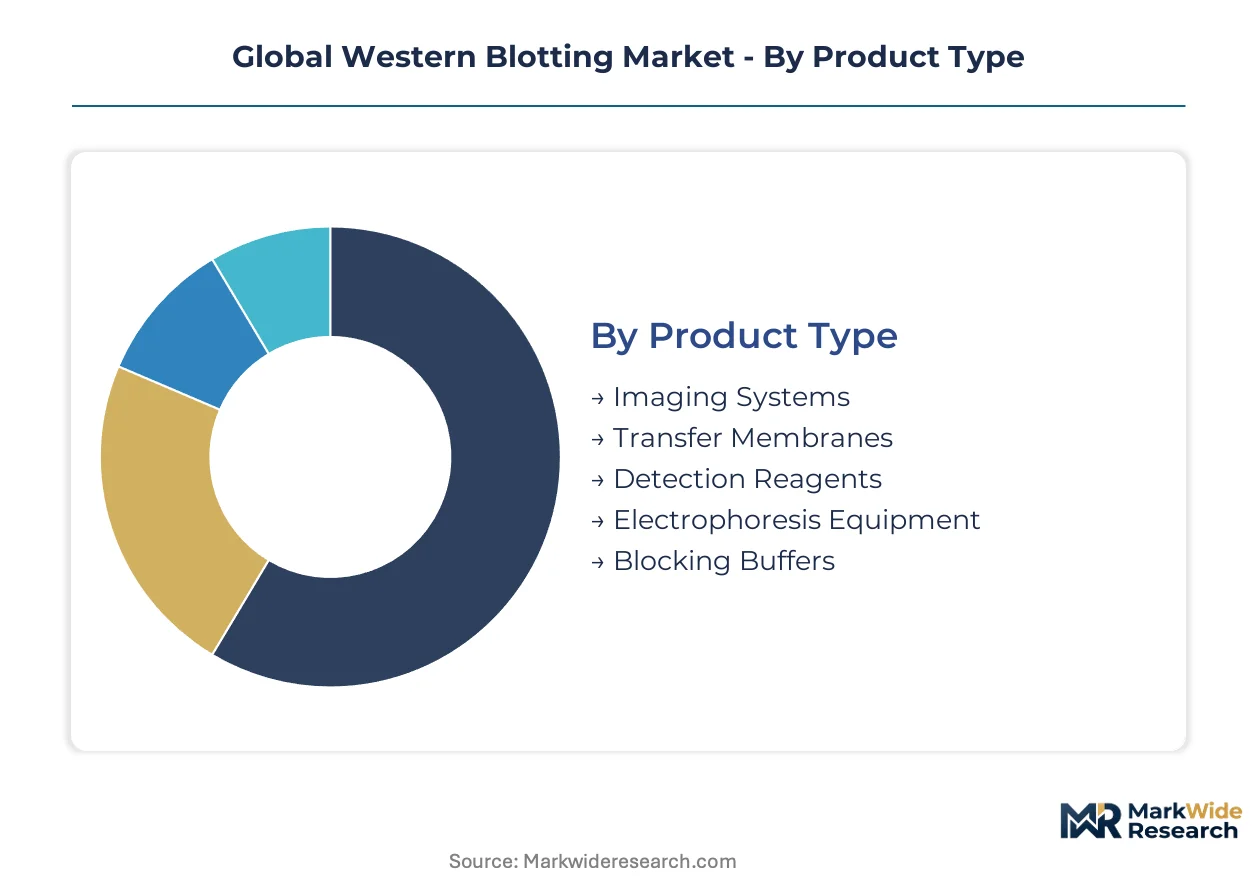
Western blotting workflows fragment across five product tiers, five detection modalities, five application domains, and five institutional buyer types. Each dimension carries distinct margin profiles and procurement rhythms that shape vendor positioning strategies.
Product Type:
Standalone instruments dominate capital budgets while consumables integrate into recurring revenue streams through bundled service contracts.
- Imaging Systems:CCD and CMOS-based detection platforms span chemiluminescence, fluorescence, and near-infrared modalities. Pharmaceutical quality-control labs in Germany and the United States are standardizing on quantitative fluorescence systems to satisfy FDA bioanalytical guidance.
- Transfer Membranes:Nitrocellulose and PVDF membranes in 0.2–0.45 μm pore sizes mediate protein immobilization efficiency. REACH constraints on acrylamide chemistries are forcing European suppliers toward reformulated PVDF formulations with enhanced binding capacity.
- Detection Reagents:Enzymatic substrates and fluorescent antibody conjugates generate recurring revenue through kit-based replenishment cycles.
- Electrophoresis Equipment:Tank-based and capillary separation systems face extended replacement cycles as precast gel formats reduce instrument utilization.
- Blocking Buffers:Protein-based and synthetic polymer formulations prevent non-specific antibody binding during target detection.
Detection reagents lead volumes today; imaging systems are gaining share fastest.
Technology:
Cost tiers stratify sharply, with enzymatic methods anchoring budget workflows and fluorescence platforms commanding premium positioning in regulated environments.
- Chemiluminescence:Horseradish peroxidase and alkaline phosphatase substrates remain the workhorse detection modality for routine protein validation. Academic core facilities in China under the 14th Five-Year Plan infrastructure investments continue procuring chemiluminescence systems for high-throughput screening.
- Fluorescence:Direct fluorophore labeling enables quantitative multiplexing with linear dynamic ranges exceeding chemiluminescence by orders of magnitude. EMA biosimilar comparability requirements are compelling CMOs in Switzerland to qualify fluorescence platforms for post-translational modification profiling.
- Near-Infrared:Li-COR and Azure Biosystems platforms enable four-target simultaneous detection with reduced background autofluorescence.
- Colorimetric:Chromogenic substrates provide visual endpoint detection without specialized imaging hardware.
- Radioisotopic:Iodine-125 and phosphorus-32 labeling persists in specialized research applications requiring absolute quantification sensitivity.
Chemiluminescence anchors installed base volumes; near-infrared platforms are climbing the fastest.
Application:
Maturity curves diverge: foundational research applications show replacement-cycle economics while regulatory-driven testing commands sustained investment.
- Protein Research:Fundamental validation of expression, localization, and post-translational modification underpins academic publishing output. Research institutes in Beijing and Shanghai are expanding automated western blotting capacity under national proteomics infrastructure programs.
- Drug Discovery:Target engagement confirmation and mechanism-of-action studies drive iterative assay development cycles. Biotechnology firms advancing CAR-T programs require western blotting for viral vector confirmation at clinical manufacturing scale.
- Molecular Biology:Gene expression validation and cloning confirmation sustain baseline demand in academic settings.
- Food Safety Testing:Allergen detection and GMO confirmation employ western blotting as orthogonal validation to PCR methods.
- Forensic Analysis:Protein-based identification supplements DNA evidence in degraded sample contexts.
Protein research leads application volumes; drug discovery is expanding most quickly.
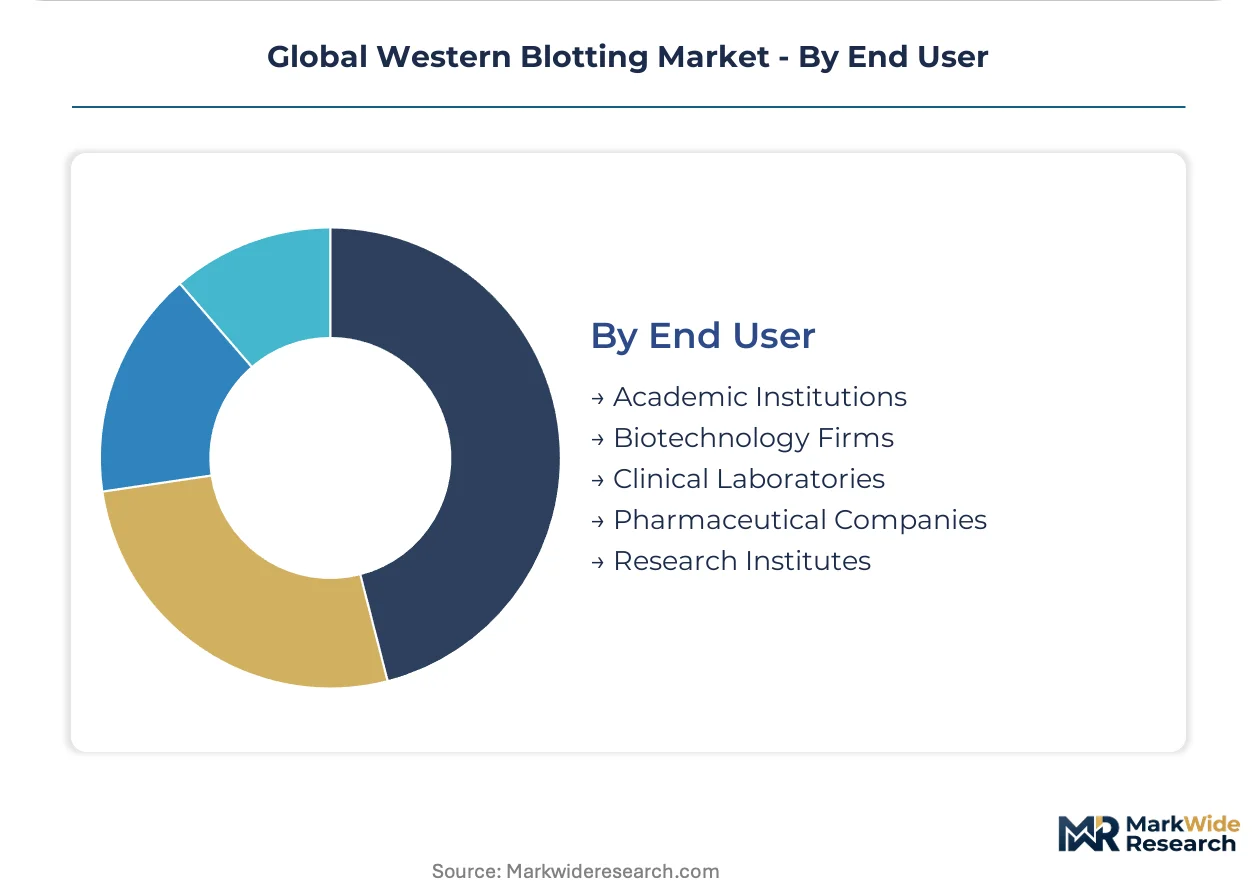
End User:
Procurement concentration varies by scale: enterprise licenses consolidate purchasing at major universities while biotechnology firms negotiate flexible terms aligned with pipeline milestones.
- Pharmaceutical Companies:Quality-control and lot-release testing demand full traceability with 21 CFR Part 11 compliant documentation. FDA updated guidance on bioanalytical method validation is forcing upgrades from film-based detection to quantitative fluorescence with audit trails.
- Biotechnology Firms:Cell and gene therapy developers require western blotting for viral vector titer confirmation and protein expression validation. CDSCO streamlining of biologics approvals is attracting CROs to establish QC laboratories in Hyderabad and Bangalore.
- Academic Institutions:Shared core facilities centralize purchasing decisions across individual laboratories through group purchasing organizations.
- Clinical Laboratories:ISO 15189 accreditation drives instrument specifications and reagent traceability requirements.
- Research Institutes:National laboratory systems operate on government funding cycles with multi-year capital planning horizons.
Academic institutions lead installed base volumes; biotechnology firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western blotting technology originated in academic laboratories at Stanford University during the late 1970s, establishing the United States as the foundational market before European and Asian research centers adopted and scaled protein immunodetection workflows.
United States
FDA bioanalytical guidance updates are compelling pharmaceutical manufacturers to upgrade detection platforms with full traceability documentation. The National Institutes of Health stabilizes research funding flows into proteomics core facilities. Massachusetts and California host the densest concentrations of biotechnology firms advancing cell therapy pipelines requiring viral vector confirmation.
Germany
EMA biosimilar comparability mandates drive contract manufacturing organizations toward orthogonal analytical method qualification. REACH chemical restrictions on acrylamide chemistries force reformulation of casting buffers and transfer membranes. Bavaria and Baden-Württemberg concentrate pharmaceutical quality-control laboratories serving European biologics production.
China
National research infrastructure investments under the 14th Five-Year Plan fund proteomics facility construction. NMPA alignment with international bioanalytical standards accelerates method validation platform adoption. Beijing, Shanghai, and Shenzhen municipal governments direct capital toward automated western blotting capacity in newly established precision medicine institutes.
Switzerland
Swissmedic quality requirements for biologics characterization sustain demand for high-sensitivity detection systems. The country's pharmaceutical manufacturing density supports specialized reagent consumption at commercial scale. Basel and Zurich anchor contract research operations performing lot-release testing for monoclonal antibody production.
India
CDSCO streamlining of biologics approval pathways attracts contract research organizations establishing quality-control operations. Government production-linked incentive schemes support domestic manufacturing of diagnostic reagents. Hyderabad and Bangalore emerge as clusters where multinational pharmaceutical firms localize analytical method validation for regional market access.
Global Western Blotting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detection technology tiers, with fluorescence and near-infrared platforms commanding price multiples over chemiluminescence workhorses. The vendor base stratifies into three layers: diversified life sciences conglomerates with end-to-end workflow portfolios, specialized electrophoresis and imaging equipment manufacturers, and regional reagent suppliers competing on consumable pricing. Consolidation pressures intensify as group purchasing organizations concentrate procurement decisions at major research universities. Dominant competitive moves include strategic partnerships bundling hardware with recurring reagent subscriptions, and technology licensing arrangements transferring detection chemistry intellectual property across geographic markets.
Among diversified platform providers, Thermo Fisher Scientific and Danaher occupy positions anchoring large-account contracts through integrated instrument-reagent-service bundles. Bio-Rad Laboratories exemplifies the specialized equipment archetype, sustaining loyalty among core protein research laboratories through dedicated electrophoresis and transfer system portfolios. These three entities represent distinct strategic postures: conglomerate scale, specialized depth, and hybrid positioning respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| GE HealthCare |
| F. Hoffmann-La Roche Ltd |
| Lumigen |
| LI-COR Biosciences |
| Bio-Techne |
| Danaher |
| Others |
Supply & Pricing Matrix
Group purchasing organizations at American research universities anchor procurement concentration, driving vendors toward subscription-based reagent bundles rather than standalone consumable sales. Pharmaceutical quality-control contracts in Germany and Switzerland command premium fluorescence platform pricing through regulatory-mandated traceability requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the western blotting market, with near-infrared and fluorescence systems commanding multiples over chemiluminescence workhorses due to FDA bioanalytical validation tiers and EMA biosimilar comparability mandates. Price differentiation rests on certification grade and after-sales service bundling, with 21 CFR Part 11 compliant documentation carrying substantial premiums. Pricing pressure stems from precast gel standardization extending instrument replacement cycles and compressing capital equipment margins. Academic core facilities in China exhibit highest price sensitivity, while Swiss CMOs demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Direct-to-laboratory channels handle pharmaceutical and biotechnology demand, while distribution runs through group purchasing organizations and specialized life sciences distributors for academic procurement. Manufacturing concentrates in the United States, Germany, and China, with PVDF membrane production drawing from petrochemical feedstocks and antibody conjugate synthesis resting on bioreactor capacity. Single-source vulnerability pervades high-affinity monoclonal antibody supply, where serum availability constraints and specialized hybridoma cell line dependence create bottlenecks for detection reagent manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in western blotting hinges on the shift from film-based chemiluminescence to quantitative fluorescence platforms, where regulatory-mandated traceability documentation enables sustained premium pricing against cost-compressed legacy detection methods.
For Market Incumbents: Lock in large-account contracts through integrated instrument-reagent-service bundles that embed recurring revenue streams and raise switching costs. Anchor enterprise licenses with University of California-scale systems and Harvard-MIT shared services organizations. Deepen backward integration into proprietary antibody production to insulate margin pools from serum supply volatility and bioreactor capacity constraints that squeeze detection kit manufacturers. For New Entrants and Emerging Players: CDSCO streamlining of biologics approval pathways in India opens a window for establishing quality-control laboratory operations in Hyderabad and Bangalore, where contract research organization demand for viral vector confirmation assays is accelerating. Target near-infrared multiplexing applications in biomarker screening panels, where Li-COR and Azure Biosystems have validated four-target detection workflows but reagent bundling opportunities remain underexploited. Pursue cloud-connected imaging integration with laboratory information management systems as a software subscription wedge. For Investors and Strategic Acquirers: Diversified life sciences conglomerates are the most active acquirer in this space, seeking specialized electrophoresis and imaging equipment manufacturers to fill workflow portfolio gaps. Long-term viability centers on regulatory tailwind sustainability, with FDA and EMA analytical method validation convergence supporting platform upgrade cycles across pharmaceutical quality-control environments. Monitor antibody cost volatility indices and bioreactor capacity utilization as inflection indicators for detection reagent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Workflow Platform Integration | Thermo Fisher Scientific anchors large-account contracts through end-to-end instrument-reagent bundles spanning chemiluminescence to near-infrared detection modalities. |
| Regulatory Compliance Certification | 21 CFR Part 11 documentation and EMA biosimilar comparability mandates force pharmaceutical manufacturers toward fluorescence systems with full audit trail capabilities. |
| Cloud-Connected Imaging Development | AI-powered band analysis integration with laboratory information management systems creates recurring software subscription revenue streams independent of hardware cycles. |
| Antibody Supply Backward Integration | Proprietary hybridoma cell line development insulates detection reagent manufacturers from serum supply constraints and bioreactor capacity bottlenecks. |
| Geographic Expansion to India | CDSCO regulatory streamlining attracts contract research organizations to Hyderabad and Bangalore for biologics quality-control localization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with proteomics core facility directors, pharmaceutical quality-control managers, regulatory affairs specialists at CMOs, and life sciences distribution channel partners with secondary validation from FDA bioanalytical guidance documents, EMA quality requirement filings, NMPA infrastructure investment disclosures, and SEC 10-K filings from diversified platform providers. Bottom-up instrument and reagent volume estimates triangulated against top-down market sizing from national research funding flows and proteomics facility construction announcements.
Segment-weighting approaches distributed value across product type, detection technology, application domain, and end-user institution tiers, with geographic allocation reflecting country-level research infrastructure investment cycles and regulatory framework convergence patterns. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics, pipeline-stage biotechnology firm expansion rates, and academic procurement consolidation trends. Forecast inputs included cell and gene therapy pipeline progression, automated imaging platform adoption trajectories, and antibody cost volatility indices.
Revisions become necessary when FDA-EMA regulatory divergence on analytical method validation materializes, when antibody supply disruptions exceed historical serum availability variance bands, or when capillary electrophoresis absorption of pharmaceutical quality-control workflows accelerates beyond modeled substitution rates. Periodic stress-testing of base assumptions against GPO contract renewal patterns and national research funding allocation shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Monoclonal Antibody Custom Service Market