
 Biologics CDMO Market | 2026-2036
Biologics CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Biologics CDMO Market Analysis
Buyer concentration among top-20 biopharmaceutical sponsors is consolidating as patent cliffs and pipeline pressures force smaller developers to merge or license assets to larger entities with established CDMO relationships. Lonza Group leverages its global multi-modal biologics network to sustain long-term commercial supply agreements. Samsung Biologics anchors massive mammalian cell culture capacity in South Korea. WuXi Biologics differentiates through integrated discovery-to-commercial platforms spanning China and Europe.
A biologics contract development and manufacturing organization provides outsourced services for the production of protein-based therapeutics derived from living cells, typically requiring aseptic processing in controlled environments with temperatures maintained between 2°C and 8°C for drug substance stability. The primary commercial purpose is to enable biopharmaceutical innovators to access specialized manufacturing expertise without capital-intensive facility construction. Monoclonal antibodies dominate current revenue pools due to established downstream purification protocols and higher per-batch values, while biosimilars represent the fastest-growing product category as originator patents expire across major markets. Cell line development commands premium pricing among service types because early-stage clonal selection directly determines yield consistency and regulatory acceptance.
FDA enforces current Good Manufacturing Practice through rigorous pre-approval inspections that determine whether foreign and domestic CDMO facilities can supply the US market, while EMA's centralized marketing authorization procedures create parallel compliance obligations for European commercialization. The EU AI Act and FDA's evolving guidance on computerized systems in manufacturing are reshaping how CDMOs validate process analytical technology and electronic batch records. Stakeholders must monitor whether regulatory divergence between Washington and Brussels forces redundant qualification studies or creates competitive advantage for operators with harmonized quality systems.
Market Dynamics
Patent expirations across blockbuster monoclonal antibody franchises are forcing originator biopharmaceutical companies to outsource manufacturing rather than absorb idle capacity, while simultaneously pulling biosimilar developers into CDMO partnerships that demand rapid scale-up capabilities.
Growth Catalysts
- EMA centralized marketing authorization:The procedure harmonizes quality standards across EU member states, enabling CDMOs to qualify once for commercial access across twenty-seven national markets.
- Cell and gene therapy pipelines:Viral vector manufacturing requires specialized aseptic suites that few innovators maintain in-house, driving contract demand for plasmid DNA and lentiviral production.
- South Korean biocluster expansion:Government-backed infrastructure investments near Seoul and Incheon have created contiguous supplier ecosystems that compress development timelines for mammalian cell culture programs.
Market Restraints
- Plasmid DNA supply concentration:Three specialized suppliers control majority access to GMP-grade starting material for gene therapy, creating single-source vulnerability for viral vector programs.
- FDA pre-approval inspection backlog:Foreign facility scheduling delays extend commercial launch timelines by six to eighteen months for CDMO-dependent sponsors.
- Stainless steel bioreactor obsolescence:Capital-intensive legacy assets face stranded value risk as single-use systems capture ninety percent of new capacity installations.
Strategic Opportunities
- India's emerging biologics corridor:CDSCO streamlined biosimilar approval pathways and PLI scheme production incentives are attracting fill-finish investments near Hyderabad and Bengaluru.
- Continuous bioprocessing convergence:Integration of perfusion cell culture with continuous chromatography promises order-of-magnitude facility footprint reduction for high-volume antibody programs.
- EU AI Act compliance services:Validated algorithmic process control and electronic batch record systems create premium service tiers for European commercial supply.
Industry Challenges
- Cell line development scientist scarcity:Clonal selection and stability testing expertise concentrates among professionals with ten-plus years of platform-specific experience, constraining early-stage service expansion.
- Multi-product facility changeover complexity:Campaign-to-campaign cleaning validation and viral clearance demonstration consume non-revenue-generating slot time in high-demand stainless steel suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologics CDMO Market |
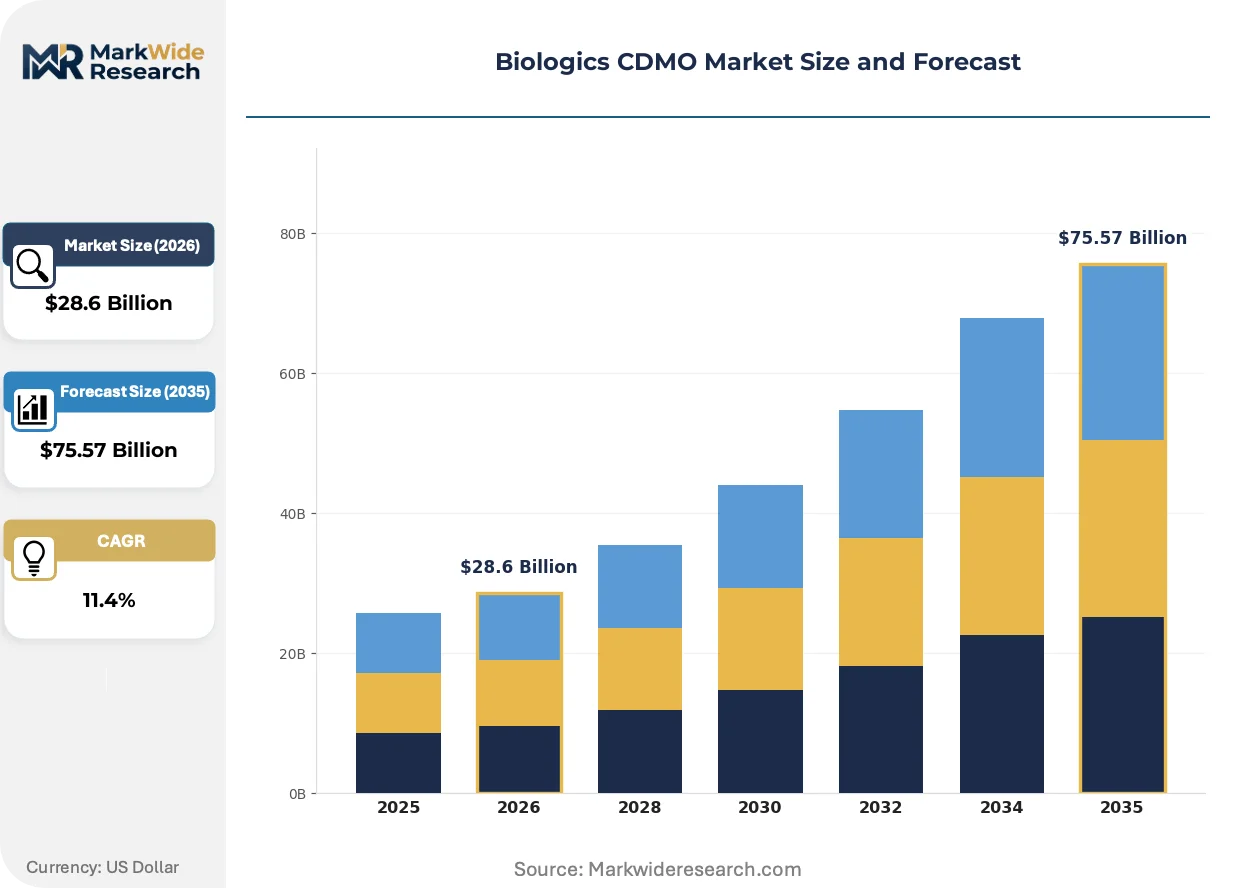
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cell Line Development, Process Development, Fill & Finish, Quality Control Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Biosimilars Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Topical End User: Biotechnology Firms, Pharmaceutical Companies, Research Institutions, Contract Research Organizations |
| Companies Covered | Lonza Group, Samsung Biologics, WuXi Biologics, Catalent, Boehringer Ingelheim, Fujifilm Diosynth Biotechnologies, Thermo Fisher Scientific, AGC Biologics, Rentschler Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologics CDMO Market Emerging Trajectories
Process analytical technology and artificial intelligence are converging to enable real-time release testing, compressing quality control timelines from weeks to hours while reducing in-process inventory holding costs across mammalian and microbial production platforms.
Single-use sensor arrays integrated with distributed control systems are automating glucose, lactate, and viable cell density monitoring in perfusion bioreactors. Mid-cap biopharmaceutical developers with limited process development groups are adopting these platforms fastest. The technology is automating manual sampling workflows that previously required dedicated analytical staff per production suite.
EU AI Act risk classification rules for manufacturing software are mandating documented algorithmic validation for process control systems used in European commercial supply. CDMOs must maintain technical files demonstrating human oversight and output traceability. Mammalian cell culture facilities with EU commercial ambitions are retrofitting legacy distributed control systems to meet these documentation burdens.
Biopharmaceutical procurement functions are consolidating supplier panels from fifteen-plus CDMO relationships to three-to-five strategic partnerships with integrated discovery-to-commercial capabilities. Large-cap sponsors now demand dedicated manufacturing capacity commitments and preferential slot access in exchange for pipeline exclusivity. This concentration is most visible among top-twenty biopharmaceutical companies headquartered in the United States and Switzerland.
Biologics CDMO Market Segmentation
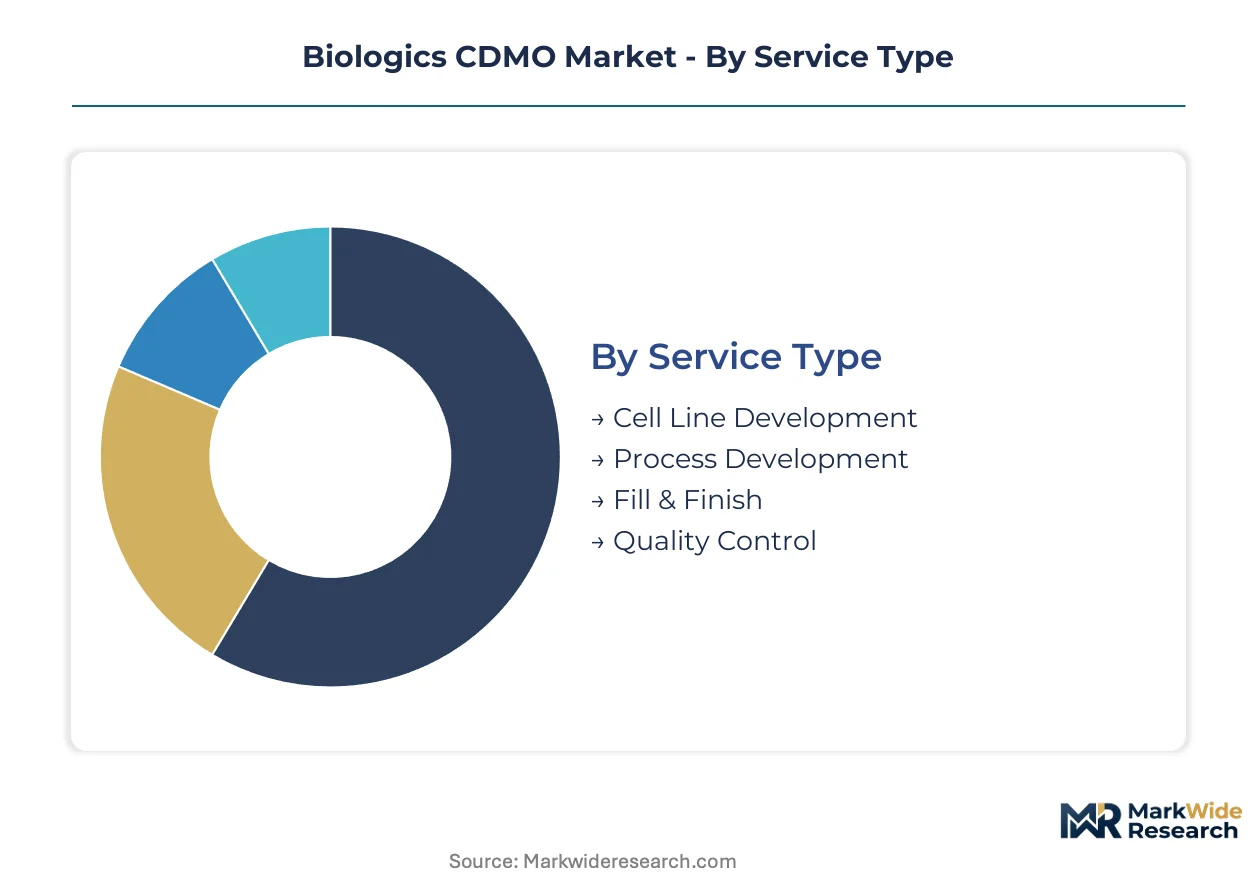
Segmentation in biologics CDMO services reveals divergent margin profiles and capacity allocation priorities across the value chain. Service mix determines whether providers capture early-stage premium pricing or lock in long-term commercial supply volumes.
Service Type:
Volume concentration sits with late-stage manufacturing, while premium pricing attaches to early technical services that determine regulatory success.
- Cell Line Development:Clonal selection and stability testing establish yield consistency for subsequent manufacturing campaigns. United States-based biotech sponsors concentrate demand here as FDA pre-approval inspections hinge on documented cell line provenance. The ten-plus-year experience threshold for platform scientists constrains supply expansion.
- Process Development:Scale-up optimization and technology transfer bridge discovery chemistry to GMP manufacturing. South Korean CDMOs capture accelerating demand as government-backed bioclusters compress mammalian cell culture timelines for export-oriented sponsors.
- Fill & Finish:Aseptic vialing and final packaging complete the sterile manufacturing chain.
- Quality Control:Release testing and stability studies ensure batch-to-batch consistency for regulatory filings.
Mature deployment sits with Fill & Finish. Newer deployment is concentrated in Cell Line Development as gene therapy pipelines multiply vector production needs.
Product Type:
Cost tier differentiation separates high-value originator molecules from price-competitive follow-on biologics with divergent CDMO partnership structures.
- Monoclonal Antibodies:Established downstream purification protocols and higher per-batch values sustain revenue concentration. Swiss and United States sponsors dominate demand as patent cliffs across blockbuster franchises force outsourcing rather than idle capacity absorption.
- Biosimilars:Cost-driven manufacturing requirements and compressed development timelines favor CDMOs with rapid scale-up capabilities. European commercialization through EMA centralized authorization pulls capacity investments toward EU-compliant facilities.
- Vaccines:Pandemic preparedness investments and seasonal production cycles create surge capacity requirements.
- Recombinant Proteins:Diverse therapeutic applications span enzyme replacement to cytokine therapies with variable batch economics.
Established revenue concentration centers on Monoclonal Antibodies. Steepest expansion trajectory belongs to Biosimilars as originator patents expire across major markets.
Delivery Mode:
Application context determines aseptic processing complexity and cold chain infrastructure requirements across administration routes.
- Intravenous:Infusion-center administration requires large-volume parenteral manufacturing with extended stability data. Hospital-centric distribution in the United States and Switzerland sustains demand for multi-thousand-liter bioreactor output.
- Subcutaneous:Prefilled syringe and autoinjector formats demand specialized fill-finish lines with reduced overfill tolerances. Patient self-administration trends in chronic disease management accelerate capacity conversion from vial to device-ready presentation.
- Intramuscular:Vaccine administration drives seasonal production peaks with dedicated multi-product suite requirements.
- Topical:Limited biologics applicability restricts CDMO investment in specialized semi-solid manufacturing infrastructure.
High-volume deployment concentrates in Intravenous. Patient convenience trends are reshaping investment toward Subcutaneous presentation formats.
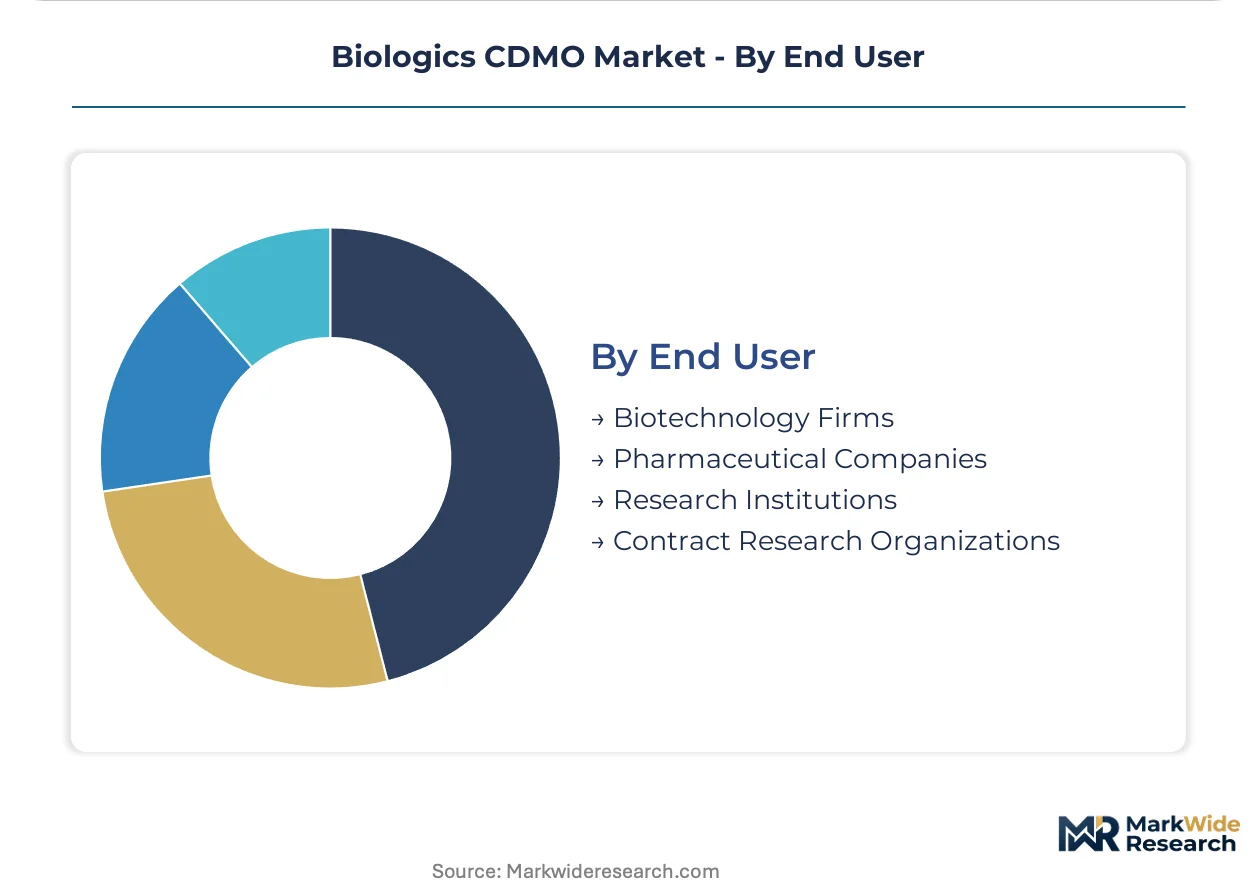
End User:
Customer type dictates contract structure, risk tolerance, and geographic proximity preferences in CDMO selection.
- Biotechnology Firms:Capital-constrained innovators outsource entire manufacturing functions from cell line development through commercial supply. United States coastal clusters—Boston, San Francisco, San Diego—generate concentrated demand for integrated discovery-to-commercial platforms.
- Pharmaceutical Companies:Large-cap sponsors consolidate supplier panels to three-to-five strategic partnerships with dedicated capacity commitments. Switzerland and United States headquarters dominate procurement functions demanding preferential slot access.
- Research Institutions:Academic and government laboratories require small-scale GMP batches for early-phase clinical investigation.
- Contract Research Organizations:CRO-CDMO alliance structures emerge as sponsors seek single accountability across development phases.
Long-term commercial volume anchors with Pharmaceutical Companies. Emerging pipeline growth concentrates among Biotechnology Firms advancing cell and gene therapy assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sponsors concentrate demand for integrated discovery-to-commercial platforms, while South Korean and Swiss facilities capture expanding commercial manufacturing volumes as FDA and EMA quality requirements tighten.
United States
FDA pre-approval inspections drive demand for documented cell line provenance and GMP compliance among Boston and San Francisco biotech clusters. The agency's rigorous foreign facility scheduling backlog extends commercial launch timelines for CDMO-dependent sponsors. Multi-thousand-liter single-use bioreactor capacity has expanded fastest near Research Triangle Park and Greater Boston.
Switzerland
Swissmedic oversight of commercial biologics supply creates premium positioning for facilities serving European and US markets simultaneously. Large-cap pharmaceutical procurement functions headquartered near Basel demand dedicated capacity commitments and preferential slot access. The country's biocluster concentration anchors long-term commercial supply agreements for monoclonal antibody programs.
South Korea
Government-backed infrastructure investments near Seoul and Incheon have created contiguous supplier ecosystems that compress development timelines for mammalian cell culture programs. MFDS alignment with FDA and EMA standards enables dual-approval pathway efficiency for export-oriented sponsors. Samsung Biologics anchors massive mammalian cell culture capacity serving global biopharmaceutical sponsors.
Germany
EMA centralized marketing authorization procedures create parallel compliance obligations that German facilities leverage for EU-wide commercial access. Boehringer Ingelheim maintains integrated biologics manufacturing networks serving European and international markets. The country's industrial concentration supports fill-finish investments for prefilled syringe and autoinjector presentation formats.
India
CDSCO streamlined biosimilar approval pathways and PLI scheme production incentives attract fill-finish investments near Hyderabad and Bengaluru. Cost-driven manufacturing requirements favor CDMOs with rapid scale-up capabilities for biosimilar developers. The emerging biologics corridor concentrates early-stage process development and analytical testing services.
Biologics CDMO Market Vendor Landscape
Swiss and United States producers anchor one tier; South Korean and Chinese specialists hold scale-driven positions in mammalian cell culture. The vendor base stratifies across integrated discovery-to-commercial platforms, dedicated commercial manufacturing networks, and viral vector specialists for cell and gene therapy. Three archetypes dominate: full-service integrators, capacity-heavy commercial manufacturers, and niche viral vector players. Competitive moves concentrate on multi-thousand-liter single-use capacity expansion and strategic partnerships that lock in dedicated manufacturing slots.
Within the full-service integrator tier, Lonza Group and WuXi Biologics exemplify geographic diversification strategies spanning multiple regulatory jurisdictions. Samsung Biologics occupies a position as a capacity-driven commercial manufacturer with government-backed infrastructure scale. These three entities represent divergent approaches to sponsor relationship structures—long-term commercial supply agreements, integrated platform access, and massive mammalian cell culture output.
| Leading Market Players |
|---|
| Lonza Group |
| Samsung Biologics |
| WuXi Biologics |
| Catalent |
| Boehringer Ingelheim |
| Fujifilm Diosynth Biotechnologies |
| Thermo Fisher Scientific |
| AGC Biologics |
| Rentschler Biopharma |
| Others |
Supply Flow & Price Mechanics
Top-twenty biopharmaceutical sponsors consolidating supplier panels to three-to-five strategic partnerships have compressed pricing power toward volume-commitment contract structures with preferential slot access clauses. Cell line development commands premium pricing due to ten-plus-year platform scientist scarcity, while fill-finish services face margin compression from single-use technology commoditization.
Pricing Analysis
Volume concentration in late-stage manufacturing competes against premium pricing in early-stage cell line development and process optimization services. Three-tier pricing structure across integrated discovery-to-commercial platforms, dedicated commercial manufacturing networks, and niche viral vector specialists separates full-service premiums from capacity-heavy mid-market rates. Cost compression in biosimilar manufacturing is intensifying because rapid scale-up capabilities have become table stakes for EMA centralized authorization pathways. Emerging biotechnology firms with capital constraints exhibit highest price sensitivity, while large-cap pharmaceutical sponsors prioritize dedicated capacity commitments over unit cost minimization.
Supply Chain Analysis
Workforce availability constraints in South Korea, Switzerland, and the United States have elevated compensation costs for platform-specific cell line development scientists with decade-plus experience trajectories. GMP-grade plasmid DNA supply draws from three specialized suppliers concentrated in North America and Europe, creating single-source vulnerability for viral vector programs. Tariff exposure on single-use bioreactor components sourced from Asian manufacturing hubs threatens cost structures for capacity expansion projects. Distribution runs through sponsor-directed logistics networks with cold chain integrity requirements from manufacturing site to clinical depot.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a consolidation play where FDA pre-approval inspection backlogs and stranded stainless steel asset values are forcing sub-scale operators toward acquisition or exit.
For Market Incumbents: Anchor long-term commercial supply agreements through dedicated multi-thousand-liter single-use capacity commitments that lock in preferential slot access. Samsung Biologics and Lonza Group exemplify defensive positioning through government-backed infrastructure scale and global multi-modal network density. Cell and gene therapy viral vector manufacturing represents the priority capacity addition geography as specialized aseptic suite scarcity intensifies. For New Entrants and Emerging Players: Digital-channel partnership routes with contract research organizations offer white-space entry points for integrated discovery-to-commercial platform positioning. India's emerging biologics corridor near Hyderabad and Bengaluru presents the most penetrable geography given CDSCO streamlined biosimilar pathways and PLI scheme production incentives. Continuous bioprocessing convergence capabilities serve as the differentiated go-to-market angle for high-volume antibody program capture. For Investors and Strategic Acquirers: The window for entry favors cell line development specialists with documented clonal selection expertise and established FDA pre-approval inspection track records. Long-term viability over the coming decade hinges on regulatory validation depth rather than capacity scale alone. The signal to watch is EMA centralized marketing authorization approval velocity as proxy for quality system harmonization premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-thousand-liter Single-use Capacity Expansion | FDA pre-approval inspection readiness determines US market access eligibility for CDMO-dependent sponsors. |
| Cell and Gene Therapy Viral Vector Suite Investment | Specialized aseptic manufacturing scarcity commands premium pricing from biotechnology innovators outsourcing vector production. |
| Continuous Bioprocessing Technology Integration | Perfusion cell culture with continuous chromatography reduces facility footprint for high-volume antibody manufacturing programs. |
| EU AI Act Compliance Service Development | Validated algorithmic process control creates premium service tiers for European commercial supply contracts. |
| Strategic Partnership with Top-twenty Biopharmaceutical Sponsors | Dedicated capacity commitments and preferential slot access secure long-term commercial volume pipelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews with drug development executives, regulatory affairs leads, manufacturing operations directors, and biopharmaceutical procurement managers. FDA 483 observation databases, EMA inspection reports, MFDS facility registration records, and clinical trial manufacturing agreements provided validation points. Bottom-up capacity installation tracking and top-down sponsor outsourcing spend analysis enabled triangulation across independent data streams.
Data-stream reconciliation across service type, product category, delivery mode, and end user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from capacity utilization trajectories and sponsor pipeline progression rates rather than extrapolation of historical growth patterns. Single-use bioreactor installation databases, patent expiration calendars for blockbuster monoclonal antibodies, and viral vector manufacturing suite construction permits served as industry-specific forecast inputs.
The model holds under stable regulatory inspection scheduling and continued biopharmaceutical outsourcing trend acceleration; deviation in FDA foreign facility backlog resolution or plasmid DNA supply disruption would shift capacity absorption timelines. Forecasts reflect assumptions regarding sponsor consolidation behavior and cell line development scientist availability constraints. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
GMO Testing Services Market