
 Dnases, Ligases, and RNA Polymerases Market | 2026-2036
Dnases, Ligases, and RNA Polymerases Market Size, Share, and Industry Trends Forecast 2026-2036
Dnases, Ligases, and RNA Polymerases Market Intelligence
North American biologics manufacturers is shifting capacity toward mRNA and cell therapy platforms, tightening supply chains for GMP-grade enzymes. Thermo Fisher Scientific leverages its Fisher Scientific distribution arm to control channel access for research-grade ligases across academic accounts. New England Biolabs anchors its position through specialized enzyme engineering for CRISPR applications. Merck KGaA/Sigma Aldrich competes on backward integration into fermentation capacity for industrial-scale RNA polymerase output.
Dnases, ligases, and RNA polymerases comprise recombinant enzymes that catalyze nucleic acid cleavage, ligation, and transcription respectively, typically produced through bacterial or yeast expression systems with purity grades spanning research-use to GMP-compliant specifications. Their primary commercial purpose is to enable nucleic acid manipulation across drug discovery, diagnostic assay development, and therapeutic manufacturing workflows. RNA polymerases command premium positioning within the product type dimension due to mRNA vaccine and gene therapy manufacturing pull, while CRISPR within the technology dimension is displacing legacy PCR workflows for complex genome engineering. Pharmaceutical companies within the end user dimension represent the fastest-expanding margin pool as therapeutic developers in-source enzyme qualification rather than rely on catalog suppliers.
FDA oversight of gene therapy starting materials and EMA's ATMP guidelines are elevating documentation and traceability requirements for enzyme suppliers seeking therapeutic manufacturing contracts. ISO 13485 and GMP standards are forcing research-grade producers to either upgrade quality systems or exit clinical-adjacent segments. Stakeholders must monitor how regulatory divergence between FDA lot-release expectations and EMA centralized assessment timelines reshapes supplier qualification strategies for dual-territory therapeutic developers.
Market Dynamics
mRNA vaccine manufacturing is concentrating purchasing power among a handful of biologics producers, forcing enzyme suppliers to retool capacity toward GMP-grade specifications and audit-ready documentation systems.
Growth Catalysts
- EMA ATMP Guidelines:Europe's advanced therapy medicinal products framework is accelerating qualification timelines for RNA polymerases used in cell therapy manufacturing, pulling suppliers into clinical-grade production.
- CRISPR Workflows:Pharmaceutical pipelines are embedding CRISPR-based editing into discovery and manufacturing stages, expanding demand for precision nucleases and specialized ligase variants.
- United States:mRNA vaccine producers and gene therapy developers in Boston and San Diego are anchoring bulk purchasing of high-specificity enzymes, tightening regional supply chains.
Market Restraints
- Fermentation Input Volatility:Recombinant enzyme production depends on consistent glucose and yeast extract supply, with price swings in agricultural commodities compressing margin predictability for bacterial expression systems.
- Single-Source Concentration:GMP-grade RNA polymerase supply concentrates among three primary fermentation facilities, creating vulnerability to contamination events or capacity constraints.
- Regulatory Friction:Divergent FDA lot-release documentation requirements versus EMA centralized assessment timelines force dual-territory developers to maintain parallel qualification dossiers.
Strategic Opportunities
- Japan:METI's biomanufacturing infrastructure investments are opening procurement channels for foreign enzyme suppliers serving domestic cell therapy developers.
- Continuous Bioprocessing:Real-time enzyme monitoring and inline quality verification are converging with mRNA manufacturing platforms, enabling subscription-based supply contracts.
- Direct-to-Biotech Distribution:Specialized enzyme suppliers are bypassing traditional distributor markups by establishing dedicated sales teams for Series B and C therapeutic developers.
Industry Challenges
- GMP Certification Timelines:ISO 13485 and FDA drug master file preparation requires 18-24 month investment cycles, straining cash reserves for mid-tier enzyme engineering firms.
- Skill Scarcity:Qualified fermentation scientists capable of scaling recombinant enzyme production from bench to industrial bioreactors command premium compensation, constraining workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dnases, Ligases, and RNA Polymerases Market |
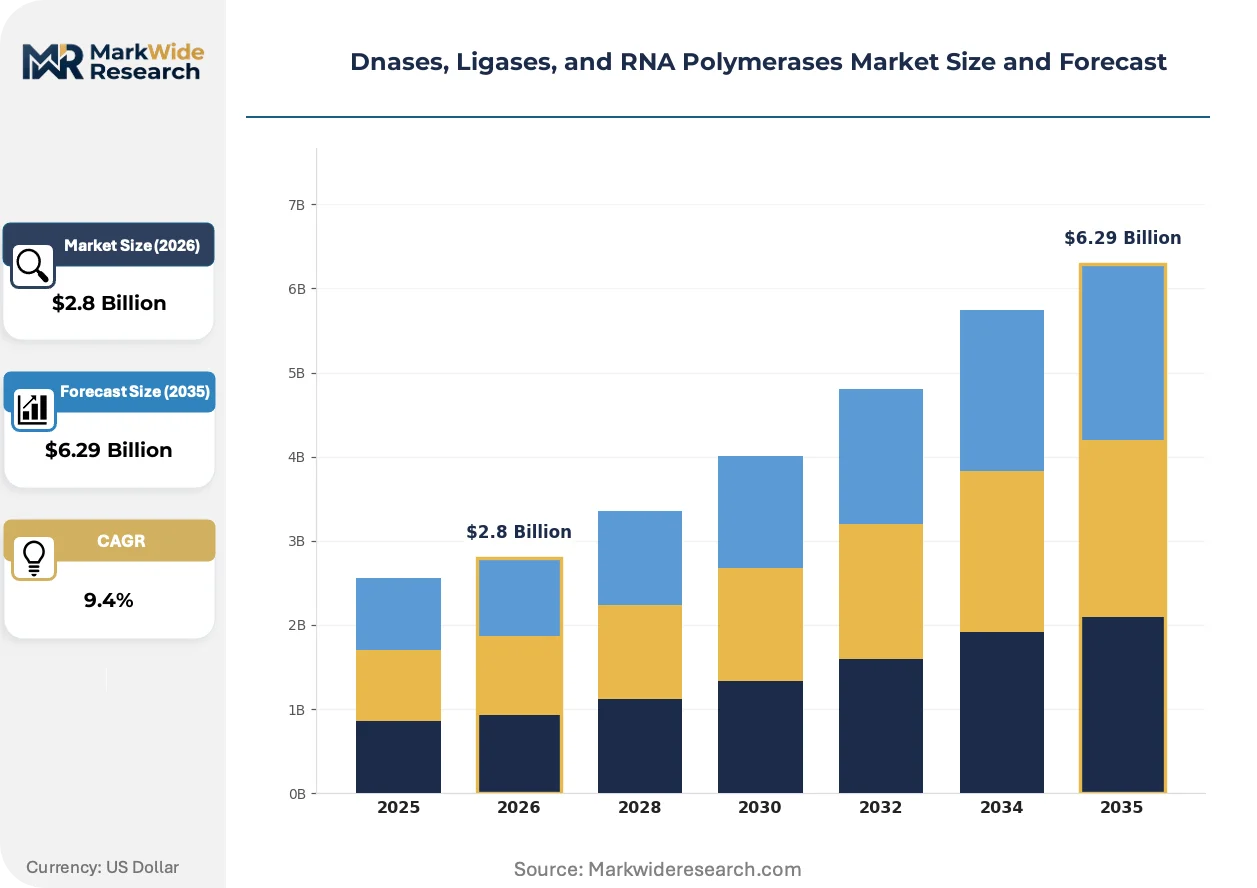
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dnases, Ligases, RNA Polymerases, Reverse Transcriptases Application: Molecular Cloning, Gene Expression, DNA Repair, Sequencing End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Research Labs Technology: Enzymatic Reactions, PCR, CRISPR, Gene Editing |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA/Sigma Aldrich, New England Biolabs, Takara Bio, Promega Corporation, Agilent Technologies, QIAGEN, Calzyme, RayBiotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dnases, Ligases, and RNA Polymerases Market Strategic Shifts & Innovations
Enzyme engineering and manufacturing workflows are fragmenting along therapeutic-grade versus research-grade fault lines, with distinct technology stacks and qualification protocols emerging for each tier.
Synthetic biology toolkits for enzyme optimization are decentralizing access to high-performance variants previously locked behind proprietary strain libraries. Mid-sized biotechs in Cambridge and Research Triangle Park are adopting cloud-based protein design platforms at accelerating pace. This capability diffusion is compressing the historical R&D advantage of incumbent suppliers with decades of strain development.
FDA's enhanced oversight of gene therapy starting materials is elevating documentation burdens for enzyme suppliers seeking therapeutic manufacturing contracts. Suppliers must now maintain electronic batch records and chain-of-custody systems that satisfy both agency inspectors and sponsor quality audits. GMP-grade RNA polymerase producers are responding by segregating research and clinical production facilities to prevent cross-contamination risks.
Consolidated purchasing by mRNA vaccine manufacturers is compressing supplier negotiation leverage and accelerating long-term contract structures. Catalog distributors serving academic accounts are losing share to direct manufacturer relationships as biotech procurement teams centralize enzyme sourcing. This channel compression is most visible in Massachusetts and California, where therapeutic developers maintain dedicated supplier qualification staff.
Dnases, Ligases, and RNA Polymerases Market Segmentation
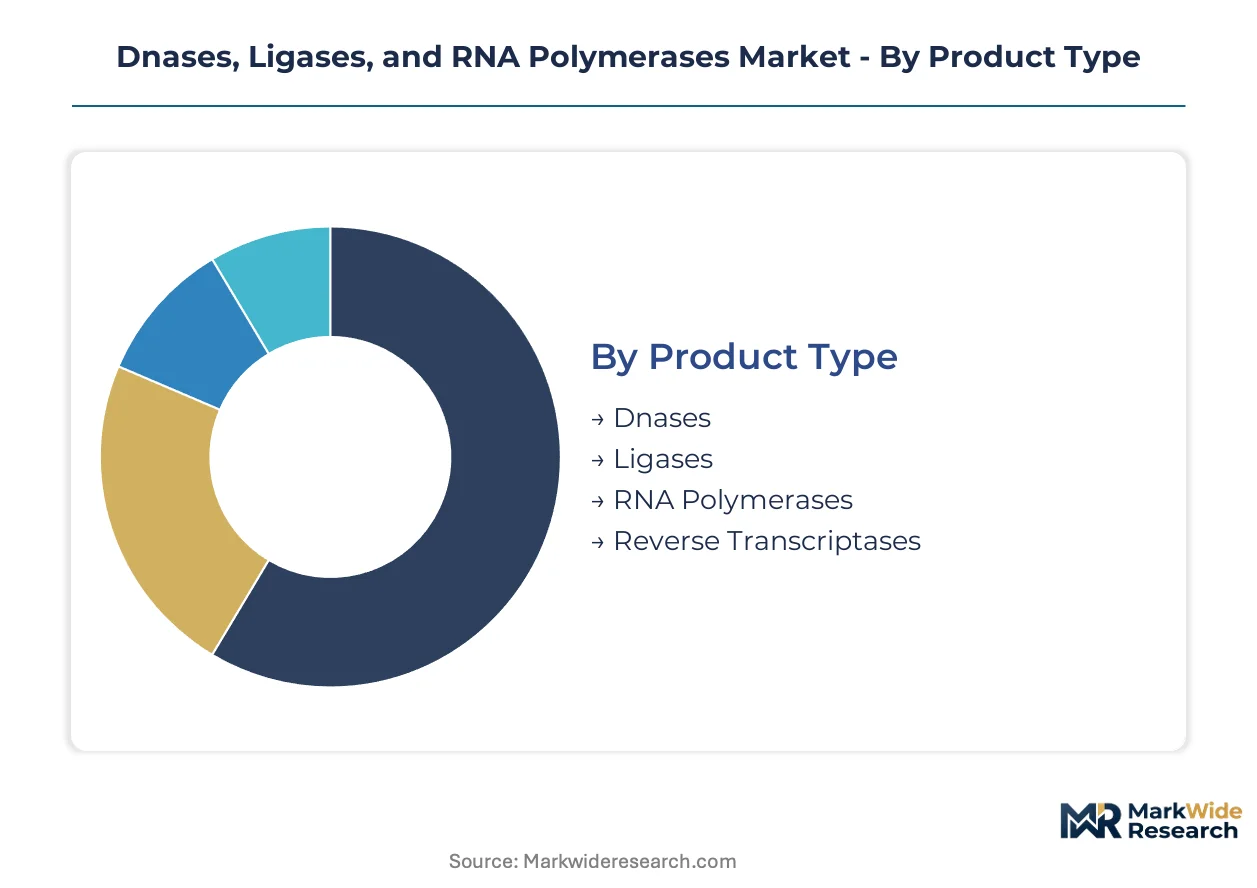
Enzyme procurement patterns fragment sharply across therapeutic manufacturing versus research workflows, with purity grades and documentation requirements diverging by end-use. Suppliers must configure parallel production lines and qualification protocols to serve these incompatible demand profiles without cross-contamination risk.
Product Type:
Pricing power and margin structure diverge based on therapeutic certification requirements and manufacturing complexity.
- RNA Polymerases:These enzymes catalyze DNA-dependent RNA synthesis with high fidelity requirements for mRNA vaccine production. GMP-grade specifications command substantial premiums from manufacturers in the United States running large-scale transcription reactions for approved therapies.
- Dnases:Deoxyribonucleases cleave phosphodiester bonds in DNA backbones for sample preparation and contamination control. Academic sequencing cores and diagnostic assay developers in Germany and Japan drive steady catalog demand for research-grade formulations.
- Ligases:DNA ligases seal nicks in DNA strands during cloning and repair workflows.
- Reverse Transcriptases:RNA-dependent DNA polymerases enable cDNA synthesis from RNA templates.
Volume sits with Dnases; growth tilts toward RNA Polymerases.
Application:
Workflow complexity and regulatory scrutiny intensify as applications progress from discovery tools to therapeutic manufacturing inputs.
- Gene Expression:Quantitative measurement of transcript levels demands enzyme lots with validated activity coefficients and minimal batch-to-batch variation. Cell therapy developers in Switzerland and the United Kingdom require extensive documentation for enzymes entering ATMP manufacturing workflows.
- Molecular Cloning:Assembly of recombinant DNA constructs depends on restriction enzymes and ligases with standardized unit definitions. Contract research organizations in India and South Korea consume high volumes for antibody engineering and vector construction projects.
- DNA Repair:Enzymatic restoration of damaged DNA sequences supports basic research and synthetic biology.
- Sequencing:Library preparation protocols consume nucleases and polymerases with defined performance in NGS workflows.
Sequencing commands the largest installed base; gene expression climbs the fastest as therapeutic developers in-source enzyme qualification.
End User:
Procurement sophistication and supplier relationship intensity scale with therapeutic proximity and regulatory exposure.
- Pharmaceutical Companies:Integrated biologics manufacturers conduct extensive supplier audits and lock in multi-year enzyme supply agreements. Boston and San Diego gene therapy developers maintain dedicated procurement staff qualifying GMP-grade RNA polymerases for commercial manufacturing.
- Biotechnology Firms:Venture-backed therapeutic developers prioritize speed-to-clinic over cost optimization in enzyme selection. Series B and C companies in Cambridge and Research Triangle Park negotiate direct manufacturer relationships bypassing distributor markups.
- Academic Institutions:University core facilities and individual laboratories purchase research-grade enzymes through catalog distributors.
- Research Labs:Government and private research institutes run standardized molecular biology protocols with price-sensitive procurement.
Academic Institutions move the highest unit volumes; Pharmaceutical Companies deliver steepest expansion trajectory as therapeutic pipelines mature.
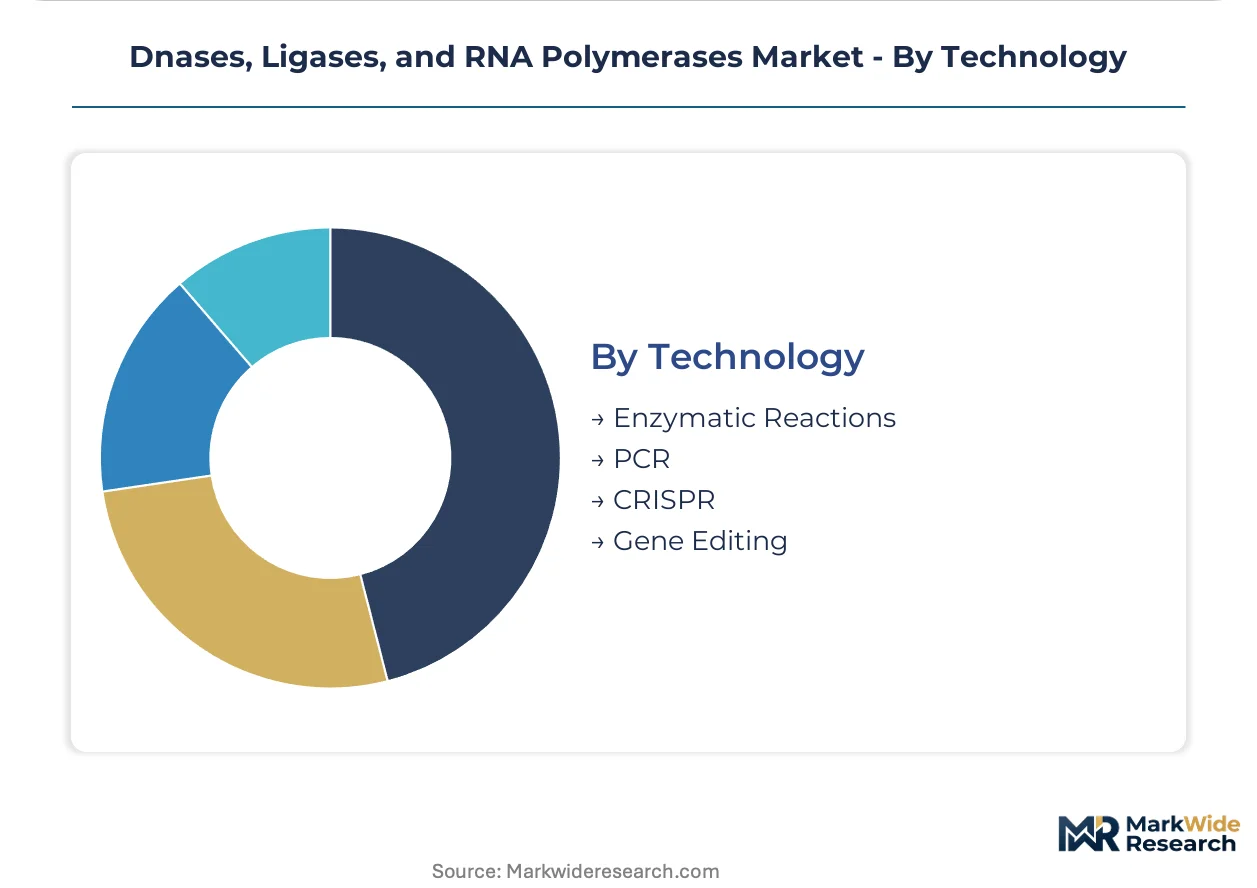
Technology:
Platform selection determines enzyme performance specifications and supplier technical support requirements.
- CRISPR:Genome editing workflows demand high-specificity nucleases and engineered variants with reduced off-target activity. Discovery groups in the Netherlands and Sweden are displacing legacy PCR methods with CRISPR-based screening for complex genetic targets.
- PCR:Polymerase chain amplification remains ubiquitous for diagnostic and research applications. Reference laboratories in France and Italy maintain high-throughput thermal cycling infrastructure consuming thermostable polymerases in bulk quantities.
- Gene Editing:Zinc-finger and TALEN platforms persist in specialized therapeutic applications.
- Enzymatic Reactions:General-purpose biocatalysis spans DNA modification and nucleic acid processing workflows.
PCR retains the broadest installed base; CRISPR gains share fastest as pharmaceutical pipelines embed editing into manufacturing stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for recombinant enzyme production clusters around established bioprocessing corridors in the United States, Germany, Japan, China, and Switzerland. These geographies concentrate both GMP-grade manufacturing infrastructure and the therapeutic development pipelines that pull high-purity enzymes through qualified supply chains.
United States
mRNA vaccine manufacturers in Massachusetts and California drive concentrated procurement of GMP-grade RNA polymerases for commercial transcription workflows. FDA lot-release documentation requirements for gene therapy starting materials force enzyme suppliers to maintain electronic batch records and audit-ready quality systems. The Boston-Cambridge corridor anchors therapeutic developer density, with dedicated procurement teams qualifying multi-year enzyme supply agreements.
Germany
Specialized fermentation facilities in Baden-Württemberg and Bavaria supply research-grade nucleases to European sequencing cores and diagnostic assay developers. EMA ATMP guidelines accelerate qualification timelines for enzymes entering cell therapy manufacturing, pulling suppliers toward clinical-grade production. The Heidelberg-Mannheim biotech cluster generates sustained demand for precision ligases in CRISPR-based discovery workflows.
Japan
METI biomanufacturing infrastructure investments are opening procurement channels for foreign enzyme suppliers serving domestic regenerative medicine developers. PMDA oversight of gene therapy products elevates documentation requirements comparable to FDA standards. The Kanto region around Tokyo concentrates cell therapy developers sourcing high-fidelity RNA polymerases for iPSC-derived therapeutic manufacturing.
China
Domestic enzyme engineering firms are scaling bacterial expression capacity to serve local gene therapy developers and mRNA vaccine producers. NMPA regulatory pathways for innovative biologics are maturing, though GMP-grade enzyme qualification timelines lag Western benchmarks. The Yangtze River Delta biotech corridor in Shanghai and Suzhou shows accelerating demand for CRISPR-grade nucleases in discovery applications.
Switzerland
Cell therapy developers in Basel and Zurich require extensive enzyme documentation for ATMP manufacturing workflows under Swissmedic oversight. The country's precision manufacturing heritage supports specialized suppliers producing high-specificity ligases for complex genome engineering. Roche and Novartis anchor a therapeutic ecosystem that in-sources enzyme qualification rather than relying on catalog distributors.
Dnases, Ligases, and RNA Polymerases Market Key Industry Players
Global majors compete with regional champions across distribution reach and therapeutic-grade certification depth. The vendor base stratifies between diversified life science conglomerates controlling channel access and specialized enzyme engineering houses competing on technical performance. Three archetypes dominate: fermentation-scale manufacturers with backward integration into raw material supply, precision enzyme engineering specialists with proprietary strain libraries, and catalog distributors serving price-sensitive academic accounts. Competitive intensity centers on GMP certification speed and direct-to-biotech relationship building.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages its Fisher Scientific distribution arm to control research-grade enzyme access across academic accounts. Merck KGaA/Sigma Aldrich anchors industrial-scale RNA polymerase output through captive fermentation capacity. New England Biolabs exemplifies the specialized engineering archetype, occupying a position defined by CRISPR-application enzyme optimization rather than scale-driven cost competition.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA/Sigma Aldrich |
| New England Biolabs |
| Takara Bio |
| Promega Corporation |
| Agilent Technologies |
| QIAGEN |
| Calzyme |
| RayBiotech |
| Others |
Cost & Logistics Intelligence
Fermentation input costs for glucose and yeast extract cascade through three distinct pricing tiers, with GMP-grade RNA polymerase producers in the United States and Germany absorbing agricultural commodity volatility to maintain contract margins with mRNA vaccine manufacturers.
Pricing Analysis
Extended validation warranties and electronic batch record systems bundle into premium GMP-grade RNA polymerase contracts, while research-grade catalog sales strip these services to hit price points for academic sequencing cores. Three-tier pricing structure across therapeutic-certified, research-grade, and bulk economy levels separates qualification documentation depth. Cost compression in the research tier intensifies as cloud-based protein design platforms enable mid-sized biotechs to engineer enzyme variants in-house. Academic institutions exhibit the highest price sensitivity, negotiating through distributor consortiums, whereas pharmaceutical companies prioritize supply security over unit cost.
Supply Chain Analysis
Recombinant enzyme production rests on bacterial and yeast expression systems concentrated in the United States, Germany, and Switzerland, with GMP-grade capacity tethered to FDA-inspected and EMA-qualified fermentation facilities. Critical inputs span proprietary expression strains, pharmaceutical-grade glucose, and chromatography resins for downstream purification. Single-source vulnerability concentrates among three primary RNA polymerase fermentation sites, exposing therapeutic developers to contamination-driven supply interruptions. Distribution runs through direct manufacturer relationships for GMP-grade procurement, while catalog distributors and Fisher Scientific channels serve research-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA drug master file preparation and EMA ATMP compliance documentation erect substantial cost-of-compliance barriers, with 18-24 month certification timelines filtering out undercapitalized enzyme engineering firms and rewarding incumbent suppliers with audit-ready quality systems.
For Market Incumbents: Cement GMP certification speed as a competitive moat by segregating clinical and research production facilities to prevent cross-contamination risks. Accelerate direct-to-biotech sales team deployment in Boston and San Diego to bypass distributor markups and capture multi-year supply agreements from Series B and C therapeutic developers. Threat: synthetic biology toolkits decentralizing access to high-performance enzyme variants. Lever: proprietary strain libraries for CRISPR-application optimization. For New Entrants and Emerging Players: Enter via Japan's regenerative medicine corridor, where METI infrastructure investments and PMDA regulatory maturation create procurement openings for foreign enzyme suppliers serving domestic iPSC-derived therapeutic manufacturers. Target cloud-based protein design partnerships with Cambridge and Research Triangle Park biotechs seeking customized nuclease variants. Go-to-market angle: subscription-based continuous bioprocessing supply contracts with real-time enzyme monitoring. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized enzyme engineering houses with captive fermentation capacity in Baden-Württemberg or Bavaria, where EMA ATMP qualification timelines have strained mid-tier firm cash reserves. Long-term viability hinges on therapeutic manufacturing contract density rather than research-grade catalog volume. Signal to watch: FDA lot-release documentation standardization that collapses parallel qualification dossier requirements for dual-territory developers.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA ATMP guidelines accelerate clinical-grade production timelines for RNA polymerase suppliers. |
| Direct-to-Biotech Distribution | Bypassing Fisher Scientific markups captures procurement teams at San Diego gene therapy developers. |
| Continuous Bioprocessing Partnership | Real-time enzyme monitoring converges with mRNA manufacturing platforms for subscription contracts. |
| Strain Library Acquisition | Proprietary expression systems defend against synthetic biology toolkit decentralization. |
| Regional Fermentation Expansion | Capacity additions in Switzerland support Swissmedic-qualified ATMP enzyme documentation. |
Research Approach
Multi-period observation of enzyme procurement patterns, GMP certification timelines, and CRISPR workflow adoption anchored the trend analysis, supplemented by interviews with fermentation scientists, therapeutic developer procurement leads, regulatory affairs specialists, and academic core facility directors. Secondary validation drew from FDA drug master file databases, EMA ATMP submission records, ISO 13485 certification registries, and SEC filings of diversified life science conglomerates. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Input-output matrices mapped recombinant enzyme production capacity across bacterial and yeast expression systems, with segmentation dimensions spanning product type, purity grade, end-user sophistication, and regional regulatory cluster. CAGRs were derived from trajectory analysis of therapeutic pipeline maturation and manufacturing scale-up timelines across the projection horizon. Industry-specific forecast inputs incorporated mRNA vaccine production forecasts and cell therapy ATMP approval velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios or agricultural commodity price spikes. Forecasts reflect documented assumptions regarding therapeutic developer in-sourcing trends and GMP-grade capacity expansion rates. Gene therapy starting material oversight intensity and fermentation input cost trajectories warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Prokaryotic Expression Systems Market