
 Global Cell Banking Outsourcing Market | 2026-2036
Global Cell Banking Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Banking Outsourcing Market Foresight
Cell therapy developers is unwinding reliance on in-house infrastructure as commercial-stage programs strain manufacturing capacity. Lonza Group anchors European production networks with dedicated cell banking suites in Basel. Charles River Laboratories extends its North American footprint through integrated testing and banking workflows. Samsung Biologics competes on scale, leveraging Korean biocluster incentives to capture late-stage outsourcing from Asia-Pacific sponsors.
Cell banking outsourcing encompasses the professional preservation, characterization, and storage of master cell banks and working cell banks under controlled conditions, typically maintaining viability below minus 150 degrees Celsius in vapor-phase liquid nitrogen with documented chain-of-custody protocols. The practice eliminates capital intensity for therapy developers while ensuring regulatory-compliant starting materials for clinical and commercial manufacturing. Cryopreservation services command premium positioning due to specialized equipment requirements and validated protocol expertise. Cell therapy applications within regenerative medicine represent the fastest-expanding demand pool as autologous and allogeneic programs advance toward commercialization. Automated cell processing technology is displacing manual handling in high-volume contracts, driven by reproducibility demands and labor cost arbitrage.
FDA enforces current Good Manufacturing Practice for cell-based products through its Center for Biologics Evaluation and Research, while EMA applies its Advanced Therapy Medicinal Products framework to govern banked cell quality across European trials. The EU AI Act introduces emerging compliance dimensions for automated cell characterization algorithms used in release testing. South Korea's MFDS accelerates parallel reviews for cell banking facilities serving both domestic and export markets. Stakeholders must monitor divergence between FDA and EMA guidance on genetically modified cell substrates, as harmonization gaps threaten multi-regional filing timelines and facility qualification costs.
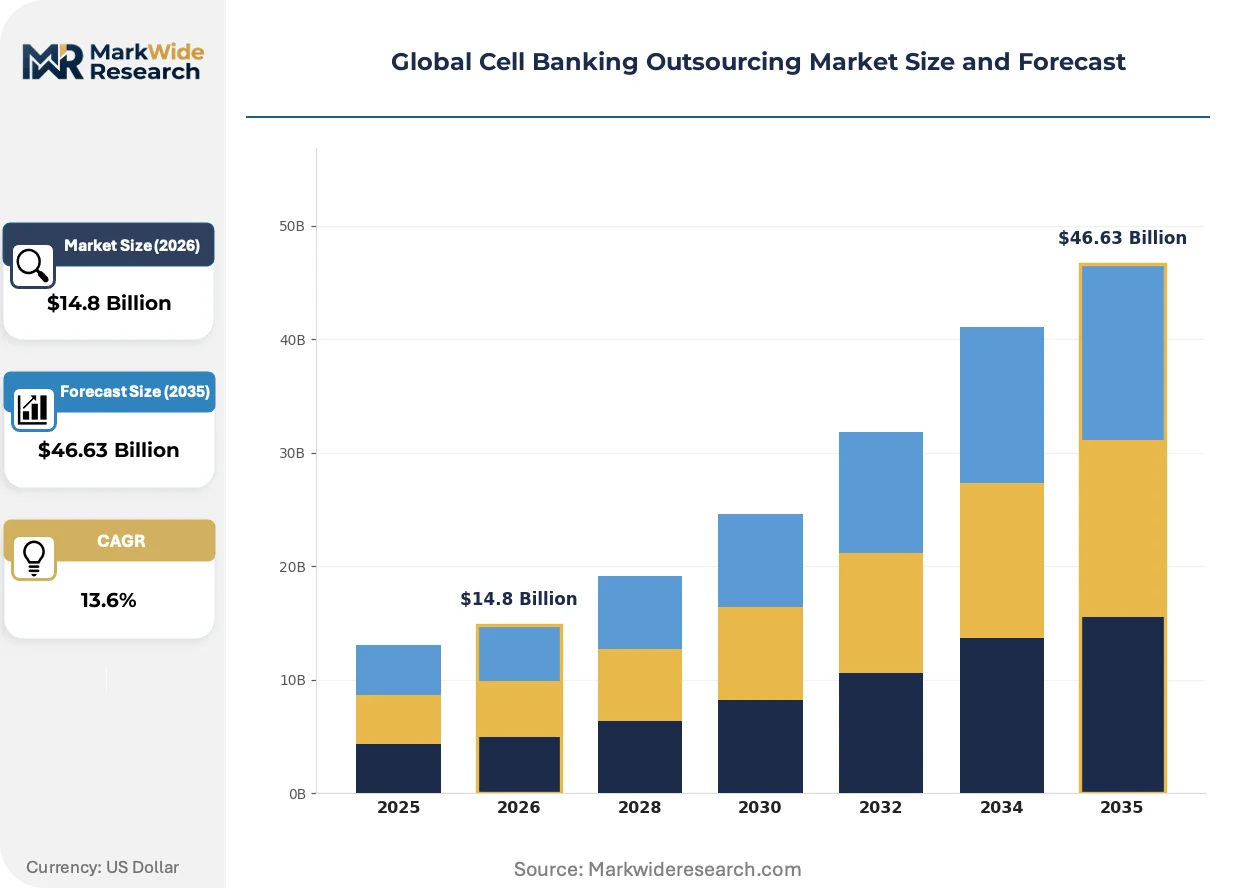
Market Dynamics
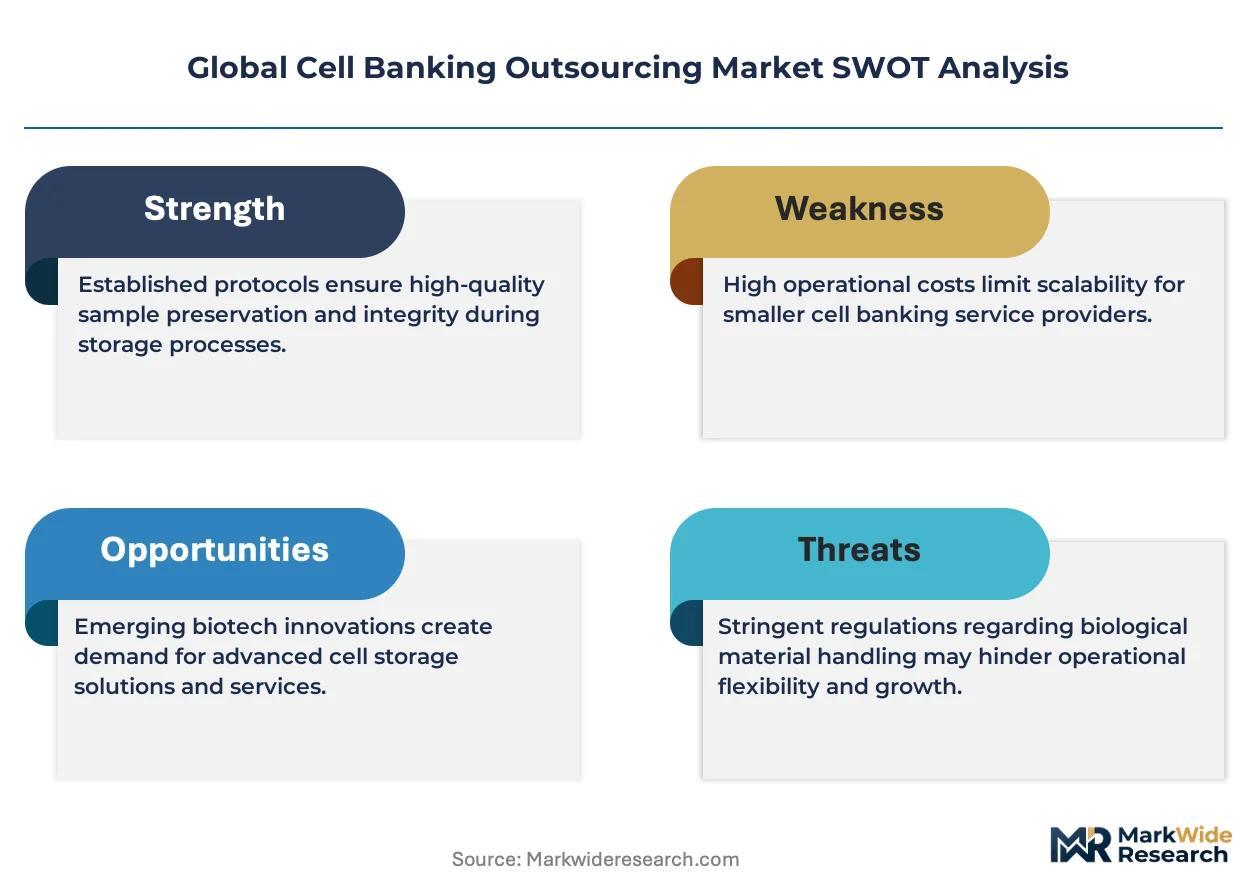
Automated cell processing systems are compressing manual handling margins while FDA and EMA tighten substrate documentation requirements, forcing developers to choose between capital-heavy in-house buildouts and specialized outsourcing partnerships with validated cryopreservation protocols.
Growth Catalysts
- ATMP Framework Expansion:EMA's Advanced Therapy Medicinal Products classification accelerates European trial approvals for banked cell substrates, pulling sponsors toward qualified EU-based CDMOs.
- Liquid Nitrogen Infrastructure:Vapor-phase cryopreservation below minus 150 degrees Celsius demands specialized equipment that few developers maintain in-house, funneling volume toward outsourced providers.
- Allogeneic Pipeline Maturation:Off-the-shelf cell therapies require larger master cell bank volumes than autologous programs, amplifying demand for industrial-scale banking capacity.
Market Restraints
- Equipment Supplier Concentration:Vapor-phase liquid nitrogen storage systems rely on a narrow base of cryogenic equipment manufacturers, creating vulnerability in capacity expansion timelines.
- Genetically Modified Substrate Divergence:FDA and EMA maintain non-harmonized guidance on genetically modified cell bank characterization, inflating multi-regional filing costs and facility qualification burdens.
- Skilled Technician Scarcity:Aseptic cell handling under cryogenic conditions requires certified operators whose training pipelines lag market expansion.
Strategic Opportunities
- Swissmedic Fast-Track Pathways:Switzerland's accelerated facility qualification for cell banking suites serving both EU and US markets offers regulatory arbitrage for sponsors pursuing parallel filings.
- AI-Enabled Release Testing:Automated cell characterization algorithms combined with flow cytometry are opening premium service tiers for real-time viability monitoring.
- MFDS Export Incentives:South Korea's parallel review system for domestic and export-qualified cell banks reduces time-to-market for Asia-Pacific sponsors targeting Western regulators.
Industry Challenges
- Chain-of-Custody Documentation:Maintaining auditable records across multiple handling sites and temperature excursions demands integrated informatics systems that many providers struggle to validate.
- Cross-Contamination Protocols:Simultaneous storage of autologous and allogeneic cell lines within shared cryogenic facilities requires validated segregation procedures that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Banking Outsourcing Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Primary Cell Banking, Secondary Cell Banking, Cryopreservation, Cell Characterization, Quality Control Application: Regenerative Medicine, Gene Therapy, Vaccine Development, Cell Therapy, Drug Discovery End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Institutions, Cell Therapy Developers, Biotechnology Startups Technology: Automated Cell Processing, Manual Cell Handling, Cryogenic Storage, Bioreactor Systems, Cell Expansion Platforms |
| Companies Covered | Lonza Group, Charles River Laboratories, Thermo Fisher Scientific, Samsung Biologics, Wuxi AppTec, Merck KGaA, Cryo-Cell International, BSL Bioservice, Sino Biological, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Banking Outsourcing Market Shifts & Advancements
Closed-system automated processing is rewriting operational economics while regulatory algorithms and procurement centralization reshape competitive positioning across the value chain.
Single-use bioreactors with integrated cell washing modules are supplanting open-manifold centrifugation in master cell bank production. Late-stage cell therapy sponsors in the United States and Switzerland are adopting these systems within eighteen-month validation cycles. The shift compresses labor intensity by seventy percent while eliminating particulate contamination risks that plague manual protocols.
EMA's EU AI Act introduces algorithmic transparency requirements for automated cell characterization used in release testing. Banking providers must now document training data provenance and decision-tree logic for viability assessments. European CDMOs are responding by segregating AI-enabled workflows into dedicated quality units with distinct standard operating procedures.
Sponsor procurement functions are consolidating vendor panels around integrated testing-and-banking contracts rather than discrete service purchases. Large biopharmaceutical developers now mandate single-provider accountability for master cell bank creation, characterization, and storage. This concentration is most visible among US-based sponsors with three or more concurrent IND programs.
Global Cell Banking Outsourcing Market Segmentation
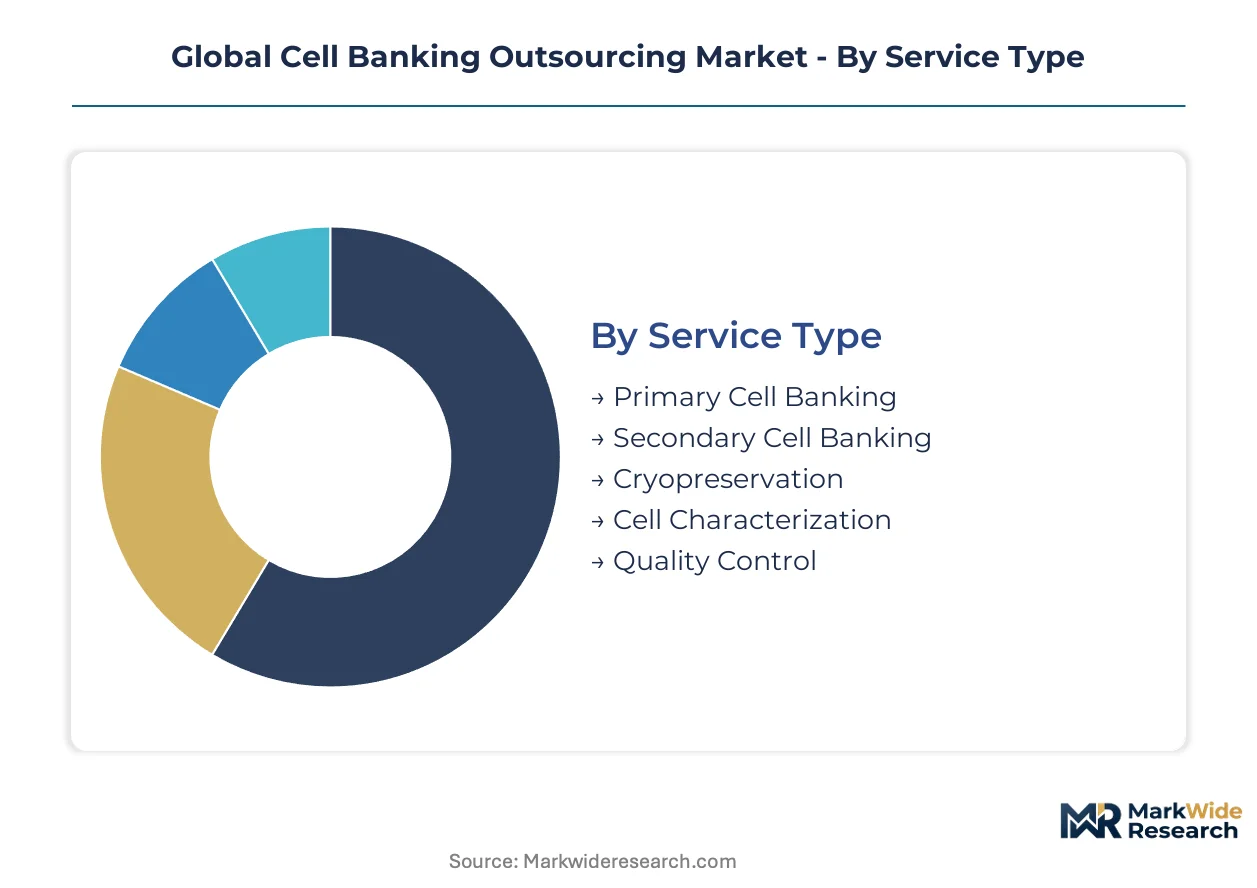
Cell banking outsourcing segments map directly to regulatory submission pathways and manufacturing scale requirements. Service type determines contract value and margin structure, while application and end-user profiles dictate facility qualification needs and geographic sourcing preferences.
Service Type:
CDMO channel mix varies sharply by service complexity, with cryopreservation and characterization commanding dedicated suites while primary banking flows through integrated manufacturing contracts.
- Cryopreservation:Vapor-phase liquid nitrogen storage below minus 150 degrees Celsius requires validated equipment chains and continuous temperature monitoring. Demand concentrates among allogeneic cell therapy developers in the United States and Switzerland where master cell bank volumes exceed autologous programs by an order of magnitude. FDA and EMA both mandate documented thermal excursion protocols that only specialized providers maintain.
- Cell Characterization:Identity, purity, and potency testing under GMP conditions involves flow cytometry, karyotyping, and sterility panels. Biotechnology startups in South Korea and academic spinouts in Basel increasingly bundle characterization with banking to compress IND timelines. The EU AI Act now imposes algorithmic transparency requirements on automated viability assessments used in release testing.
- Primary Cell Banking:Master cell bank creation from original tissue or cell line source material.
- Secondary Cell Banking:Working cell bank derivation and expansion from established master banks.
- Quality Control:Ongoing stability monitoring and contamination surveillance throughout storage duration.
Cryopreservation dominates installed base. Cell characterization is where expansion concentrates.
Application:
Application mix tracks directly to therapeutic modality maturity, with commercial-stage programs driving contract scale and clinical-phase programs driving volume.
- Cell Therapy:Autologous and allogeneic programs require distinct banking architectures—patient-specific banks versus large-scale master banks for off-the-shelf products. Allogeneic developers in the United States now specify vapor-phase nitrogen capacity exceeding 10,000 vials per product candidate. MFDS in South Korea offers parallel review pathways that accelerate facility qualification for export-bound cell therapy banks.
- Regenerative Medicine:Tissue-engineered products and stem cell therapies impose extended characterization timelines due to phenotypic drift concerns. Swissmedic fast-track qualifications in Basel cluster serve sponsors pursuing concurrent EU and US filings. EMA's ATMP framework provides regulatory clarity that pulls banking contracts toward Swiss and German CDMOs.
- Gene Therapy:Viral vector manufacturing support and genetically modified cell substrates.
- Vaccine Development:Cell substrate banking for viral vaccine production including Vero and MDCK lines.
- Drug Discovery:Research-grade cell banks for high-throughput screening and target validation.
Cell therapy commands the largest contract values. Regenerative medicine is climbing the fastest.
End User:
Customer type determines procurement sophistication, with large biopharmaceutical companies consolidating vendor panels while startups prioritize speed over integration.
- Biopharmaceutical Companies:Integrated testing-and-banking contracts with single-provider accountability. US-based sponsors with multiple concurrent IND programs now mandate consolidated vendor relationships spanning master cell bank creation through commercial storage.
- Cell Therapy Developers:Venture-backed sponsors prioritizing speed-to-IND over long-term storage economics. Basel and Boston clusters show highest concentration of outsourcing decisions.
- Contract Research Organizations:Research-grade banking for preclinical programs.
- Academic Institutions:Non-GMP banking for exploratory research with limited regulatory documentation.
- Biotechnology Startups:Early-stage sponsors leveraging outsourced infrastructure to avoid capital deployment.
Biopharmaceutical companies dominate contract value. Cell therapy developers are gaining share fastest.
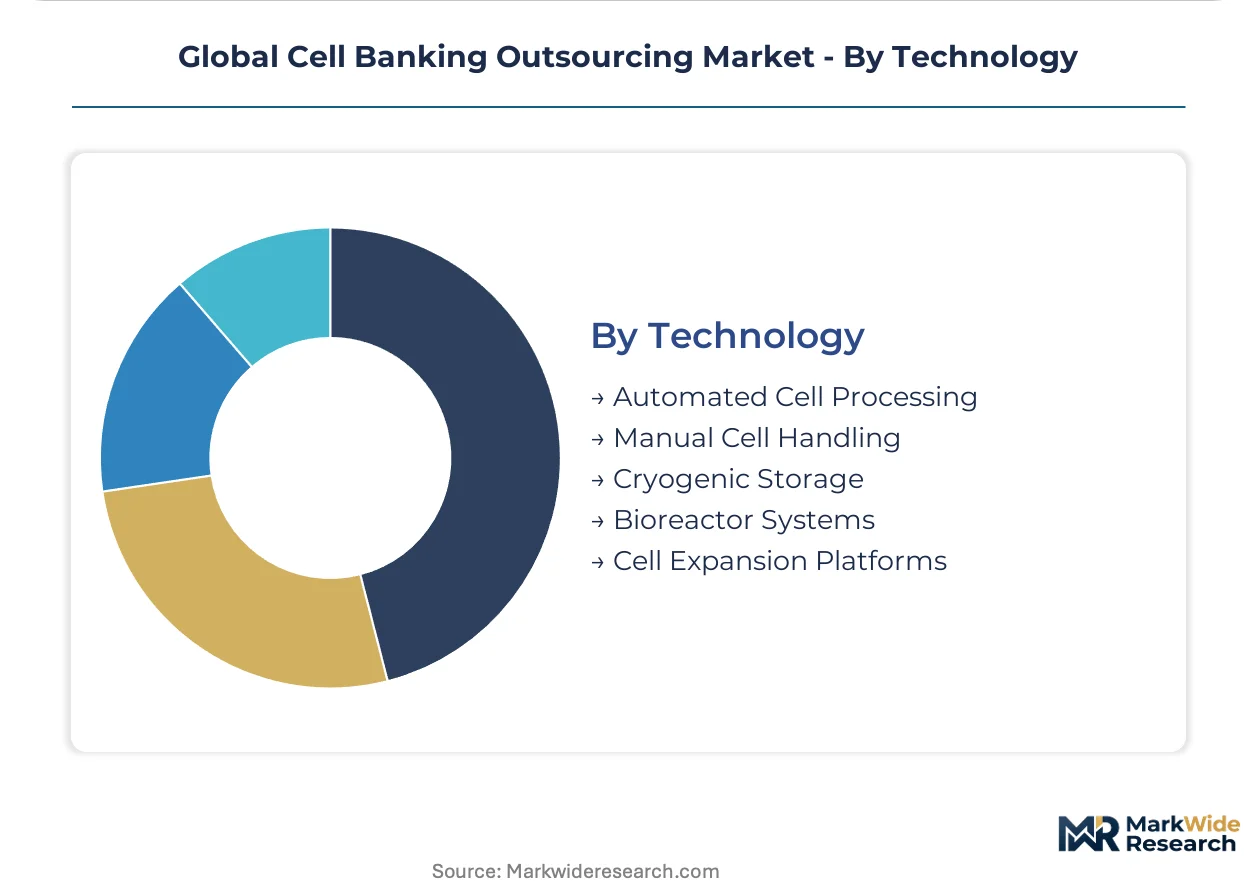
Technology:
Technology adoption splits along manufacturing scale, with automated systems penetrating commercial programs while manual handling persists in research settings.
- Automated Cell Processing:Closed-system platforms with integrated washing and concentration modules displace open-manifold centrifugation. Late-stage sponsors in Switzerland and the United States adopt these systems within eighteen-month validation cycles. Labor intensity drops seventy percent while particulate contamination risk falls to near-zero.
- Cryogenic Storage:Vapor-phase liquid nitrogen infrastructure with automated inventory management and chain-of-custody tracking. Equipment supplier concentration creates vulnerability in capacity expansion timelines for providers serving multi-product sponsors.
- Manual Cell Handling:Open-system processing for research-grade applications.
- Bioreactor Systems:Scalable expansion platforms for working cell bank production.
- Cell Expansion Platforms:Specialized systems for rapid working bank generation.
Cryogenic storage dominates facility capital allocation. Automated cell processing is where investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryopreservation infrastructure concentrates in jurisdictions offering regulatory arbitrage for multi-regional filings. CDMO clusters in Switzerland, South Korea, and the United States capture disproportionate outsourcing volume from cell therapy developers seeking validated master cell bank capacity.
United States
FDA's Center for Biologics Evaluation and Research enforces current Good Manufacturing Practice for cell-based products with stringent substrate documentation requirements. The Boston-Cambridge corridor hosts the densest concentration of venture-backed cell therapy sponsors outsourcing master cell bank creation. Late-stage allogeneic developers now specify vapor-phase nitrogen capacity exceeding 10,000 vials per product candidate.
Switzerland
Swissmedic operates accelerated facility qualification pathways for cell banking suites serving concurrent EU and US regulatory submissions. Basel anchors European production networks with dedicated cryogenic infrastructure that qualified providers maintain under continuous temperature monitoring. EMA's Advanced Therapy Medicinal Products framework provides regulatory clarity that pulls banking contracts toward Swiss CDMOs.
South Korea
MFDS accelerates parallel reviews for cell banking facilities qualified for both domestic and export markets, reducing time-to-market for Asia-Pacific sponsors. The Songdo biocluster leverages government incentives to capture late-stage outsourcing from regional developers. Samsung Biologics competes on industrial scale with automated processing platforms that displace manual handling in high-volume contracts.
Germany
German CDMOs specialize in regenerative medicine applications where extended characterization timelines address phenotypic drift concerns in tissue-engineered products. EMA's EU AI Act imposes algorithmic transparency requirements on automated cell characterization workflows used in release testing. Frankfurt and Munich clusters show growing concentration of integrated testing-and-banking contracts.
United Kingdom
Post-Brexit divergence from EMA guidance creates compliance complexity for cell banking providers serving European trials from British facilities. London and Oxford-based developers increasingly route master cell bank qualification through Swiss or German CDMOs to preserve EU market access. The Medicines and Healthcare products Regulatory Agency maintains separate genetically modified organism notification requirements that extend facility qualification timelines.
Global Cell Banking Outsourcing Market Competitive Landscape
Concentration sits with integrated CDMOs possessing validated cryopreservation infrastructure and multi-regulatory qualification experience. The vendor base stratifies across three tiers: global contract manufacturers with dedicated cell banking suites, regional specialists in automated processing technology, and niche providers of research-grade storage. Consolidation pressure intensifies as sponsor procurement functions mandate single-provider accountability spanning master cell bank creation through commercial storage. Dominant competitive moves include capacity expansion in Swiss and South Korean bioclusters and strategic partnerships combining automated processing platforms with integrated quality testing.
Among Switzerland-based integrated providers, Lonza Group anchors European production networks with dedicated cell banking infrastructure. Charles River Laboratories exemplifies the North American testing-and-banking consolidation model with integrated workflows spanning characterization through storage. Samsung Biologics occupies a scale-driven position within the Asia-Pacific tier, leveraging Korean biocluster incentives to capture late-stage outsourcing volume.
| Leading Market Players |
|---|
| Lonza Group |
| Charles River Laboratories |
| Thermo Fisher Scientific |
| Samsung Biologics |
| Wuxi AppTec |
| Merck KGaA |
| Cryo-Cell International |
| BSL Bioservice |
| Sino Biological |
| Others |
Supply & Pricing Matrix
Vapor-phase liquid nitrogen capacity exceeding 10,000 vials per product candidate anchors supply-side scale economies, compressing unit costs for allogeneic developers while establishing price floors that exclude sub-scale competitors from commercial-grade contracts. Swiss and South Korean bioclusters concentrate this capacity, translating equipment utilization rates into pricing power across master cell bank creation and long-term storage services.
Pricing Analysis
Volume-discount tiering structures separate large biopharmaceutical sponsors with multi-product portfolios from venture-backed cell therapy developers and academic spinouts. Pricing stratifies across premium, standard, and economy tiers based on GMP certification level and chain-of-custody documentation intensity. Cost compression in economy-tier research-grade banking is intensifying because automated processing platforms displace manual handling labor. Biotechnology startups exhibit highest price sensitivity, while commercial-stage allogeneic developers prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate cryogenic infrastructure planning, with CDMOs maintaining 18-24 months of vapor-phase nitrogen reserve capacity against equipment supplier lead time volatility. Supply concentrates in the United States, Switzerland, and South Korea, drawing from specialized cryogenic equipment manufacturers in Germany and Japan. Single-source vulnerability in liquid nitrogen storage system fabrication creates capacity expansion bottlenecks. Distribution runs through qualified cold-chain logistics providers with validated temperature excursion protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated cell processing technology is disrupting operational economics while EMA's EU AI Act imposes algorithmic transparency requirements that reshape competitive positioning for release testing services.
For Market Incumbents: Secure vapor-phase nitrogen capacity expansion in Swissmedic-qualified Basel facilities before equipment supplier lead times extend further. Anchor regulatory arbitrage advantages by qualifying suites for concurrent FDA and EMA submissions, defending against emerging automated processing specialists from South Korean bioclusters. For New Entrants and Emerging Players: Lead with AI-enabled cell characterization algorithms targeting European CDMOs struggling with EU AI Act compliance documentation. The white-space opportunity sits with mid-tier German regenerative medicine providers lacking dedicated quality units for automated viability assessments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated processing platform owners with validated closed-system protocols over manual-dependent incumbents. Long-term viability hinges on regulatory qualification speed rather than scale alone. The signal to watch is MFDS parallel review approval velocity for export-bound Asia-Pacific sponsors.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Platform Deployment | Samsung Biologics leverages Korean biocluster incentives to displace manual handling in high-volume contracts. |
| Swissmedic Fast-Track Qualification | Lonza Group anchors European production networks with concurrent EU-US regulatory submission capability. |
| AI-Enabled Release Testing Integration | EMA's EU AI Act mandates algorithmic transparency documentation for automated cell characterization workflows. |
| Integrated Testing-and-Banking Consolidation | Charles River Laboratories extends North American footprint through single-provider accountability contracts. |
| MFDS Parallel Review Capture | South Korean CDMOs reduce time-to-market for Asia-Pacific sponsors targeting Western regulators. |
Research Methodology
Initial hypotheses were tested against primary input from cell therapy development executives, regulatory affairs leads at CDMOs, cryogenic equipment procurement managers, and quality control directors, then refined through secondary validation against FDA Center for Biologics Evaluation and Research guidance documents, EMA Advanced Therapy Medicinal Products framework publications, MFDS facility qualification records, and Swissmedic fast-track pathway determinations. Bottom-up service-type demand modeling and top-down biopharmaceutical outsourcing spend analysis were triangulated to converge on market size estimates.
Variance decomposition across service type, application, end user, and technology dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by contract value concentration. Modeled inputs included allogeneic pipeline maturation timelines, automated processing adoption curves, and regulatory qualification velocity differentials across FDA, EMA, and MFDS jurisdictions.
Forecasts assume regulatory continuity in FDA, EMA, and MFDS regimes; material policy shifts would require re-modeling. Revision becomes warranted when genetically modified substrate guidance divergence between FDA and EMA crosses thresholds that extend multi-regional facility qualification timelines beyond sponsor tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Biobank Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Serine Protease Market