
 Uganda Mobile Money Market | 2026-2036
Uganda Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Uganda Mobile Money Market Intelligence
The Bank of Uganda's tiered KYC framework is restructuring how mobile money providers onboard customers and manage transaction limits. MTN Mobile Money leverages its agent network density to sustain dominance in rural corridors. Airtel Money competes through aggressive pricing on peer-to-peer transfers. Chipper Cash navigates cross-border regulatory complexity to extend remittance corridors into East Africa.
Mobile money denotes a financial service enabling electronic value storage, transfer, and payment through cellular network infrastructure, typically requiring only a basic SIM-enabled handset and USSD or SMS protocols for transaction authentication. Its primary commercial purpose centers on financial inclusion for unbanked populations and digitization of informal cash economies. Peer-to-Peer Transfers anchors transaction volume across all demographic tiers, while Merchant Payments represents the fastest-growing segment as informal traders adopt QR-based acceptance. International Remittances commands premium fee structures but faces margin pressure from fintech entrants.
The Bank of Uganda enforces capital adequacy and consumer protection rules under the National Payment Systems Act, while the Uganda Communications Commission mandates telecom infrastructure standards that underpin platform reliability. The Financial Intelligence Authority imposes anti-money laundering protocols that shape wallet design and transaction monitoring architecture. Stakeholders must monitor how interoperability mandates between MTN Mobile Money and Airtel Money reshape competitive dynamics and fee structures across the ecosystem.
Market Dynamics
The Bank of Uganda's National Payment Systems Act is restructuring capital adequacy requirements for mobile money operators, forcing platform redesigns that prioritize compliance architecture over feature expansion. Agent banking networks sustain rural penetration while tiered KYC frameworks segment customer onboarding by transaction volume thresholds.
Growth Catalysts
- Agent Banking Density:Rural corridor expansion through physical cash-in/cash-out points addresses last-mile access gaps where traditional banking infrastructure remains absent.
- National Payment Systems Act:Regulatory clarity from the Bank of Uganda reduces operational uncertainty for licensed operators and attracts institutional capital into digital wallet infrastructure.
- QR Code Merchant Acceptance:Informal traders in Kampala's commercial corridors adopt smartphone-based payment acceptance, converting cash transactions into trackable digital flows.
Market Restraints
- Telecom Infrastructure Concentration:Platform reliability depends on MTN and Airtel network coverage, creating single-point-of-failure risk in remote districts.
- Foreign Exchange Volatility:Cross-border remittance corridors face margin compression when shilling-dollar spreads widen unpredictably.
- Biometric Verification Costs:Tiered KYC mandates from the Financial Intelligence Authority impose per-customer onboarding expenses that strain low-margin rural acquisition.
Strategic Opportunities
- Northern Uganda Reconstruction:Post-conflict districts around Gulu and Lira present underpenetrated wallet adoption potential among returning agricultural populations.
- Interoperability Mandates:Regulatory pressure for MTN-Airtel transaction routing creates fee compression that favors platform-agnostic fintech aggregators.
- API Banking Convergence:Mobile money rails integrating with core banking systems enable salary disbursement and micro-lending products for formal sector employers.
Industry Challenges
- Agent Liquidity Management:Cash float requirements at rural agent locations demand working capital forecasting capabilities that exceed current platform analytics.
- Legacy USSD Migration:Transitioning basic handset users from unstructured supplementary service data to smartphone applications requires interface redesign without alienating core demographics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uganda Mobile Money Market |
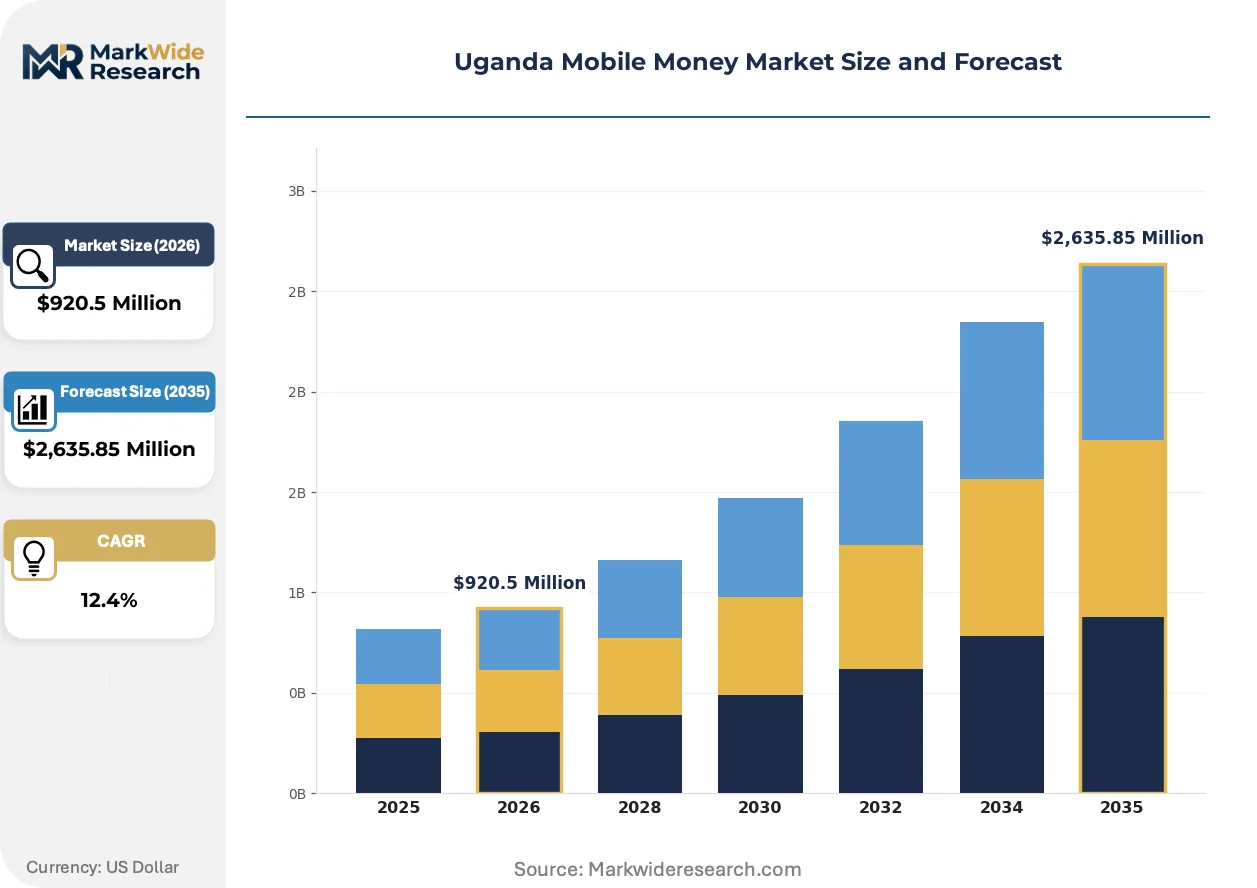
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,635.85 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer Transfers, Bill Payments, Merchant Payments, International Remittances User Demographic: Urban Youth, Rural Adults, Small Business Owners, Corporate Clients Transaction Volume: Low Value, Medium Value, High Value, Micro Transactions Device Type: Smartphones, Feature Phones, Tablets, POS Terminals |
| Companies Covered | MTN Mobile Money, Airtel Money, Wave Mobile Money, MTN Uganda, Bharti Airtel Uganda, Yo! Uganda, Chipper Cash, Equity Bank EazzyMoney, Stanbic Bank Mobile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uganda Mobile Money Market Strategic Shifts & Innovations
Technology convergence between mobile money rails and formal banking infrastructure is dissolving historical boundaries between telco-operated wallets and deposit-taking institutions. Platform operators now compete on API sophistication rather than subscriber base alone.
Smartphone-based QR code acceptance is absorbing merchant payment volume from cash-dominant informal trade. Kampala market vendors and upcountry produce buyers adopt camera-based scanning faster than NFC hardware deployment permits. The technology is absorbing transaction authentication costs that previously required dedicated point-of-sale terminals.
The Bank of Uganda's tiered KYC framework is segmenting customer verification by transaction limits and risk profiles. Wallet providers redesign onboarding flows to route low-value users through simplified identity checks while reserving biometric capture for high-limit applicants. Rural agents now carry tablet devices for field-level document capture that previously required branch visits.
Salary disbursement patterns are shifting from cash envelopes to mobile wallet credits among Kampala-based employers. Manufacturing and service sector firms bypass payroll bank accounts entirely, routing wages directly to employee SIM-linked wallets. Construction and agricultural hiring halls in Jinja and Mbale display the most visible adoption of this channel substitution.
Uganda Mobile Money Market Segmentation
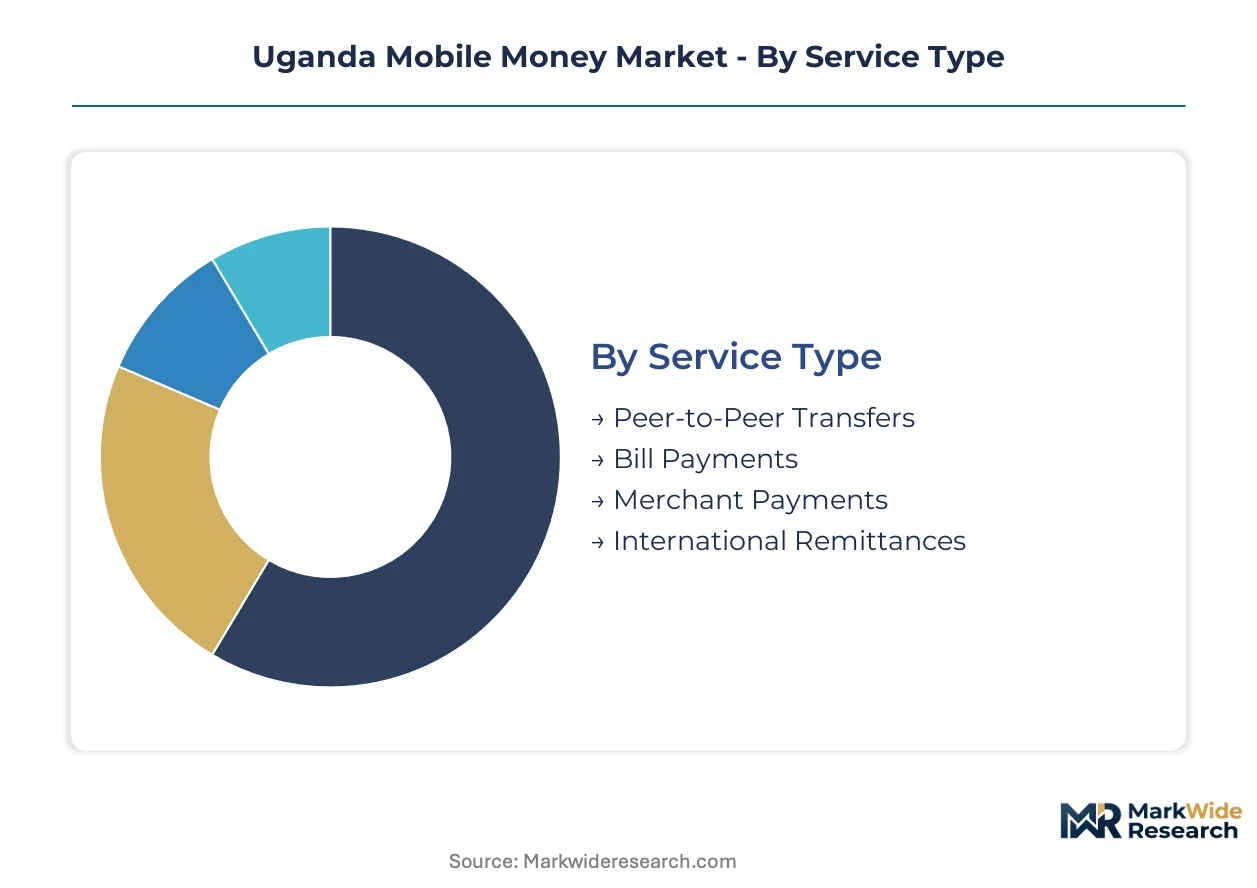
Segmentation in Uganda's mobile money market reveals how transaction patterns diverge across infrastructure access, user sophistication, and regulatory exposure. Each dimension exposes distinct operational requirements for platform providers and agent networks.
Service Type:
Standalone payment services operate through basic USSD menus, while embedded financial products integrate with banking APIs and merchant systems.
- Peer-to-Peer Transfers:The foundational service enabling wallet-to-wallet value movement via USSD shortcodes or smartphone applications. Volume concentrates in Kampala's informal labor markets and cross-family support flows to rural districts; agent liquidity management determines service reliability in low-banking-density zones.
- Merchant Payments:QR-code-enabled acceptance at retail points, absorbing transaction volume from cash-dominant informal trade. Kampala market vendors and upcountry produce buyers adopt camera-based scanning faster than dedicated POS hardware deployment permits; interoperability mandates between MTN and Airtel reshape fee structures.
- Bill Payments:Utility and service settlement through integrated billing APIs.
- International Remittances:Cross-border corridors facing margin pressure from fintech entrants and foreign exchange volatility.
Volume placements concentrate in Peer-to-Peer Transfers; the faster expansion belongs to Merchant Payments.
User Demographic:
Cost tiers segment users by transaction frequency and average wallet balance, with fee sensitivity driving distinct platform engagement patterns.
- Urban Youth:Smartphone-native users generating high-frequency, low-value transactions across social and commercial use cases. Kampala's university corridors and informal gig economies display dense adoption; QR-based merchant acceptance and app-based interfaces match their device capabilities.
- Rural Adults:Feature phone-dependent populations relying on agent-assisted transactions for agricultural payments and family remittances. Northern Uganda's post-conflict districts around Gulu and Lira present underpenetrated acquisition potential; tiered KYC frameworks and biometric verification costs strain rural onboarding economics.
- Small Business Owners:Informal traders requiring working capital float and supplier payment rails.
- Corporate Clients:Formal sector employers shifting salary disbursement from cash envelopes to wallet credits.
Transaction density peaks among Urban Youth; Rural Adults offer the steepest expansion trajectory as agent networks extend.
Transaction Volume:
Application context determines volume thresholds, with regulatory scrutiny intensifying at higher value tiers.
- Micro Transactions:Sub-threshold transfers below tiered KYC verification requirements, enabling rapid onboarding of unbanked users.
- Low Value:Daily commerce and social payments routing through simplified identity checks.
- Medium Value:Agricultural commodity purchases and small business supplier settlements.
- High Value:Salary disbursements and capital equipment payments triggering enhanced due diligence; construction and agricultural hiring halls in Jinja and Mbale display visible adoption of this channel.
Platform design prioritizes Micro Transaction throughput; High Value flows are gaining share fastest as formal sector employers bypass payroll banking.
Device Type:
Customer type stratification follows hardware access, with interface design constraints shaping feature roadmaps.
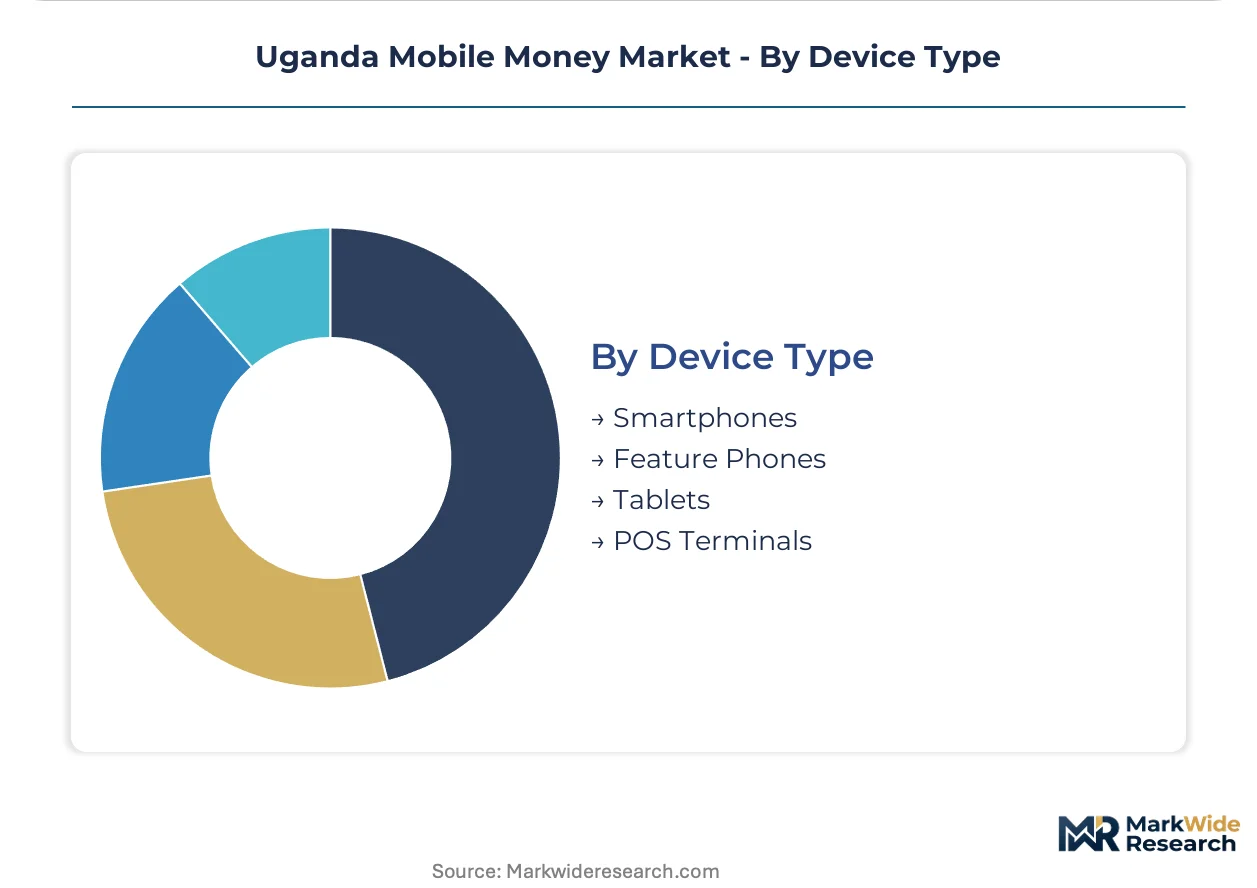
- Feature Phones:USSD-dependent devices dominating rural penetration; legacy migration challenges persist as platforms attempt interface redesign without alienating core demographics.
- Smartphones:Camera-enabled QR scanning and app-based authentication absorbing merchant payment growth; Kampala's commercial corridors drive adoption velocity.
- Tablets:Field-level document capture devices carried by rural agents for tiered KYC compliance.
- POS Terminals:Dedicated hardware at formal retail points facing displacement by smartphone-based alternatives.
Active accounts cluster on Feature Phones; Smartphones command the steepest user growth curve as device affordability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kampala's merchant payments corridor concentrates transaction density and shapes national adoption patterns. The capital's commercial zones generate the highest wallet velocity across East Africa's mobile money ecosystem. Sub-regional variation reflects infrastructure access and post-conflict recovery timelines.
Central Region
Kampala Metropolitan drives merchant payment innovation through QR-code adoption at informal trading posts. The Bank of Uganda's National Payment Systems Act mandates interoperability standards that reshape fee structures across the urban corridor. Jinja's manufacturing hiring halls display accelerating salary disbursement shifts from cash to wallet credits.
Northern Region
Gulu and Lira districts present underpenetrated acquisition potential among returning agricultural populations. Post-conflict reconstruction programs channel development finance through mobile disbursement rails. Agent banking networks extend into remote districts where traditional banking infrastructure remains absent.
Eastern Region
Mbale's agricultural commodity markets anchor peer-to-peer transfer volume for seasonal crop payments. The Financial Intelligence Authority's tiered KYC mandates strain rural onboarding economics through biometric verification costs. Construction hiring halls in the region bypass formal payroll accounts for direct wallet salary routing.
Western Region
Fort Portal and Mbarara corridors sustain cross-border trade flows into Rwanda and DRC. Foreign exchange volatility compresses remittance margins when shilling-dollar spreads widen unpredictably. Telecom infrastructure concentration creates single-point-of-failure risk in remote border districts.
Southwestern Region
Kabale and Kisoro districts exhibit feature-phone-dependent demographics requiring USSD interface retention. Legacy migration challenges persist as platforms attempt smartphone app redesign without alienating core rural users. Agricultural payment cycles dominate transaction timing across the region's tea and coffee cooperatives.
Uganda Mobile Money Market Key Industry Players
Premium-margin players sit above commodity-margin players across agent network density and API sophistication vectors. The market structure consolidates around telecom-operated wallets with banking partnerships forming a secondary tier. Three archetypes dominate: telco-native platforms with rural agent penetration, bank-integrated wallets with formal sector focus, and cross-border fintech aggregators navigating regulatory complexity. Competitive moves center on interoperability compliance and merchant acquisition velocity rather than feature differentiation.
Within the telco-native tier, MTN Mobile Money and Airtel Money occupy positions defined by infrastructure control and subscriber base scale. MTN Mobile Money exemplifies agent network density as a defensive moat across rural corridors. Airtel Money represents pricing aggression on peer-to-peer transfers to capture urban youth transaction frequency. Chipper Cash sits within the cross-border specialist archetype, navigating East African regulatory fragmentation to extend remittance corridors.
| Leading Market Players |
|---|
| MTN Mobile Money |
| Airtel Money |
| Wave Mobile Money |
| MTN Uganda |
| Bharti Airtel Uganda |
| Yo! Uganda |
| Chipper Cash |
| Equity Bank EazzyMoney |
| Stanbic Bank Mobile |
| Others |
Cost & Logistics Intelligence
Salary disbursement shifts from cash envelopes to mobile wallet credits are compressing transaction fees across Kampala's formal sector corridors. The Bank of Uganda's National Payment Systems Act compliance costs are forcing platform operators to absorb KYC infrastructure investments rather than pass through to end users.
Pricing Analysis
Transaction volume-based pricing anchors fee structures across peer-to-peer and merchant payment rails. Price differentiation rests on agent network density and API sophistication tiers. Cost compression in rural onboarding is intensifying because biometric verification requirements strain low-margin customer acquisition. Small business owners display highest price sensitivity; corporate salary disbursement clients accept premium routing for reliability guarantees.
Supply Chain Analysis
Single-source vulnerability sits with MTN and Airtel telecom infrastructure controlling platform reliability across remote districts. Hardware components draw from China, South Korea, and Taiwan for smartphone and tablet devices. Biometric verification hardware imports face logistics chokepoint exposure through Mombasa port congestion. Distribution runs through tiered agent banking networks with cash float managed at rural cash-in/cash-out points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bank of Uganda's National Payment Systems Act has erected a compliance moat that favors capitalized incumbents while raising entry barriers for unlicensed fintech aggregators.
For Market Incumbents: Acquire rural agent network density in Northern Uganda's post-conflict districts around Gulu and Lira. Backward integration into biometric verification hardware supply reduces per-customer onboarding costs. Chipper Cash's cross-border corridor expansion represents the primary emerging entrant threat requiring defensive API standardization investment. For New Entrants and Emerging Players: Enter via platform-agnostic fintech aggregation under interoperability mandates reshaping MTN-Airtel fee structures. Northern Uganda's agricultural payment corridors offer the steepest white-space expansion trajectory. Position through QR-code merchant acceptance tools targeting Kampala's informal trading posts. For Investors and Strategic Acquirers: The window for entry favors compliant wallet operators with existing Bank of Uganda licensing. Long-term viability hinges on API banking convergence enabling salary disbursement and micro-lending product expansion. Watch for interoperability mandate enforcement velocity as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Agent Network Expansion | Physical cash-in/cash-out points in Gulu and Lira districts capture returning agricultural populations. |
| API Banking Integration | Mobile money rails connecting to core banking systems enable direct salary disbursement products. |
| Biometric Verification Infrastructure | Tiered KYC compliance investments satisfy Financial Intelligence Authority mandates while segmenting customer tiers. |
| QR Code Merchant Acceptance | Smartphone-based payment absorption converts Kampala's cash-dominant informal trade into trackable digital flows. |
| Interoperability Compliance | MTN-Airtel transaction routing mandates reshape competitive fee structures across the ecosystem. |
Research Approach
Bank of Uganda regulatory filings, Uganda Communications Commission infrastructure reports, and Financial Intelligence Authority compliance bulletins formed the secondary backbone. Primary interviews with mobile money platform executives, rural banking agents, and Kampala merchant association leaders combined with customs data on biometric hardware imports. Bottom-up transaction volume modeling and top-down GDP-correlation approaches enabled triangulation across the analysis window.
Historical trendline analysis examined adoption velocity across urban-rural divides and device-type transitions. Segmentation dimensions modeled include service type, user demographic, transaction volume tier, and device capability. CAGRs were derived from agent network expansion rates and merchant payment adoption curves. Salary disbursement channel substitution patterns and cross-border remittance corridor volumes served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under telecom infrastructure disruption or foreign exchange volatility shocks. Forecasts reflect documented assumptions regarding interoperability mandate timing and tiered KYC enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Retail Cash Management Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Singapore Remittance Market
Payments
Norway POS Terminals Market
Payments
Smart POS System Market
Payments
Cross-Border Payment Platform Market
Payments
Germany Payments Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Global Gift Card Market
Payments
Digital Payment Market
Payments
UK Prepaid Cards Market
Payments
Mobile Money Market
Payments
Japan Credit Cards Market
Payments
Southeast Asia POS Terminal Market
Payments
Canada POS Terminal Market
Payments
Cash Management System Market